
 Bidet Market | 2026-2036
Bidet Market Size, Share, and Industry Trends Forecast 2026-2036
Bidet Market Analysis
Residential buyer fragmentation is expanding as first-time homeowners and aging-in-place seniors enter the bidet category simultaneously. Toto Ltd. anchors premium electronic bidet manufacturing through its integrated Washlet production system in Japan. Kohler Co. competes across North American retail channels with broad installation-format coverage. LIXIL Corp. leverages its global plumbing fixture network to distribute bidet toilets across European and Asian markets.
A bidet is a plumbing fixture designed for personal cleansing with water, typically operating through pressurized spray nozzles with adjustable temperature and flow controls, constructed from vitreous china, stainless steel, or polymer composites. Electronic variants integrate heating elements, self-sanitizing nozzles, and sensor-activated functions for hands-free operation in residential and commercial bathrooms. Electronic bidets command the highest margin pool due to component complexity and replacement-part revenue streams. Bidet attachments lead volume growth in North American retrofit markets where consumers seek lower-cost entry points without full toilet replacement. Smart-feature technology is displacing manual controls in new construction across hospitality and healthcare end-user segments.
EPA WaterSense certification shapes product development for US market access by establishing flow-rate maximums that manufacturers must meet. Japan's JIS standards and the EU's CE marking requirements for electronic bathroom fixtures create divergent compliance pathways that favor regionally established producers. Stakeholders must monitor evolving plumbing code adoptions at municipal levels, where bidet integration into building standards remains inconsistent and creates patchwork installation requirements.
Market Dynamics
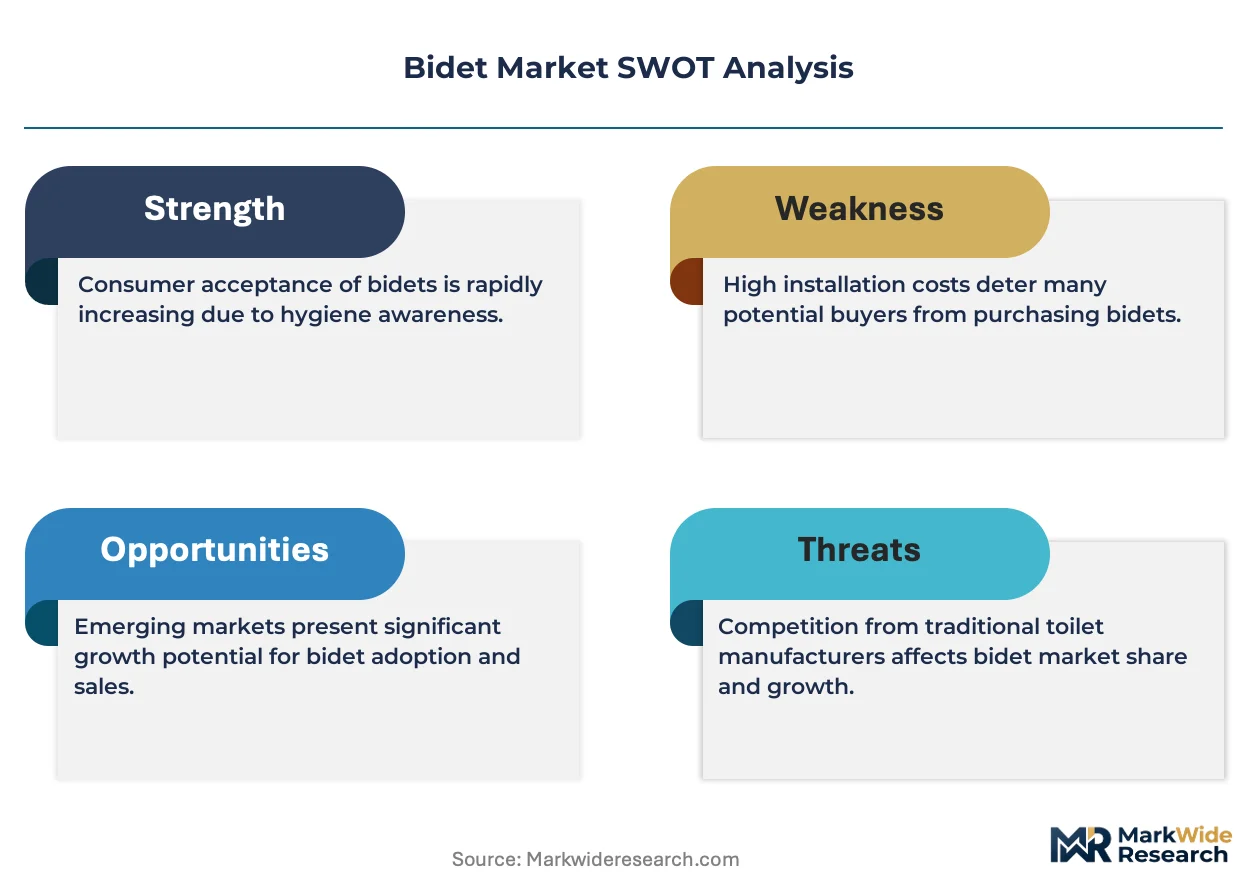
Water-efficiency mandates from the EPA WaterSense program and parallel standards across multiple jurisdictions are forcing manufacturers to redesign spray systems and heating elements, compressing legacy product lines while accelerating premium electronic bidet adoption in renovation cycles.
Growth Catalysts
- EPA WaterSense Certification:Flow-rate maximums established by the EPA are compelling manufacturers to redesign nozzles and heating systems, creating compliant product tiers that unlock municipal procurement channels and retail shelf space across the United States.
- Aging-in-Place Renovation Cycles:Seniors retrofitting bathrooms for accessibility are specifying electronic bidets with grab-bar compatibility and hands-free operation, expanding the residential addressable base beyond traditional early-adopter demographics.
- Stainless Steel Nozzle Adoption:Self-sanitizing spray components using antimicrobial alloys are replacing polymer alternatives in premium installations, elevating perceived hygiene standards and justifying replacement cycles in hospitality and healthcare settings.
Market Restraints
- Ceramic Vitreous China Supply Concentration:Foundry capacity for high-grade ceramic bases clusters in specific manufacturing regions, exposing assemblers to input bottlenecks when freight rates fluctuate or energy costs spike at production sites.
- Dual-Voltage Electrical Standards:Divergent residential voltage requirements between North American 120V and European 230V systems force manufacturers to maintain separate SKUs, inflating inventory carrying costs and complicating cross-border distribution.
- Disposable Wipe Substitution:Flushable wet wipe products retain price-positioning advantages in price-sensitive consumer segments, delaying bidet attachment penetration in rental housing and transient-occupancy settings where installation costs fall on tenants.
Strategic Opportunities
- India Residential Sanitation Upgrades:Central government cleanliness initiatives targeting household toilet installation are creating adjacent demand for water-based cleansing fixtures in new construction across tier-2 and tier-3 urban centers.
- Healthcare Infection Control Mandates:Joint Commission standards for hospital-acquired infection reduction are elevating sensor-activated, self-sanitizing bidet specifications in new facility construction and renovation tenders.
- Voice-Interface Convergence:Integration of bidet controls with smart-home ecosystems and voice-activated bathroom fixtures is opening premium positioning in connected-home new construction segments.
Industry Challenges
- Licensed Plumbing Integration:Bidet toilet installation requires coordination between electrical and plumbing trades, creating scheduling friction and cost overruns in renovation projects where contractor availability is constrained.
- CE Marking Timeline Compression:European electronic fixture compliance testing cycles are extending due to backlog at notified bodies, delaying product launches and freezing marketing commitments for manufacturers targeting EU market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bidet Market |
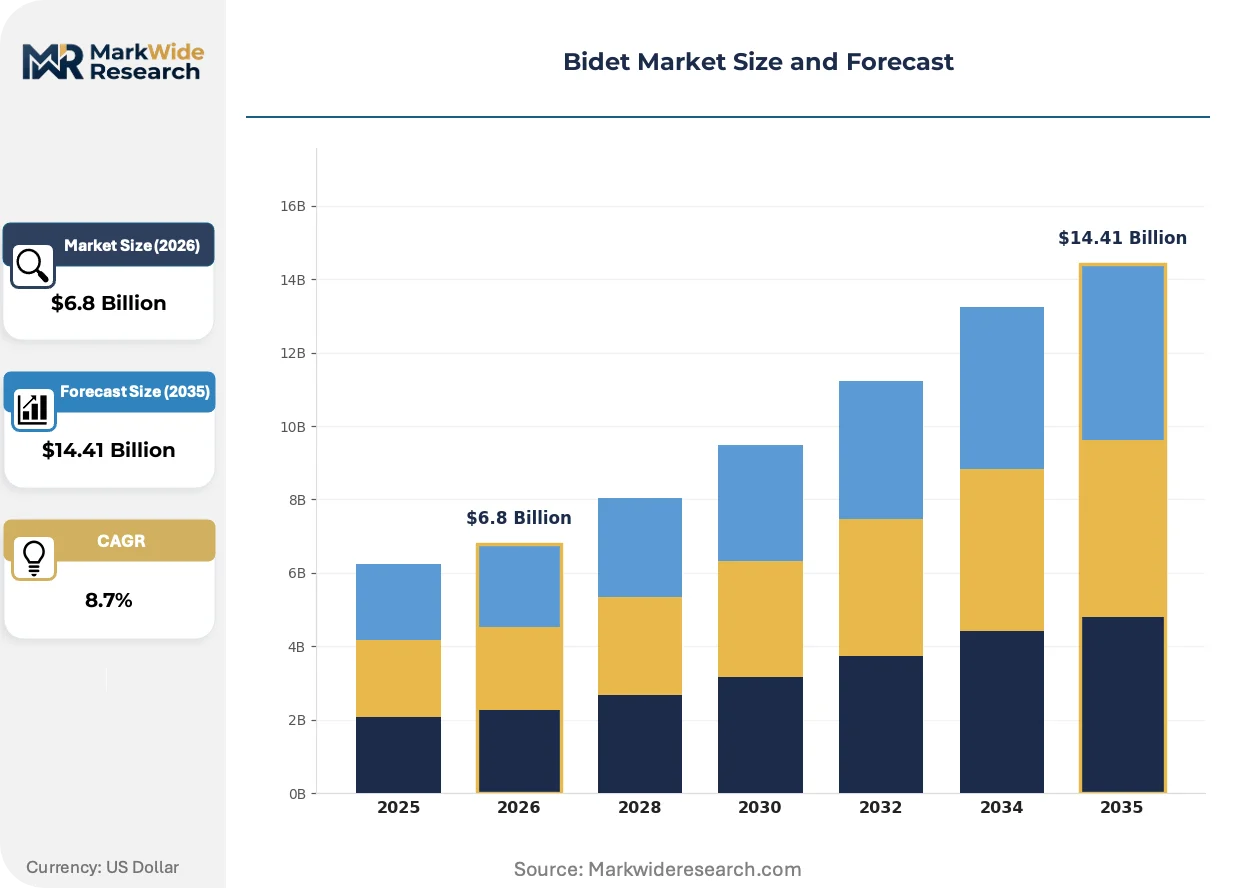
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Bidets, Bidet Toilets, Bidet Attachments, Electronic Bidets End User: Residential Users, Commercial Facilities, Hospitality Sector, Healthcare Institutions Technology: Manual, Electronic, Smart Features, Hybrid Installation: Wall-Mounted, Floor-Mounted, Bidet Conversion Kits, Portable |
| Companies Covered | Bio Bidet, Geberit International AG, Toto Ltd., Bemis Manufacturing Co., Panasonic Holdings Corp., Kohler Co., LIXIL Corp., Duravit AG, Brondell Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bidet Market Emerging Trajectories
Sensor-activated operation and connectivity features are compressing manual control market share, while regulatory water-flow limits and hygiene certification requirements are reshaping product development roadmaps across manufacturing bases.
Ultraviolet-C LED sterilization modules are integrating into electronic bidet nozzle assemblies to eliminate bacterial colonization between uses. Hospitality operators in Japan and South Korea are specifying these systems in new property construction to differentiate guest experience and reduce housekeeping chemical usage. The technology is integrating with existing ceramic production lines without requiring foundry retooling, preserving capital efficiency for mid-tier manufacturers.
Japan's METI energy-efficiency standards for household appliances now encompass bidet seat heating elements, mandating standby power limits that obsolete resistive heating designs. Manufacturers are responding with ceramic plate and instant-heating technologies that reduce continuous energy draw. Premium product lines destined for Japanese domestic market distribution are most affected, with compliance costs absorbed through feature bundling rather than price elevation.
Direct-to-consumer channel expansion is fragmenting traditional plumbing wholesaler dominance in North American distribution. First-time homeowners and renovation DIYers are researching and purchasing bidet attachments through e-commerce platforms before consulting installers, compressing the influence of contractor recommendations on brand selection. This pattern is most visible in United States metropolitan markets where same-day delivery logistics support impulse replacement of failed fixtures.
Bidet Market Segmentation
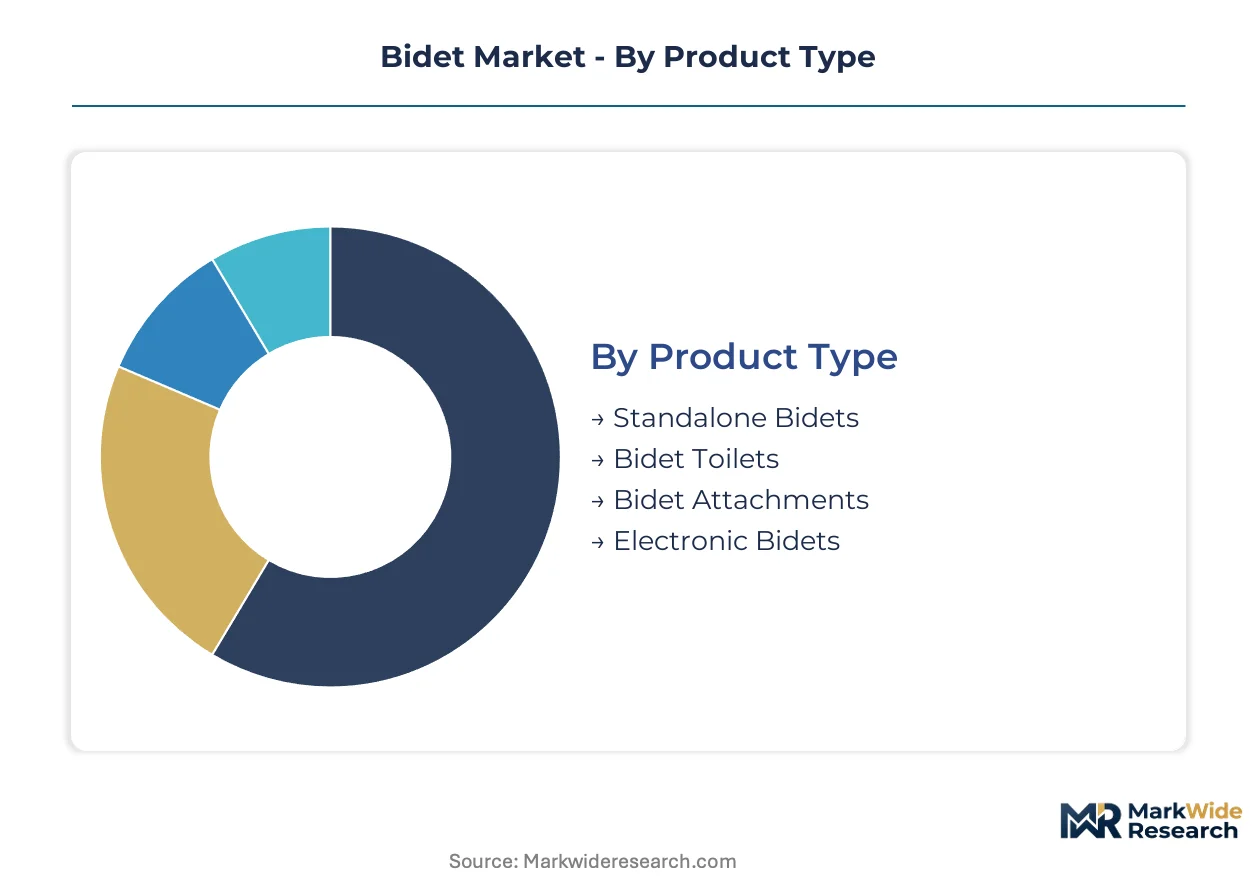
Product configuration in the bidet market spans from basic mechanical attachments to fully integrated smart systems, with each tier demanding distinct supply chain capabilities and installation expertise. Manufacturers must align production flexibility with divergent margin profiles across these categories.
Product Type:
The customization-to-standardization spectrum runs from mass-produced attachments to bespoke integrated systems requiring coordinated plumbing and electrical trades.
- Standalone Bidets:Vitreous china or ceramic fixtures installed adjacent to toilets, featuring independent water supply and drainage. Demand concentrates in European residential renovations where bathroom floor plans accommodate separate fixtures. Aging-in-place retrofits in Germany and France specify these for accessibility compliance.
- Bidet Toilets:Integrated units combining toilet bowl and cleansing functions in single ceramic assemblies. Japan's METI energy standards and JIS certification requirements shape product development for domestic distribution. Toto Ltd. and LIXIL Corp. dominate manufacturing through captive foundry networks.
- Bidet Attachments:Retrofit devices mounting between existing toilet seat and bowl, operating without electrical connection. North American DIY channels drive volume through e-commerce platforms.
- Electronic Bidets:Heated-seat variants with programmable spray patterns, self-sanitizing nozzles, and remote controls. EPA WaterSense flow-rate maximums compel nozzle redesign for US market access.
Most installed capacity flows through Bidet Toilets. Expansion is steepest in Bidet Attachments.
End User:
Application intensity varies from single-fixture residential replacement to multi-unit commercial specifications with centralized maintenance protocols.
- Residential Users:Homeowners and renters undertaking bathroom renovations or accessibility modifications. First-time buyers in United States metropolitan markets research products through direct-to-consumer channels before consulting installers.
- Commercial Facilities:Office buildings and institutional properties specifying durable fixtures with vandal-resistant controls. Joint Commission infection control standards elevate sensor-activated specifications in healthcare-adjacent facilities.
- Hospitality Sector:Hotels and resorts differentiating guest experience through premium bathroom amenities. Japanese and South Korean operators specify ultraviolet-C sterilization modules to reduce housekeeping chemical usage.
- Healthcare Institutions:Hospitals and long-term care facilities mandating hands-free operation for infection prevention. Grab-bar compatibility and ADA compliance shape procurement criteria in United States facilities.
Residential Users account for the dominant share of unit demand. Healthcare Institutions are expanding most quickly.
Technology:
Capital requirements escalate from mechanical simplicity to semiconductor-dependent control systems with firmware update capabilities.
- Manual:Spring-loaded or lever-actuated valves without electrical components. Price-sensitive segments in rental housing and transient-occupancy settings favor these for minimal installation complexity.
- Electronic:Microprocessor-controlled heating and spray functions with user memory settings. Dual-voltage requirements between North American 120V and European 230V systems fragment SKU proliferation.
- Smart Features:Voice-interface compatibility and smart-home ecosystem integration. Connected-home new construction in United States metropolitan markets drives specification.
- Hybrid:Battery-assisted mechanical systems offering limited electronic functions without full wiring requirements. Emerging category bridging cost and convenience gaps.
Electronic systems carry the highest revenue concentration. Smart Features are climbing the fastest.
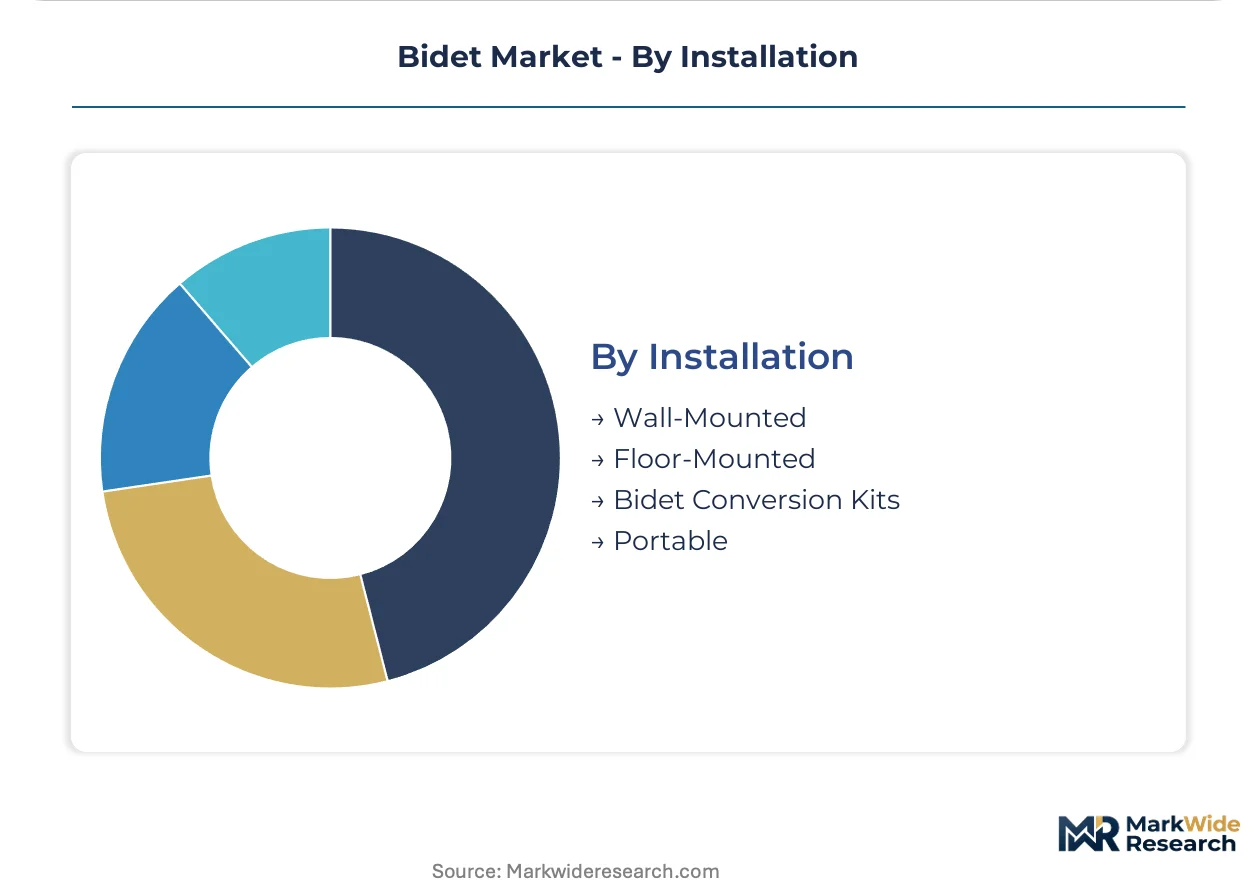
Installation:
Trade coordination intensity ranges from consumer self-installation to licensed plumber-electrician collaboration with permit requirements.
- Wall-Mounted:Fixtures anchored to structural backing with concealed supply lines. European residential construction accommodates these through standardized rough-in dimensions.
- Floor-Mounted:Traditional pedestal or skirted bases connecting to flange-mounted drainage. Foundry capacity for high-grade ceramic concentrates in specific manufacturing regions.
- Bidet Conversion Kits:Adapter hardware enabling toilet-to-bidet transformation without fixture replacement. North American retrofit markets favor these for lower entry cost.
- Portable:Travel-sized units with collapsible reservoirs or bottle attachments. Niche demand from international travelers and camping enthusiasts.
Floor-Mounted systems retain the largest installed base. Bidet Conversion Kits are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's electronic bidet penetration exceeds sixty percent of households while the United States remains below ten percent, illustrating divergent cultural adoption curves that manufacturers navigate through product localization strategies.
United States
Residential renovation cycles and aging-in-place bathroom retrofits drive specification of electronic bidets with grab-bar compatibility. EPA WaterSense flow-rate maximums compel nozzle redesign for compliant product tiers. California's Title 24 building standards accelerate water-efficient fixture adoption in new construction across Los Angeles and San Francisco metropolitan corridors.
Japan
Washlet saturation in residential and commercial properties sustains replacement demand and premium feature upgrades. METI energy-efficiency standards for household appliances mandate standby power limits that obsolete resistive heating designs. Toto Ltd. and LIXIL Corp. anchor manufacturing in the Chubu region around Nagoya through captive ceramic foundry networks.
Germany
European bathroom renovation standards and accessibility compliance in aging housing stock support standalone bidet specification. CE marking requirements for electronic bathroom fixtures create compliance testing cycles that favor established regional producers. Industrial concentration in North Rhine-Westphalia around Düsseldorf and Cologne clusters plumbing fixture distribution and technical service capabilities.
India
Central government cleanliness initiatives targeting household toilet installation create adjacent demand for water-based cleansing fixtures in tier-2 and tier-3 urban construction. Bureau of Indian Standards certification requirements shape product specifications for domestic market entry. Manufacturing activity concentrates in Gujarat and Maharashtra where ceramic foundry capacity serves broader sanitaryware demand.
South Korea
Hospitality sector differentiation through premium bathroom amenities sustains specification of ultraviolet-C sterilization modules in new property construction. Ministry of Trade, Industry and Energy efficiency standards parallel Japanese regulatory frameworks. Seoul Capital Area concentration of hotel development and residential high-rise construction drives premium electronic bidet procurement.
Bidet Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that segments by installation complexity and price tier. Premium integrated systems require captive ceramic supply and coordinated electrical-plumbing distribution, while attachment specialists exploit e-commerce channel fragmentation. Three archetypes dominate: integrated fixture conglomerates with foundry control, electronic component specialists with firmware capabilities, and retrofit attachment assemblers sourcing commoditized valves. Capacity expansion in ceramic foundries and strategic partnerships for smart-home ecosystem integration represent the dominant competitive moves.
Among Japanese integrated fixture producers, Toto Ltd. and LIXIL Corp. exemplify the foundry-captive archetype through Washlet and bidet toilet manufacturing. Panasonic Holdings Corp. represents the electronics-specialist position with component and control system supply. North American diversification is occupied by Kohler Co., which spans multiple installation formats across retail channels. Swiss-headquartered Geberit International AG and German Duravit AG occupy positions within the European premium ceramic fixture tier, while Brondell Inc. and Bio Bidet exemplify the direct-to-consumer attachment specialist model.
| Leading Market Players |
|---|
| Bio Bidet |
| Geberit International AG |
| Toto Ltd. |
| Bemis Manufacturing Co. |
| Panasonic Holdings Corp. |
| Kohler Co. |
| LIXIL Corp. |
| Duravit AG |
| Brondell Inc. |
| Others |
Supply Flow & Price Mechanics
Electronic bidet premium tiers diverge from mechanical attachment commodity tiers through EPA WaterSense certification ladders and ceramic foundry access, with that divergence compressing margins at the low end while insulating pricing power where captive production and regulatory compliance create scarcity.
Pricing Analysis
Capacity additions in Gujarat and Maharashtra ceramic foundries are reshaping price floors for floor-mounted bidet toilets, yet electronic bidet margins resist compression because METI standby power compliance and dual-voltage SKU proliferation inflate cost structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with rental housing buyers exhibiting highest price sensitivity and healthcare institutions showing lowest. Pricing pressure stems from flushable wet wipe substitution in transient-occupancy segments.
Supply Chain Analysis
Direct-to-consumer channels handle North American DIY retrofit demand while plumbing wholesaler networks manage commercial specification flow. Ceramic vitreous china production draws from Japan, Germany, and India, with electronic control systems sourcing from South Korean and Japanese semiconductor assembly. Single-source vulnerability concentrates in Chubu region captive foundries serving Toto and LIXIL. Distribution runs through coordinated electrical-plumbing trade partnerships for integrated systems and e-commerce platforms for attachment kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bidet market compounds steadily as aging-in-place demographics and water-efficiency mandates create replacement cycle visibility across residential and healthcare end uses.
For Market Incumbents: Extend ceramic foundry utilization into ultraviolet-C sterilization module integration, capturing hospitality sector premium specifications. Deepen backward integration into antimicrobial alloy nozzle supply to defend against stainless steel substitution threats. Strengthen EPA WaterSense pre-certification pipelines to lock municipal procurement channels before compliance deadlines tighten.
For New Entrants and Emerging Players: Capture tier-2 and tier-3 Indian urban construction adjacency through Bureau of Indian Standards certification and ceramic fixture bundling. Target North American bidet attachment retrofit white space via direct-to-consumer voice-interface positioning. Pursue smart-home ecosystem partnerships as primary go-to-market anchor.
For Investors and Strategic Acquirers: Consolidation pressure builds where electronic firmware capabilities and ceramic foundry access diverge across mid-tier assemblers. Long-term viability favors foundry-captive integrated fixture producers with healthcare channel penetration. Watch Joint Commission infection control standard expansion as inflection signal for sensor-activated specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Home Ecosystem Integration | Voice-interface compatibility opens premium positioning in connected-home new construction across United States metropolitan markets. |
| Ultraviolet-C Sterilization Module Launch | Japanese and South Korean hospitality operators specify these systems to reduce housekeeping chemical usage. |
| EPA WaterSense Certification Investment | Flow-rate compliance unlocks municipal procurement channels and retail shelf space across California Title 24 corridors. |
| Ceramic Foundry Capacity Expansion | Gujarat and Maharashtra production hubs serve adjacent Indian sanitation upgrade demand from central government cleanliness initiatives. |
| Healthcare Channel Partnership | Joint Commission standards for hospital-acquired infection reduction elevate sensor-activated bidet specifications in facility tenders. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plumbing fixture procurement managers, ceramic foundry operations directors, EPA compliance officers, hospitality FF&E specifiers, and healthcare facilities engineers with secondary validation from EPA WaterSense certification databases, METI appliance efficiency filings, Bureau of Indian Standards registration records, and customs trade flow data. Bottom-up unit shipment modeling and top-down value chain sizing were triangulated against channel inventory checks.
Historical reference periods anchored the projection horizon to observed renovation cycle durations and regulatory adoption lags across jurisdictions. Segmentation dimensions modeled include product configuration tier, installation complexity, end-user application intensity, and technology sophistication level. CAGRs were derived from installed base turnover rates and new construction fixture specification trends, with inputs from aging-in-place demographic projections and municipal plumbing code adoption patterns.
Regulatory timeline delays, ceramic foundry energy cost volatility, and smart-home platform fragmentation are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Artificial Stone Bathtubs Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market