
 Toilet Seat Market | 2026-2036
Toilet Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Seat Market Outlook
Subscription-based filter replacement and maintenance bundling for smart bidet seats is rebalancing how manufacturers capture lifetime value from each installation. Toto leverages its integrated washlet ecosystem to sustain recurring revenue streams across Asian and North American markets. Kohler anchors its competitive position through in-house production of electronic control modules and ceramic bases. Bemis Manufacturing Company specializes in private-label and branded mechanical seats, dominating mass retail channels in the United States.
A toilet seat is a hinged, removable fixture designed to cover the bowl of a water closet, typically manufactured from thermoset plastics, molded wood composites, or ceramic with load-bearing capacities exceeding 150 kg and corrosion-resistant hinge mechanisms. Its primary commercial purpose is to provide hygienic seating, structural closure, and mounting compatibility with standardized bowl geometries across residential and commercial sanitation systems. Elongated and round configurations remain the volume leaders, though bidet-integrated and heated variants capture disproportionate margin pools in premium residential and hospitality channels. Plastic and wood materials occupy the mass-market core, while ceramic and metal variants serve institutional specifications demanding elevated durability and antimicrobial surface properties.
The US EPA WaterSense program and the EU Ecodesign Directive shape product specifications by mandating reduced water consumption and material recyclability thresholds, directly influencing R&D allocation across manufacturers. China's GB standards for sanitary ceramics and Japan's JIS certification for electronic bidet functions create divergent compliance requirements that fragment global product portfolios. Stakeholders must monitor how regional efficiency mandates and smart-home interoperability standards reshape the boundary between commodity seating and connected bathroom fixtures.
Market Dynamics
The toilet seat market is experiencing structural pressure from WaterSense certification mandates, which are compressing replacement cycles and forcing manufacturers to redesign hinge mechanisms and seat geometries for lower-flow bowl compatibility.
Growth Catalysts
- WaterSense Certification:The US EPA's efficiency program mandates reduced water consumption, compelling residential bathroom renovation programs to specify compatible seating. This accelerates replacement demand across North American housing stock.
- Smart Home Integration:Bidet-integrated and heated variants are capturing premium residential channels as urban housing upgrades in China prioritize connected bathroom fixtures with electronic control modules.
- GB Standards Compliance:China's national sanitary ceramics standards are driving specification upgrades in urban housing, creating pull for antimicrobial surface properties and elevated durability in institutional procurement.
Market Restraints
- Thermoset Plastic Input Volatility:Petroleum-derived resin costs fluctuate with crude pricing, compressing margin pools for mass-market mechanical seat producers dependent on molded plastic production.
- Electronic Component Concentration:Smart bidet seat manufacturers face supply risk from concentrated Asian semiconductor and control module suppliers, creating vulnerability in premium product lines.
- JIS Certification Friction:Japan's electronic bidet function standards create divergent compliance requirements that fragment global product portfolios and extend R&D timelines for multi-region launches.
Strategic Opportunities
- Subscription Maintenance Bundling:Filter replacement and service contracts for smart bidet seats enable recurring revenue capture from each installation, rebalancing lifetime value extraction.
- Ecodesign Directive Tailwinds:The EU's material recyclability thresholds are creating preference for ceramic and metal variants in institutional specifications, opening premium margin pools.
- Channel Convergence:Direct-to-installer platforms are displacing traditional wholesale distribution for renovation contractors, compressing working capital requirements and improving specification control.
Industry Challenges
- Cross-Functional Talent Scarcity:Manufacturers struggle to source engineers fluent in both sanitary ceramics engineering and IoT firmware development required for connected seat platforms.
- Dual Certification Timelines:Simultaneous pursuit of WaterSense validation and EU Ecodesign compliance extends product launch schedules by 8-14 months for global portfolio items.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Seat Market |
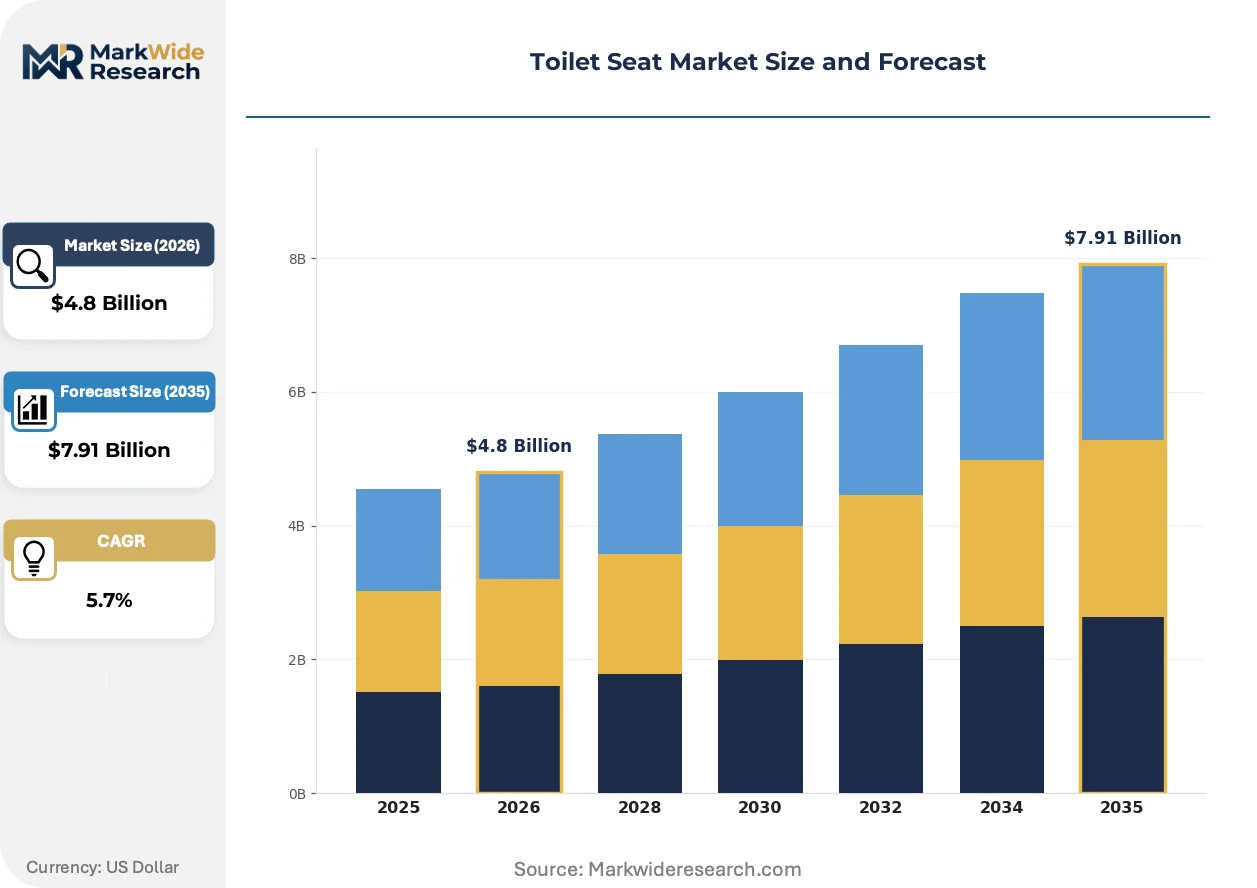
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Elongated, Round, Heated, Bidet Material: Plastic, Wood, Ceramic, Metal Feature: Soft-Close, Automatic, Portable, Quick-Release End User: Residential, Commercial, Institutional, Hospitality |
| Companies Covered | Roca Sanitario, American Standard, Kohler, Bemis Manufacturing Company, Duravit, Toto, Villeroy and Boch, Centoco Manufacturing, Lixil Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Seat Market Strategic Shifts
Connected bathroom fixtures are unifying previously separate hardware categories, while regulatory efficiency mandates and procurement model evolution are compressing traditional specification pathways.
Sensor-integrated bidet seats is unifying temperature control, water pressure modulation, and occupancy detection into single electronic modules. Hospitality chains and premium residential developers are specifying these systems at accelerating rates. This convergence is unifying margin capture around software-enabled service contracts rather than discrete hardware sales.
REACH substance restrictions are reshaping surface coating formulations across European supply chains, forcing manufacturers to eliminate specific antimicrobial chemistries from hinge mechanisms and seat surfaces. Ceramic and thermoset plastic producers are reformulating material specifications to maintain institutional certification eligibility. Germany and France are experiencing the most acute compliance-driven product line adjustments.
Renovation contractors are consolidating purchasing authority through digital procurement platforms, aggregating previously fragmented residential replacement demand. Mass retail channels are losing specification influence as professional installers direct product selection through specialized distributor portals. This concentration is most visible in North American metropolitan renovation markets.
Toilet Seat Market Segmentation
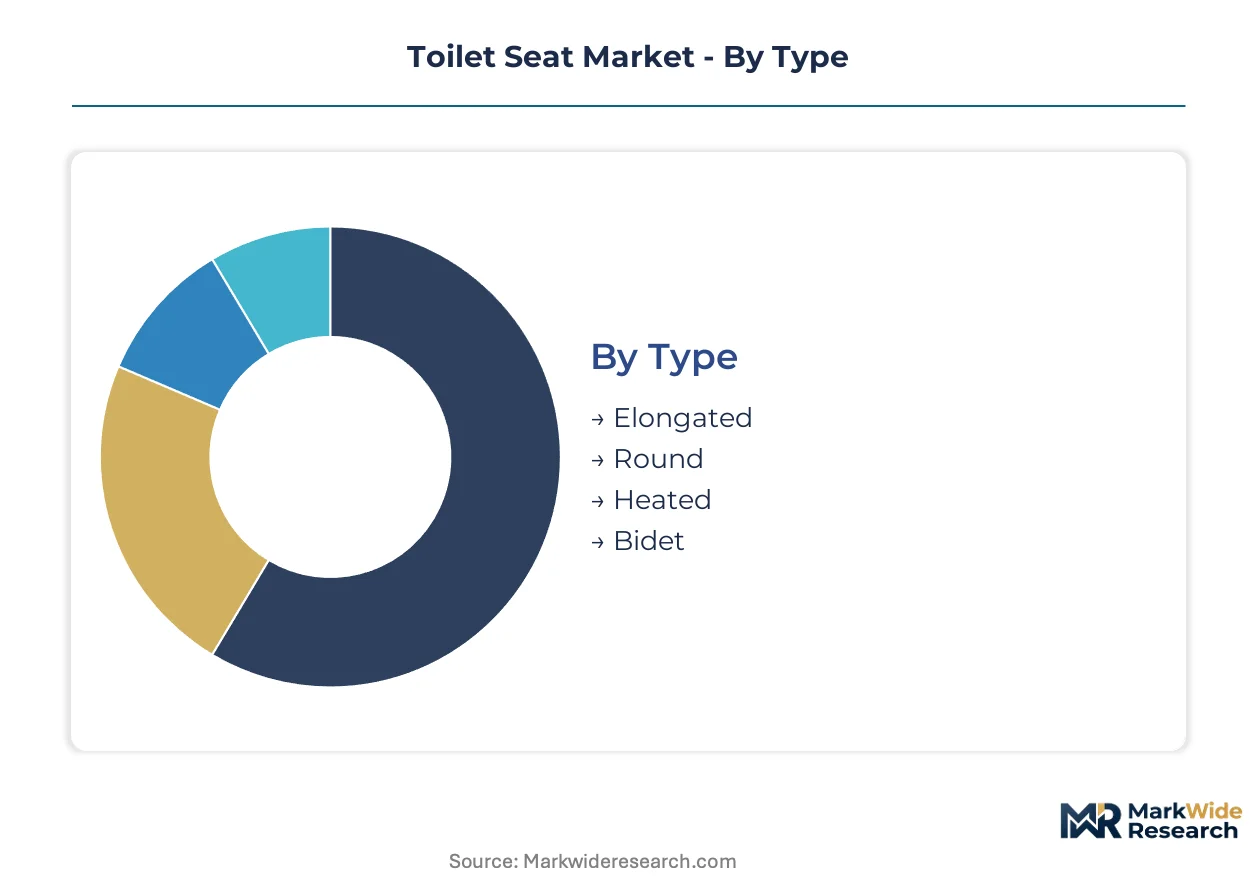
Product differentiation in toilet seating concentrates around bowl geometry compatibility, material durability thresholds, and electronic integration depth. Manufacturers configure production assets around segment-specific capital requirements, with smart bidet platforms demanding semiconductor assembly lines while mechanical seating relies on injection molding capacity.
Type:
Capital intensity escalates sharply from passive mechanical designs through electronically actuated washlet systems, with heated and bidet variants requiring control module fabrication and firmware development infrastructure.
- Elongated:Oval bowl geometries measuring 18.5 inches from mounting holes to front rim dominate new residential construction specifications across the United States. Demand clusters in suburban housing developments where WaterSense-certified low-flow toilets mandate compatible seat geometries.
- Bidet:Electronic washlet platforms integrate retractable spray wands, heated water reservoirs, and occupancy sensors into thermoplastic housings. Urban housing upgrades in China and premium renovation channels in Japan absorb the majority of volume, driven by smart home integration mandates.
- Round:Compact 16.5-inch profiles serve older housing stock and space-constrained bathrooms. Replacement demand sustains production lines without requiring new mold investments.
- Heated:Resistive element integration adds temperature control circuitry to standard seat platforms. Cold-climate residential markets and hospitality specifications drive adoption.
Most installed capacity flows through Elongated. Expansion is steepest in Bidet.
Material:
Raw material selection determines manufacturing footprint scale, with ceramic sintering furnaces representing the heaviest capital commitment and thermoplastic injection lines offering the most flexible capacity deployment.
- Plastic:Thermoset polypropylene and urea-formaldehyde compounds deliver corrosion resistance at sub-$20 price points. Mass retail channels and residential replacement cycles absorb continuous volume from high-throughput molding operations.
- Ceramic:Vitrified clay bodies fired above 1200°C provide antimicrobial surface properties and indefinite service life. Institutional procurement in Germany and France specifies ceramic under REACH-compliant coating reformulations.
- Wood:Molded wood composites with phenolic resin binders occupy mid-tier price positioning. Hospitality renovation programs specify wood for aesthetic warmth in premium guest bathrooms.
- Metal:Stainless steel and chrome-plated brass variants serve detention facilities, healthcare settings, and high-traffic commercial restrooms where vandalism resistance outweighs first-cost considerations.
Plastic commands the largest production base. Ceramic is climbing the fastest on regulatory tailwinds.
Feature:
Value capture mechanics diverge between passive mechanical differentiators and sensor-enabled automation, with the latter requiring firmware development teams and supply chain integration with semiconductor distributors.
- Soft-Close:Damper-integrated hinge mechanisms eliminate slamming through hydraulic or pneumatic resistance. Now standard in mid-tier and above across North American retail.
- Automatic:Proximity sensors trigger lid actuation and pre-wetting cycles. Premium residential and hospitality channels absorb volume where touchless operation carries hygiene signaling value.
- Quick-Release:Detachable hinge pins enable tool-free removal for thorough bowl cleaning. Specification rates rise in healthcare and food service settings.
- Portable:Lightweight folding designs serve camping, RV, and emergency sanitation applications. Niche volume without integration into permanent plumbing systems.
Soft-Close holds the broadest installed base. Automatic is gaining share fastest on hygiene differentiation.
End User:
Procurement authority concentration varies dramatically, with residential decisions fragmenting across individual homeowners while institutional buyers aggregate specification power through centralized facilities management.
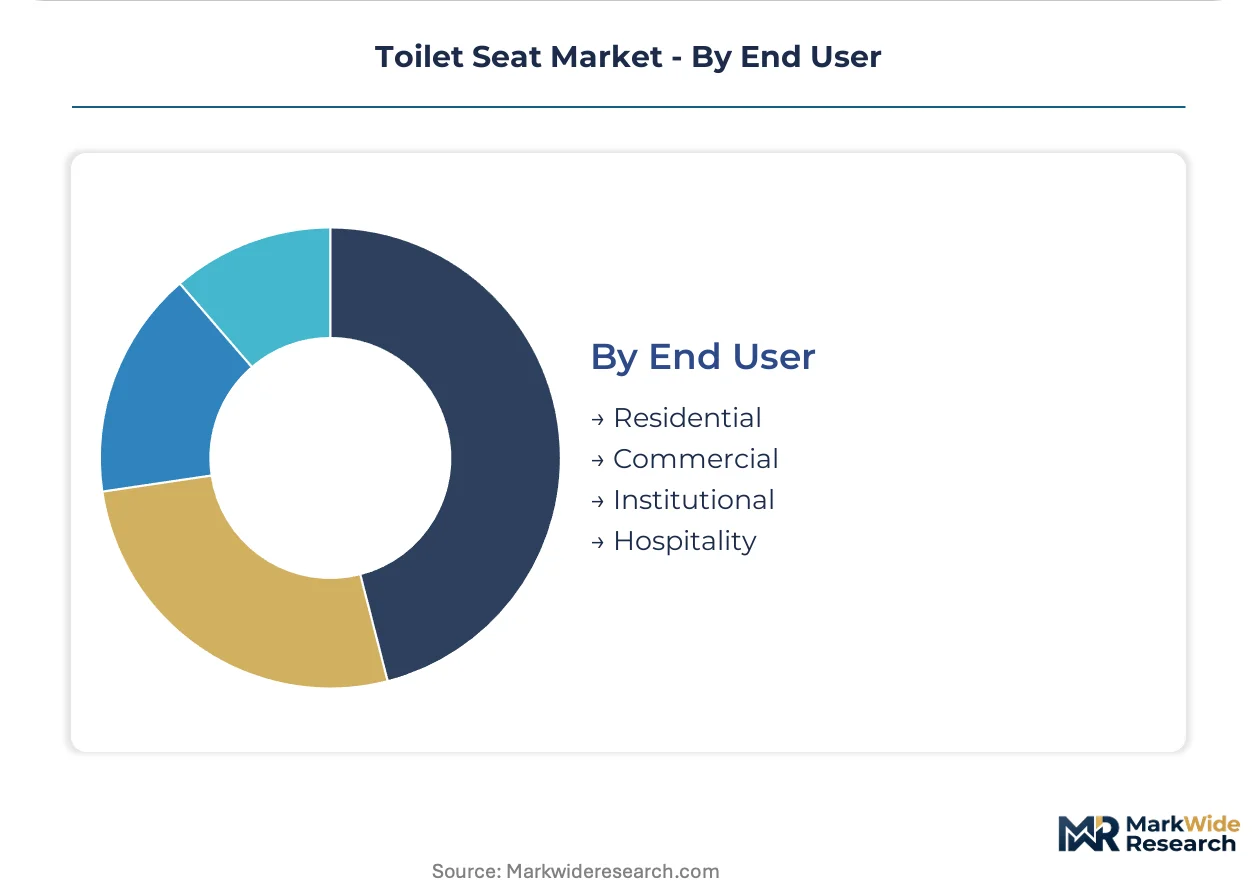
- Residential:Individual homeowners and renovation contractors drive replacement cycles averaging 7-12 years. Digital procurement platforms are consolidating previously fragmented demand in metropolitan markets.
- Hospitality:Hotel chains and cruise operators specify premium bidet and heated variants as competitive amenities. Brand standards increasingly mandate electronic seat platforms in four-star and above properties.
- Commercial:Office buildings and retail facilities prioritize durability and vandalism resistance over comfort features. Metal and heavy-duty plastic dominate specification.
- Institutional:Healthcare, education, and correctional facilities impose antimicrobial surface requirements and ligature-resistant designs. Public procurement frameworks govern the majority of volume.
Residential absorbs the greatest unit volume. Hospitality is expanding most quickly on amenity competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's urban housing stock dwarfs Japan's installed base, yet both markets prioritize electronic bidet penetration through divergent regulatory pathways. Germany and the United States anchor Western demand through institutional procurement and residential renovation cycles respectively.
United States
Suburban housing developments in Texas and Florida drive elongated seat specifications compatible with WaterSense-certified low-flow toilets. The EPA's efficiency program mandates reduced water consumption, compelling bathroom renovation contractors to specify compatible seating geometries. Atlanta and Phoenix metropolitan areas concentrate distributor portals that aggregate fragmented residential replacement demand.
China
Urban housing upgrades in Shanghai and Shenzhen prioritize smart home integration with electronic bidet platforms. GB standards for sanitary ceramics mandate specification upgrades in new construction, creating pull for antimicrobial surface properties. The Yangtze River Delta manufacturing corridor hosts control module suppliers serving domestic washlet assembly lines.
Japan
Tokyo and Osaka metropolitan areas sustain replacement demand for integrated washlet systems with JIS-certified electronic functions. METI oversees standards that fragment global product portfolios through divergent compliance requirements. The Chubu region around Nagoya concentrates semiconductor suppliers for sensor-integrated seat platforms.
Germany
REACH substance restrictions reshape surface coating formulations across Bavarian and North Rhine-Westphalian supply chains. ECHA mandates eliminate specific antimicrobial chemistries from hinge mechanisms, forcing ceramic and thermoset plastic reformulations. The Stuttgart industrial cluster hosts manufacturers pivoting toward EU Ecodesign-compliant institutional specifications.
India
Maharashtra and Gujarat construction booms absorb mass-market plastic seating through high-throughput molding operations. BIS standards for sanitary ceramics create compliance thresholds for imported electronic bidet platforms. The Delhi-NCR corridor concentrates hospitality procurement authority specifying premium heated variants for four-star properties.
Toilet Seat Market Competitive Environment
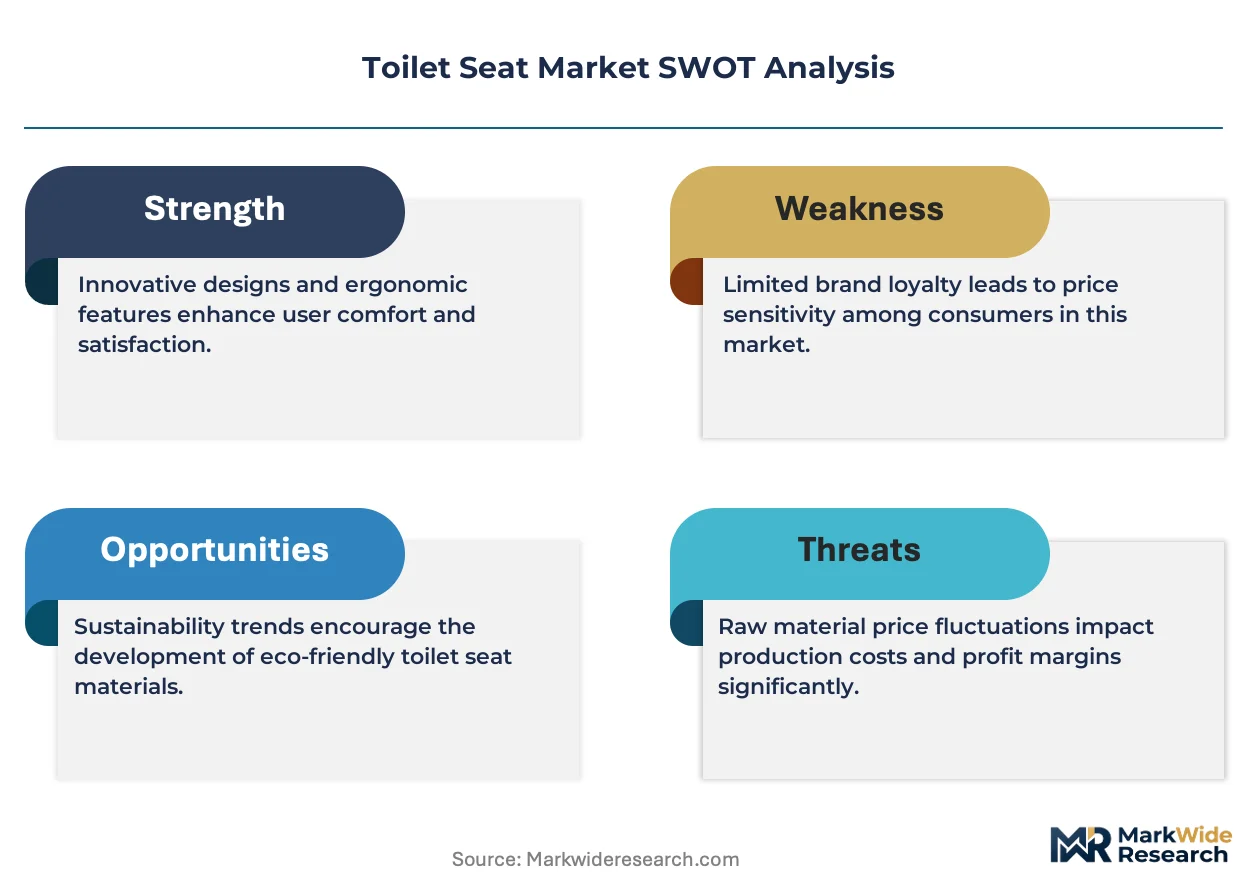
Top-tier vendors anchor integrated washlet ecosystems, while mid-tier fabricators dominate mechanical seating through private-label arrangements. The vendor base stratifies across three functional tiers: semiconductor-integrated platform developers, ceramic-specialized institutional suppliers, and mass-market molded plastic producers. Strategic moves concentrate on backward integration into electronic control modules and captive supply of thermoset resin compounds.
Within the integrated platform tier, Toto and Kohler exemplify divergent approaches to recurring revenue capture. Toto sustains subscription-based filter replacement through its washlet ecosystem across Asian and North American channels. Kohler anchors competitive position through in-house production of electronic control modules and ceramic bases. Bemis Manufacturing Company occupies a distinct position in private-label and branded mechanical seating, dominating mass retail channels in the United States through high-throughput molding capacity.
| Leading Market Players |
|---|
| Roca Sanitario |
| American Standard |
| Kohler |
| Bemis Manufacturing Company |
| Duravit |
| Toto |
| Villeroy and Boch |
| Centoco Manufacturing |
| Lixil Group |
| Others |
Value Chain & Pricing Dynamics
Renovation contractor consolidation through digital procurement platforms is compressing price premiums for branded mechanical seating while elevating specification power for mid-tier electronics. This buyer concentration rewards suppliers with captive control module production and punishes pure-play resin molders exposed to petroleum input volatility.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing corridor are reshaping price floors for electronic bidet platforms. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified washlet systems from WaterSense-compatible mid-tier units and commodity plastic replacements. Pricing pressure stems from thermoset resin cost volatility, which squeezes margin pools for mass-market mechanical seat producers. Residential replacement buyers exhibit highest price sensitivity, while hospitality procurement committees prioritize amenity differentiation over unit economics.
Supply Chain Analysis
Direct-to-installer platforms are displacing traditional wholesale distribution for renovation contractors. Manufacturing concentrates in China, Vietnam, and Mexico, with ceramic sintering furnaces anchored in Germany and Portugal for institutional specifications. Raw material dependencies rest on petroleum-derived polypropylene, semiconductor control modules, and phenolic resin binders for wood composites. Single-source vulnerability concentrates in Asian semiconductor suppliers for sensor-integrated seats. Distribution runs through specialized distributor portals aggregating metropolitan renovation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The toilet seat market functions as a stable compounder anchored by mandatory replacement cycles driven by WaterSense certification and GB standards compliance. Regulatory efficiency mandates ensure steady demand refresh regardless of macroeconomic cyclicality.
For Market Incumbents: Acquire captive electronic control module fabrication capacity to defend against semiconductor supply disruption threatening premium bidet lines. Deepen backward integration into thermoset resin compounding to buffer petroleum input volatility. Secure JIS certification ahead of METI standards evolution to maintain Japanese market access against Korean and Chinese platform competitors.
For New Entrants and Emerging Players: Enter via direct-to-installer digital platforms targeting North American metropolitan renovation markets where specification authority is consolidating. Target hospitality procurement committees in India and Southeast Asia specifying premium heated variants as competitive amenities. Pursue private-label arrangements with mass retail chains seeking to displace legacy mechanical seat suppliers.
For Investors and Strategic Acquirers: Building products conglomerates with bathroom fixture portfolios are the most active acquirer in this space, seeking washlet platform capabilities to complete smart home ecosystems. Mid-cap electronics assemblers with semiconductor relationships represent optimal acquisition targets. Monitor REACH substance restriction enforcement in Germany as signal for ceramic and metal variant demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Modules | Kohler's in-house electronic production insulates premium bidet lines from Asian semiconductor concentration risk. |
| Subscription Filter Replacement Launch | Toto's recurring revenue capture from washlet ecosystems rebalances lifetime value extraction toward service contracts. |
| REACH-Compliant Coating Reformulation | Ceramic producers pivoting toward ECHA-mandated surface chemistry maintain German institutional procurement eligibility. |
| Direct-to-Installer Platform Deployment | Digital procurement portals aggregating renovation contractor demand compress working capital requirements and improve specification control. |
| WaterSense Certification Acceleration | EPA-mandated low-flow compatibility compresses replacement cycles across North American housing stock. |
Study Parameters
Bottom-up residential and hospitality procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with product development directors at integrated washlet manufacturers, procurement managers at hospitality chains, renovation contractor purchasing coordinators, and facilities management executives at healthcare systems were cross-validated against secondary sources including EPA WaterSense certification databases, ECHA REACH substance restriction filings, and customs trade records for thermoset plastic resin imports.
Historical trendline analysis across product type, material grade, feature integration depth, and end-use vertical established baseline penetration rates. Segmentation dimensions modeled include bowl geometry configuration, electronic integration tier, surface material specification, and regional regulatory compliance cluster. CAGRs were derived from replacement cycle velocity analysis and new construction fixture specification rates, with semiconductor availability and petroleum resin pricing incorporated as sensitivity inputs.
Inputs from METI JIS certification registries and EPA WaterSense product listings were available through the study window; gaps in real-time hospitality procurement contract data introduce uncertainty bands around premium segment forecasts. Periodic stress-testing of base assumptions against regulatory enforcement timelines and raw material cost trajectories is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Plumbing Fixtures and Fittings Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market
Bathroom Fixtures and Accessories
India Steam Rooms Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Faucet Market