
 Artificial Stone Bathtubs Market | 2026-2036
Artificial Stone Bathtubs Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Stone Bathtubs Market Insights
Freestanding-plus-accessory bundling is consolidating buyer choice around complete bathroom suites rather than standalone tubs. Kohler leverages its captive distribution network to control specification flow in North American hospitality projects. MTI Baths anchors its position through deep specialization in custom solid-surface configurations. KingKonree competes on manufacturing scale across quartz composite and engineered stone formulations.
Artificial stone bathtubs are cast or molded fixtures composed of mineral fillers bound with resin or acrylic polymers, typically achieving wall thicknesses of 12-25 millimeters and weights of 80-200 kilograms depending on size and formulation. Their primary commercial purpose centers on delivering stone-like aesthetics and thermal mass with consistent coloration and repairability superior to natural stone. Quartz composite and engineered stone formulations lead in margin contribution due to material premiums and brand positioning, while resin-based drop-in installations occupy the high-volume renovation channel where cost sensitivity dominates contractor specifications. Freestanding shapes across rectangular and oval profiles sustain the fastest expansion as residential developers and boutique hotels prioritize spatial statement pieces.
The EPA regulates VOC emissions from resin manufacturing facilities under Clean Air Act standards, while China's SAMR enforces GB standards for sanitary ceramic and stone products including artificial stone fixtures. REACH compliance in Europe restricts specific phthalates and heavy metals in polymer binders, reshaping formulation requirements for export-oriented manufacturers. Stakeholders must monitor evolving chemical disclosure mandates across multiple jurisdictions to preempt supply chain disruption and secure specification eligibility in premium project channels.
Market Dynamics
Resin formulation chemistry is fragmenting competitive advantage as China's GB standards for VOC emissions force manufacturers to reformulate mineral-polymer binders or exit specification-eligible channels entirely.
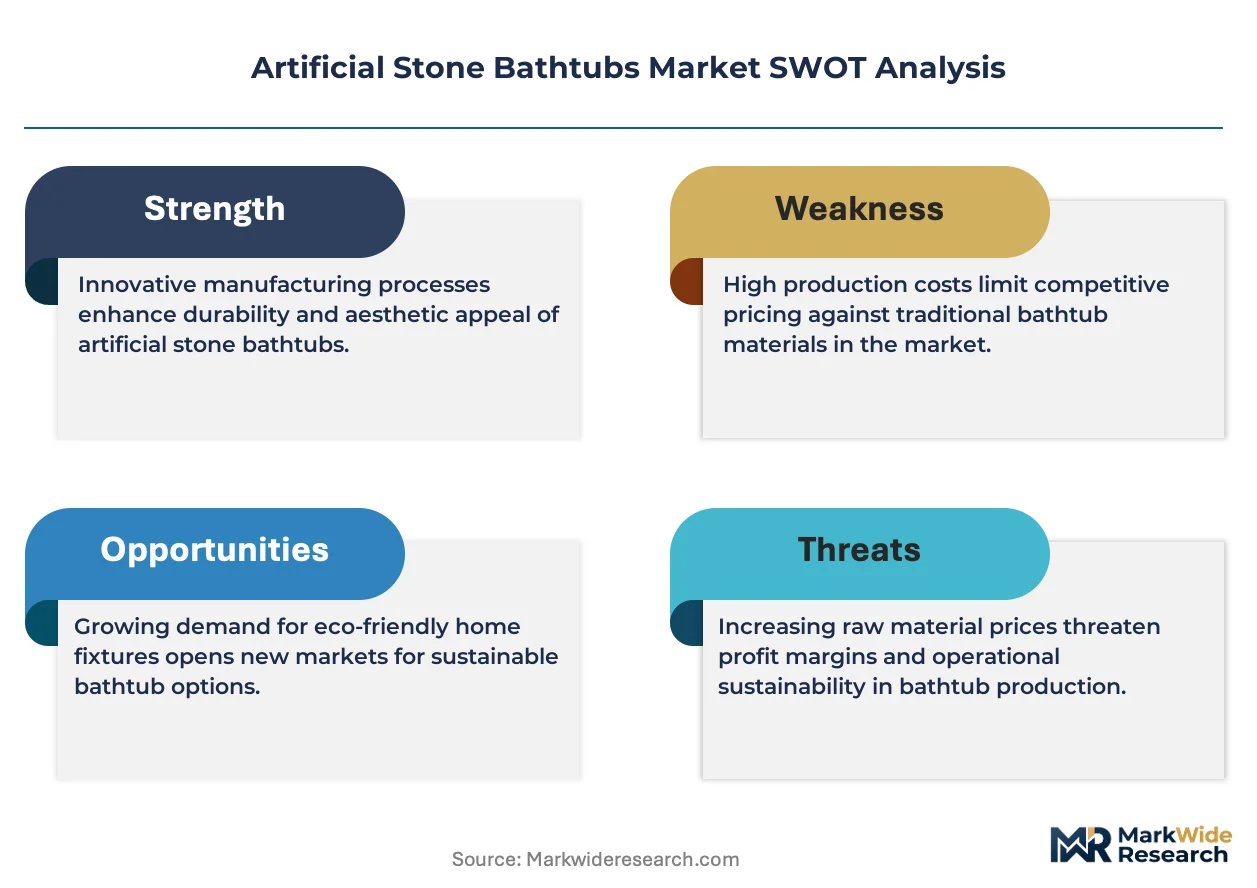
Growth Catalysts
- REACH compliance migration:European ECHA restrictions on phthalates in polymer binders are accelerating reformulation investments by export-oriented Chinese manufacturers, opening premium specification access previously blocked by chemical disclosure gaps.
- Boutique hospitality procurement:Vietnam's hospitality construction corridor is absorbing freestanding oval and rectangular profiles as developers prioritize spatial statement pieces in coastal resort developments.
- GB standards tightening:China's SAMR enforcement of stricter VOC emission limits for resin-based sanitary ware is consolidating supply around compliant mineral-acrylic formulations with documented emission testing.
Market Restraints
- Petrochemical input volatility:Unsaturated polyester resin and methyl methacrylate monomer prices fluctuate with crude oil derivatives, compressing margin predictability for cast-mold producers without captive chemical supply.
- Quartz composite supply concentration:Engineered stone slab feedstock for bathtub production clusters in Fujian and Guangdong provinces, creating geographic vulnerability to regional environmental enforcement actions.
- Natural stone substitution:Carrara and travertine alternatives retain specification preference in ultra-luxury residential segments where thermal mass authenticity outweighs repairability advantages.
Strategic Opportunities
- Solid-surface customization:Thermoformable acrylic-mineral composites enable bespoke geometries for architect-specified wellness installations, capturing margin premiums unavailable to standardized casting operations.
- Accessory bundling integration:Freestanding tub-plus-vanity-plus-basin suite procurement is consolidating contractor specifications around single-source bathroom system providers.
- EPA Clean Air Act alignment:US resin manufacturing facilities achieving Title V permit compliance can access hospitality specification flows requiring documented emission control throughout the supply chain.
Industry Challenges
- Thermoforming technician scarcity:Custom solid-surface production requires skilled heat-and-mold specialists whose training pipelines lag demand expansion in Southeast Asian manufacturing zones.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of GB standards compliance, REACH registration, and EPA facility permits extends product launch cycles by 18-24 months for reformulated resin systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Stone Bathtubs Market |
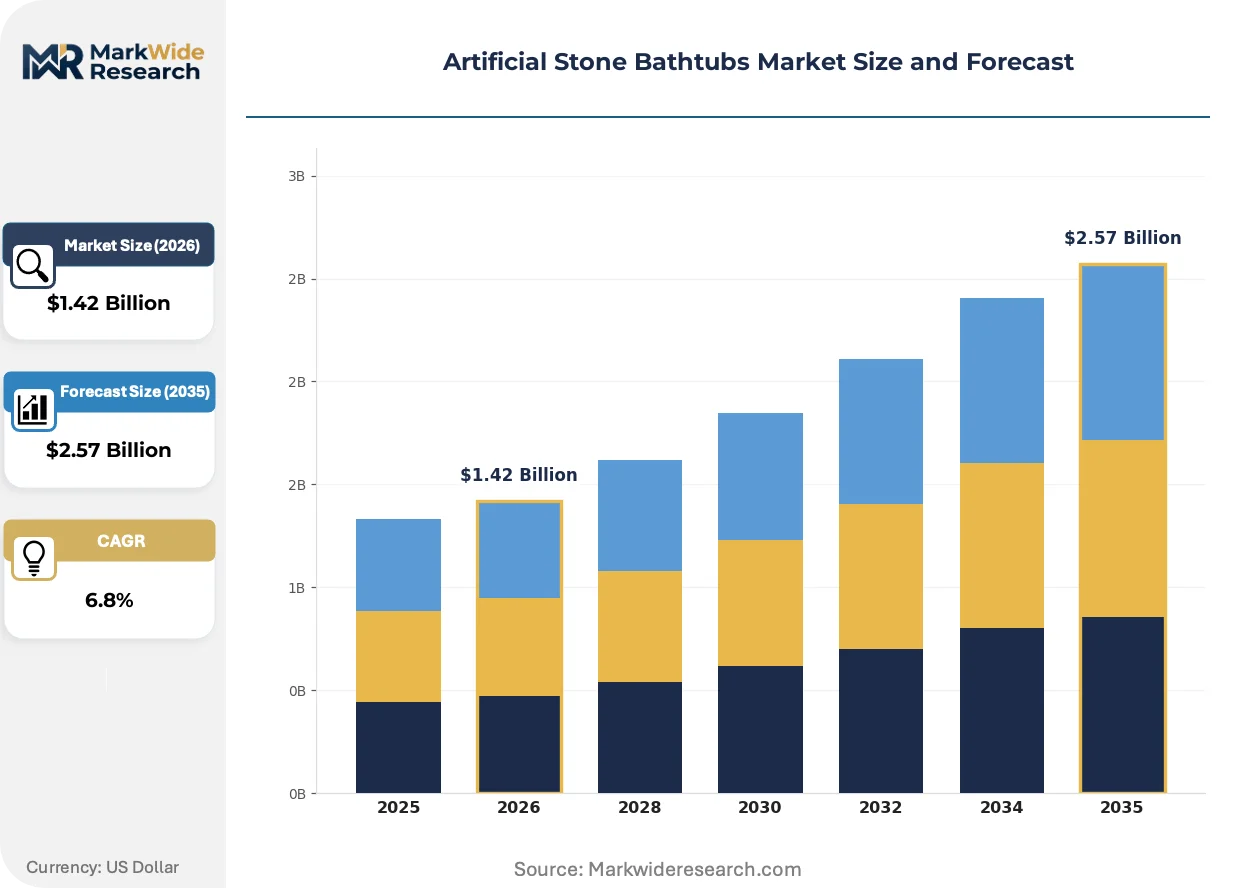
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Quartz Composite, Marble Composite, Resin, Acrylic Blend, Engineered Stone Shape: Rectangular, Oval, Round, Square, Freeform End User: Residential Developers, Boutique Hotels, Luxury Spas, Wellness Centers, Renovation Contractors Installation Type: Freestanding, Drop-in, Alcove, Corner, Undermount |
| Companies Covered | KingKonree, MTI Baths, MUNK, Kohler, Aquatica, Badeloft, KDY Bath, Toto, Vanity Art, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Stone Bathtubs Market Trends and Innovations
Automation of casting and finishing operations is compressing unit economics while regulatory chemical disclosure mandates are reshaping formulation transparency requirements across export markets.
Closed-loop resin mixing and vacuum-degassing systems are automating wall-thickness consistency in cast-mineral production, reducing manual finishing labor by half. North American hospitality project specifiers are prioritizing suppliers with automated quality documentation. This automation is compressing price differentials between mid-tier and premium manufacturing tiers.
China's GB standards for sanitary ware now mandate third-party VOC emission testing with published test reports, eliminating self-certified material claims. Export manufacturers must maintain dual formulation inventories: compliant versions for regulated markets, legacy versions for price-sensitive domestic renovation channels. Quartz composite bathtub lines face the steepest compliance cost escalation due to higher resin loading ratios.
Boutique hotel developers are consolidating procurement around complete bathroom suite specifications rather than standalone fixture bidding, favoring suppliers with integrated vanity, basin, and tub catalogs. Southeast Asian hospitality construction corridors are the primary venue for this bundling shift. Specifiers in Vietnam's Da Nang-Phu Quoc axis increasingly disqualify standalone tub vendors from shortlists.
Artificial Stone Bathtubs Market Segmentation
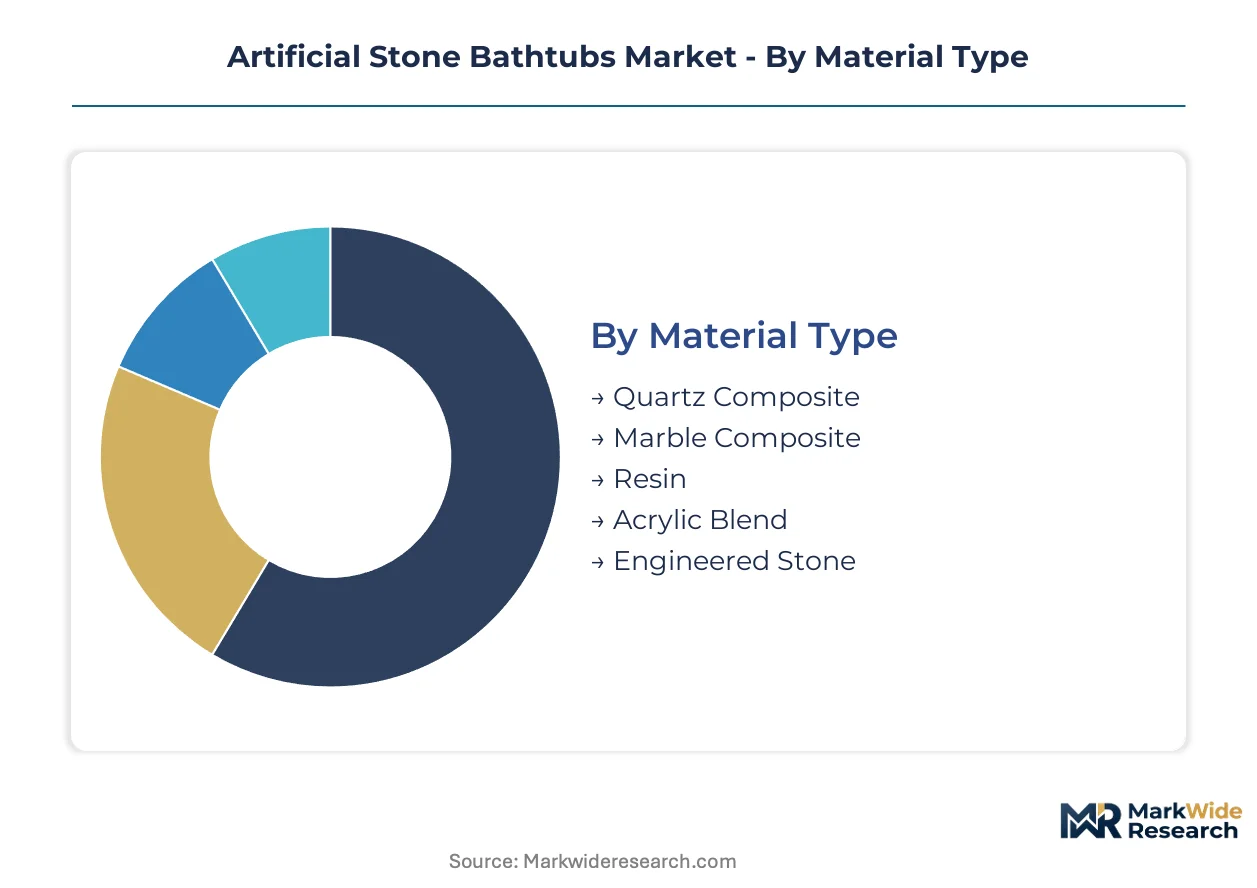
Artificial stone bathtub procurement splits across material chemistry, spatial configuration, and channel access. Each segmentation axis reveals distinct margin structures and specification barriers that reshape competitive positioning.
Material Type:
Upgrade cycles vary dramatically by material durability and surface degradation profiles, with premium formulations commanding replacement intervals three times longer than economy alternatives.
- Quartz Composite:Mineral-quartz aggregates bound with polyester resin achieve superior scratch resistance and thermal stability. Vietnam's hospitality construction corridor specifies quartz composite for coastal resort developments where salt-air corrosion accelerates surface degradation in lesser formulations.
- Engineered Stone:Vacuum-vibrated mineral blends with controlled porosity deliver consistent color matching across large installations. China's GB standards for VOC emissions have forced reformulation of traditional engineered stone binders, consolidating supply around compliant acrylic-polymer alternatives.
- Marble Composite:Calcium carbonate fillers with resin binders replicate natural veining at reduced weight.
- Resin:Cast polymer systems dominate renovation channel volume through cost-optimized formulations.
- Acrylic Blend:Thermoformable mineral-acrylic composites enable custom geometries for architect-specified wellness installations.
Volume placements concentrate in Resin; the faster expansion belongs to Quartz Composite.
Shape:
Cost tier separation runs deepest in shape selection, where manufacturing complexity and freight logistics create step-function price escalations between standardized and custom profiles.
- Freestanding:Self-supporting sculptural forms require reinforced wall structures and floor-load engineering. Boutique hotels across Southeast Asia prioritize freestanding oval and rectangular profiles as spatial statement pieces in guest bathroom designs.
- Rectangular:Modular dimensional standards align with global shipping container optimization and contractor familiarity. Residential developers in China's tier-two cities specify rectangular drop-in units for high-volume apartment fit-outs where installation speed dominates specification criteria.
- Oval:Curved geometries command thermoforming expertise or multi-piece casting with seam concealment.
- Round:Compact footprints suit urban bathroom constraints in Japanese and Korean residential markets.
- Square:Sharp-cornered modern aesthetics align with contemporary architectural minimalism.
Rectangular configurations dominate unit shipments; freestanding shapes are climbing the fastest as hospitality procurement shifts toward experiential bathroom design.
End User:
Customer type determines specification authority concentration, with project-scale buyers wielding bundled procurement leverage unavailable to fragmented retail channels.
- Boutique Hotels:Design-forward properties with 50-200 room counts prioritize distinctive bathroom fixtures as brand differentiation tools. Vietnam's Da Nang-Phu Quoc development axis is absorbing freestanding artificial stone tub capacity as coastal resort construction accelerates.
- Residential Developers:Volume purchasers of standardized configurations across multi-unit construction. China's presale apartment market demands rapid bathroom installation cycles that favor drop-in resin units with documented GB standards compliance.
- Luxury Spas:Wellness-focused facilities requiring hydrotherapy integration and ergonomic depth profiles.
- Wellness Centers:Commercial bathing facilities with high-cycling durability requirements.
- Renovation Contractors:Price-sensitive replacement market accessing artificial stone as natural stone alternatives.
Residential Developers move the highest unit volumes; Boutique Hotels represent the steepest expansion trajectory as Southeast Asian hospitality investment accelerates.
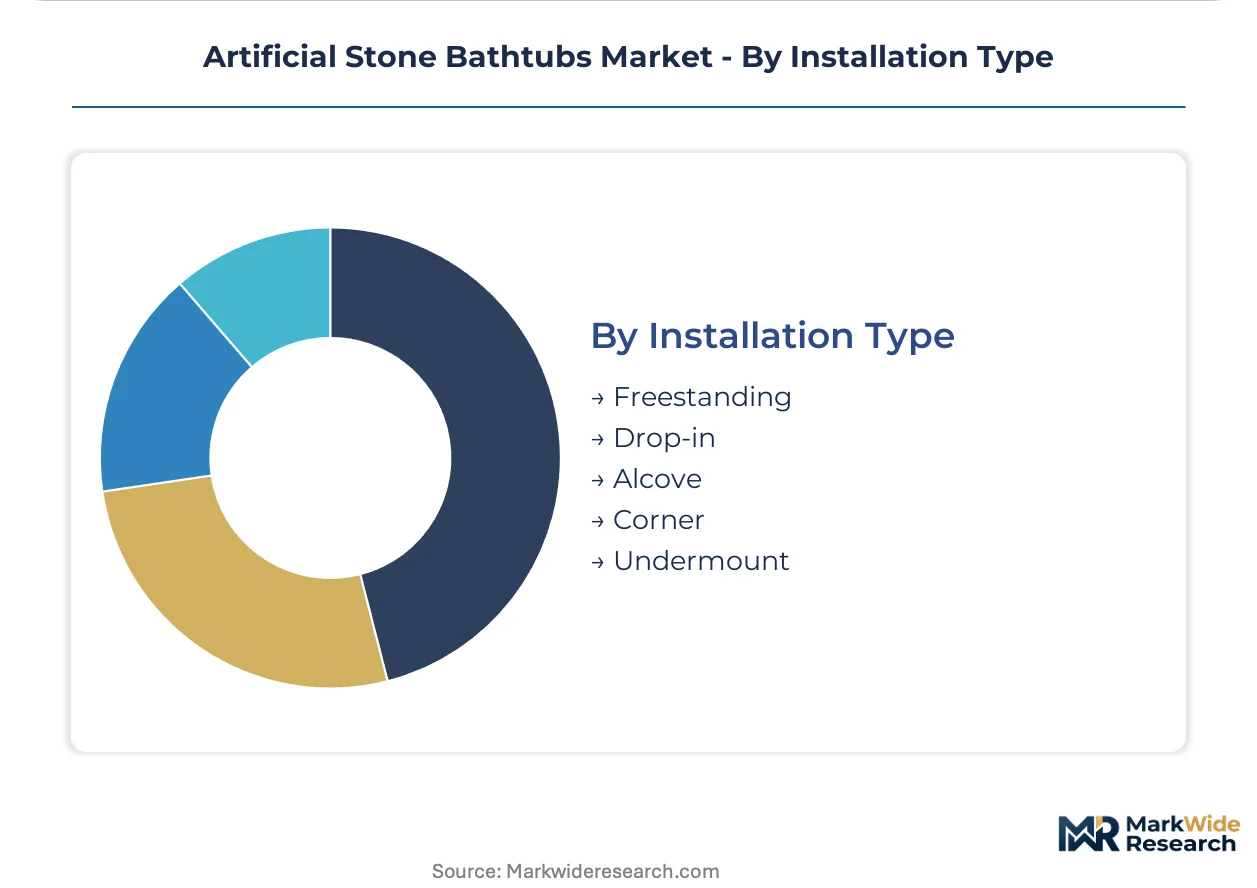
Installation Type:
Supply concentration in molded-cast manufacturing favors certain installation geometries while excluding others from efficient production.
- Freestanding:Complete perimeter exposure demands flawless surface finish and structural self-support. North American hospitality specifiers increasingly require freestanding units with automated quality documentation and supply chain emission disclosures.
- Drop-in:Rim-supported designs integrate with built-up platform construction common in renovation applications. China's domestic renovation channel absorbs drop-in resin units where cost sensitivity dominates contractor specifications and GB standards compliance remains uneven.
- Alcove:Three-wall surround configurations maximize space efficiency in compact residential bathrooms.
- Corner:Angular placement geometries suit non-rectangular bathroom footprints.
- Undermount:Deck-integrated profiles require precise countertop coordination and waterproofing.
Drop-in installations retain the highest shipment volumes; freestanding configurations are gaining share fastest as design-specified bathroom aesthetics displace contractor-driven selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China's coastal provinces while consumption disperses across Southeast Asian hospitality corridors and North American renovation channels. This geographic split creates divergent regulatory exposure and margin profiles for suppliers serving each demand node.
China
Domestic apartment presales absorb standardized drop-in resin units where GB standards compliance has become a non-negotiable specification filter. SAMR enforcement of third-party VOC emission testing is eliminating self-certified material claims from government-procured projects. Fujian and Guangdong provinces concentrate engineered stone slab feedstock production, though environmental enforcement actions periodically disrupt regional supply.
Vietnam
The Da Nang-Phu Quoc coastal development axis is absorbing freestanding oval and rectangular profiles as boutique resort construction accelerates. Hospitality developers prioritize spatial statement pieces that differentiate guest bathroom experiences in competitive coastal markets. Local distributors report consolidation of procurement around complete bathroom suite specifications rather than standalone fixture bidding.
United States
North American hospitality project specifiers increasingly require automated quality documentation and supply chain emission disclosures for freestanding unit qualification. EPA Title V permit compliance at resin manufacturing facilities has become a specification gate for premium project channels. California and Florida hospitality markets lead adoption of documented emission control throughout supply chain verification.
Germany
REACH compliance migration is accelerating reformulation investments by export-oriented manufacturers seeking premium specification access previously blocked by chemical disclosure gaps. ECHA restrictions on phthalates in polymer binders are reshaping formulation requirements for bathtub products destined for European markets. Bavarian and North Rhine-Westphalian distributors report preference for suppliers with dual GB standards and REACH registration documentation.
Japan
Compact round and square configurations dominate residential replacement demand in urban bathroom constraints across Greater Tokyo and Osaka metropolitan areas. METI energy efficiency guidelines indirectly influence material selection through thermal mass performance expectations. Kanto region renovation contractors specify artificial stone as natural stone alternatives where weight restrictions limit traditional material deployment.
Artificial Stone Bathtubs Market Competitive Landscape
The competitive structure tilts toward manufacturing-scale specialists with compliant formulation capabilities and captive distribution networks controlling specification flow in project channels. Market concentration remains moderate with tiered differentiation between premium custom fabricators, mid-scale standardized producers, and regional renovation suppliers. Two strategic archetypes dominate: vertically integrated mineral-polymer compounders with in-house resin formulation, and design-forward specialists leveraging thermoformable solid-surface customization. Dominant competitive moves include backward integration into mineral filler sourcing and strategic bundling of freestanding tubs with coordinated vanity and basin suites.
Among North American fabricators, Kohler and MTI Baths occupy positions reflecting divergent strategic postures. Kohler exemplifies the captive distribution archetype with network control over hospitality specification flows. MTI Baths represents deep specialization in custom solid-surface configurations. KingKonree anchors the manufacturing-scale tier among Asia-Pacific compounders competing across quartz composite and engineered stone formulations.
| Leading Market Players |
|---|
| KingKonree |
| MTI Baths |
| MUNK |
| Kohler |
| Aquatica |
| Badeloft |
| KDY Bath |
| Toto |
| Vanity Art |
| Others |
Pricing and Supply Chain Analysis
Thermoforming technician scarcity in Southeast Asian manufacturing zones widens labor-cost differentials between standardized casting operations and custom solid-surface fabrication, compressing margin spreads across premium and economy tiers as automation investments partially offset skill premiums.
Pricing Analysis
Margin tightening in mid-tier quartz composite lines traces to GB standards compliance costs and petrochemical input volatility, forcing manufacturers to absorb reformulation expenses or cede share to compliant rivals. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered European-export units from domestic China renovation channel products, with boutique hotel specifiers exhibiting lowest price sensitivity and residential renovation contractors highest.
Supply Chain Analysis
Single-source vulnerability sits with Fujian and Guangdong province engineered stone slab feedstock, where environmental enforcement actions periodically disrupt regional mineral-polymer compound availability. Raw material dependencies center on unsaturated polyester resin from petrochemical derivatives, methyl methacrylate monomer, and calcium carbonate fillers sourced from Vietnam and Malaysia. Distribution runs through captive specification networks in North American hospitality and fragmented distributor channels in Southeast Asian construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's SAMR enforcement of third-party VOC emission testing creates a regulatory moat consolidating supply around documented mineral-acrylic formulations and eliminating self-certified competitors from premium project channels.
For Market Incumbents: Acquire captive resin formulation capabilities or mineral filler quarries to secure input cost predictability against petrochemical volatility and regional environmental enforcement disruptions. Defend specification flow in Vietnam's hospitality corridor through pre-integrated bathroom suite catalogs that disqualify standalone tub vendors from boutique resort shortlists. For New Entrants and Emerging Players: The premium-to-economy price-point gap in custom solid-surface wellness installations offers white-space entry for thermoformable acrylic-mineral composite specialists with architect-direct relationships. Target Vietnam's Da Nang-Phu Quoc development axis where procurement consolidation around complete bathroom systems favors single-source entrants with documented emission disclosures over fragmented component suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mineral-polymer compounders possessing dual GB standards and REACH registration documentation, given accelerating reformulation investments by export-oriented manufacturers seeking premium European specification access. Watch ECHA phthalate restriction expansion timelines as inflection indicators for compliant formulation premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Filler Sourcing | Captive supply of calcium carbonate and quartz aggregates insulates margin from Fujian-Guangdong environmental enforcement volatility. |
| Dual Certification Investment | Simultaneous GB standards and REACH registration opens specification eligibility in China's government-procured projects and European premium channels. |
| Freestanding-Plus-Accessory Bundling | Pre-integrated bathroom suite catalogs capture contractor consolidation toward single-source providers in Southeast Asian hospitality procurement. |
| Automation of Casting Operations | Closed-loop resin mixing and vacuum-degassing systems compress unit economics between mid-tier and premium manufacturing tiers. |
| Thermoforming Technician Training Pipeline | Skilled heat-and-mold specialist development addresses capability scarcity constraining custom solid-surface expansion in Southeast Asian zones. |
Research Methodology
Independent corroboration across plant managers at Fujian and Guangdong compounding facilities, procurement leads at North American hospitality developers, and distribution channel partners in Vietnam's construction corridor underwrites the qualitative findings. Secondary validation drew from SAMR GB standards documentation, ECHA REACH registration databases, EPA Title V permit records, and customs trade data for mineral-polymer bathtub imports. Bottom-up capacity assessments and top-down consumption estimates were reconciled through iterative triangulation.
Rate-of-change decomposition across material chemistry, spatial configuration, end-user segment, and installation type dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by margin contribution, with inputs from presale apartment construction pipelines in China's tier-two cities, coastal resort development permits in Vietnam's Da Nang-Phu Quoc axis, and North American hospitality capital expenditure disclosures.
Inputs from ECHA regulatory filings and SAMR enforcement bulletins were available through the study window; gaps in real-time petrochemical derivative pricing introduce uncertainty bands around margin forecasts for resin-dependent formulations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market
Bathroom Fixtures and Accessories
Toilet Seat Market