
 Europe Bath Fitting Market | 2026-2036
Europe Bath Fitting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bath Fitting Market Foresight
Residential-to-hospitality demand is rebalancing across Europe as boutique hotel construction in Lisbon, Barcelona, and Milan outpaces single-family housing starts in Northern markets. Grohe leverages its German manufacturing base to dominate specification channels for premium commercial projects. Hansgrohe differentiates through WaterSense-adjacent engineering adapted for EU Ecodesign compliance. Villeroy & Boch anchors the ceramic sanitaryware segment with deep vertical integration into its own kiln operations.
Europe bath fittings encompass plumbed fixtures and accessories that regulate, direct, or contain water for personal hygiene, typically manufactured from brass castings with chrome or PVD surface finishing to resist chloride corrosion in hard-water environments. Their primary purpose centers on delivering metered water flows while meeting acoustic, thermal, and pressure-performance thresholds for building certification. Faucets and showers together command the largest product-type share, with brass-bodied mixer valves retaining margin pools despite stainless-steel encroachment in budget specifications. Modern and minimalist design styles are capturing specification share in new-build hospitality, while traditional styling sustains replacement demand across heritage residential stock in France and the UK.
The EU Ecodesign Directive, REACH, and CE marking collectively shape product compliance costs and market access across member states, with ECHA scrutiny of nickel and lead content in brass alloys forcing reformulation of cast billet feedstocks. National building codes in Germany and France layer additional acoustic and pressure-testing requirements that filter out non-specialist importers. Stakeholders must monitor how the EU Green Deal's embodied-carbon reporting rules will reconfigure material sourcing decisions for ceramic and metal components alike.
Market Dynamics
The EU Ecodesign Directive is compressing flow-rate tolerances across all plumbed fixtures, forcing brass foundries to re-engineer casting geometries and valve architectures before the next compliance deadline. This regulatory tightening intersects with Southern Europe's hospitality renovation wave to create simultaneous pressure on manufacturing flexibility and specification-grade capacity.
Growth Catalysts
- Hospitality Renovation Cycles:Boutique hotel construction in Lisbon, Barcelona, and Milan is accelerating fixture replacement schedules. Water-efficient mixer valves now dominate new-build specifications across Iberian and Italian hospitality clusters.
- REACH-Driven Alloy Reformulation:ECHA scrutiny of nickel and lead content in brass billet feedstocks is compelling foundries to develop low-lead casting grades. Compliant alloys are unlocking specification access in Germany and France.
- Water Labeling Mandates:Tighter EU Energy Label framework requirements for water consumption disclosure are steering procurement toward lower-flow technologies. Retail and contract channels now prioritize labeled fixtures.
Market Restraints
- Brass Input Cost Volatility:Copper and zinc price swings from Chilean and Peruvian concentrate supply disruptions are compressing margin pools for mid-tier manufacturers. Foundries lack pricing power to pass through raw material spikes.
- Acoustic Certification Barriers:German DIN 4109 and French NF S 31-010 building codes impose pressure-drop and noise-testing requirements that filter out non-specialist importers. Compliance infrastructure demands capital investment many entrants cannot sustain.
- Stainless-Steel Substitution:Budget specification channels are adopting 304-grade stainless mixer bodies for corrosion resistance in hard-water environments. Brass retains premium positioning but loses volume in economy tiers.
Strategic Opportunities
- Portuguese Hospitality Expansion:Lisbon and Porto hotel development pipelines remain underpenetrated by specification-grade suppliers. Local distribution partnerships can capture volume before incumbent channels consolidate.
- Embodied-Carbon Reporting Alignment:EU Green Deal rules on Scope 3 emissions disclosure are creating first-mover advantage for manufacturers with kiln and foundry energy audits. Ceramic and metal component sourcing decisions will reconfigure around verified carbon footprints.
- Digital Specification Platforms:Building information modeling (BIM) object libraries are displacing traditional catalog-based contractor outreach. Fixture manufacturers embedding parametric product data can intercept architect-led procurement earlier in design cycles.
Industry Challenges
- CE Marking Timeline Compression:Notified body backlogs for pressure-testing and material certification are extending product launch cycles. Manufacturers face revenue recognition delays while awaiting conformity assessment completion.
- Cross-Border Logistics Reconfiguration:Post-Brexit customs friction and Red Sea shipping disruptions are forcing inventory positioning changes. UK and Irish market service levels require duplicate warehousing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bath Fitting Market |
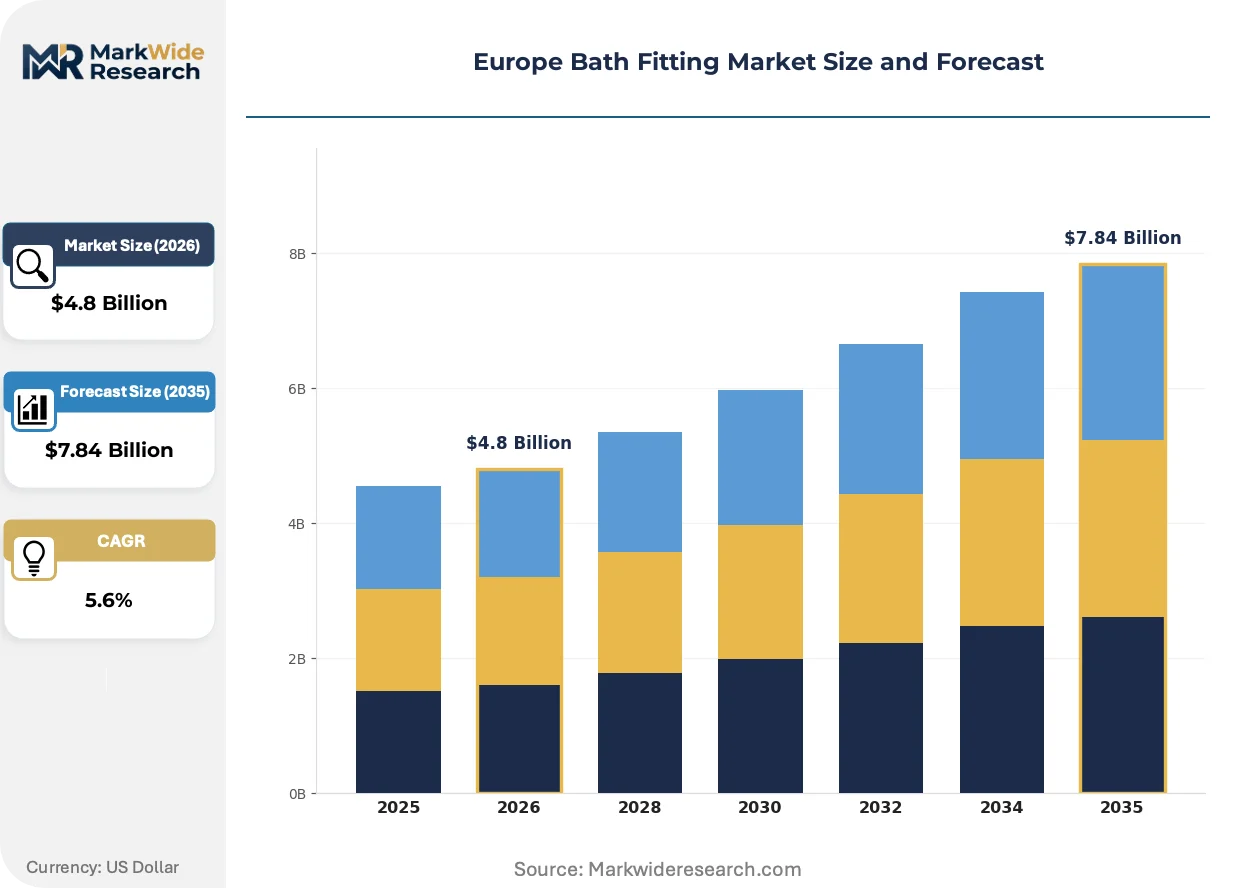
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Showers, Faucets, Bathtubs, Sinks Material: Stainless Steel, Brass, Plastic, Ceramic Design Style: Modern, Traditional, Minimalist, Vintage End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Grohe, Steinberg, Kohler, Jaguar, Delta Faucets, ROCA, TOTO, Villeroy & Boch, Hansgrohe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bath Fitting Market Shifts & Advancements
Digital water management systems are penetrating specification channels as hospitality operators seek utility cost transparency. Sensor-integrated fixtures now compete with mechanical mixers on total cost of ownership rather than upfront capital outlay alone.
Thermostatic cartridge technology is expanding into mid-market hospitality specifications. These precision temperature-control devices eliminate scald risk while reducing water waste during temperature adjustment. Spanish and Portuguese boutique hotel chains are specifying thermostatic showers at scale previously limited to Northern European premium residential. The technology is expanding into specification tiers where mechanical mixing once dominated, compressing price premiums for basic brass-bodied alternatives.
REACH enforcement on nickel release rates is tightening surface-finishing requirements for chrome-plated brass. ECHA's 2023 restriction proposal on nickel in prolonged skin contact applications is forcing PVD coating adoption for high-touch fixtures. German sanitaryware specialists are accelerating physical vapor deposition line investments. The regulation is reshaping competitive positioning among foundries with captive plating versus those reliant on third-party finishing.
Architects are consolidating specification authority through centralized procurement platforms. Boutique hotel developers now mandate pre-approved manufacturer lists that bypass traditional distributor relationships. Direct manufacturer-to-developer contracting is displacing wholesale channel intermediaries in Southern European hospitality clusters. This concentration is most visible in Milan and Barcelona, where design-build firms bundle fixture selection with interior architecture services.
Europe Bath Fitting Market Segmentation
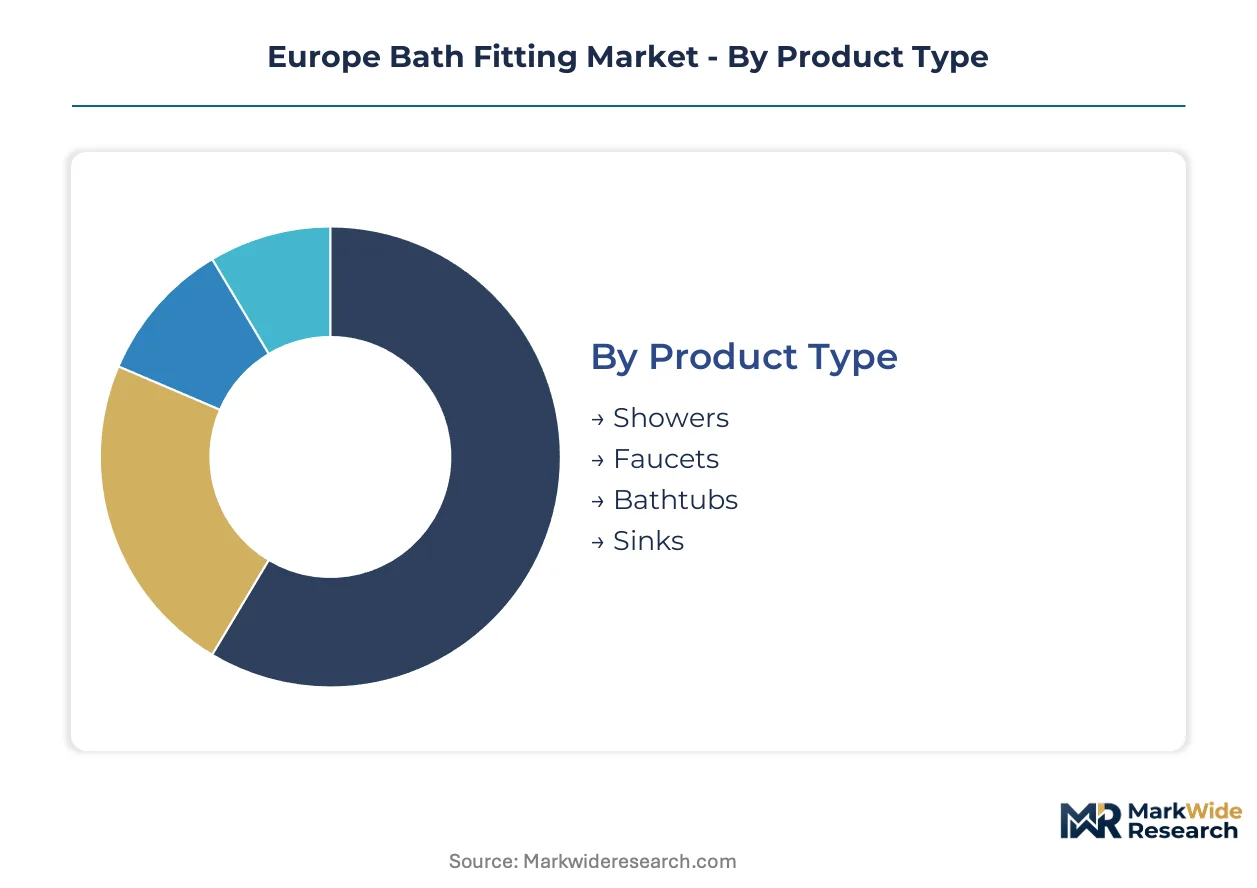
Segmentation in the Europe Bath Fitting Market reveals how regulatory pressure and end-use specialization fragment procurement patterns. Specification-grade requirements diverge sharply between heritage renovation stock and new-build hospitality, forcing manufacturers to maintain parallel product architectures.
Product Type:
Customization intensity varies from standardized mass-market mixers to architect-specified shower systems with embedded digital controls.
- Showers:Thermostatic cartridge technology dominates specification tiers, eliminating scald risk while reducing water waste during temperature adjustment. Spanish and Portuguese boutique hotel chains now specify these at scale previously limited to Northern European premium residential, compressing price premiums for basic alternatives.
- Faucets:Brass-bodied mixer valves retain margin pools in specification channels despite stainless-steel encroachment in budget tiers. REACH-driven alloy reformulation is forcing foundries to re-engineer casting geometries for Ecodesign compliance.
- Bathtubs:Ceramic and acrylic variants serve distinct installation contexts, with freestanding designs commanding premium positioning in Milan and Barcelona hospitality clusters.
- Sinks:Vessel and undermount configurations split along residential-commercial lines, with countertop-integrated basins gaining traction in Lisbon hotel renovations.
Most installed capacity flows through Faucets. Expansion is steepest in Showers.
Material:
Cost tier stratification separates premium metal alloys from commodity substitutes, with compliance costs reshaping competitive boundaries.
- Brass:Cast billets with chrome or PVD surface finishing resist chloride corrosion in hard-water environments across Germany and France. ECHA scrutiny of nickel and lead content is compelling foundries to develop low-lead casting grades that unlock specification access.
- Stainless Steel:304-grade mixer bodies capture budget specification channels for corrosion resistance, displacing brass volume in economy tiers while premium positioning remains metal-dependent.
- Plastic:Polymer composites serve price-sensitive replacement markets and temporary installations where acoustic certification is not required.
- Ceramic:Kiln-fired sanitaryware anchors vessel sinks and bathtubs, with embodied-carbon reporting rules under the EU Green Deal reconfiguring sourcing decisions for fired components.
Brass commands the specification premium tier. Stainless Steel is climbing the fastest in volume terms.
Design Style:
Application context determines styling preference, with hospitality procurement consolidating around architect-led aesthetic programs.
- Modern:Clean-line mixer bodies and concealed thermostatic controls dominate new-build hospitality specifications across Iberian and Italian clusters, aligning with boutique hotel branding requirements.
- Minimalist:Reduced visual mass and wall-mounted configurations capture specification share in Milan and Barcelona design-build projects where spatial efficiency intersects with premium positioning.
- Traditional:Cross-handle mixers and exposed valve architectures sustain replacement demand across heritage residential stock in France and the UK, where building conservation requirements limit modernization.
- Vintage:Reproduction styling serves boutique hospitality differentiation in Lisbon and Porto, where property developers leverage local architectural identity as a competitive marker.
Traditional styling retains the largest installed base. Minimalist is gaining share fastest in new-build specifications.
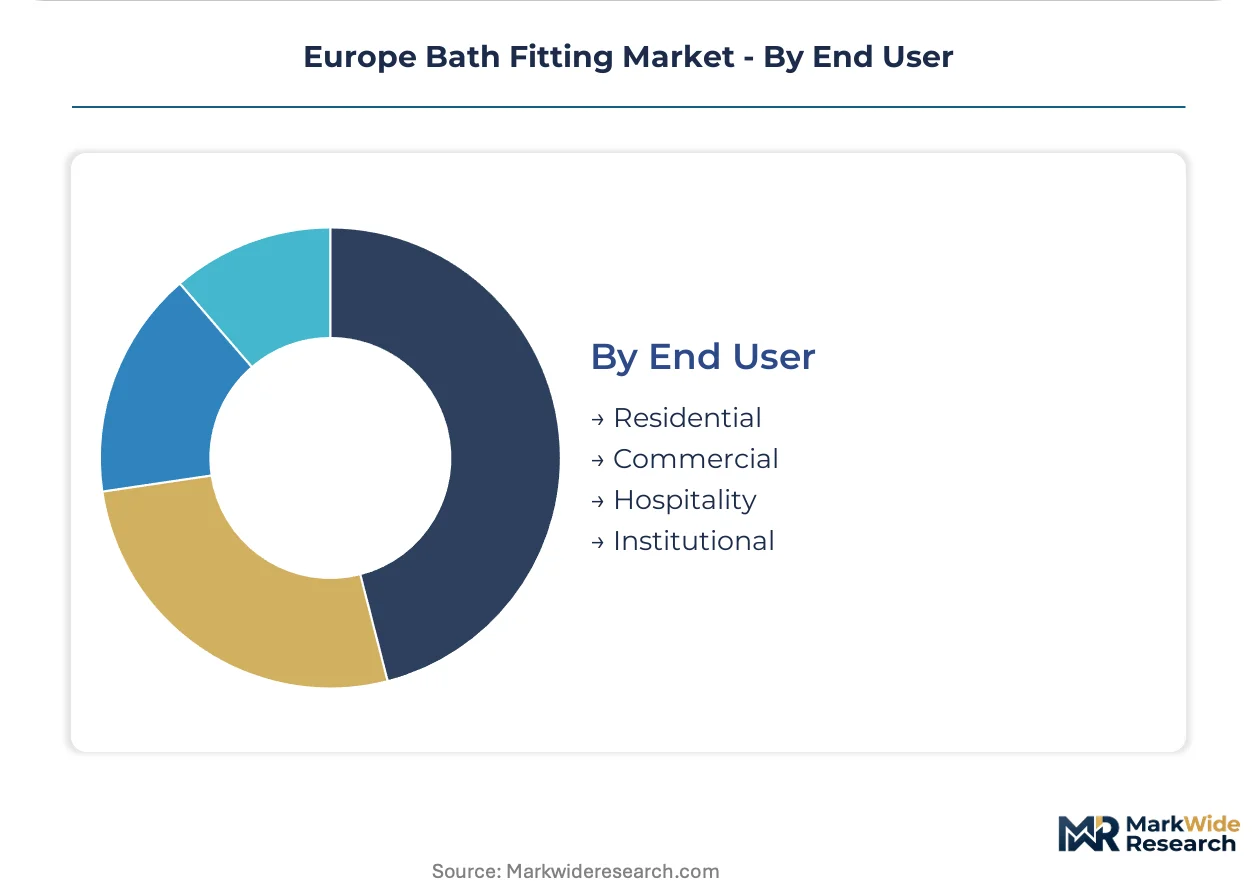
End User:
Customer type dictates certification burden and channel structure, with institutional procurement imposing the most stringent performance thresholds.
- Hospitality:Boutique hotel construction in Lisbon, Barcelona, and Milan accelerates fixture replacement schedules, with water-efficient mixer valves now dominating new-build specifications. Pre-approved manufacturer lists are displacing traditional distributor relationships.
- Residential:Single-family housing starts in Northern markets lag Southern European hospitality activity, with replacement cycles driven by renovation rather than new construction.
- Commercial:Office and retail fit-outs prioritize total cost of ownership calculations, where sensor-integrated fixtures compete with mechanical mixers on utility transparency.
- Institutional:Healthcare and education facilities impose acoustic and pressure-testing requirements that filter out non-specialist suppliers, with German DIN 4109 and French NF S 31-010 codes serving as entry barriers.
Residential channels absorb the highest unit volumes. Hospitality represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European bath fitting manufacturing, with specification-grade procurement clustering around German foundries and French distribution hubs. Southern European hospitality renovation cycles now outpace Northern residential construction, redirecting supply chain investment toward Iberian logistics nodes.
Germany
Acoustic certification requirements under DIN 4109 filter out non-specialist importers, concentrating specification-grade procurement among domestic foundries with captive testing infrastructure. ECHA scrutiny of nickel release rates forces PVD coating line investments across the Ruhr Valley. Cologne and Düsseldorf serve as distribution command centers for contract channels serving Benelux and Scandinavian markets.
France
Heritage residential stock in Paris and Lyon sustains replacement demand for traditional-styled fixtures, while NF S 31-010 building codes layer pressure-testing requirements atop EU baseline regulations. REACH-driven alloy reformulation compels foundries serving French channels to develop low-lead casting grades. The Île-de-France region concentrates architect-led specification authority for hospitality projects.
Spain
Barcelona and Madrid hospitality clusters drive thermostatic shower specifications at scale previously limited to Northern European premium segments. Boutique hotel developers now mandate pre-approved manufacturer lists that bypass traditional wholesale channels. Spanish building codes transposing EU Ecodesign Directive requirements compress flow-rate tolerances ahead of the next compliance deadline.
Italy
Milan design-build firms bundle fixture selection with interior architecture services, consolidating procurement authority among architect-led platforms. Ceramic sanitaryware production in the Veneto region faces embodied-carbon reporting pressure under EU Green Deal rules. Northern Italian foundries supply brass castings to specification channels across Alpine transit corridors.
Portugal
Lisbon and Porto hotel development pipelines remain underpenetrated by specification-grade suppliers, creating first-mover opportunities for local distribution partnerships. Portuguese hospitality operators prioritize water-efficient mixer valves aligned with EU Energy Label framework requirements. The Tagus Valley logistics corridor offers inventory positioning advantages for Southern European market service.
Europe Bath Fitting Market Competitive Landscape
Capacity expansion dominates the current landscape as foundries re-engineer casting geometries for Ecodesign compliance. The vendor base stratifies across three tiers: German specialists with captive plating infrastructure, Southern European ceramic-integrated groups, and Asian-origin volume players serving budget replacement channels. Two archetypes define competitive positioning: vertically integrated foundry-to-finish operators and design-forward brands architect-specified for hospitality. M&A activity concentrates on plating asset acquisition, while strategic partnerships with BIM platform providers reshape early-cycle specification access.
Among German-based fabricators, Grohe and Hansgrohe exemplify the specification-grade archetype with Ruhr Valley manufacturing footprints. Villeroy & Boch anchors the ceramic-integrated tier through its captive kiln operations. These three entities occupy positions where regulatory compliance infrastructure and design authority intersect, representing the competitive standard against which mid-tier foundries measure plating line investments and alloy reformulation timelines.
| Leading Market Players |
|---|
| Grohe |
| Steinberg |
| Kohler |
| Jaguar |
| Delta Faucets |
| ROCA |
| TOTO |
| Villeroy & Boch |
| Hansgrohe |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between DIN 4109-compliant German foundries and uncertified import channels splits pricing power along acoustic compliance lines, with compliant castings commanding 40-60% premia that reflect captive testing infrastructure rather than material costs alone. This bifurcation feeds back into supply chain configuration: specification-grade procurement clusters around Ruhr Valley manufacturers with in-house pressure-testing labs, while budget channels source from distributors without certification burden.
Pricing Analysis
Input-cost pass-through from copper and zinc concentrate markets runs unevenly across manufacturer tiers, with mid-tier foundries absorbing brass billet spikes while integrated operators leverage backward control over casting feedstocks. Three-tier pricing structure across premium specification, standard certified, and economy import levels separates channels by CE marking depth and acoustic testing documentation. Pricing pressure stems from stainless-steel substitution in hard-water replacement markets, compressing brass volume in economy tiers. Residential renovators in France and the UK exhibit highest price sensitivity, while German contract channels for institutional builds prioritize performance documentation over unit cost.
Supply Chain Analysis
Regional distribution centers in Cologne, Düsseldorf, and Milan anchor hub-and-spoke patterns serving specification-grade channels across Benelux, France, and Alpine corridors. Manufacturing concentrates in Germany, Italy, and Spain, with German foundries supplying brass castings and Italian kilns firing ceramic sanitaryware. Raw material dependencies rest on Chilean copper concentrate, Peruvian zinc, and Ukrainian nickel for PVD coating feedstocks. Single-source vulnerability in nickel supply threatens PVD line operations as ECHA restrictions accelerate coating transitions. Distribution runs through architect-led procurement platforms displacing traditional wholesale intermediaries in Southern European hospitality clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Bath Fitting Market compounds steadily as regulatory ratchets under EU Ecodesign and REACH force recurring replacement cycles and compliance-driven upgrades across installed base.
For Market Incumbents: Anticipate stainless-steel encroachment by hardening specification-channel relationships through BIM object library integration and captive PVD plating investments that lock out import competitors. Deepen backward integration into low-lead brass billet supply as ECHA scrutiny tightens, securing alloy reformulation timelines ahead of compliance deadlines. Prioritize acoustic certification maintenance as DIN 4109 and NF S 31-010 requirements filter non-specialist entrants from German and French institutional procurement. For New Entrants and Emerging Players: Launch via local distribution partnerships in Lisbon and Porto hospitality corridors where pre-approved manufacturer lists remain underpenetrated by specification-grade suppliers. Target Portuguese boutique hotel developers with water-efficient mixer valve portfolios aligned to EU Energy Label framework requirements. Establish digital specification presence through parametric BIM object libraries that intercept architect-led procurement before distributor engagement. For Investors and Strategic Acquirers: Consolidation pressure builds where plating asset scarcity intersects REACH-driven surface-finishing mandates, favoring acquisition of German foundries with captive PVD infrastructure over asset-light brand operators. Five-to-ten year viability hinges on embodied-carbon audit readiness under EU Green Deal Scope 3 disclosure rules. Watch ECHA nickel restriction enforcement timelines as inflection signal for coating technology transition capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| PVD Coating Line Investment | Captive physical vapor deposition capacity secures REACH-compliant nickel-release performance for German specification channels. |
| Low-Lead Alloy Development | ECHA-compliant brass billet reformulation unlocks procurement access in France and Germany under tightening lead content scrutiny. |
| BIM Object Library Integration | Parametric digital product data intercepts architect specification authority before traditional distributor engagement in Milan and Barcelona. |
| Portuguese Distribution Partnership | Local logistics positioning captures Lisbon and Porto hospitality volume before incumbent channels consolidate Southern European access. |
| Embodied-Carbon Audit Program | Kiln and foundry energy verification aligns ceramic and metal component sourcing with EU Green Deal Scope 3 disclosure mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with foundry operations directors, hospitality procurement managers, architect specification leads, and ceramic sanitaryware plant engineers alongside secondary validation. Trade data from Eurostat customs records, ECHA restriction proposal documentation, EU Energy Label framework regulatory texts, and national building code transpositions in Germany, France, Spain, Italy, and Portugal anchored supply-side modeling. Bottom-up channel volume estimates triangulated against top-down construction activity indices across residential and hospitality end-use segments.
Segment-weighting approaches distributed value and volume across product type, material grade, design style, and end-user categories, with hospitality renovation cycles and residential replacement demand modeled separately for each national market. CAGRs derived from fitted growth curves applied to base-year estimates, calibrated against brass foundry capacity utilization, ceramic kiln firing rates, and specification-grade shipment patterns. Forecast inputs incorporated EU Ecodesign Directive compliance timelines, REACH enforcement trajectories, and embodied-carbon reporting phase-in schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material price volatility, notified body certification backlogs, or Red Sea logistics disruptions extending lead times. Outputs reflect documented assumptions on regulatory implementation pacing and construction activity trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
US Faucet Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
Artificial Stone Bathtubs Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
India Steam Rooms Market