
 United States Running Gear Market | 2026-2036
United States Running Gear Market Size, Share, and Industry Trends Forecast 2026-2036
United States Running Gear Market Intelligence
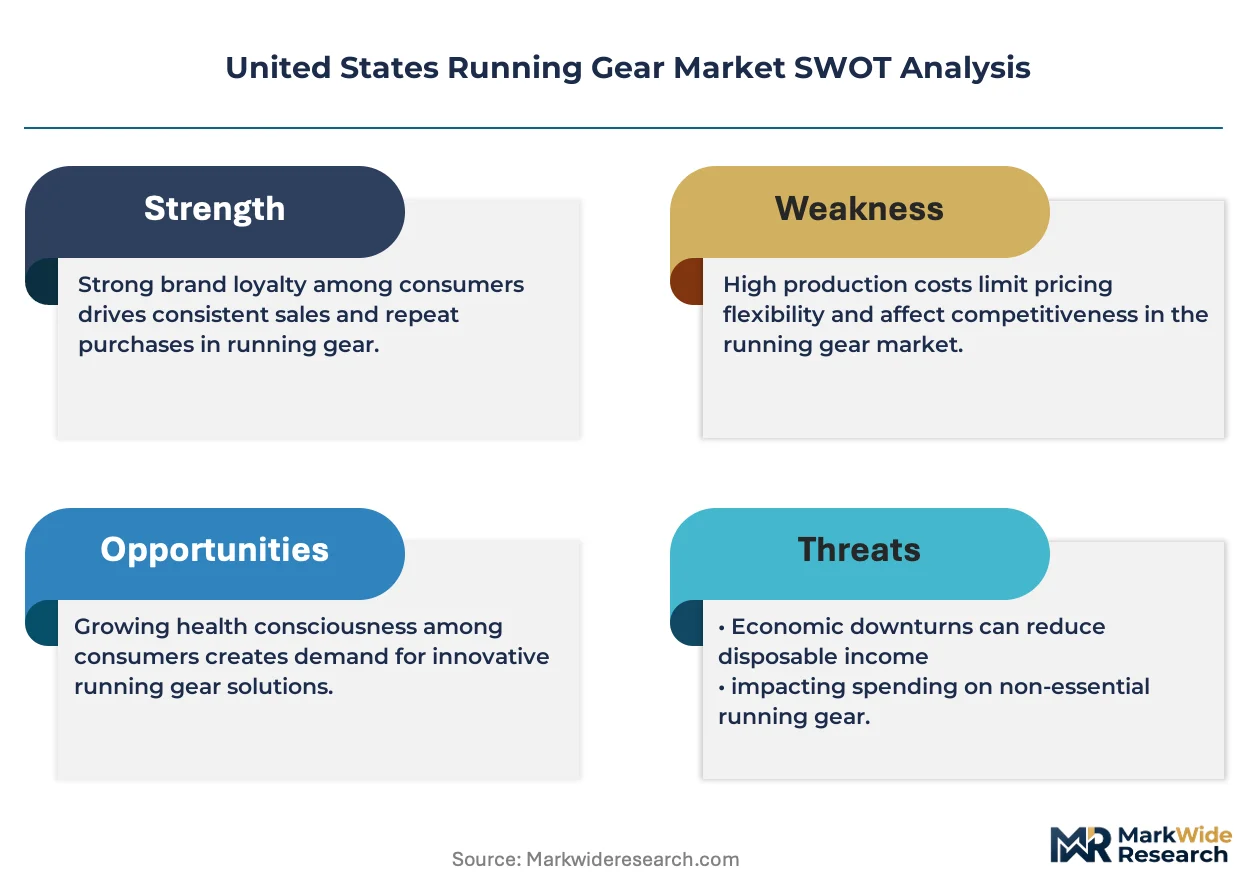
Aftermarket service revenue from shoe refurbishment and resale authentication is rewriting margin capture in the United States running gear sector. Nike leverages its proprietary foam compounds and direct-to-consumer app ecosystem to sustain premium pricing power. Brooks Sports anchors its competitive position through specialty running shop partnerships and gait-analysis fitting protocols. ASICS differentiates via its Institute of Sports Science and heritage technical credibility among marathon demographics.
United States running gear encompasses engineered footwear, performance textiles, wearable electronics, and auxiliary equipment designed to reduce impact stress, regulate thermodynamics, and quantify biomechanical output during locomotion. Products integrate ethylene-vinyl acetate midsole foams, engineered mesh uppers, and GPS-enabled watch sensors to serve both recreational joggers and competitive distance athletes. Shoes and apparel together command the dominant revenue share, though accessories and watches represent the fastest-expanding margin pool as biometric tracking penetrates amateur training regimens. The distribution channel structure tilts toward online platforms for replenishment purchases while specialty stores retain critical influence for initial fit-intensive acquisitions.
The Federal Trade Commission enforces Green Guides that mandate substantiation of environmental marketing claims on recycled-content footwear, reshaping product labeling and material sourcing disclosures. ASTM International maintains performance testing standards for athletic shoe durability and slip resistance that govern wholesale and retail acceptance. The Consumer Product Safety Commission monitors phthalate and lead content restrictions in youth-targeted running accessories. Stakeholders must track evolving state-level extended producer responsibility legislation in California and Oregon that could impose end-of-life collection obligations on running shoe manufacturers.
Market Dynamics
The Federal Trade Commission's Green Guides enforcement is forcing running gear brands to substantiate recycled-content claims, reshaping material sourcing disclosures and supplier qualification protocols across domestic manufacturing networks.
Growth Catalysts
- Trail Running Participation:Recreational athlete enrollment in trail disciplines is expanding across the Pacific Northwest and Rocky Mountain states, driving demand for lug-soled outsoles and protective rock plates.
- FTC Green Guides Compliance:Mandatory substantiation of environmental marketing claims on recycled polyester footwear is accelerating transparency investments and certified material adoption.
- Biometric Tracking Integration:GPS-enabled watch sensors and foot-pod cadence monitors are penetrating amateur training regimens, expanding the accessories margin pool.
Market Restraints
- Petrochemical Input Volatility:Ethylene-vinyl acetate foam and engineered mesh polymers face price instability tied to crude oil derivatives, compressing midsole margin predictability.
- Specialty Retail Concentration:Gait-analysis fitting protocols depend on independent running shops concentrated in California and Colorado urban corridors, creating geographic access inequities.
- Technical Durability Ceilings:ASTM International testing standards for outsole abrasion resistance create performance ceilings that limit product differentiation claims.
Strategic Opportunities
- Aftermarket Service Expansion:Shoe refurbishment and resale authentication protocols represent unclaimed margin pools in circular economy service models.
- State-Level EPR Legislation:Extended producer responsibility frameworks advancing in California and Oregon may create first-mover advantages for end-of-life collection infrastructure.
- Wearable-Convergence:Integration of force-plate insoles with smartphone biomechanics apps is digitizing gait coaching for remote athletes.
Industry Challenges
- Specialized Fitting Talent Scarcity:Gait-analysis certification programs produce insufficient certified fitters to staff specialty retail expansion.
- Phthalate Compliance Testing:Consumer Product Safety Commission monitoring of youth-targeted accessories requires extended laboratory validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Running Gear Market |
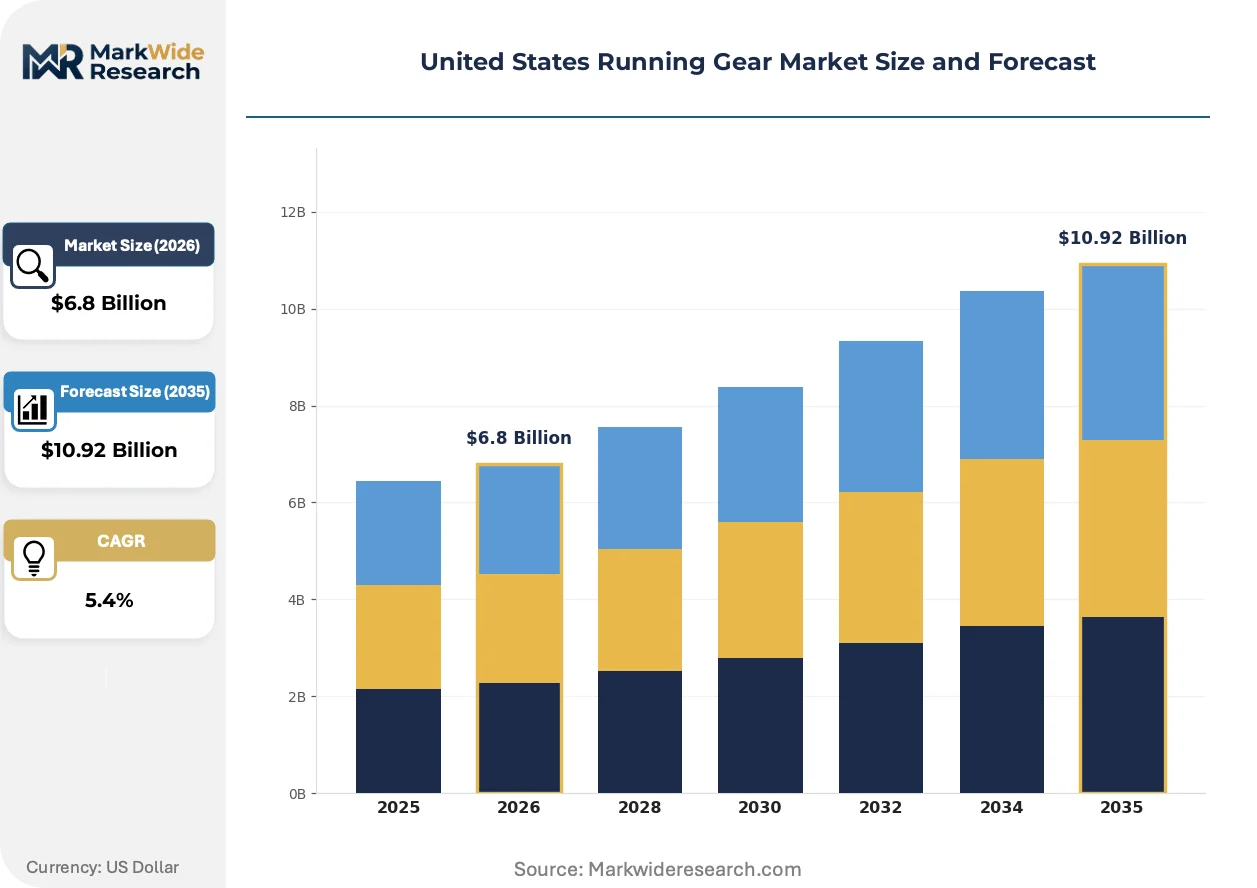
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shoes, Apparel, Accessories, Watches End User: Men, Women, Kids, Professionals Distribution Channel: Online, Specialty Stores, Supermarkets, Department Stores Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Nike, Adidas, New Balance, Brooks Sports, ASICS, Under Armour, Puma, Hoka One One, Saucony, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Running Gear Market Strategic Shifts & Innovations
Three intersecting forces are restructuring competitive positioning in United States running gear: embedded sensor proliferation, environmental claim substantiation mandates, and direct-to-consumer channel maturation.
Force-sensing insole technology is digitizing ground-contact metrics for amateur runners previously restricted to laboratory motion-capture facilities. Specialty clinics and physical therapy practices are adopting these systems for remote patient monitoring. The technology is digitizing gait assessment economics by collapsing the cost per analysis from facility-based to consumer-owned hardware.
The Federal Trade Commission's Green Guides are mandating documentary evidence for recycled-content percentages on footwear labels. Brands must now maintain chain-of-custody documentation from polymer reclamation through finished goods assembly. California and Oregon state attorneys general are actively monitoring compliance, with misrepresentation carrying civil penalty exposure.
Replenishment purchasing behavior is consolidating onto brand-owned mobile applications with size-history memory and automated replacement timing. Specialty retail retains influence for initial fit-intensive acquisitions, but subsequent volume migrates to direct channels. This bifurcation is most visible in Colorado's Front Range and California's Bay Area fitness corridors.
United States Running Gear Market Segmentation
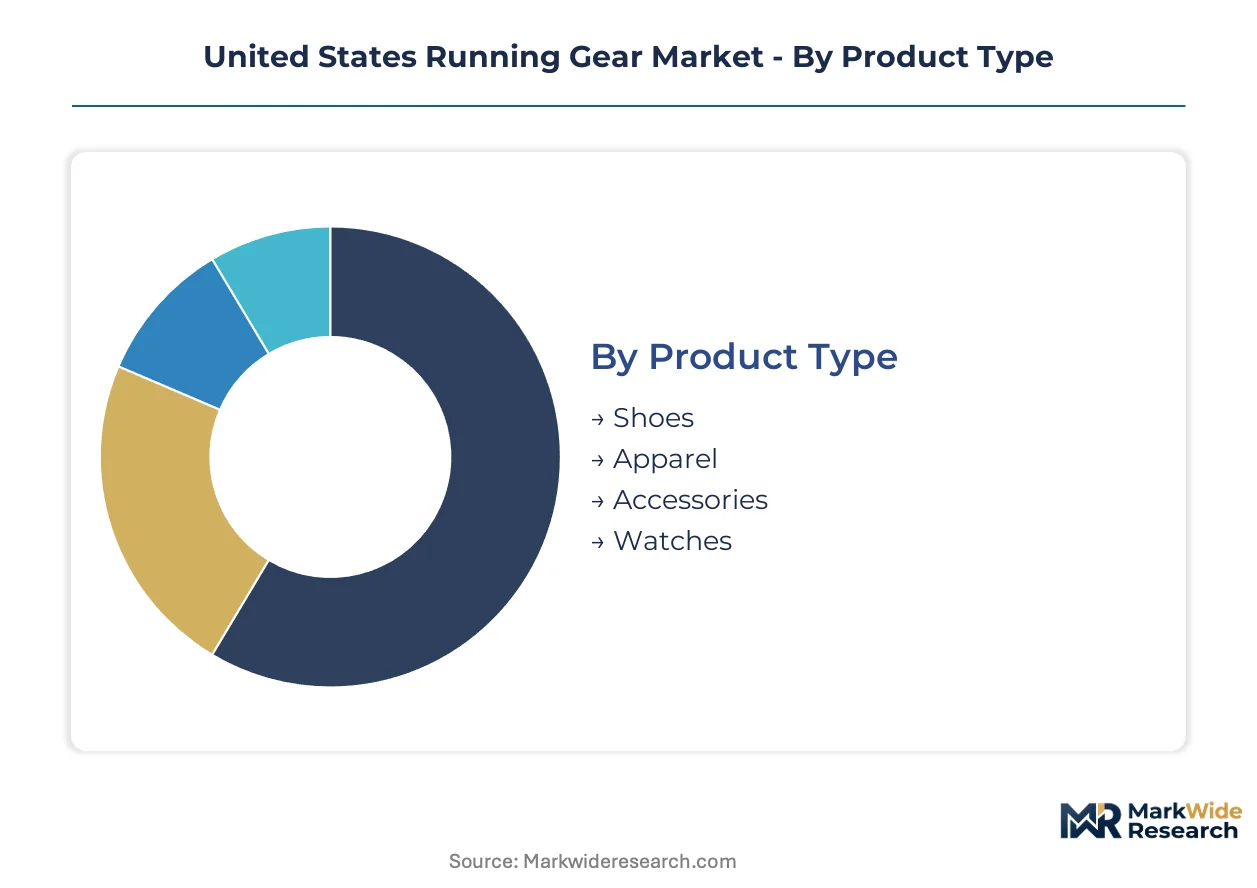
Segmentation in United States running gear reveals how biomechanical requirements, retail channel economics, and price elasticity create distinct profit pools. Product architecture and distribution access together determine which consumer cohorts brands can serve profitably.
Product Type:
Engineered footwear and performance textiles span recreational joggers to competitive marathoners, with sensor-integrated accessories now penetrating amateur training regimens.
- Shoes:Ethylene-vinyl acetate midsole foams and engineered mesh uppers dominate construction. Demand concentrates in California's urban fitness corridors and Colorado's outdoor recreation hubs, driven by gait-analysis fitting protocols at specialty retail.
- Apparel:Moisture-wicking synthetic blends and compression textiles regulate thermodynamics during exertion. Pacific Northwest trail running participation is expanding demand for weather-resistant outer layers with reinforced seam construction.
- Accessories:GPS-enabled foot-pod cadence monitors and hydration systems serve distance athletes. FTC Green Guides compliance is accelerating transparency investments in recycled-content production.
- Watches:Biometric tracking hardware with heart-rate variability and VO2 max estimation penetrates amateur regimens. These devices are expanding the accessories margin pool through subscription coaching integrations.
Established volume favors Shoes; emerging adoption favors Watches.
End User:
Demographic differentiation in United States running gear reflects distinct biomechanical profiles, training frequencies, and replacement cycle economics across gender and age cohorts.
- Men:Higher average purchase frequency in technical footwear with structured stability features. Rocky Mountain states show concentrated demand for lug-soled trail configurations.
- Women:Expanding share in performance apparel with engineered support integration. Specialty running shops in California's Bay Area report gait-analysis appointment growth in this segment.
- Kids:Youth-targeted accessories face Consumer Product Safety Commission phthalate and lead content monitoring. Extended laboratory validation timelines constrain new product introduction speed.
- Professionals:Elite athletes and coaches demand force-plate insoles and laboratory-grade biomechanics hardware. This cohort drives technology transfer from institutional research to consumer markets.
Volume concentration sits with Men; steepest expansion trajectory belongs to Women.
Distribution Channel:
Channel economics in United States running gear bifurcate between fit-intensive initial purchases and frictionless replenishment transactions.
- Online:Brand-owned mobile applications with size-history memory capture replenishment volume. Automated replacement timing algorithms reduce customer acquisition costs for repeat purchases.
- Specialty Stores:Independent running shops concentrated in California and Colorado urban corridors provide gait-analysis fitting protocols. Geographic access inequities persist outside these fitness clusters.
- Supermarkets:Mass-market entry-level footwear and basic apparel serve price-sensitive recreational joggers. Limited technical staff constrains fit precision.
- Department Stores:Mid-range fashion-athletic crossover products target occasional runners. Inventory breadth trades off against technical depth in specialty categories.
Specialty Stores anchor initial fit acquisition; Online channels capture replenishment economics.
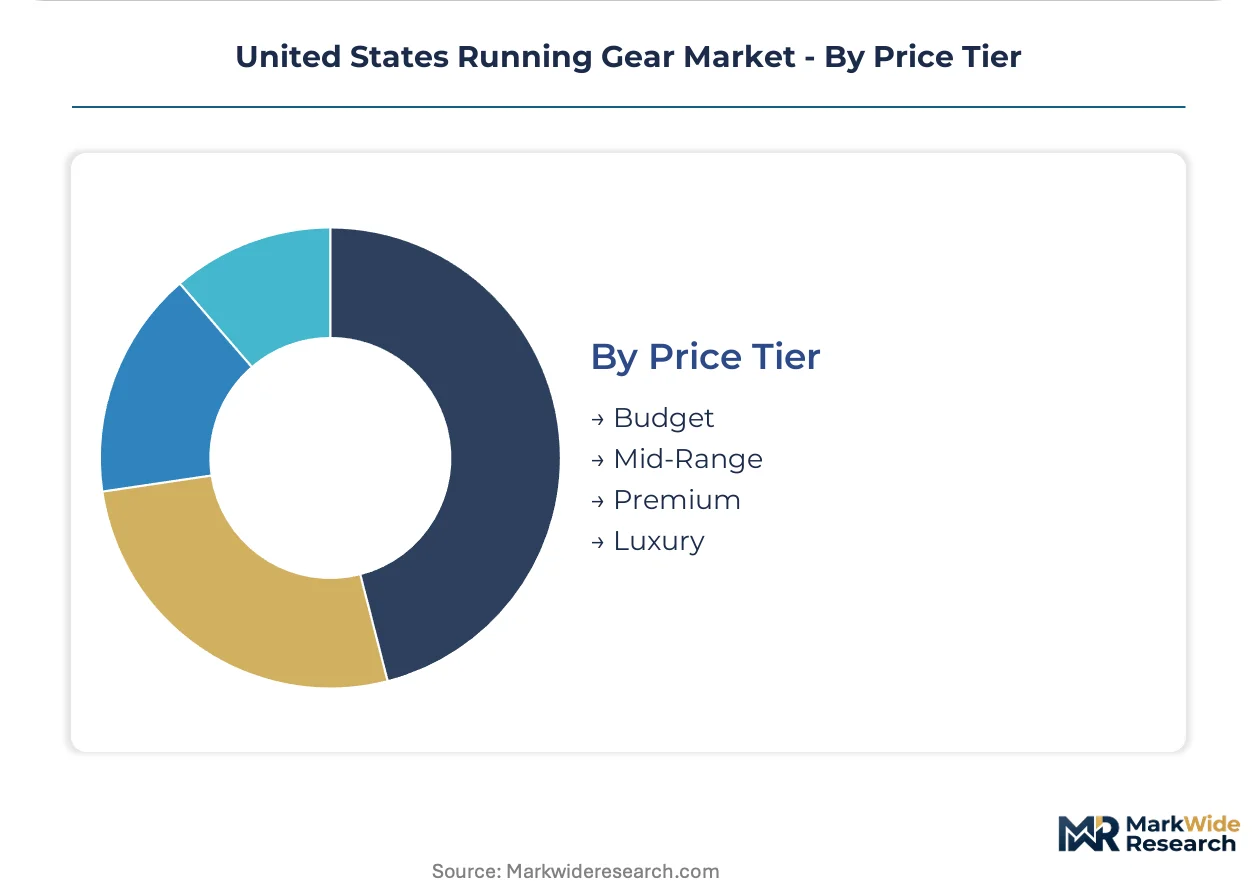
Price Tier:
Pricing architecture reflects material specification tiers, proprietary technology licensing, and certification-grade durability testing.
- Budget:Basic ethylene-vinyl acetate constructions and generic mesh uppers serve entry-level participation. Price volatility in petrochemical inputs compresses margin predictability.
- Mid-Range:Branded foam compounds and engineered knit uppers balance performance with accessibility. This tier absorbs the largest share of trail running participation growth.
- Premium:Proprietary midsole formulations and carbon-fiber plate integrations target competitive distance athletes. Direct-to-consumer app ecosystems sustain pricing power through loyalty lock-in.
- Luxury:Limited-edition collaborations and heritage craftsmanship positioning serve collector and fashion-adjacent demand. Aftermarket resale authentication protocols extend product lifecycle value.
Mid-Range commands unit volume; Premium captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns in United States running gear diverge sharply between coastal fitness corridors and interior trail-running territories, with urban athletes prioritizing biometric-integrated accessories while mountain-state participants drive demand for protective lug-soled configurations.
California
Bay Area and Los Angeles fitness corridors generate concentrated demand for gait-analysis fitting protocols at specialty retail. The California attorney general actively monitors FTC Green Guides compliance on recycled-content footwear claims. Los Angeles hosts the nation's densest cluster of independent running shops with certified fitter staffing.
Colorado
Front Range urban centers anchor specialty retail density for initial fit-intensive acquisitions. State-level extended producer responsibility legislation under legislative review may impose end-of-life collection obligations on manufacturers. Boulder and Denver metropolitan areas report the highest per-capita trail running participation rates nationally.
Pacific Northwest
Oregon and Washington states show expanding recreational athlete enrollment in trail disciplines requiring weather-resistant outer layers. Oregon's attorney general coordinates with California on environmental marketing claim enforcement. Portland and Seattle metropolitan areas concentrate demand for protective rock plate footwear configurations.
Rocky Mountain States
Utah, Idaho, and Montana demonstrate concentrated demand for lug-soled outsoles on technical terrain. Federal land management policies governing trail access influence regional participation patterns. Salt Lake City and Boise anchor specialty retail distribution for mountain-state athletes.
Texas
Dallas-Fort Worth and Houston metropolitan areas show expanding women's segment participation in performance apparel with engineered support. The state's business-friendly regulatory environment attracts distribution center investment from major brands. Austin's fitness culture supports independent running shop viability outside traditional coastal corridors.
United States Running Gear Market Key Industry Players
Capability concentration sits with heritage technical specialists; scale advantage sits with diversified sportswear conglomerates. The market structures around three tiers: proprietary foam compound innovators, specialty retail-anchored technical brands, and fashion-athletic crossover players. Dominant competitive moves include direct-to-consumer app ecosystem development and aftermarket service infrastructure construction.
Within the heritage technical tier, Nike and Brooks Sports exemplify divergent scale-capability positioning. Nike occupies the scale-driven end with proprietary material science and integrated digital ecosystems. Brooks Sports represents the specialty-retail anchored archetype with gait-analysis partnership protocols. ASICS sits within the technical credibility segment, transferring institutional sports science research into consumer-facing product architectures.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| New Balance |
| Brooks Sports |
| ASICS |
| Under Armour |
| Puma |
| Hoka One One |
| Saucony |
| Others |
Cost & Logistics Intelligence
Dongguan and Shenzhen manufacturing clusters anchor global ethylene-vinyl acetate foam production, with capacity utilization swings in these Guangdong hubs directly transmitting into midsole cost volatility for domestic brands. The petrochemical input exposure creates asymmetric pricing power where vertically integrated conglomerates absorb shocks better than specialty retail-dependent competitors.
Pricing Analysis
Long-term offtake contracts for engineered mesh polymers dominate procurement between major brands and Taiwanese textile suppliers, insulating premium tier players from spot market volatility. Price differentiation rests on proprietary foam compound certification tiers and gait-analysis service bundling. Cost compression in the budget segment intensifies as generic EVA suppliers from Vietnam expand capacity. Specialty running shops show least price sensitivity due to fitting protocol loyalty, while supermarket channels face acute margin pressure from private-label entrants.
Supply Chain Analysis
Upstream feedstock dependence on crude oil derivatives and recycled polyester reclamation streams creates dual sourcing complexity for midsole and upper construction. Manufacturing concentrates in Vietnam, China, and Indonesia for cut-and-sew assembly, with domestic finishing retained for speed-to-market. Single-source vulnerability persists in carbon-fiber plate fabrication for premium racing flats. Distribution runs through brand-owned direct-to-consumer applications for replenishment, with specialty retail handling fit-intensive initial purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States running gear sits in early-cycle expansion as biometric tracking penetration in amateur training regimens accelerates replacement cycles beyond traditional footwear wear-out timelines.
For Market Incumbents: Insulate proprietary foam compound advantages through backward integration into polymer reclamation streams, securing chain-of-custody documentation for FTC Green Guides compliance. Defend specialty retail partnerships against direct-to-consumer entrants by embedding gait-analysis certification into shop-in-shop formats. The emerging threat of force-sensing insole digitization demands R&D investment in smartphone-integrated biomechanics apps to retain coaching relationship ownership. For New Entrants and Emerging Players: Pursue aftermarket service white space in shoe refurbishment and resale authentication, where circular economy infrastructure remains underdeveloped. The Pacific Northwest trail running corridor offers the most penetrable geographic entry point, with demand for weather-resistant outer layers outpacing established brand localization. A go-to-market angle anchored in state-level extended producer responsibility pre-positioning creates regulatory goodwill in California and Oregon. For Investors and Strategic Acquirers: Long-term, this sits as a subscription-recurring play because biometric watch coaching integrations and automated replacement timing algorithms transform transactional footwear into ongoing revenue relationships. Acquisition targets should screen for direct-to-consumer app ecosystem maturity and certified fitter network density. The signal to watch is specialty retail consolidation velocity, as independent shop survival rates indicate brand pricing power sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer App Ecosystem | Nike's proprietary platform with size-history memory captures replenishment economics from specialty retail. |
| Aftermarket Service Infrastructure | Brooks Sports' refurbishment protocols extend product lifecycle value in circular economy positioning. |
| Biometric Integration Partnership | ASICS' force-plate insole development transfers institutional sports science into consumer coaching subscriptions. |
| State EPR Pre-Positioning | Early collection infrastructure investment in Oregon creates regulatory compliance advantage before mandate activation. |
| Certified Fitter Network Expansion | Specialty shop gait-analysis staffing scarcity makes trained talent acquisition a channel control lever. |
Research Approach
A standing panel of brand product development directors, specialty running shop owners, polymer procurement managers, and certified gait-analysis fitters provided ongoing calibration against secondary validation from SEC footwear segment filings, U.S. Customs import records for engineered textiles, and ASTM International testing standard updates. Bottom-up unit economics from retail channel partners triangulated against top-down consumer expenditure surveys from the Bureau of Economic Analysis.
Scenario-bracketing around trail participation growth rates and FTC enforcement intensity framed the projection horizon across product type, price tier, distribution channel, and regional fitness corridor segmentation dimensions. CAGRs derived from historical replacement cycle analysis adjusted for biometric tracking penetration effects and state-level extended producer responsibility implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil derivative pricing or consumer discretionary expenditure indices would shift the trajectory. Cross-checking against National Sporting Goods Association participation survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Gear Bicycle Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Go Kart Market
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Riding Gear Market
Sports Equipment
Diving Board Market
Sports Equipment
United States Archery Equipment Market
Sports Equipment
North America Sporting Goods Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Football Equipment Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Fishing Rods Market