
 Volleyball Equipment Market | 2026-2036
Volleyball Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Volleyball Equipment Market Outlook
Subscription-based net maintenance and digital court calibration services is repositioning how volleyball equipment vendors monetize long-term relationships with institutional buyers. Mikasa Corporation leverages its FIVB certification pipeline to sustain premium pricing in the competition ball segment. Mizuno Corporation anchors its North American presence through specialized footwear R&D facilities in California. Senoh Corporation competes on manufacturing scale for adjustable steel-aluminum hybrid systems shipped to school districts across Japan.
Volleyball equipment encompasses balls constructed from bonded leather or synthetic composite panels with butyl rubber bladders, nets woven from polyethylene or nylon with vinyl-coated steel cables, and protective gear incorporating EVA foam and thermoplastic polyurethane. The primary commercial purpose is to enable standardized competitive play while reducing injury incidence through engineered impact absorption. Footwear and protective gear command the deepest margin pools as material innovation differentiates premium tiers from budget alternatives. Balls and nets represent mature categories where brand certification from federations governs institutional procurement. The online retail channel is capturing share from sports shops as direct-to-consumer customization tools expand.
FIVB equipment standards, CE marking requirements for protective gear sold in Europe, and ASTM International specifications for indoor court surfaces collectively shape product compliance burdens and market access conditions. The US Consumer Product Safety Commission monitors youth protective gear for chemical content under CPSIA guidelines. Stakeholders must track evolving federation certification timelines and regional testing protocol harmonization to anticipate procurement cycle disruptions.
Market Dynamics
FIVB standardization of competition ball specifications is compressing procurement cycles for institutional buyers and forcing equipment vendors to recertify product lines against tightened tolerances.
Growth Catalysts
- Federal sports ministry investment:Brazil's beach volleyball infrastructure buildout ahead of major tournament cycles is pulling net systems and court surfaces through public procurement channels.
- School athletic program expansion:North American districts are adding competitive volleyball offerings, driving recurring replacement demand for balls and protective gear.
- CE marking harmonization:European protective gear manufacturers gain streamlined market access across EU member states, reducing testing redundancy for EVA foam and TPU-based products.
Market Restraints
- Butyl rubber price volatility:Ball bladder input costs fluctuate with petrochemical feedstock markets, squeezing margin on mid-tier synthetic composite products.
- Polyethylene supply concentration:Net weaving raw materials depend on Asian petrochemical clusters, exposing vendors to freight rate spikes and tariff uncertainty.
- ASTM surface specification delays:Indoor court flooring certification timelines lag behind installation demand, freezing project approvals in school districts.
Strategic Opportunities
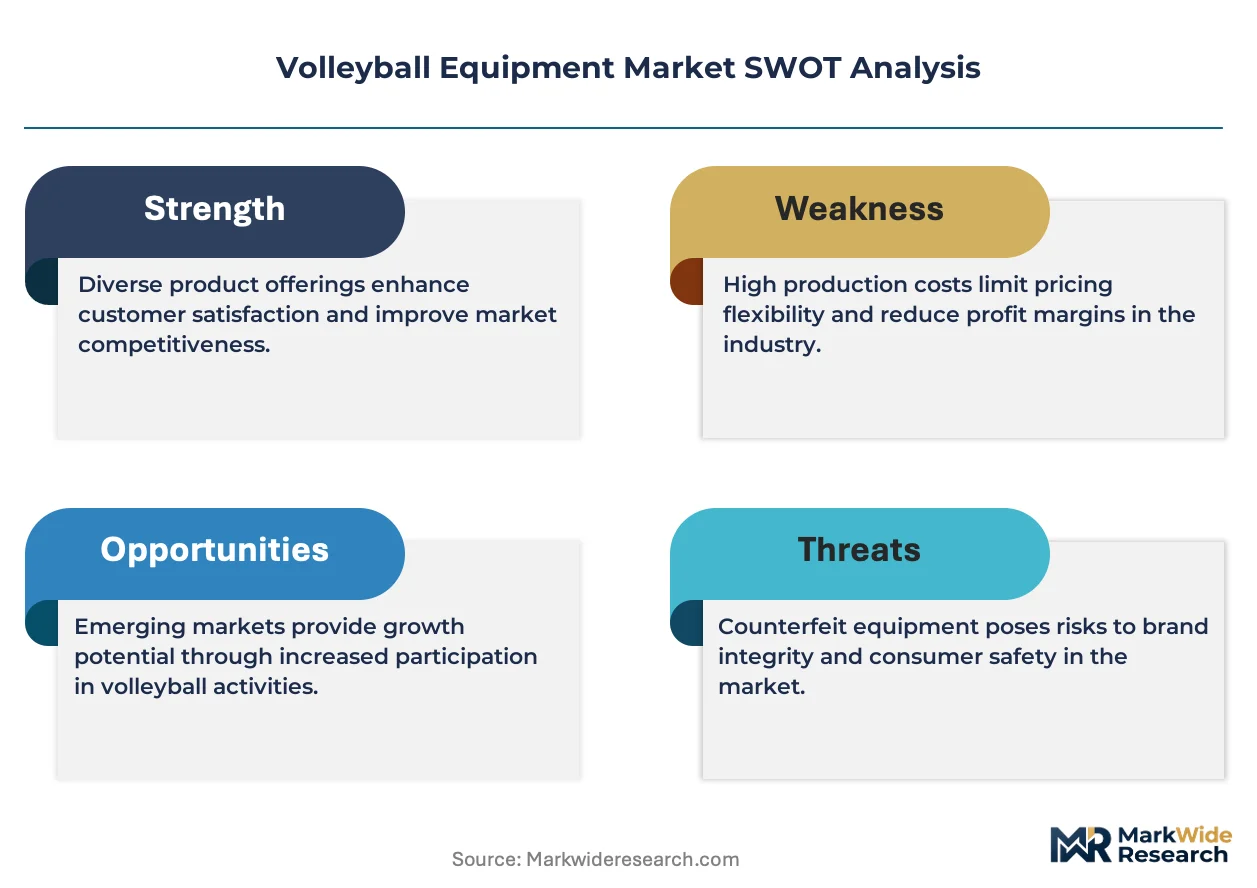
- Subscription-based maintenance services:Digital court calibration and net tension monitoring create recurring revenue streams from institutional buyers.
- Direct-to-consumer customization:Online retail channels bypass sports shop intermediaries, enabling personalized ball panel designs for club teams.
- Beach volleyball infrastructure mandates:Coastal municipalities in Brazil and Australia are codifying public court construction into urban planning frameworks.
Industry Challenges
- FIVB recertification backlog:Competition ball approval queues stretch six to nine months, delaying product launches and inventory positioning.
- EVA foam formulation expertise:Protective gear manufacturers face scarcity of polymer engineers capable of tuning impact absorption densities for youth segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volleyball Equipment Market |
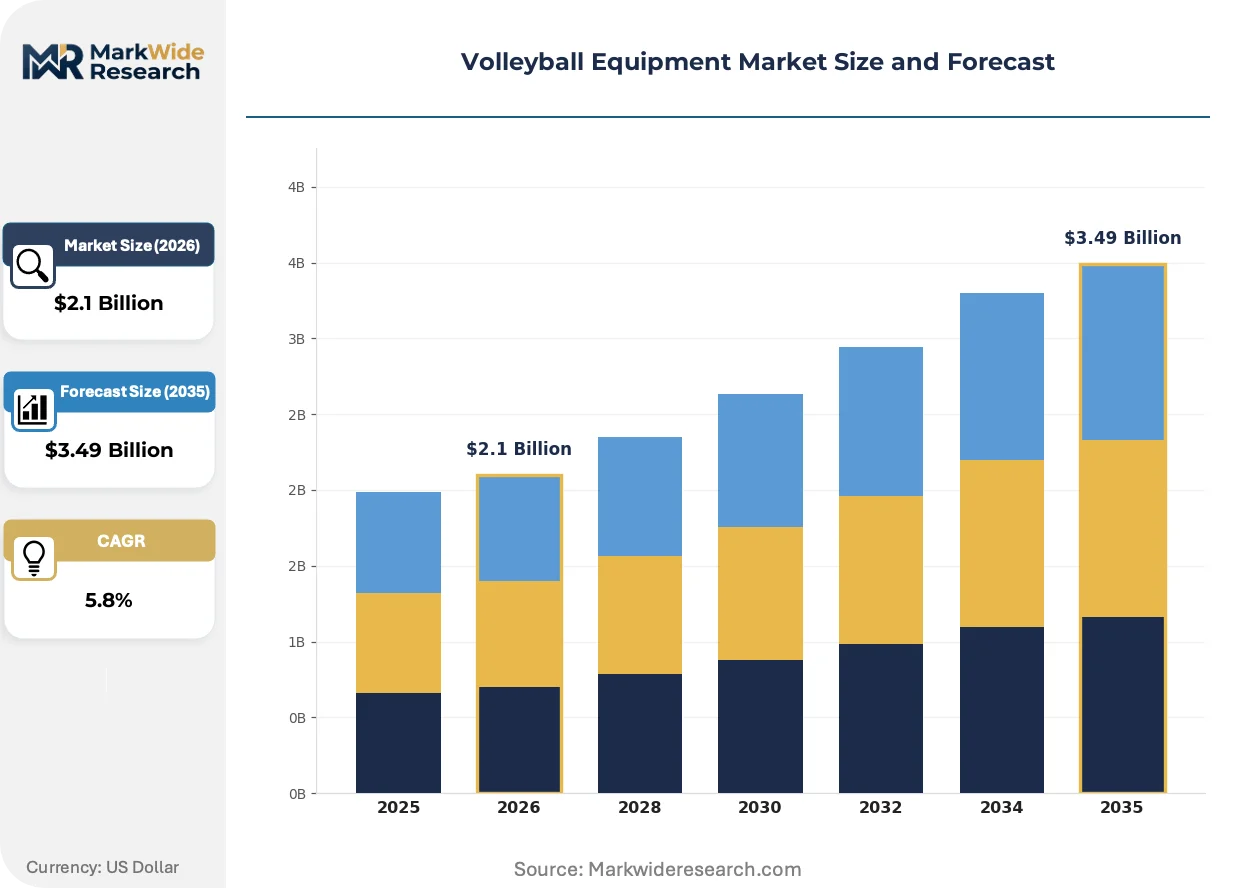
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balls, Nets, Footwear, Protective Gear End User: Professional Teams, Schools, Recreational Players, Clubs Distribution Channel: Online Retail, Sports Shops, Department Stores, Direct Sales Price Tier: Budget, Mid-Range, Premium, Institutional |
| Companies Covered | Spalding Sports Equipment, Senoh Corporation, Mikasa Corporation, Adidas AG, Mizuno Corporation, Molten Corporation, Tachikara Holdings, Ltd., ASICS America Corporation, Wilson Sporting Goods Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volleyball Equipment Market Strategic Shifts
Equipment vendors are embedding sensor technology into traditional product categories while federation certification requirements accelerate material substitution cycles.
Microchip-enabled volleyballs are converging with training analytics platforms to capture spin rate, impact force, and trajectory data. Collegiate programs in the United States are piloting these systems during preseason camps. The technology is converging with video replay infrastructure to compress coaching feedback loops and justify premium equipment pricing tiers.
REACH substance restrictions on phthalates and heavy metals are forcing European protective gear manufacturers to reformulate TPU coatings and EVA foam catalysts. Compliance testing costs have risen substantially for mid-sized suppliers without captive laboratories. The volleyball knee pad and ankle brace segments are absorbing the heaviest compliance burden, with several vendors relocating finishing operations to non-EU jurisdictions.
Institutional buyers are consolidating vendor relationships through multi-year equipment framework agreements. School districts and municipal recreation departments now specify total cost of ownership metrics rather than unit pricing. This pattern is most visible across California and Texas, where statewide cooperative purchasing vehicles aggregate demand and compress supplier margins in exchange for volume commitments.
Volleyball Equipment Market Segmentation
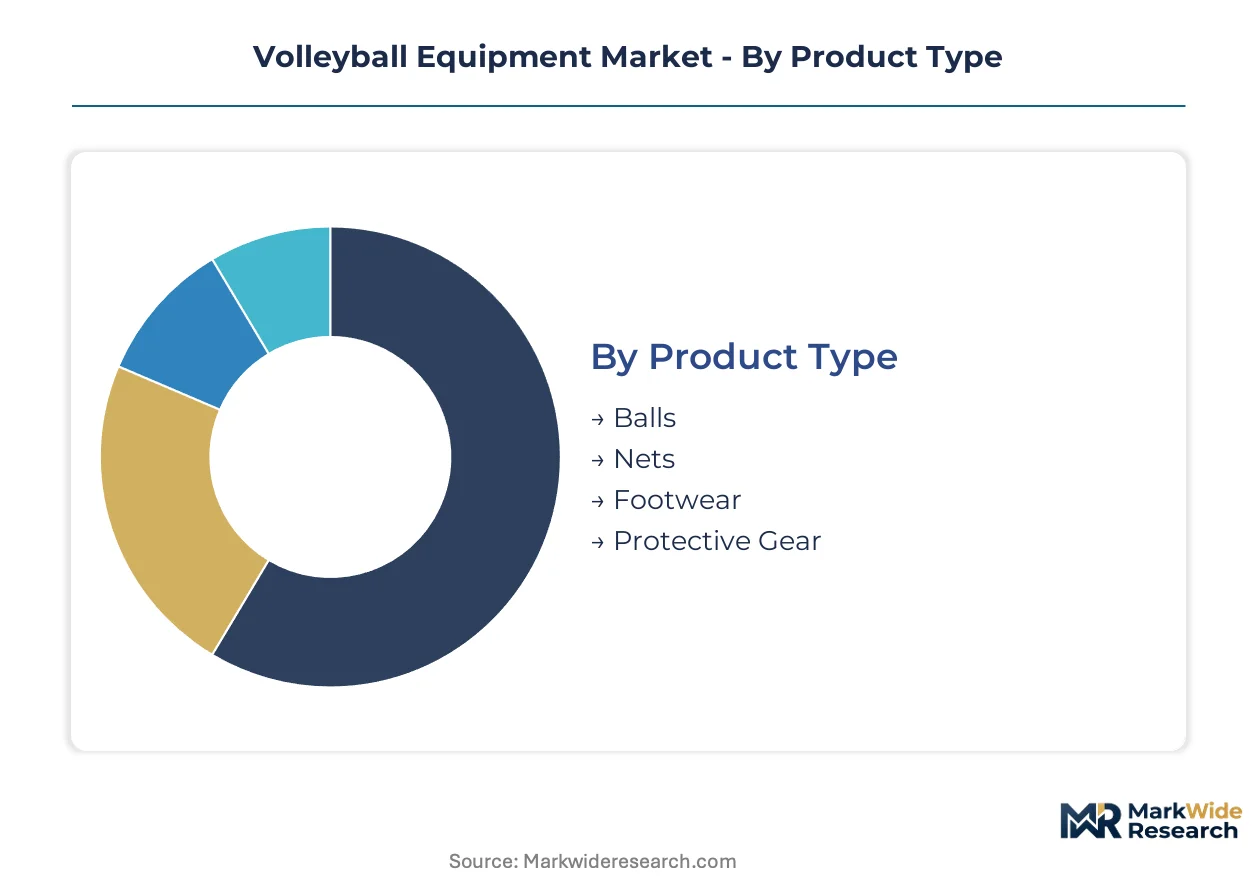
Volleyball equipment procurement cycles diverge sharply across user categories, with institutional buyers prioritizing durability metrics while recreational segments respond to customization and brand affiliation. Understanding these segment-specific purchase triggers enables vendors to align certification investments with revenue concentration.
Product Type:
Replacement frequency and wear patterns create distinct upgrade cycles across equipment categories, with high-contact items demanding shorter refresh intervals than fixed infrastructure.
- Balls:Competition-grade balls utilize bonded leather or synthetic composite panels with butyl rubber bladders to maintain air retention across temperature variations. School districts in Texas and California aggregate procurement through cooperative purchasing vehicles, compressing unit pricing in exchange for volume commitments.
- Footwear:Specialized volleyball shoes incorporate gel cushioning systems and gum rubber outsoles engineered for lateral court movement and abrupt directional changes. Mizuno Corporation's California R&D facility anchors North American product development, responding to collegiate program specifications for enhanced ankle stability.
- Nets:Polyethylene or nylon weaving with vinyl-coated steel cable tensioning systems defines institutional-grade net construction. Brazilian federal sports ministry infrastructure investments are pulling net systems through public procurement channels ahead of tournament cycles.
- Protective Gear:Knee pads and ankle braces integrate EVA foam and thermoplastic polyurethane for engineered impact absorption. REACH substance restrictions are forcing reformulation of TPU coatings and foam catalysts for European market access.
Volume placements concentrate in balls and nets; the faster expansion belongs to footwear as material innovation differentiates premium tiers.
End User:
Procurement authority and budget elasticity separate institutional buyers from individual purchasers, with framework agreements dominating high-volume segments.
- Schools:North American districts are expanding competitive volleyball offerings, driving recurring replacement demand through standardized specifications. Total cost of ownership metrics now govern vendor selection rather than unit pricing alone.
- Professional Teams:FIVB certification requirements compress procurement cycles as tightened tolerances force product line recertification. Competition ball approval queues stretching six to nine months delay inventory positioning for sanctioned events.
- Clubs:Collegiate programs in the United States pilot microchip-enabled volleyballs converging with training analytics platforms. Direct-to-consumer customization tools enable personalized ball panel designs bypassing sports shop intermediaries.
- Recreational Players:Online retail channels capture share from traditional sports shops as price transparency and review aggregation influence purchase decisions. Budget-tier synthetic composite balls dominate this segment.
Institutional contracts anchor revenue stability in schools; clubs are gaining share fastest through analytics integration and customization demand.
Distribution Channel:
Channel economics reflect inventory carrying costs and service intensity requirements, with digital platforms displacing intermediaries in low-touch categories.
- Online Retail:Direct-to-consumer platforms bypass sports shop margins while enabling mass customization for club team orders. California and Texas statewide cooperative purchasing vehicles aggregate institutional demand through digital procurement portals.
- Sports Shops:Specialized retailers retain relevance for footwear fitting services and protective gear try-on requirements. Staff expertise in court surface recommendations sustains foot traffic despite price competition from online channels.
- Direct Sales:Multi-year equipment framework agreements with school districts and municipal recreation departments specify performance metrics and maintenance service tiers. Subscription-based net maintenance and digital court calibration services create recurring revenue streams.
- Department Stores:Mass-market retailers stock budget-tier balls and basic protective gear for casual recreational purchasers. Limited SKU depth constrains market share in performance-oriented segments.
Direct sales capture the largest institutional commitments; online retail is climbing the fastest as customization tools expand accessibility.
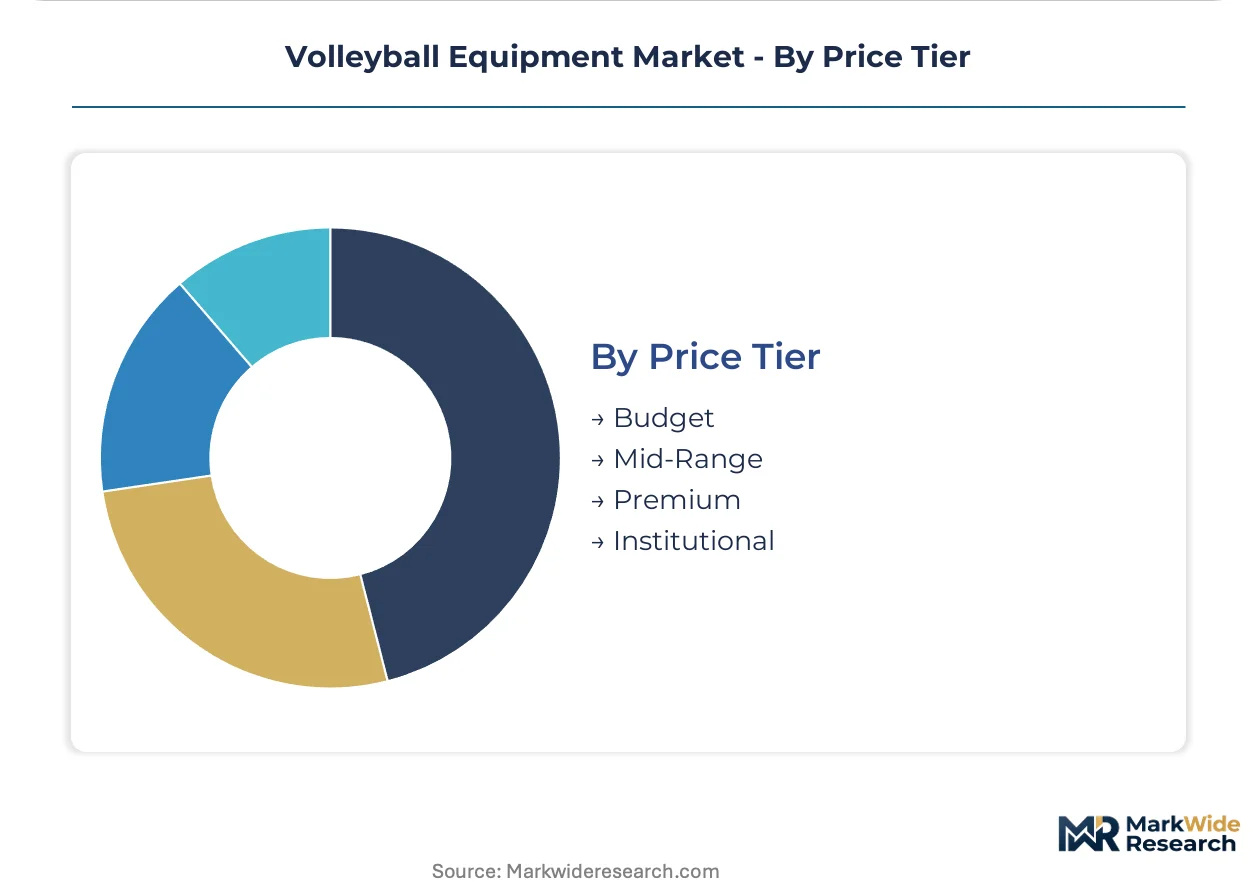
Price Tier:
Certification grade and material specification separate pricing strata, with federation endorsement commanding sustained premium positioning.
- Premium:FIVB-certified competition balls and specialized footwear with proprietary cushioning systems justify elevated pricing through performance guarantees. Mikasa Corporation leverages its certification pipeline to sustain margin in this tier.
- Institutional:Framework agreements specify durability benchmarks and replacement intervals for school district and municipal procurement. Volume commitments compress unit margins while securing multi-year revenue visibility.
- Mid-Range:Synthetic composite balls and standard protective gear serve club programs and serious recreational players. Butyl rubber price volatility squeezes margin as petrochemical feedstock costs fluctuate.
- Budget:Basic polyethylene nets and uncertified balls address price-sensitive recreational demand. Asian petrochemical supply concentration exposes this tier to freight rate spikes and tariff uncertainty.
Institutional tier anchors procurement volume; premium tier demonstrates the steepest expansion trajectory as federation certification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of volleyball equipment concentrates in Asian manufacturing clusters while consumption pulls strongest from North American and Brazilian institutional buyers. This geographic separation shapes freight logistics and certification sequencing for vendors serving multiple markets.
United States
School districts in Texas and California are expanding competitive volleyball programs through statewide cooperative purchasing vehicles. The US Consumer Product Safety Commission monitors youth protective gear under CPSIA chemical content guidelines. Collegiate programs across the Midwest and Southeast pilot microchip-enabled training balls converging with analytics platforms.
Brazil
Federal sports ministry investment in beach volleyball infrastructure ahead of tournament cycles is pulling net systems and court surfaces through public procurement. ANVISA regulates protective gear imports for chemical safety compliance. Coastal municipalities in Rio de Janeiro and São Paulo are codifying public court construction into urban planning frameworks.
Japan
Senoh Corporation anchors domestic manufacturing scale for adjustable steel-aluminum hybrid systems shipped to school districts nationwide. METI oversees industrial standards coordination for sports equipment exports. The Kanto region around Tokyo hosts specialized R&D facilities for net tension monitoring and digital court calibration technologies.
Germany
European protective gear manufacturers reformulate TPU coatings and EVA foam catalysts to satisfy REACH substance restrictions on phthalates and heavy metals. CE marking harmonization streamlines market access across EU member states. Industrial clusters in Bavaria and North Rhine-Westphalia specialize in polymer engineering for impact absorption density tuning.
Australia
Coastal municipalities are embedding beach volleyball court construction into public recreation infrastructure mandates. The TGA monitors therapeutic claims on protective gear marketed with injury prevention benefits. Urban planning frameworks in Queensland and New South Wales specify standardized court dimensions for tournament-ready facilities.
Volleyball Equipment Market Competitive Environment
Capital-heavy producers compete with asset-light designers across distinct equipment categories, with ball manufacturing requiring captive molding capacity while footwear and protective gear rely on outsourced polymer engineering. The market structure fragments across federation-certified competition suppliers, institutional framework contractors, and direct-to-consumer customization platforms. Three archetypes dominate: FIVB certification holders commanding premium pricing, scale manufacturers serving school district procurement vehicles, and digital-native brands leveraging online customization tools. Competitive moves concentrate on multi-year framework agreement capture and subscription-based maintenance service bundling.
Among Japanese manufacturers, Mikasa Corporation, Senoh Corporation, and Mizuno Corporation exemplify divergent strategic positioning. Mikasa occupies the federation-certification tier, leveraging FIVB approval pipelines to sustain premium positioning in competition balls. Senoh represents the scale-manufacturing archetype, optimizing production throughput for institutional net systems. Mizuno anchors the specialized footwear segment, with California-based R&D facilities responding to North American collegiate program specifications.
| Leading Market Players |
|---|
| Spalding Sports Equipment |
| Senoh Corporation |
| Mikasa Corporation |
| Adidas AG |
| Mizuno Corporation |
| Molten Corporation |
| Tachikara Holdings, Ltd. |
| ASICS America Corporation |
| Wilson Sporting Goods Co. |
| Others |
Value Chain & Pricing Dynamics
Institutional procurement vehicles in Texas and California aggregate demand through cooperative purchasing frameworks, compressing unit pricing in exchange for multi-year volume commitments and reshaping vendor margin structures across equipment tiers.
Pricing Analysis
Margin tightening in the mid-range synthetic composite ball segment reflects butyl rubber feedstock volatility tied to petrochemical markets. Three-tier pricing structure across premium, standard, and economy levels separates FIVB-certified competition balls from institutional durability-specified products and uncertified recreational alternatives. Price differentiation hinges on federation certification grade and customization depth for club team orders. Budget-tier buyers exhibit highest price sensitivity, while professional teams and collegiate programs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Brazil's federal sports ministry infrastructure mandates and local-content preferences for public procurement are redirecting net system sourcing toward domestic assembly partnerships. Manufacturing concentration centers on Japan for precision molding equipment, China for polyethylene and nylon raw materials, and Germany for polymer engineering expertise. Ball bladder production draws from Asian petrochemical clusters, while protective gear foam formulation rests on specialized Bavarian and North Rhine-Westphalia industrial capabilities. Tariff exposure on Chinese-sourced net weaving materials poses structural vulnerability. Distribution runs through direct sales channels for institutional framework agreements and online platforms for club and recreational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microchip-enabled training analytics are displacing traditional equipment specifications, creating technology-transition arbitrage for vendors capable of integrating sensor hardware with software subscription models.
For Market Incumbents: Deploy certification pipeline investments to lock in FIVB competition ball approvals before tolerance tightening accelerates. Capture multi-year framework agreements with California and Texas cooperative purchasing vehicles to secure volume visibility against direct-to-consumer entrants. Counter sensor-technology substitutes by bundling digital court calibration services with hardware contracts. For New Entrants and Emerging Players: Begin with beach volleyball infrastructure buildout in Brazilian coastal municipalities where federal sports ministry investment is codifying public court construction. Target club team customization demand through online direct-to-consumer platforms bypassing sports shop intermediaries. Anchor go-to-market strategy around personalized ball panel design tools for collegiate programs. For Investors and Strategic Acquirers: The window for entry favors polymer engineering specialists with EVA foam formulation expertise, as REACH compliance costs and talent scarcity consolidate mid-sized European protective gear suppliers. Long-term viability hinges on subscription-based maintenance service attach rates rather than transactional hardware margins. Watch FIVB recertification queue lengths as inflection signal for competition ball inventory positioning disruptions.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Technology Integration | Microchip-enabled volleyballs converge with analytics platforms to justify premium pricing tiers. |
| Subscription Service Launch | Digital court calibration and net tension monitoring create recurring revenue from institutional buyers. |
| Direct-to-Consumer Platform | Online customization tools bypass sports shop intermediaries for club team orders. |
| Certification Pipeline Investment | FIVB approval queues stretching six to nine months reward early compliance positioning. |
| Framework Agreement Capture | Multi-year contracts with Texas and California cooperative vehicles secure volume commitments. |
Study Parameters
FIVB technical documentation, ASTM International surface specifications, and Brazilian federal sports ministry procurement records formed the secondary backbone. Primary interviews with equipment procurement directors at North American school districts, polymer engineers at protective gear manufacturers, and channel managers at sports retail distributors triangulated against customs data and federation certification databases. Bottom-up demand modeling across user segments and top-down supply validation from manufacturing clusters ensured cross-verification.
Bottom-up volume projections aggregated replacement cycles by equipment category, user tier, and regional procurement intensity. Top-down value estimates calibrated against framework agreement disclosures and direct sales channel throughput. Segmentation dimensions spanned product type, end user category, distribution channel, and price tier across the analysis window. CAGRs derived from historical procurement elasticity and infrastructure investment trajectories, with specific inputs including collegiate program expansion rates and beach volleyball court construction mandates.
Underlying measurement precision varies by segment; institutional framework agreements carry tighter precision than recreational online retail estimates. Forecasts reflect documented assumptions on FIVB standardization timelines and petrochemical feedstock stability. Specific risk factors including butyl rubber price volatility and polyethylene supply concentration could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Europe Running Gear Market
Sports Equipment
Gym Bag Market
Sports Equipment
Mouthguard Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Boxing Gear Market
Sports Equipment
United States Archery Equipment Market
Sports Equipment
Boxing Gloves Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Field Hockey Equipment Market