
 Gear Bicycle Market | 2026-2036
Gear Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Bicycle Market Analysis
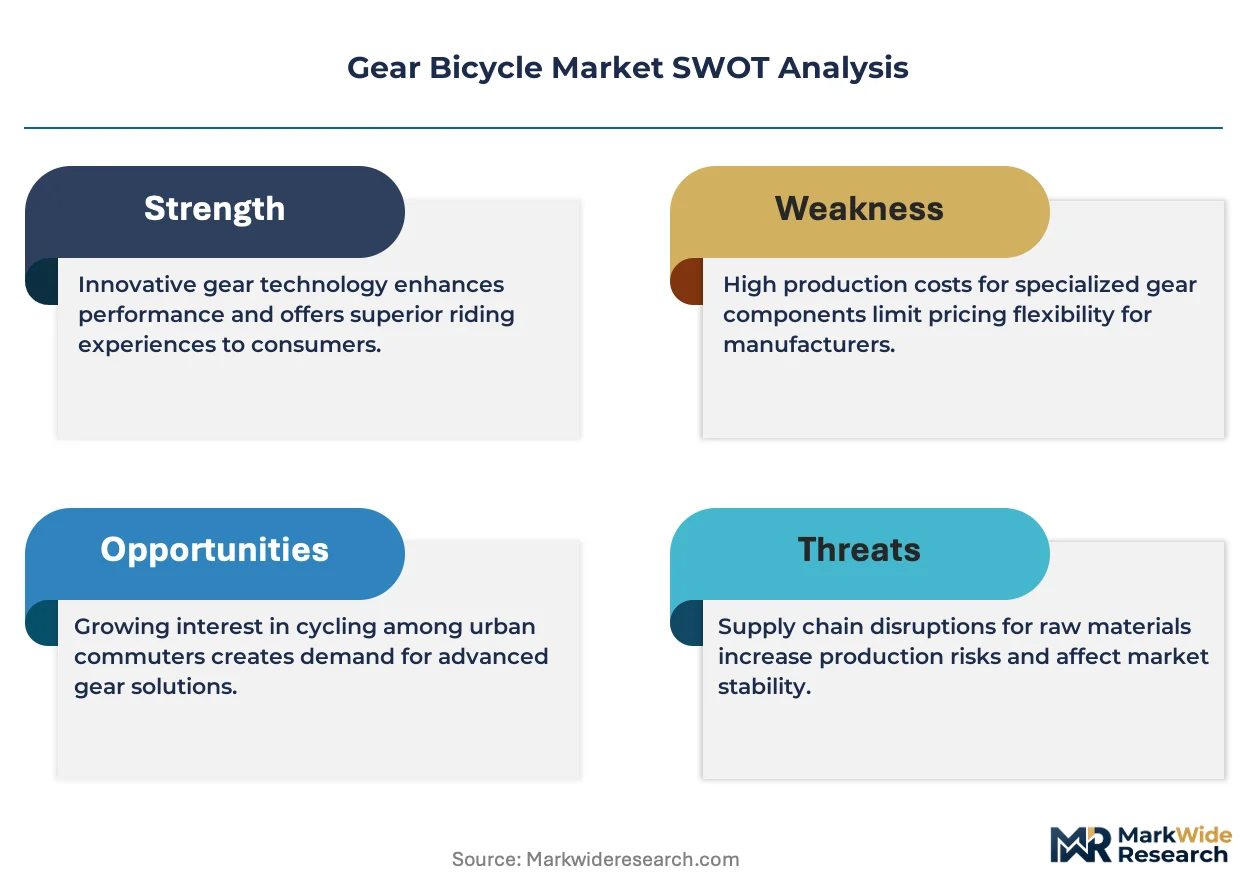
EU Green Deal cycling infrastructure targets are restructuring manufacturer compliance obligations across frame durability and component interoperability standards. Trek leverages in-house carbon fiber layup expertise to sustain premium road bike margins in North American and European markets. Giant anchors mass-market production scale across Taiwan and China manufacturing bases, competing on cost-adjusted specification density against European specialists.
A gear bicycle integrates a mechanical drivetrain comprising derailleurs, gear shifters, chains, and cassettes to enable variable torque conversion across terrain gradients, typically achieving 16 to 33 distinct gear ratios depending on chainring and sprocket configuration. Mountain bikes occupy the largest product type volume pool as trail accessibility expands across North American and Asia-Pacific recreational networks, while road bikes concentrate margin in performance-tier carbon fiber segments where component weight thresholds determine competitive positioning. Hybrid bikes serve the fastest-expanding end-user segment among urban fitness enthusiasts seeking multi-terrain versatility without dedicated fleet investment.
FDA oversight applies to cycling-related medical devices and biometric wearables increasingly bundled with premium gear bicycles, while EPA regulations govern manufacturing facility emissions for carbon fiber pre-preg curing processes in US-based production. REACH compliance in Europe restricts hazardous substances in frame coatings and lubricant formulations, compelling reformulation across supply chains. Stakeholders must monitor evolving e-bike motor integration standards that threaten to subsume traditional mechanical drivetrain demand in commuter and utility segments.
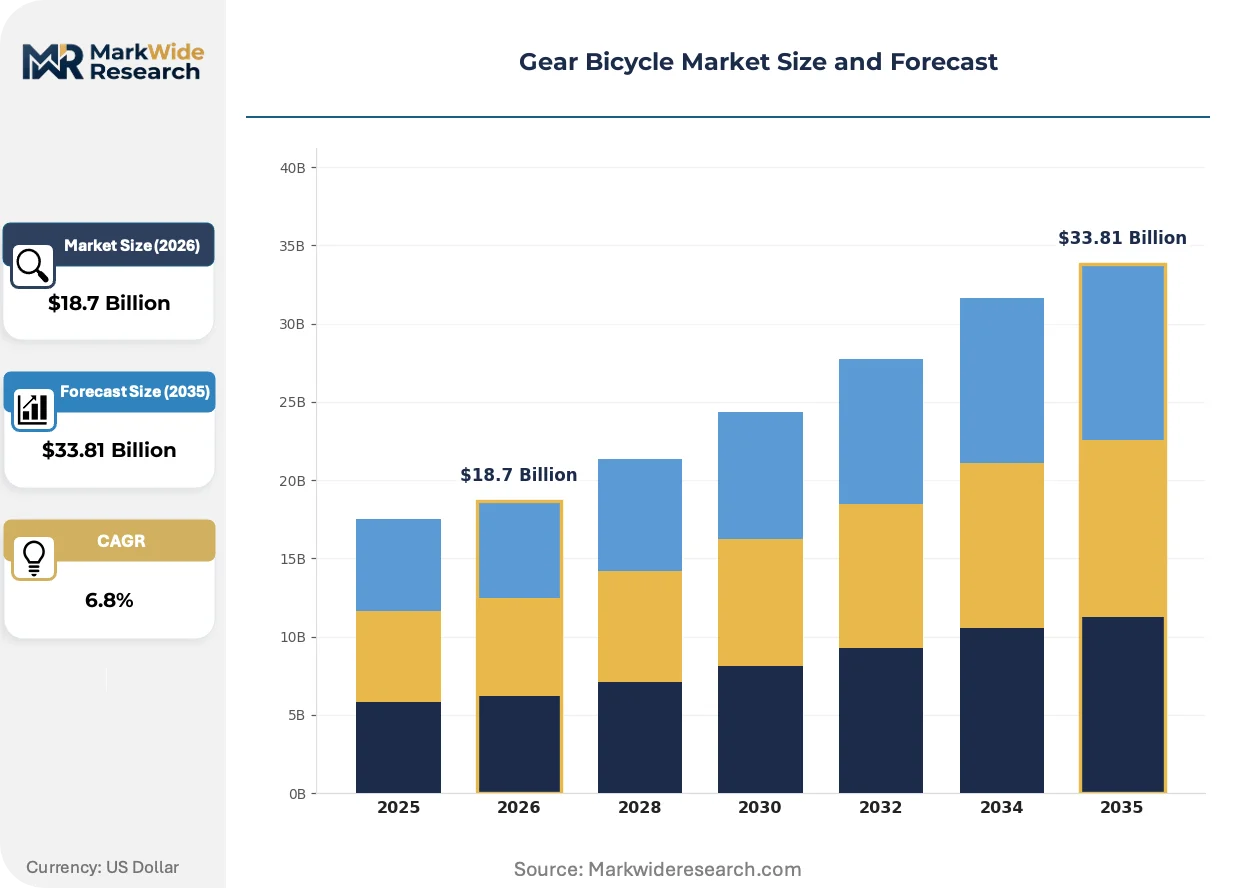
Market Dynamics
EU Green Deal cycling infrastructure mandates are forcing frame durability and component interoperability recalibrations across European supply chains, while e-bike motor integration standards threaten mechanical drivetrain displacement in commuter segments.
Growth Catalysts
- REACH compliance reformulation:ECHA restrictions on hazardous substances in frame coatings and lubricants are accelerating supply chain consolidation toward certified chemical suppliers.
- Urban fitness enthusiast demand:Hybrid bike configurations capture multi-terrain versatility seekers unwilling to maintain dedicated road and mountain fleets.
- Carbon fiber pre-preg curing:Advanced composite manufacturing processes enable sub-kilogram frame production at performance-tier specification density.
Market Restraints
- Titanium and carbon fiber input volatility:Aerospace sector competition for high-modulus fiber and aerospace-grade titanium creates raw material allocation pressure.
- Taiwan and China supply concentration:Frame and component manufacturing gravity in East Asian contract manufacturers exposes buyers to geopolitical logistics friction.
- E-bike motor substitution:Hub and mid-drive electric propulsion systems reduce mechanical complexity requirements in urban commuter and utility segments.
Strategic Opportunities
- Biometric wearable integration:FDA-regulated cycling medical devices bundled with premium drivetrain systems create service revenue attachment.
- EU CSRD reporting alignment:Sustainability disclosure mandates favor manufacturers with verified carbon footprint documentation across frame production.
- Direct-to-consumer channel expansion:Online configuration platforms bypass traditional bike shop intermediaries in North American and European markets.
Industry Challenges
- Carbon fiber layup technician scarcity:Specialized composite manufacturing skills concentrate in aerospace and motorsport sectors, limiting cycling industry access.
- ISO 4210 frame safety certification timelines:Extended testing protocols for impact resistance and fatigue life delay new model introductions.
- Legacy mechanical-electric system integration:Hybrid drivetrains combining traditional derailleurs with electronic shifting require firmware-hardware compatibility management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Bicycle Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain Bikes, Road Bikes, Hybrid Bikes, Commuter Bikes End User: Professional Cyclists, Casual Riders, Fitness Enthusiasts, Youth Component: Derailleurs, Gear Shifters, Chains, Cassettes Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Scott, Cannondale, Specialized, Bianchi, Pinarello, Trek, Canyon, Orbea, Giant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Bicycle Market Emerging Trajectories
Electronic shifting systems and integrated power meters are compressing the performance gap between enthusiast and professional equipment tiers, while regulatory pressure on manufacturing emissions reshapes material sourcing strategies.
Wireless electronic groupsets is unifying derailleur actuation, brake modulation, and power measurement into single-housing units. Performance-tier road cyclists and competitive amateur racers adopt these systems at accelerating replacement cycles. Component manufacturers are unifying previously separate mechanical and electronic supply chains into consolidated firmware-controlled architectures.
EPA emissions standards for carbon fiber pre-preg curing facilities are compelling US-based manufacturers to invest in thermal oxidizer and solvent recovery systems. European frame builders face parallel pressure under EU F-Gas Regulation restrictions on hydrofluorocarbon blowing agents in foam core materials. Premium road and triathlon bike segments absorb compliance costs through specification-tier pricing differentiation.
Subscription-based bike ownership models disrupt traditional retail channels in German and Dutch urban corridors. Metropolitan commuters lease fully maintained gear bicycles with included insurance and seasonal storage, displacing outright purchase. This pattern concentrates in cycling infrastructure-dense municipalities where modal share targets justify fleet-scale procurement.
Gear Bicycle Market Segmentation
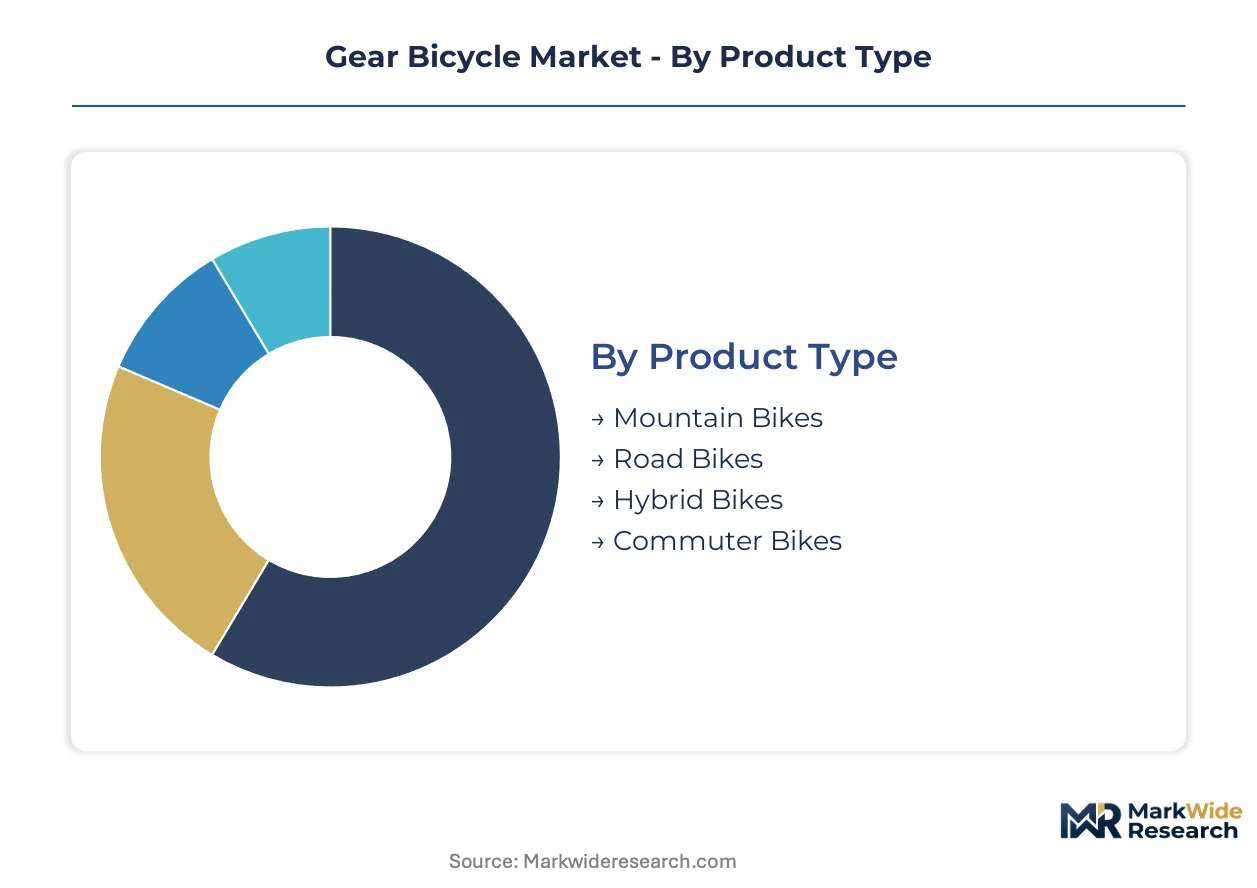
Gear bicycle segmentation reveals divergent capital requirements across manufacturing tiers, with carbon fiber road frames demanding tenfold tooling investment versus aluminum hybrid platforms. Component integration complexity and frame material selection drive fundamentally different margin structures and supplier consolidation patterns across each category.
Product Type:
Capital intensity peaks in carbon fiber road bike manufacturing, where autoclave curing and layup automation require dedicated facility investment exceeding mass-market aluminum production.
- Mountain Bikes:Suspension kinematics and impact-resistant frame geometries dominate engineering priorities. Demand concentrates in North American trail networks and Asia-Pacific recreational clusters where trail accessibility investments are accelerating. Frame durability standards under ISO 4210 certification create compliance barriers for new entrants.
- Road Bikes:Sub-kilogram carbon fiber frames with integrated cable routing define performance-tier positioning. European competitive cycling federations and North American gran fondo participants absorb premium specification density, though titanium input competition from aerospace sectors constrains frame production scaling.
- Hybrid Bikes:Aluminum frame platforms with utility-focused geometry serve multi-terrain versatility seekers in German and Dutch urban corridors.
- Commuter Bikes:Steel and aluminum configurations prioritize rack and fender integration for daily transport use in infrastructure-dense municipalities.
Mountain bikes absorb the bulk of installed capacity; hybrid bikes are expanding most quickly.
End User:
Customer lifetime value varies dramatically, with professional cyclists generating recurring component replacement demand versus single-purchase casual riders.
- Professional Cyclists:UCI-registered teams and continental squads mandate equipment homologation and power meter integration. European WorldTour programs and North American domestic elite teams concentrate sponsorship-driven procurement through authorized dealers.
- Casual Riders:Weekend recreational users prioritize comfort geometry and low maintenance requirements in suburban and ex-urban settings.
- Fitness Enthusiasts:Indoor-outdoor crossover athletes seeking training data integration drive smart trainer compatibility demand.
- Youth:Growth-adjustable frame sizing and simplified drivetrain configurations address parental purchase criteria for durability and value retention.
Professional cyclists command highest per-unit revenue; fitness enthusiasts are climbing the fastest as biometric integration expands.
Component:
Precision manufacturing requirements separate premium drivetrain suppliers from commodity chain and sprocket producers.
- Derailleurs:Parallelogram linkage tolerances and cage stiffness determine shifting precision under load. Electronic actuation systems from Japanese and Italian manufacturers are displacing mechanical alternatives in performance segments.
- Gear Shifters:Ergonomic lever design and cable pull ratio standardization enable cross-manufacturer compatibility.
- Chains:Hollow pin and roller geometries reduce friction losses in high-wattage applications.
- Cassettes:Spider-mounted sprocket clusters versus individual cog designs affect weight and service intervals.
Derailleurs concentrate supplier margins; electronic shifters are gaining share fastest as wireless protocols mature.
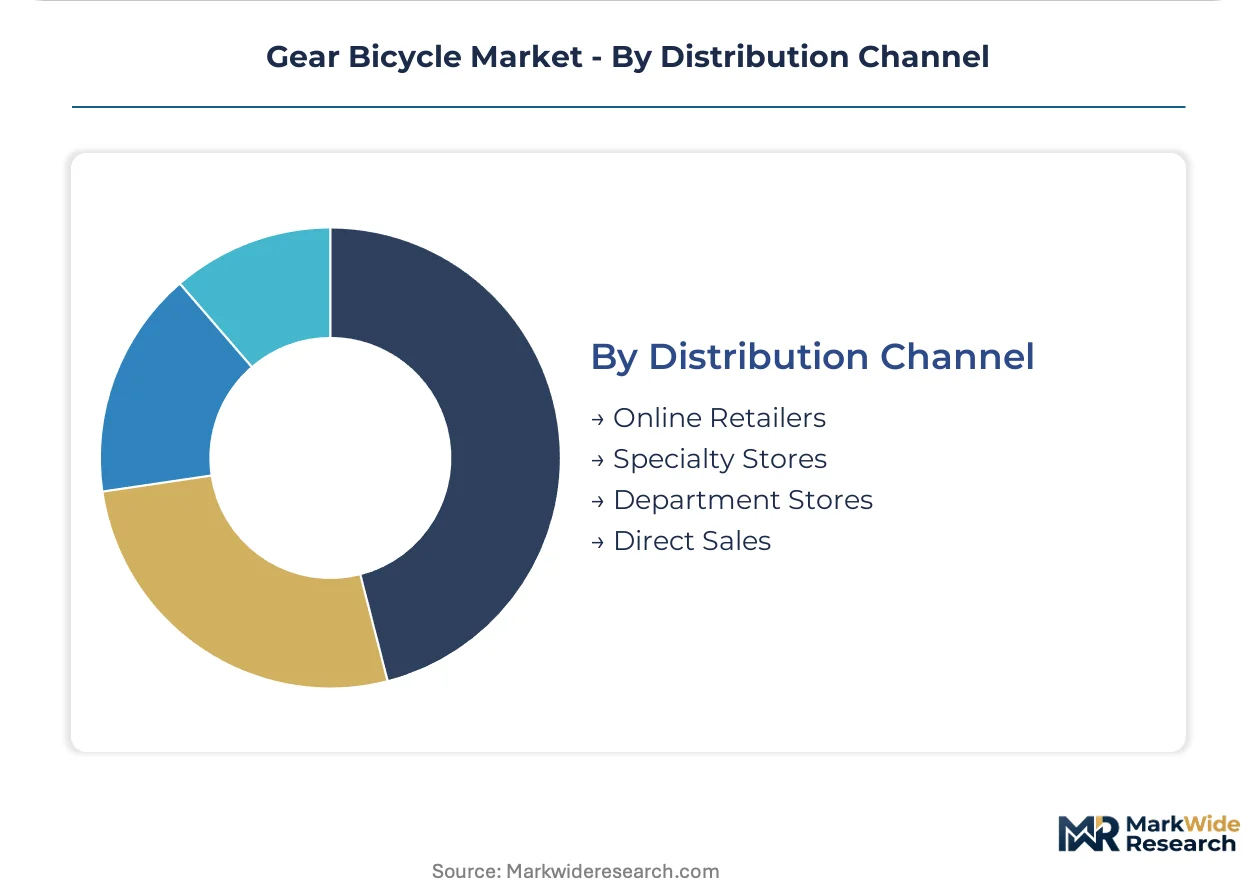
Distribution Channel:
Channel economics reflect service intensity requirements, with specialty stores capturing premium assembly and fitting revenue versus transactional online fulfillment.
- Online Retailers:Direct-to-consumer platforms bypass intermediary markups in North American and European markets. German and Dutch subscription fleet operators source through bulk procurement channels with integrated maintenance contracts.
- Specialty Stores:Professional bike fitters and suspension technicians anchor high-margin service attachment in metropolitan cycling corridors.
- Department Stores:Mass-market volume moves through big-box retail with limited technical support.
- Direct Sales:Manufacturer-owned showrooms and mobile demo programs control brand presentation in premium segments.
Specialty stores retain premium transaction share; online retailers are expanding most quickly as configuration platforms improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, the Netherlands, and Denmark concentrate the deepest cycling infrastructure investment, while regulatory mandates across these jurisdictions reshape frame and drivetrain specifications. Demand clusters in metropolitan corridors where modal share targets drive fleet-scale procurement.
Germany
Fitness enthusiasts and urban commuters in Berlin, Munich, and Hamburg propel hybrid and commuter bike demand. The KBA enforces e-bike motor integration standards that alter mechanical drivetrain requirements. The Ruhr industrial corridor hosts carbon fiber composite suppliers serving premium road bike manufacturers.
Netherlands
Metropolitan Amsterdam and Rotterdam sustain the highest cycling modal share in Europe, driving utility-focused gear bicycle adoption. EU Green Deal cycling infrastructure targets mandate frame durability certifications under ISO 4210. Eindhoven-based component fabricators specialize in electronic shifting system integration.
Denmark
Copenhagen's cycling-first urban planning generates concentrated demand for commuter and cargo-capable gear bicycles. REACH compliance requirements restrict hazardous substances in frame coatings and lubricants across Danish supply chains. Aarhus hosts testing facilities for impact resistance and fatigue life certification.
United States
Trail accessibility investments across Colorado, Utah, and Pacific Northwest states expand mountain bike volume. EPA emissions standards govern carbon fiber pre-preg curing processes for US-based frame production. Greater Boston and San Francisco Bay Area clusters concentrate specialty retail and professional bike fitting services.
China
Recreational cycling growth in Chengdu, Hangzhou, and Shenzhen metropolitan areas drives mid-tier gear bicycle demand. GB standards and MIIT regulations shape domestic manufacturing quality benchmarks. The Yangtze River Delta concentrates contract frame and component production for export markets.
Gear Bicycle Market Vendor Landscape
Taiwan and China producers anchor mass-market scale; European specialists hold premium-tier positioning. The vendor base separates into three functional tiers: integrated multinational brands with captive carbon fiber capabilities, regional specialists competing on specification density, and contract manufacturers serving private-label programs. Consolidation pressures concentrate among mid-scale players lacking proprietary layup expertise or direct-to-consumer channel control. Dominant competitive moves include backward integration into composite material supply and subscription fleet partnerships with municipal procurement programs.
Among US-based integrated brands, Trek and Specialized exemplify the multinational archetype with diversified portfolio coverage across performance road, mountain, and urban segments. Giant anchors the Taiwan-based contract manufacturing tier, supplying frame and component volumes to multiple brand portfolios while maintaining proprietary retail channels. Canyon represents the direct-to-consumer specialist model, bypassing traditional bike shop intermediaries through online configuration platforms. These three companies occupy distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Scott |
| Cannondale |
| Specialized |
| Bianchi |
| Pinarello |
| Trek |
| Canyon |
| Orbea |
| Giant |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap frame builders in northern Italy and southern Germany exercise outsized pricing discipline through captive carbon fiber layup expertise and limited-batch production scheduling. Their ownership structure insulates margin targets from quarterly earnings pressure, enabling selective order acceptance that sustains premium positioning against private-equity-rolled-up competitors chasing volume.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard production slots across European specialty manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by ISO 4210 certification tier and customization depth. Cost compression in aluminum hybrid platforms is intensifying because Taiwanese contract manufacturers are absorbing frame tooling amortization across higher volumes. Casual riders in suburban North American markets exhibit highest price sensitivity, while UCI-registered teams demonstrate lowest elasticity due to sponsorship-driven procurement protocols.
Supply Chain Analysis
EU domestic-content mandates under the Green Deal Industrial Plan are reshaping sourcing patterns for frame coatings and lubricant formulations. Manufacturing gravity draws from Taiwan, China, and Vietnam for aluminum frame extrusion and component forging. High-modulus carbon fiber and aerospace-grade titanium constitute critical input dependencies. Single-source vulnerability concentrates in Toray carbon fiber pre-preg supply for premium road bike segments. Distribution runs through authorized dealer networks for assembly-intensive transactions, with direct-to-consumer platforms capturing lower-complexity hybrid and commuter configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber layup technician scarcity across aerospace and motorsport competitors props pricing in performance-tier segments, constraining capacity expansion regardless of downstream demand signals. This bottleneck sustains margin structures that would otherwise erode under volume competition.
For Market Incumbents: Anchor proprietary composite manufacturing capabilities through apprenticeship partnerships with technical institutes in Stuttgart and Milan. E-bike motor substitution in commuter segments threatens mechanical drivetrain attach rates; defend through firmware-controlled electronic groupset bundling that locks replacement cycles. Prioritize backward integration into carbon fiber pre-preg supply through long-term offtake agreements with Toray or Mitsubishi Chemical.
For New Entrants and Emerging Players: Launch via subscription fleet partnerships with municipal procurement programs in Amsterdam, Copenhagen, and Berlin. White-space targets include biometric wearable integration for fitness enthusiasts seeking indoor-outdoor training data continuity. The most penetrable segment is aluminum hybrid platforms for urban corridors where cycling infrastructure investment is accelerating. Go-to-market angle: configuration platforms with seasonal storage and insurance bundling that displaces outright purchase.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European frame builders with ISO 4210 certification infrastructure but lacking direct-to-consumer channel control. Long-term viability hinges on 5-10 year cycling modal share commitments in EU municipal planning documents. The signal to watch is KBA e-bike motor integration standard revisions that could accelerate mechanical drivetrain displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Pre-preg | Toray supply agreements insulate against aerospace sector allocation pressure. |
| Direct-to-Consumer Channel Expansion | Online configuration platforms bypass bike shop intermediaries in North America. |
| Electronic Groupset Platform Standardization | Firmware-controlled architectures unify previously separate mechanical supply chains. |
| Subscription Fleet Partnerships | Municipal modal share targets in Amsterdam and Copenhagen justify fleet-scale procurement. |
| REACH Compliance Reformulation | ECHA-certified chemical suppliers capture consolidated lubricant and coating demand. |
Methodological Framework
Document review covered trade customs data, SEC filings from publicly traded component manufacturers, ECHA substance restriction databases, and municipal cycling infrastructure investment disclosures, complemented by interviews with frame engineering directors, procurement leads at specialty retail chains, carbon fiber composite plant managers, and UCI team equipment managers. Secondary validation drew from ISO certification registries, EPA emissions compliance records, and EU Green Deal implementation tracking. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Historical shipment data cross-referenced against panel input from component suppliers and frame manufacturers anchored the analytical framework. Segmentation dimensions modeled include frame material tier, end-user category, drivetrain configuration, and regional regulatory cluster. CAGRs derived from slope-intercept fitting of normalized growth curves. Industry-specific forecast inputs incorporated e-bike motor penetration trajectories and cycling infrastructure investment pipelines.
Raw material price volatility, regulatory standard revision timelines, and substitution technology adoption curves are the dominant revision risks to projection assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Archery Equipment Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Tetherball Market
Sports Equipment
Global Wakeboarding Equipment Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Mini Balance Beam Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Golf Club Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Winter Sports Equipment Market
Sports Equipment
Ergonomic Strap Systems Market