
 Campsite Cooking Gears Market | 2026-2036
Campsite Cooking Gears Market Size, Share, and Industry Trends Forecast 2026-2036
Campsite Cooking Gears Market Analytics
The EU Green Deal's product sustainability requirements is realigning material sourcing priorities across campsite cooking equipment supply chains. MSR leverages its Seattle-based engineering heritage to dominate technical stove innovation for alpine conditions. Jetboil anchors the integrated canister system category through proprietary heat-exchange technology. Lodge Cast Iron sustains its position in heirloom-grade cast iron cookware despite weight penalties that limit backcountry appeal.
Campsite cooking gears encompass portable combustion and thermal preparation systems engineered for outdoor environments, typically constructed from anodized aluminum, stamped stainless steel, or investment-cast titanium to achieve weight targets below 500 grams per unit for backpacking configurations. These products serve the functional purpose of converting compressed gas, liquid fuel, or solid biomass into controlled thermal energy for food preparation and water purification in off-grid locations. Stove systems capture the largest margin pools due to patented burner architectures and fuel compatibility complexity, while titanium cookware commands premium positioning based on strength-to-weight ratios that appeal to gram-counting long-distance trekkers. The foldable and compact form factor categories are experiencing accelerated uptake as vehicle-based camping and vanlife configurations demand space-efficient storage solutions.
REACH substance restrictions govern chemical composition limits for coatings and alloys entering European distribution channels, while FDA food-contact material standards regulate surface treatments and metallic migration thresholds for products sold in the United States. The EU F-Gas Regulation indirectly shapes portable refrigeration integration trends that complement cooking gear ecosystems in basecamp scenarios. Stakeholders must monitor evolving national park service fire restrictions and backcountry combustion permit systems that periodically ban certain stove technologies across high-risk wildfire zones.
Market Dynamics
Ultralight titanium adoption is compressing aluminum's dominance across backpacking stove and cookware architectures, forcing supply chains to requalify metallurgical specifications and welding processes.
Growth Catalysts
- EU Green Deal product sustainability mandates:Manufacturers redesign coating chemistries and alloy compositions to satisfy circular economy criteria, opening premium positioning for verified low-carbon titanium sourcing.
- Vanlife configuration proliferation:Vehicle-based campers demand compact nesting cookware sets and multi-fuel stove systems that integrate with limited storage volumes.
- Wildfire risk management protocols:National park services and forest management agencies in fire-prone western US states restrict open-flame combustion, accelerating demand for contained canister systems with automatic shutoff valves.
Market Restraints
- Titanium sponge supply concentration:Primary titanium sponge production clusters in China and Russia expose Western fabricators to export control volatility and tariff uncertainty.
- REACH substance compliance costs:European manufacturers face extended testing timelines and reformulation expenses for non-stick ceramic coatings and anodized layer chemistries.
- Biomass stove substitution in emerging markets:Solid fuel rocket stoves fabricated from locally sourced materials compete on absolute cost in price-sensitive outdoor recreation segments across South Asia and sub-Saharan Africa.
Strategic Opportunities
- Indian outbound adventure tourism expansion:Himalayan trekking operators and domestic gear retailers represent underdeveloped distribution channels for technical alpine cooking systems.
- Solar-thermal hybrid integration:Convergence of photovoltaic panel miniaturization with electric heating elements enables off-grid basecamp configurations that reduce fossil fuel dependency.
- US Inflation Reduction Act clean manufacturing credits:Domestic titanium machining and precision casting facilities qualify for production tax incentives that offset capital equipment depreciation.
Industry Challenges
- TIG welding certification scarcity:Qualified titanium welders command premium wages and extended recruitment cycles, constraining production scale-up for thin-wall cookware fabrication.
- Multi-standard food-contact testing:Simultaneous FDA metallic migration, EFSA coating integrity, and JIS surface finish compliance extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Campsite Cooking Gears Market |
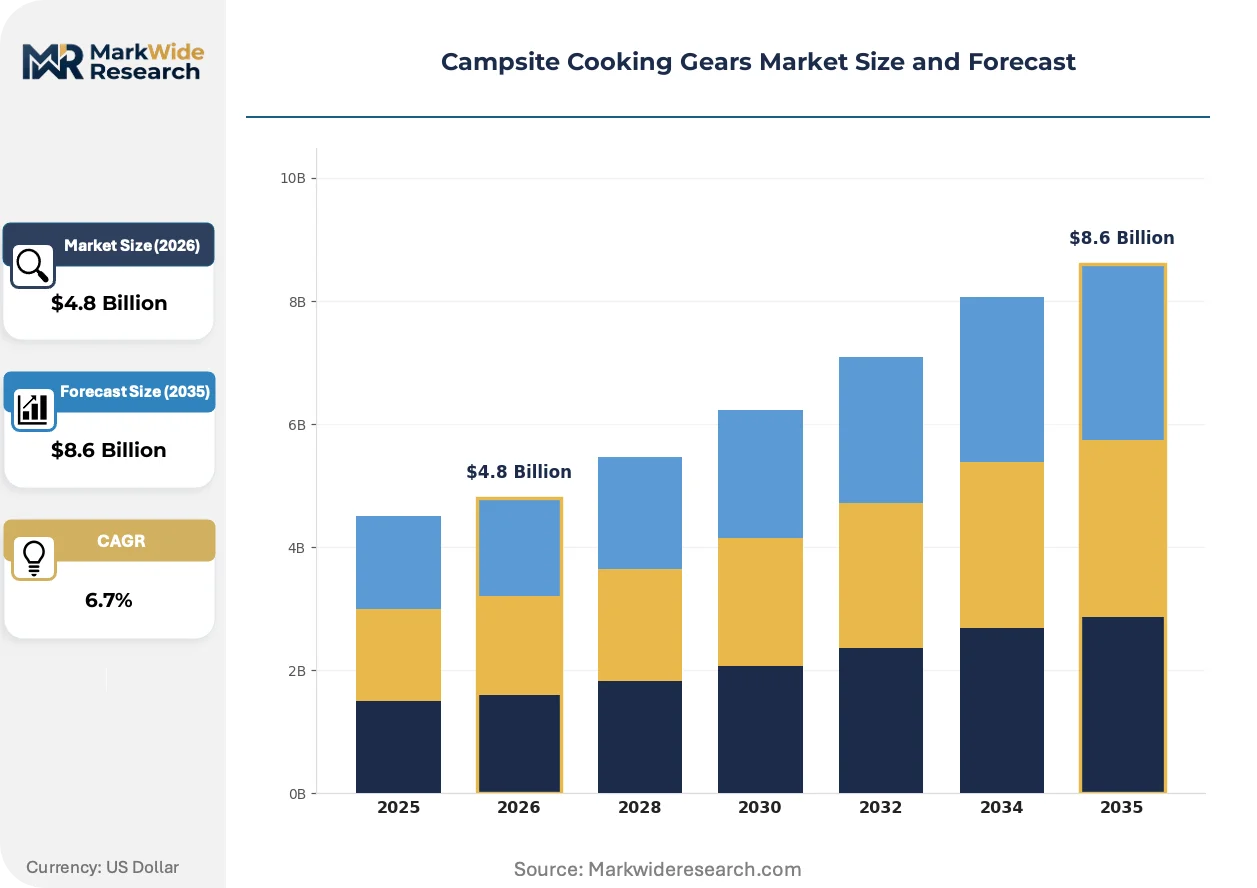
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stoves, Cookware, Grills, Utensils Material: Aluminum, Stainless Steel, Cast Iron, Titanium Form: Portable, Foldable, Compact, Multi-functional End User: Families, Backpackers, Adventurers, Campers |
| Companies Covered | Newell Brands, Vista Outdoor, MSR, GSI Outdoors, Lodge Cast Iron, Jetboil, Camp Chef, Primus, Coleman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Campsite Cooking Gears Market Evolving Landscape
Integrated heat-exchange stove systems are compressing boil times and fuel efficiency benchmarks, reshaping competitive differentiation around thermal transfer engineering rather than raw burner output.
Titanium is consolidating its position as the dominant material for gram-critical backpacking configurations. Thru-hikers and alpine climbers specify titanium pots, cups, and sporks below 100 grams per piece. This material shift is consolidating supplier relationships around Japanese and US-based titanium mills with aerospace-grade quality systems, marginalizing commodity aluminum stamping houses.
REACH substance restrictions are forcing coating reformulation across European distribution channels. Manufacturers eliminate perfluorinated compounds from non-stick surfaces and substitute ceramic-silica hybrid layers. Backpacking cookware lines bound for EU markets now carry separate SKUs with compliant surface treatments, fragmenting inventory management.
Direct-to-consumer channel expansion is compressing traditional outdoor retail margins. Specialty e-commerce platforms and brand-owned storefronts capture technical gear purchases from experienced users who bypass brick-and-tape outfitters. This behavior shift concentrates most visibly in the Pacific Northwest and Colorado Front Range, where digitally native buyers research specifications independently before purchase.
Campsite Cooking Gears Market Segmentation
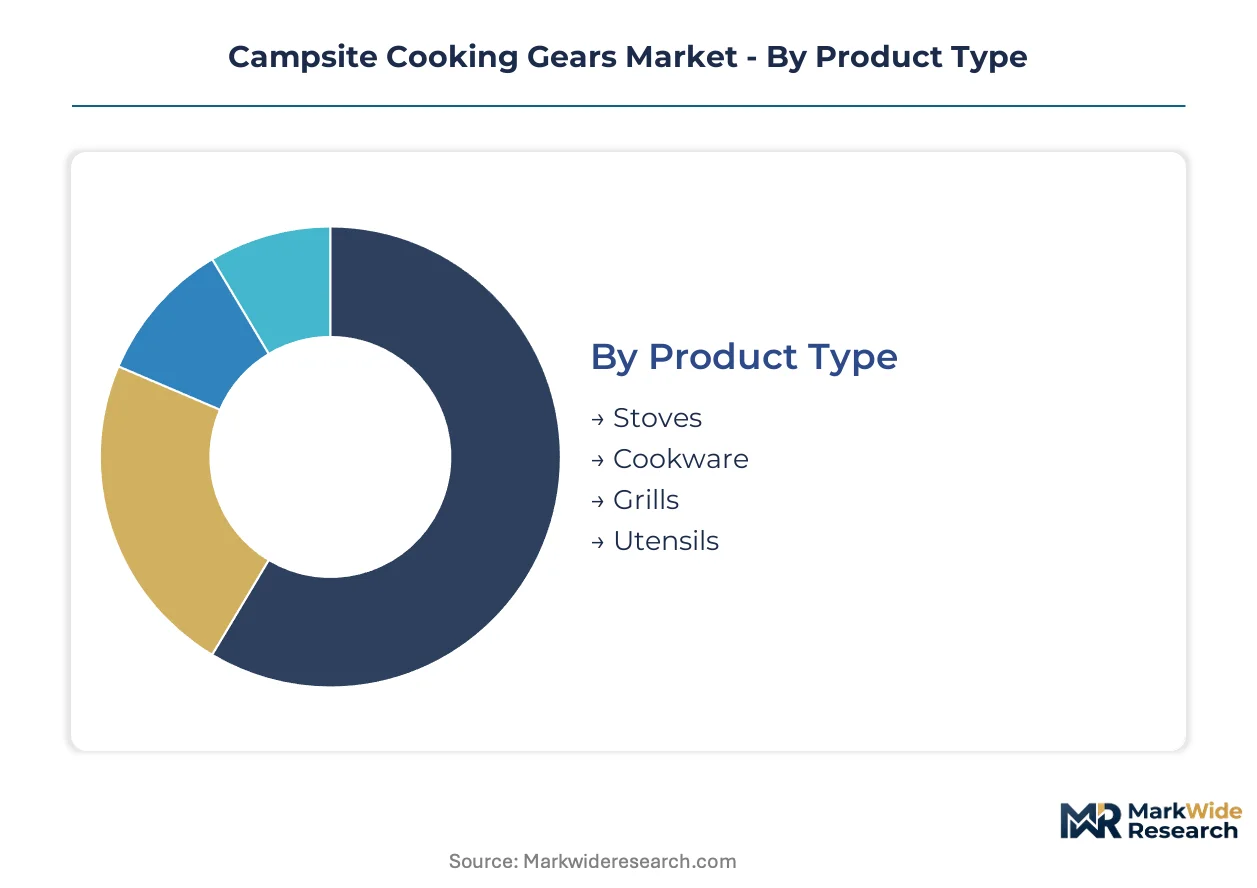
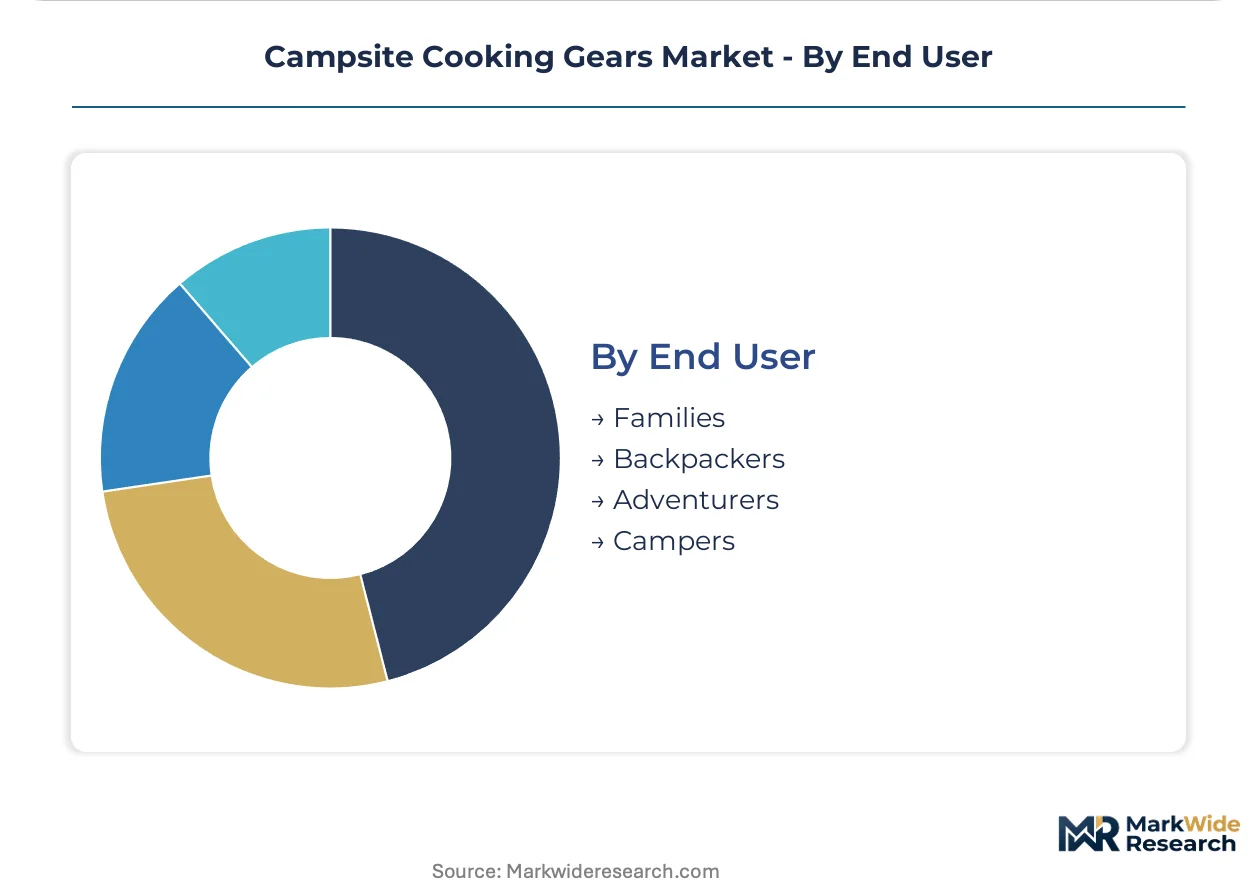
Segmentation in campsite cooking gears reveals distinct engineering priorities across user archetypes. Backpackers prioritize gram-counting specifications that reshape material selection, while vehicle-based campers optimize for nesting efficiency and multi-fuel compatibility.
Product Type:
End-use intensity dictates replacement cycles and margin capture across combustion versus thermal preparation systems.
- Stoves:Patented burner architectures and fuel-valve engineering command premium positioning. Demand concentrates in alpine zones and Pacific Northwest trailheads where multi-fuel versatility addresses variable canister availability.
- Cookware:Titanium pots and anodized aluminum nesting sets dominate gram-critical configurations. Backpacker segments in Colorado Front Range and Rocky Mountain corridors drive specifications below 500 grams per unit.
- Grills:Vehicle-based camping configurations favor collapsible charcoal and propane systems with integrated ash management.
- Utensils:Sporks, folding spatulas, and nesting cutlery sets complete system purchases for organized basecamp kitchens.
Volume sits with Cookware; growth tilts toward Stoves.
Material:
Weight-to-strength ratios and regulatory compliance reshape procurement across metallurgical supply chains.
- Titanium:Aerospace-grade sponge sourced from Japanese and US mills enables sub-100-gram cookware pieces. REACH substance restrictions and FDA metallic migration thresholds force separate EU and US SKUs for surface treatments.
- Aluminum:Anodized stamping houses face margin compression as titanium displaces mid-range backpacking configurations. Reformulation costs for ceramic-silica hybrid coatings extend European product launch timelines.
- Stainless Steel:Stamped 304-grade systems serve car-camping and overland segments where weight penalties are acceptable.
- Cast Iron:Heirloom-grade Lodge production sustains demand in frontcountry and vanlife configurations despite backcountry inapplicability.
Volume concentrates in Aluminum; titanium climbs the fastest.
Form:
Storage geometry and transport constraints determine design engineering priorities across mobile versus stationary use cases.
- Compact:Nesting cookware sets and integrated stove systems minimize cubic volume for vanlife and rooftop tent configurations. Pacific Northwest vehicle-based campers prioritize space-efficient solutions that stow in limited cabinetry.
- Foldable:Hinged grill grates and collapsible windscreens address fire restriction compliance in western US national forests.
- Portable:Detachable components and quick-connect fuel lines serve multi-activity users transitioning between car camping and short backpacking trips.
- Multi-functional:Combined pot supports, windscreens, and heat exchangers consolidate single-unit purchases for experienced users.
Volume resides in Portable; expansion tilts toward Compact.
End User:
Experience level and trip duration separate specification requirements across casual and technical outdoor recreation.
- Backpackers:Thru-hikers and alpine climbers demand sub-500-gram stove systems and titanium cookware with heat-exchange integration. Digitally native buyers in Colorado and Washington research specifications independently before direct-to-consumer purchase.
- Adventurers:Technical mountaineering and multi-day river trips require multi-fuel stoves and durable nesting sets. Himalayan trekking operators represent underdeveloped distribution channels for alpine-rated systems.
- Families:Frontcountry car campers prioritize capacity and stability over weight, driving demand for larger cookware sets and stable grill platforms.
- Campers:Occasional recreational users purchase entry-level canister stoves and aluminum cook sets through traditional outdoor retail channels.
Volume sits with Families; growth tilts toward Backpackers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors technical stove engineering for alpine conditions, while manufacturing clusters across Japan and the United States supply aerospace-grade titanium sponge to Western fabricators. Demand concentrates in Pacific Northwest and Rocky Mountain corridor destinations where vanlife configurations and backcountry trekking overlap.
United States
Pacific Northwest and Colorado Front Range campers drive specifications for sub-500-gram titanium systems and compact nesting cookware. FDA food-contact material standards regulate metallic migration thresholds for surface treatments. Seattle-based engineering heritage clusters dominate technical stove innovation for alpine-rated multi-fuel architectures.
Germany
REACH substance restrictions force coating reformulation and extended testing timelines for non-stick ceramic surfaces. EU Green Deal product sustainability mandates reshape procurement toward verified low-carbon titanium sourcing. Bavarian precision machining facilities supply thin-wall cookware fabrication for premium backpacking configurations.
Japan
Domestic titanium mills with aerospace-grade quality systems supply Western fabricators facing sponge supply concentration risks elsewhere. METI industrial standards govern surface finish specifications for food-contact applications. Osaka-based metallurgical expertise enables sub-100-gram cookware pieces for gram-critical thru-hiker segments.
India
Himalayan trekking operators and domestic gear retailers represent underdeveloped distribution channels for technical alpine cooking systems. BIS standards govern metallic migration for food-contact materials in domestic distribution. Maharashtra-based adventure tourism expansion drives outbound demand for compact multi-burner systems.
Australia
Vehicle-based camping configurations across New South Wales and Queensland prioritize space-efficient storage solutions for rooftop tent deployments. TGA regulations align with FDA metallic migration thresholds for imported titanium cookware. Sydney and Melbourne digital-native buyers research specifications independently before direct-to-consumer purchase.
Campsite Cooking Gears Market Competitive Landscape
Premium-margin players sit above commodity-margin players across patented burner architectures and fuel-valve engineering complexity. The vendor base stratifies between technical alpine specialists, integrated canister system innovators, and heritage cast iron producers. Three archetypes dominate: Seattle-engineered technical stove developers, Japanese titanium mill-integrated fabricators, and multi-brand outdoor conglomerates with portfolio diversification. Competitive moves concentrate on strategic partnerships for fuel compatibility expansion and geographic expansion into Himalayan trekking distribution channels.
Among United States-based innovators, MSR and Jetboil exemplify the premium-tier engineering archetype, while Lodge Cast Iron occupies a distinct position in heirloom-grade thermal preparation systems. Newell Brands and Vista Outdoor represent multi-brand portfolio structures that consolidate outdoor recreation assets across combustion and cookware categories. These five entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Newell Brands |
| Vista Outdoor |
| MSR |
| GSI Outdoors |
| Lodge Cast Iron |
| Jetboil |
| Camp Chef |
| Primus |
| Coleman |
| Others |
Value Network & Pricing Analysis
Titanium sponge production consolidation across Chinese and Russian metallurgical complexes simultaneously elevates raw material costs and compresses Western fabricator margins. This metallurgical transition forces pricing power toward upstream sponge producers while downstream brands absorb volatility through tiered product architectures.
Pricing Analysis
Gram-counting performance anchors value-based pricing for thru-hiker segments willing to pay premiums for sub-100-gram titanium pieces. Three-tier pricing structure across premium aerospace-grade, standard mill-certified, and economy recycled-alloy levels separates MSR and Jetboil from commodity aluminum competitors. Pricing pressure stems from REACH compliance costs forcing dual-SKU inventory for European distribution. Backpackers exhibit lowest price sensitivity; occasional family campers drive volume at entry-level aluminum price points.
Supply Chain Analysis
Single-source vulnerability sits with Chinese titanium sponge producers controlling roughly two-thirds of global primary output. Western fabricators draw from Japanese and US aerospace-grade mills for certified backpacking cookware, with anodized aluminum stamping concentrated in Vietnam and Bangladesh. Tariff exposure on Chinese-origin sponge threatens margin stability for mid-tier brands. Distribution runs through direct-to-consumer platforms and specialty outdoor retailers, with Pacific Northwest and Colorado Front Range buyers bypassing traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TIG welding certification scarcity constrains production scale-up, propping pricing for qualified titanium fabricators. This capacity bottleneck protects margin pools for incumbents with established metallurgical workforces.
For Market Incumbents: Deploy backward integration into Japanese titanium mill partnerships to secure aerospace-grade sponge allocation. Strengthen proprietary heat-exchange patent portfolios against emerging canister-system competitors. Channel control through direct-to-consumer platform investment defends against specialty retailer margin compression.
For New Entrants and Emerging Players: Launch via Himalayan trekking operator partnerships to bypass saturated North American distribution. Target Indian outbound adventure tourism with compact multi-burner systems engineered for high-altitude conditions. White-space concentration in solar-thermal hybrid basecamp configurations offers differentiation from fossil-fuel incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in multi-brand outdoor conglomerates seeking titanium machining capabilities. Long-term viability hinges on qualified welder workforce retention and REACH-compliant coating formulation assets. Watch Indian BIS standard harmonization with FDA metallic migration thresholds as inflection signal for geographic expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge Sourcing | Secures allocation from Japanese mills amid Chinese export control volatility. |
| REACH-Compliant Coating Reformulation | Enables unified SKU management across EU and US distribution channels. |
| Direct-to-Consumer Platform Expansion | Captures digitally native buyers in Pacific Northwest and Colorado corridors. |
| Himalayan Distribution Partnership | Opens underdeveloped channels among Indian trekking operators and domestic retailers. |
| Solar-Thermal Hybrid R&D Investment | Positions for EU Green Deal clean energy mandates in basecamp configurations. |
Research Methodology
Multi-period observation of titanium sponge pricing volatility and REACH compliance timelines anchored the trend analysis, supplemented by interviews with product development leads at Seattle-based stove engineers, procurement directors at Japanese titanium mills, Himalayan trekking operators, and specialty outdoor retail buyers. Secondary validation drew from USGS mineral commodity summaries, ECHA substance restriction databases, USITC trade flow records, and outdoor industry association shipment data. Bottom-up SKU-level modeling triangulated against top-down regional demand estimation.
Segment-weighting applied end-user intensity scores across backpacker, adventurer, family, and casual camper archetypes, with material-grade tiers and form-factor dimensions layered throughout the projection horizon. CAGRs derived from regression against outdoor participation rates, vanlife vehicle registration trends, and national park visitation patterns. Fuel compatibility complexity indices and wildfire restriction frequency informed stove-system demand modeling.
The model assumes a particular technology adoption path; alternative pathways for solid-fuel rocket stove substitution in emerging markets would alter the outlook. Forecasts reflect assumptions regarding REACH substance restriction enforcement consistency and titanium sponge trade policy stability. Deviation in USFS fire restriction protocols or Chinese export licensing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
North America Robotic Lawn Mower Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Camping Equipment and Furniture Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Rooftop Tent Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
Rain Boots Market
Outdoor Gear
North America Pocket Knives Market