
 Rain Boots Market | 2026-2036
Rain Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Rain Boots Market Analytics
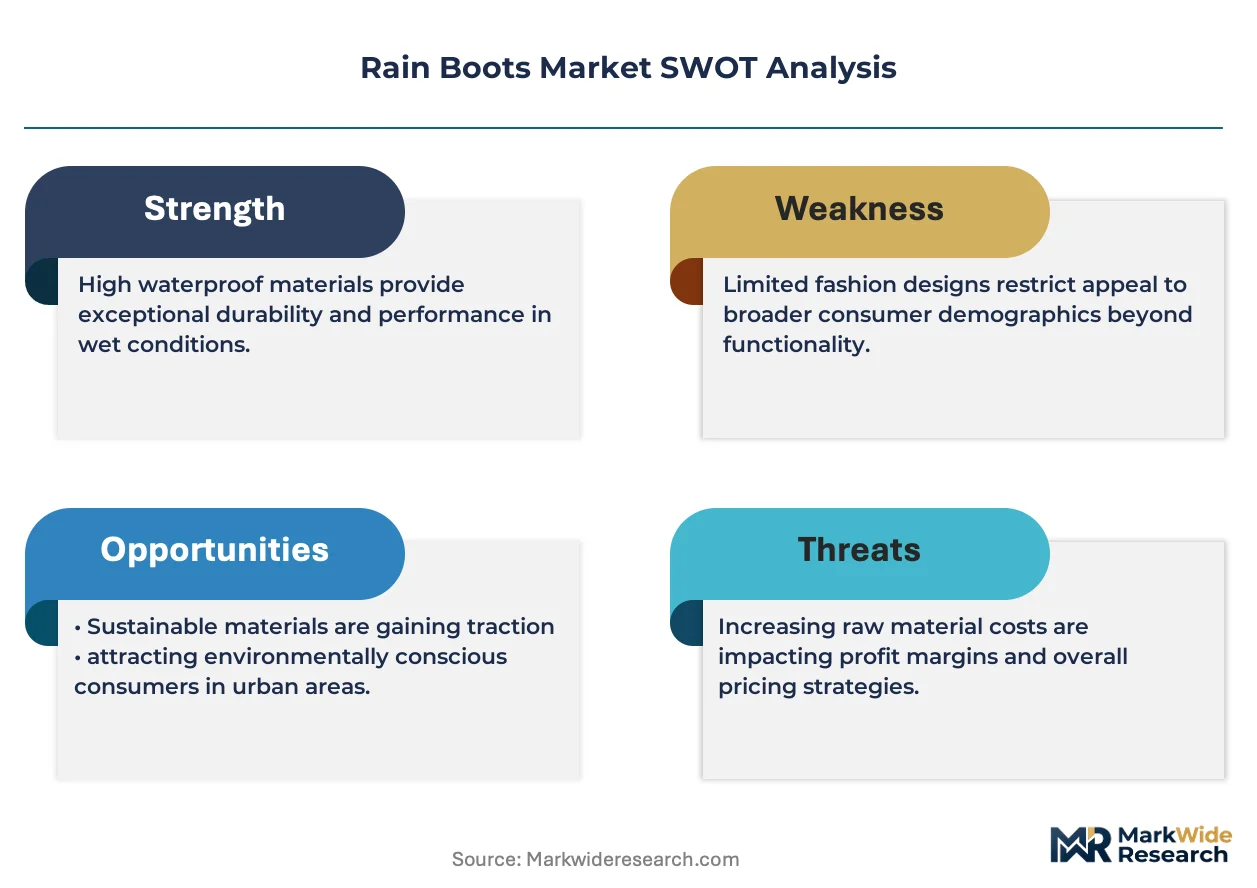
China's expanded rubber processing capacity in Guangdong and Zhejiang provinces is reshaping upstream supply dynamics for molded footwear. Hunter leverages vertical integration from compound formulation to finished goods, sustaining margin control across European distribution. Kamik dominates cold-climate variants through captive manufacturing in Quebec, insulating its North American position against Asian import competition. Bogs specializes in neoprene-lined performance boots, occupying the premium outdoor segment with proprietary insulation technology.
Rain boots are waterproof footwear constructed from vulcanized rubber, PVC, or neoprene compounds, typically featuring seamless molded construction with slip-resistant outsoles and height ranging from ankle to knee coverage. Manufacturers cure natural or synthetic rubber at 120–160°C under pressure to achieve elasticity and watertight integrity, producing protective gear for agricultural, recreational, and occupational wet-environment applications. Rubber formulations retain the largest volume share due to established recyclability infrastructure and consumer familiarity, though neoprene is gaining fastest in cold-weather performance tiers where thermal retention commands price premiums. The customer type dimension reveals women as the dominant purchasing cohort, with adult everyday-wear applications generating the steadiest replenishment cycles compared to episodic festival or gardening demand.
EPA oversight of phthalate content in PVC consumer products and REACH restrictions on polycyclic aromatic hydrocarbons in rubber compounding are elevating compliance costs for manufacturers serving transatlantic markets. ECHA's evolving SVHC candidate list pressures reformulation timelines, particularly for legacy plasticizers in children's footwear segments. ISO 20347 occupational footwear standards influence commercial procurement specifications for industrial rain boot contracts. Stakeholders must monitor regulatory divergence between European hazard-based restrictions and US risk-assessment frameworks when configuring regional product portfolios and material qualification programs.
Market Dynamics
REACH restrictions on polycyclic aromatic hydrocarbons and EPA phthalate oversight are forcing simultaneous reformulation of rubber compounds and PVC alternatives across transatlantic supply chains, compressing legacy material qualification timelines while elevating compliance spend.
Growth Catalysts
- REACH SVHC expansion:ECHA's evolving candidate list accelerates substitution of legacy plasticizers in children's footwear segments, opening qualified-supplier advantages for early reformulators.
- Guangdong-Zhejiang rubber processing:China's expanded vulcanization capacity is lowering compound input costs for molded footwear producers serving European and North American distributors.
- Municipal gardening subsidies:Germany's above-average household penetration of specialized wet-weather footwear sustains replenishment cycles distinct from episodic festival demand.
Market Restraints
- Natural rubber price volatility:Southeast Asian latex supply disruptions transmit directly to vulcanized boot margins, compressing working capital flexibility for compound-dependent manufacturers.
- Quebec manufacturing concentration:Captive cold-climate production in eastern Canada creates geographic single-point vulnerability for North American thermal boot supply.
- Neoprene thermal limitations:Proprietary insulation technology faces performance ceilings above sub-zero thresholds, restricting addressable market in extreme-climate occupational segments.
Strategic Opportunities
- Festival culture expansion:Outdoor event programming in the Netherlands and Belgium presents underpenetrated demand for fashion-forward waterproof footwear beyond core German penetration.
- ISO 20347 commercial procurement:Occupational footwear standards create specification-driven contract opportunities for industrial rain boot suppliers meeting certified slip-resistance thresholds.
- Recyclability infrastructure:Established rubber recovery networks enable closed-loop material claims that differentiate premium positioning against PVC alternatives lacking comparable end-of-life pathways.
Industry Challenges
- Reformulation chemistry expertise:SVHC-driven compound redesign requires polymer scientists capable of balancing elasticity, watertight integrity, and thermal retention under compressed timelines.
- Dual-framework compliance:Divergence between European hazard-based restrictions and US risk-assessment frameworks forces parallel qualification programs for transatlantic product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rain Boots Market |
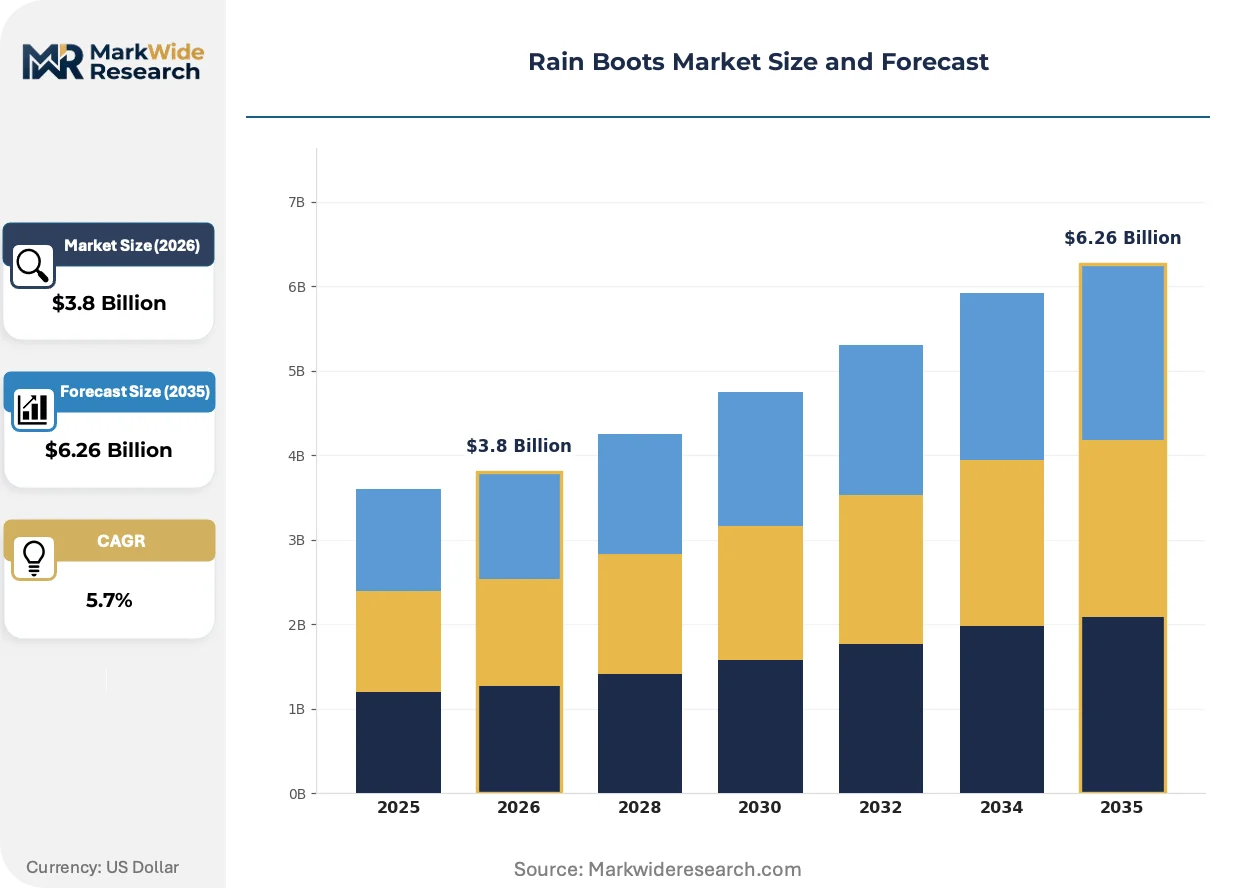
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, PVC, Neoprene, Leather Usage Scenario: Outdoor Activities, Gardening, Festivals, Everyday Wear Customer Type: Children, Adults, Women, Men Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Muck Boot Company, Joules, Bogs, XTRATUF, Le Chameau, Kamik, Crocs, Grundéns, Hunter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rain Boots Market Evolving Landscape
Digital material qualification platforms are compressing compound development cycles while regulatory automation tools reshape how manufacturers manage multi-jurisdiction compliance documentation across dispersed supply networks.
Biobased rubber alternatives derived from guayule and dandelion latex are virtualizing traditional petroleum-dependent supply chains, with agricultural cooperatives in Arizona and Kazakhstan piloting cultivation at commercial scale. Footwear compounders in Portugal and Italy are integrating these feedstocks into vulcanization trials, enabling carbon footprint claims that satisfy CSRD disclosure requirements while reducing exposure to Southeast Asian supply volatility.
EPA oversight of phthalate content in PVC consumer products is tightening material composition requirements for synthetic boot compounds serving North American retail channels. Children's footwear segments face the most acute compliance pressure, with importers accelerating shifts toward TOTM and DINCH plasticizers that maintain flexibility without triggering Section 6(a) restrictions under the Toxic Substances Control Act.
Direct-to-occupational procurement is bypassing traditional wholesale distribution for industrial rain boot contracts, with municipal park systems and agricultural cooperatives consolidating seasonal worker footwear purchases through centralized tender platforms. Germany's federal procurement office and France's national forestry service have adopted this model most extensively, compressing distributor margins while rewarding manufacturers with ISO 20347 certification and transparent compound documentation.
Rain Boots Market Segmentation
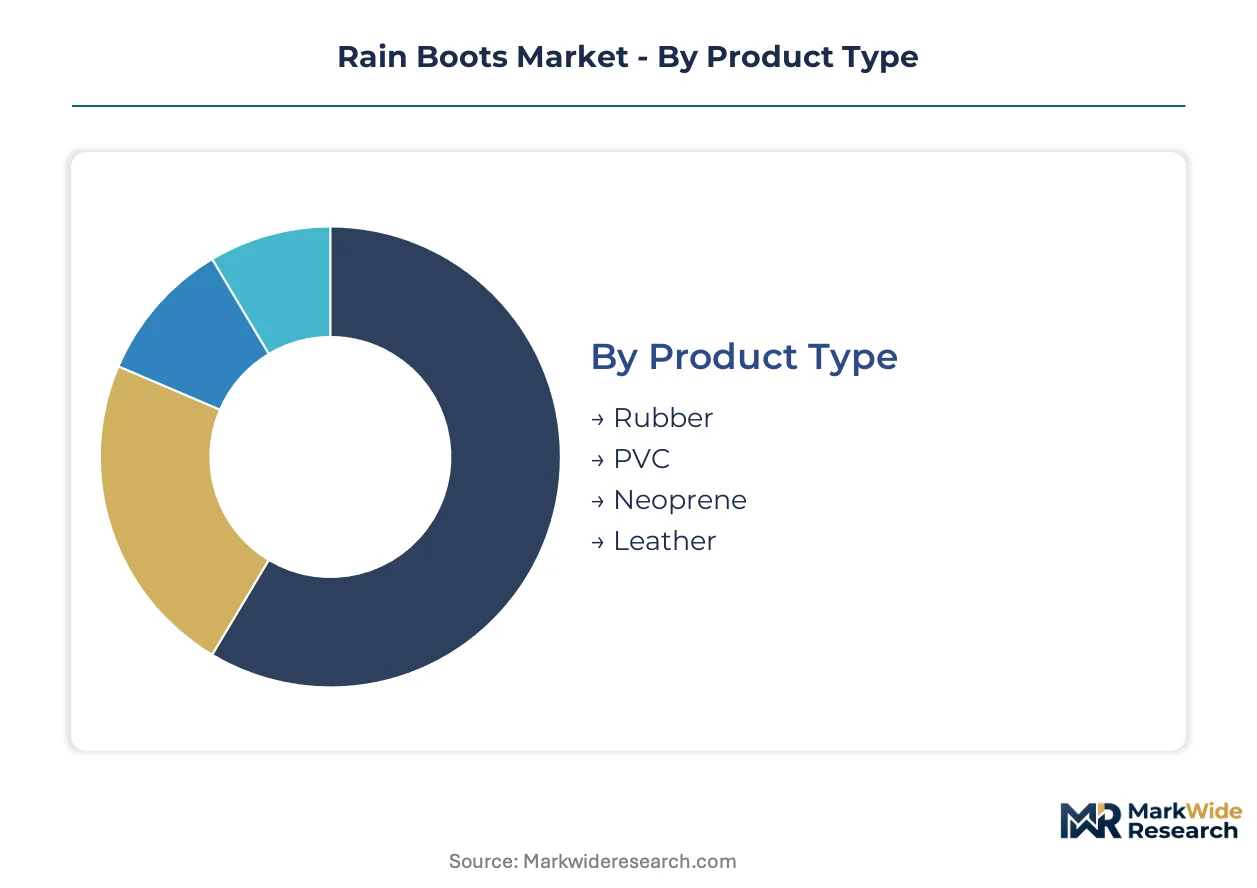
Segmentation in the rain boots market reveals how material chemistry, use occasion, and channel economics partition value capture. Manufacturers configure compound formulations and height specifications differently across these dimensions to match performance expectations with procurement budgets.
Product Type:
Material composition determines elasticity, thermal retention, and end-of-life recovery pathways for molded waterproof footwear.
- Rubber:Vulcanized natural or synthetic compounds cured at 120–160°C deliver established watertight integrity and recyclability infrastructure. Agricultural cooperatives in France and municipal park systems in Germany specify rubber compounds for seasonal worker procurement due to proven durability in continuous wet exposure.
- Neoprene:Closed-cell synthetic rubber provides thermal insulation for sub-zero performance tiers. Cold-climate occupational segments in Quebec and Scandinavian forestry operations drive specification, though performance ceilings above extreme thresholds restrict addressable market expansion.
- PVC:Injection-molded polyvinyl chloride offers cost-efficient production at compliance cost elevation from EPA phthalate oversight and REACH plasticizer restrictions.
- Leather:Treated hide constructions occupy niche fashion-forward positioning with waterproofing limitations relative to synthetic alternatives.
Rubber commands the established base. The steepest expansion runs through neoprene.
Usage Scenario:
Application context shapes frequency of replenishment, price tolerance, and performance specification intensity.
- Everyday Wear:Steady replenishment cycles in urban commuter populations sustain baseline volume. German municipal gardening subsidies and Netherlands cycling culture generate above-average household penetration distinct from episodic purchase patterns.
- Outdoor Activities:Hiking and hunting applications demand enhanced outsole traction and ankle support. ISO 20347 certification requirements influence procurement specifications for industrial and recreational crossover segments.
- Gardening:Seasonal demand concentrated in spring planting windows with specification emphasis on chemical resistance and ease of cleaning.
- Festivals:Fashion-forward waterproofing for outdoor music and cultural events in Belgium and the Netherlands presents underpenetrated demand relative to core German market maturity.
Everyday wear anchors volume consistency. Outdoor activities deliver the fastest specification-driven margin expansion.
Customer Type:
Demographic targeting aligns height coverage, aesthetic design, and thermal engineering with distinct purchasing authority patterns.
- Women:Dominant purchasing cohort across adult categories with specification influence extending to children's and men's acquisition decisions. Fashion-forward colorways and mid-calf height preferences concentrate demand in specialty retail channels.
- Adults:Consolidated segment spanning occupational, recreational, and commuter applications with widest price tier exposure from economy PVC to premium neoprene constructions.
- Children:Accelerating regulatory pressure from ECHA SVHC candidate list expansion drives plasticizer reformulation urgency. TOTM and DINCH alternatives replace legacy phthalate compounds under compressed qualification timelines.
- Men:Functional specification emphasis with higher thermal performance requirements in cold-climate occupational procurement.
Women concentrate purchasing authority. Children's segments face the steepest compliance-driven reformulation cycles.
Distribution Channel:
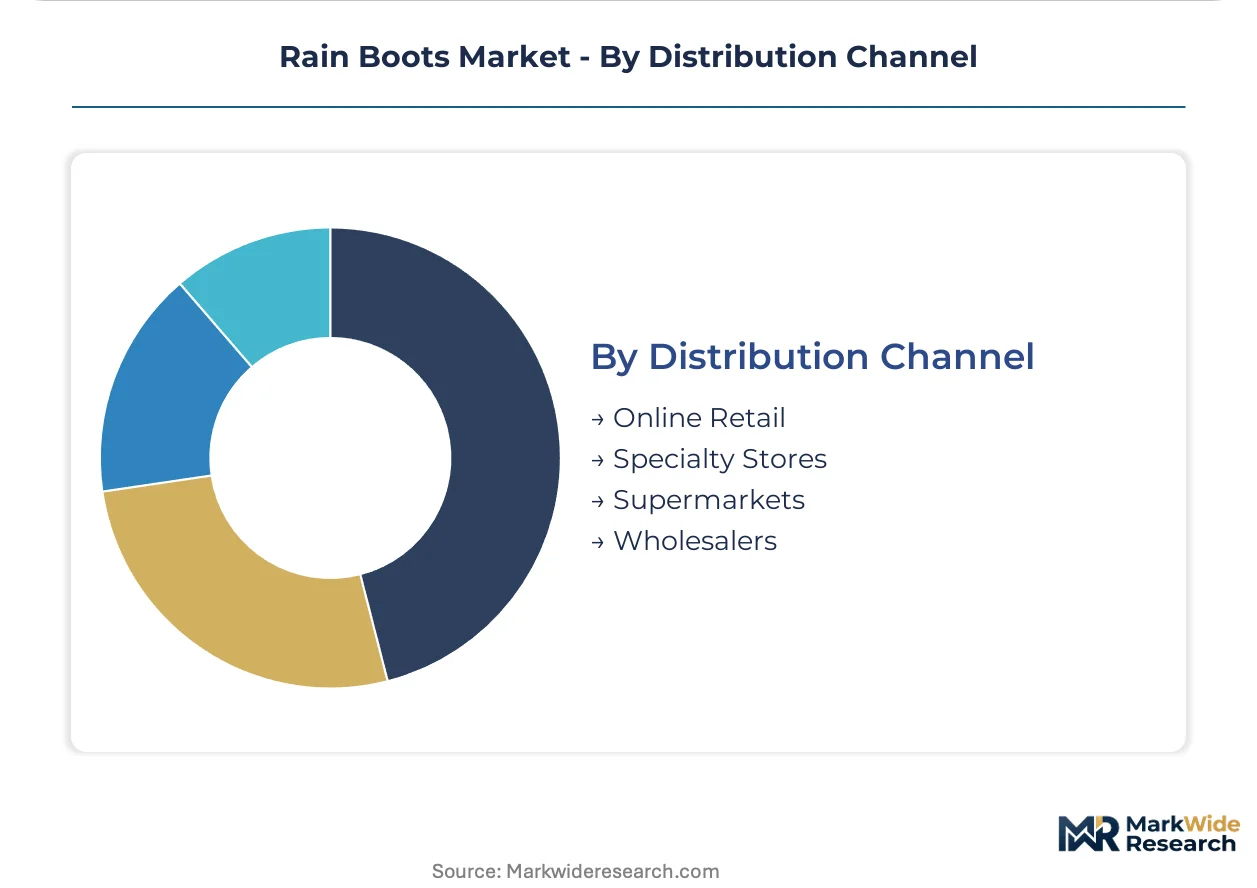
Channel configuration determines margin capture, compound documentation requirements, and speed to market for seasonal collections.
- Specialty Stores:Curated assortment with trained staff enables premium neoprene and technical rubber positioning. Footwear compound documentation and ISO 20347 certification transparency reward manufacturers with specification-driven placement.
- Online Retail:Direct-to-consumer expansion compresses distributor margins while enabling rapid seasonal colorway testing. Size return rates elevate logistics costs relative to brick-and-mortar trial.
- Supermarkets:Volume concentration in economy PVC and basic rubber constructions with limited height variation and seasonal promotional timing.
- Wholesalers:Consolidated tender platforms for municipal and agricultural cooperative procurement in Germany and France with ISO 20347 certification as table-stakes qualification.
Specialty stores defend premium positioning. Online retail captures the fastest channel share expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong and Zhejiang provinces in China host the dominant vulcanization capacity for molded rubber footwear, while downstream demand concentrates in European markets with mature festival and gardening cultures.
Germany
Municipal gardening subsidies sustain above-average household penetration of specialized wet-weather footwear distinct from episodic purchase patterns. REACH compliance requirements under ECHA oversight tighten material composition standards for rubber compounds entering German distribution channels. The Rhine-Ruhr industrial corridor hosts compound formulation facilities serving both domestic procurement and re-export markets.
United States
EPA phthalate oversight under the Toxic Substances Control Act accelerates shifts toward TOTM and DINCH plasticizers in children's footwear segments. Municipal park systems across the Pacific Northwest and Northeast are consolidating seasonal worker footwear purchases through centralized tender platforms. Cold-climate demand in the Upper Midwest and New England sustains specification intensity for thermal retention performance.
France
Agricultural cooperatives in the Loire Valley and Normandy specify rubber compounds for seasonal worker procurement due to proven durability in continuous wet exposure. The national forestry service has adopted direct-to-occupational procurement models that compress distributor margins. Lyon and Grenoble host specialty retailers curating premium neoprene assortments for Alpine recreational applications.
Canada
Quebec's captive manufacturing base insulates North American thermal boot supply against Asian import competition. Health Canada and PMRA oversight aligns with EPA frameworks on plasticizer content while maintaining distinct risk-assessment methodologies. Montreal and Quebec City clusters specialize in cold-climate variant production for sub-zero occupational segments.
Netherlands
Cycling culture generates steady replenishment cycles for urban commuter waterproof footwear distinct from episodic festival demand. Outdoor event programming in Amsterdam and Rotterdam presents underpenetrated demand for fashion-forward waterproofing relative to German market maturity. The Randstad logistics hub enables rapid seasonal colorway distribution across Benelux retail channels.
Rain Boots Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on compound formulation and thermal engineering. The vendor base organizes around three archetypes: vertically integrated rubber processors controlling formulation-to-finished-goods pipelines, regional cold-climate specialists with captive manufacturing in eastern Canada, and neoprene-focused premium tier operators with proprietary insulation technology. Consolidation pressure runs through ISO 20347 certification requirements and direct-to-occupational procurement shifts that reward transparent compound documentation.
Within the vertically integrated tier, Hunter exemplifies European compound-to-retail control, while Kamik anchors North American cold-climate positioning through Quebec-based production. Bogs occupies the premium performance segment with neoprene-lined specialization. These three represent distinct strategic postures: European margin defense through upstream integration, geographic insulation against Asian imports, and thermal technology premiumization respectively.
| Leading Market Players |
|---|
| Muck Boot Company |
| Joules |
| Bogs |
| XTRATUF |
| Le Chameau |
| Kamik |
| Crocs |
| Grundéns |
| Hunter |
| Others |
Value Network & Pricing Analysis
Guangdong and Zhejiang provinces host expanded vulcanization capacity that compresses compound input costs for European and North American distributors, translating upstream scale into downstream pricing power for volume-tier manufacturers while insulating premium neoprene operators from direct cost competition.
Pricing Analysis
REACH compliance dictates the pricing tier structure across transatlantic markets, separating ISO 20347-certified occupational boots from uncertified alternatives and creating specification-driven premiums. Three-tier pricing stratifies across premium neoprene, standard vulcanized rubber, and economy PVC constructions, with certification grade and thermal performance as primary differentiation drivers. Cost compression in the PVC tier is intensifying because EPA phthalate oversight accelerates reformulation spend, while municipal procurement buyers exhibit lowest price sensitivity due to specification-locked tenders.
Supply Chain Analysis
Natural rubber price volatility between Southeast Asian latex plantations and Chinese processing hubs dominates margin risk for compound-dependent manufacturers. Guangdong and Zhejiang provinces anchor vulcanization capacity, drawing from Malaysian and Indonesian latex feedstocks alongside petroleum-derived synthetic alternatives. Single-source vulnerability concentrates in Quebec's captive cold-climate manufacturing base. Distribution runs through specialty retail channels for premium positioning and consolidated tender platforms for occupational procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where early REACH reformulators and ISO 20347 certifiers have built switching-cost moats that compress qualification timelines for late entrants.
For Market Incumbents: Insulate margin position through backward integration into compound formulation and captive neoprene insulation technology development. Accelerate TOTM and DINCH plasticizer adoption ahead of ECHA SVHC expansion timelines. Prioritize Quebec manufacturing redundancy to offset geographic single-point vulnerability against Asian import competition. For New Entrants and Emerging Players: Festival culture in the Netherlands and Belgium represents the most penetrable entry point, with underpenetrated demand for fashion-forward waterproof footwear relative to German market maturity. Direct-to-occupational procurement platforms in France and Germany offer specification-driven contract access for ISO 20347-certified newcomers. Target biobased rubber alternatives from guayule or dandelion latex to differentiate on CSRD-aligned carbon footprint claims. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate footwear portfolios lacking REACH-compliant compound documentation or thermal engineering capabilities. Long-term viability hinges on regulatory entrenchment depth and recyclability infrastructure access. Monitor ECHA SVHC candidate list expansion velocity as the primary inflection signal for reformulation-driven consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Formulation | Hunter's captive control from rubber curing to retail distribution sustains margin defense against Asian cost competition. |
| Biobased Feedstock Adoption | Guayule and dandelion latex trials in Portugal and Italy enable CSRD-compliant carbon footprint claims for premium positioning. |
| ISO 20347 Certification Investment | Germany's federal procurement office and France's national forestry service mandate certified slip-resistance for tender eligibility. |
| Direct-to-Occupational Channel Bypass | Municipal park systems consolidating seasonal worker purchases compress distributor margins while rewarding transparent compound documentation. |
| Quebec Manufacturing Redundancy | Kamik's eastern Canada captive production insulates North American thermal boot supply against Asian import disruption. |
Research Methodology
A standing panel of compound formulation chemists, municipal procurement officers, specialty retail buyers, and agricultural cooperative managers provided ongoing calibration across primary interview rounds, with secondary validation drawing from ECHA SVHC candidate list updates, EPA TSCA Section 6(a) enforcement records, customs trade data for rubber footwear imports, and ISO 20347 certification registries. Bottom-up volume modeling triangulated against top-down market sizing from regional procurement disclosures.
Scenario-bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning material chemistry, usage scenario intensity, customer type purchasing authority, and channel economics. CAGRs derived from regression analysis of historical replenishment cycles and regulatory-driven substitution elasticities, incorporating natural rubber futures volatility and municipal subsidy program stability as industry-specific inputs.
Practitioners should monitor ECHA SVHC expansion velocity, Southeast Asian latex supply disruptions, and municipal procurement platform adoption rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
China Camping Tent Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Camping Cooler Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Global Automatic Mower Market