
 Crash Pads Market | 2026-2036
Crash Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Crash Pads Market Analytics
Aftermarket pad refurbishment and recertification services is reconfiguring margin pools away from one-time equipment sales toward recurring revenue streams. Petzl leverages its alpine heritage to sustain premium positioning in high-density foam systems. Organic Climbing anchors its brand strength through domestic manufacturing and customizable aesthetics. Mad Rock competes aggressively on price while extending distribution through direct-to-gym partnerships.
Crash pads are portable impact-absorption systems constructed from multi-layer polyurethane foam sandwiches with densities ranging from 30 kg/m³ base layers to 80 kg/m³ top sheets, engineered to dissipate kinetic energy during unroped climbing falls. Foam-based configurations dominate unit volume due to proven durability and lower replacement frequency, while inflatable variants represent the fastest-growing product type as gyms seek space-efficient storage solutions. Among end users, training centers command the highest per-facility spend as they require fleet-scale pad deployments with standardized impact ratings.
ASTM International governs fall-height ratings and foam compression set limits in North America, while the EU's CE marking framework under the General Product Safety Directive shapes market access for European distribution. OSHA workplace safety guidelines influence commercial gym liability coverage and pad inspection protocols in the United States. Stakeholders must monitor evolving national climbing gym insurance requirements as underwriters increasingly mandate third-party impact testing documentation.
Market Dynamics
The transition from one-time equipment sales to recurring refurbishment revenue streams is restructuring how crash pad vendors capture lifetime customer value. Indoor climbing gym operators now demand fleet-scale pad deployments with standardized impact ratings, forcing manufacturers to reconfigure production around volume contracts rather than retail channels.
Growth Catalysts
- ASTM foam density standards:Certification requirements for fall-height ratings and compression set limits are accelerating replacement cycles as older pads lose compliance eligibility.
- German climbing gym construction:New facility development rates in Germany exceed most other national markets, concentrating equipment procurement demand in Central Europe.
- Inflatable pad technology:Space-efficient storage solutions are penetrating commercial training centers where floor space constraints limit traditional foam inventory.
Market Restraints
- Polyurethane foam input volatility:Petrochemical feedstock price swings compress margin predictability for multi-layer foam sandwich construction.
- EU CE marking friction:The General Product Safety Directive creates certification timeline uncertainty for North American manufacturers seeking European distribution access.
- Equipment longevity:Foam-based configurations demonstrate proven durability with lower replacement frequency, extending purchase intervals versus consumable alternatives.
Strategic Opportunities
- Aftermarket refurbishment services:Recertification and pad recovery programs open recurring revenue streams beyond initial equipment transactions.
- Direct-to-gym distribution channels:Bypassing traditional retail intermediaries allows manufacturers to capture margin and build facility-level relationships.
- OSHA workplace safety alignment:Commercial gym liability coverage requirements increasingly mandate documented pad inspection protocols, creating compliance-adjacent service demand.
Industry Challenges
- Third-party impact testing documentation:Underwriters now require external certification for insurance coverage, adding cost and timeline complexity to sales cycles.
- Multi-density foam integration:Engineering 30 kg/m³ base layers with 80 kg/m³ top sheets demands specialized lamination expertise that constrains production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crash Pads Market |
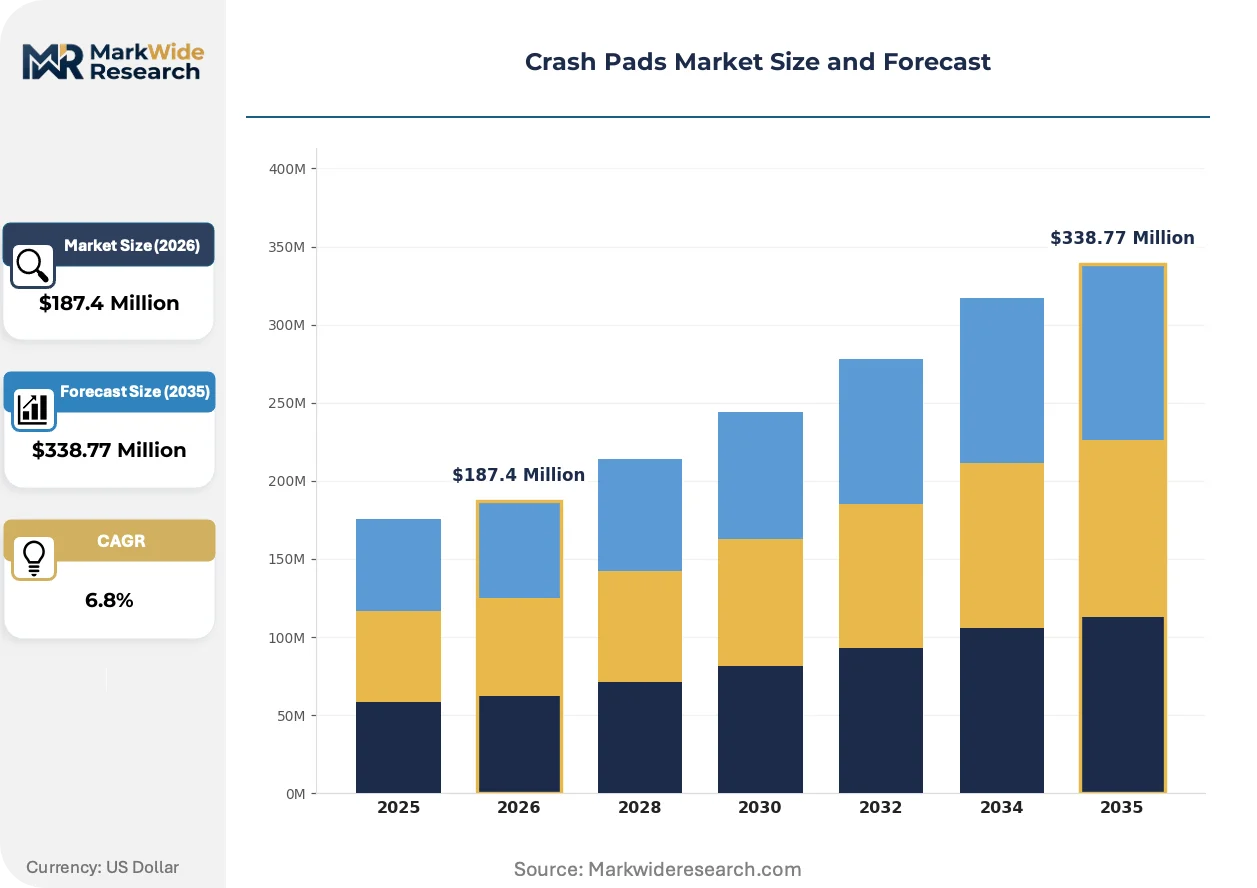
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Foam, Combine, Customized End User: Athletes, Schools, Training Centers, Events Material: Polyurethane, PVC, Rubber, Cotton Application: Gymnastics, Martial Arts, Stunt Performing, Recreational Activities |
| Companies Covered | Black Diamond Equipment, Mad Rock, Metolius Climbing, Organic Climbing, Petzl, Evolv, Prana, Edelrid, Evolution Climbing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crash Pads Market Evolving Landscape
Product architecture is diverging sharply between high-performance foam systems and space-optimized inflatable alternatives. Regulatory certification requirements are tightening simultaneously across North American and European jurisdictions.
Inflatable crash pad systems are collapsing the storage footprint constraints that previously limited gym pad inventory scale. Training centers in urban locations with premium real estate costs are adopting these variants fastest. The technology is collapsing the traditional tradeoff between impact absorption performance and facility space economics.
ASTM International governance over fall-height ratings and foam compression set limits is tightening product qualification requirements in North America. Manufacturers must now maintain continuous testing documentation to retain market access. Commercial gym operators face elevated liability exposure if pad certification lapses, driving demand for compliance-tracking services.
Gym procurement committees now prioritize fleet standardization with documented impact ratings over individual pad aesthetics. This specification-driven purchasing is displacing discretionary retail buying among institutional buyers. The shift is most visible in Germany where climbing gym construction concentrates demand among professional facility operators.
Crash Pads Market Segmentation
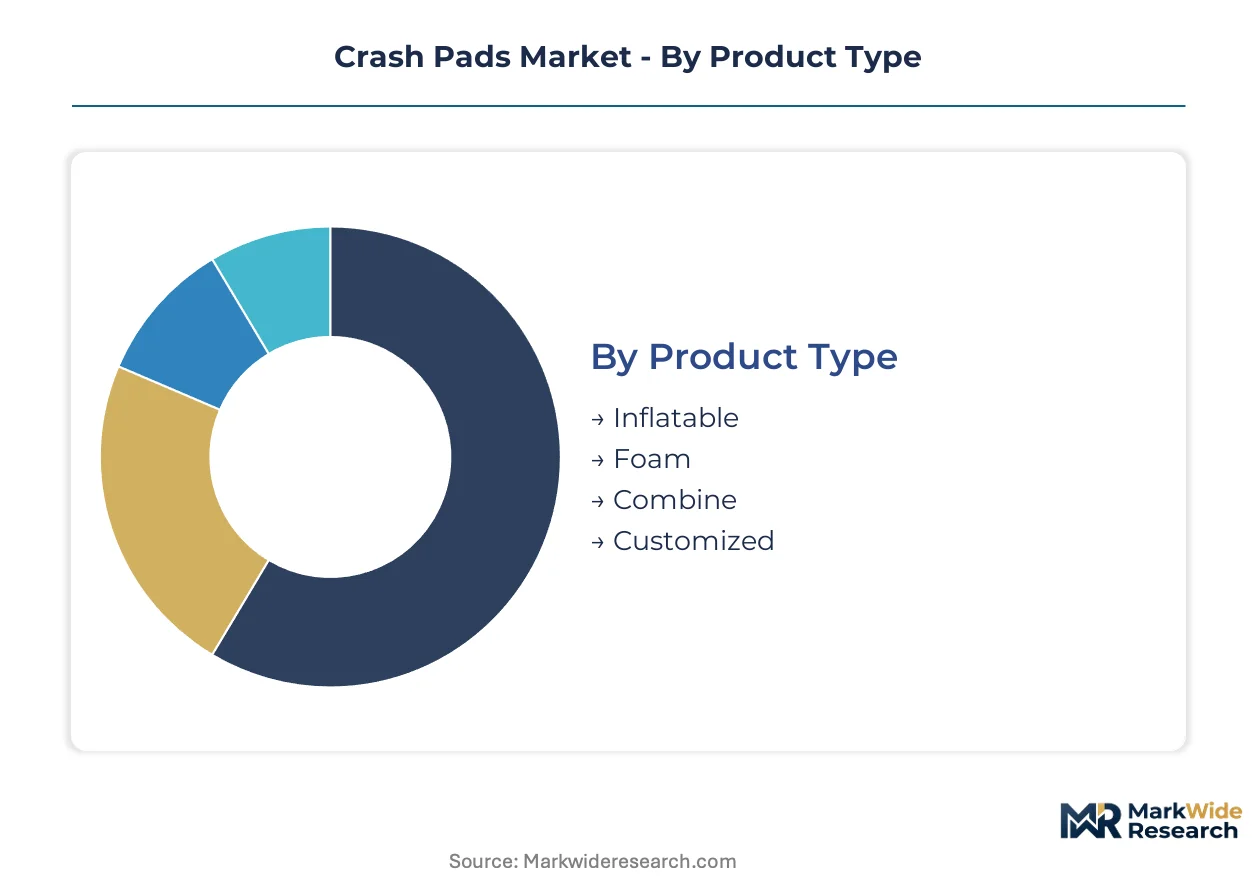
Crash pad procurement patterns diverge sharply across product architectures and end-use contexts. Facility operators prioritize replacement-cycle predictability while retail buyers emphasize portability and storage efficiency.
Product Type:
Foam-based systems turn over on multi-year cycles driven by compression set degradation, while inflatable variants refresh faster as seam integrity becomes the limiting factor.
- Foam:Multi-layer polyurethane sandwiches with 30-80 kg/m³ density gradients deliver proven durability for high-frequency gym use. German climbing facilities deploy these in fleet-scale configurations due to standardized ASTM fall-height compliance requirements and lower per-unit replacement frequency.
- Inflatable:Space-optimized air-cell architectures collapse storage footprints by 60-70% versus foam equivalents. Urban training centers in premium real estate markets adopt these most aggressively where floor space constraints previously limited inventory scale.
- Combine:Hybrid foam-air systems balance impact absorption with packability for mobile route-setting teams.
- Customized:Bespoke dimensions and branding serve event producers and sponsored athlete programs.
Foam configurations anchor the volume base while inflatable systems gain share at the steepest rate.
End User:
Cost tiers separate institutional procurement from individual purchase behavior, with facility-scale buyers commanding pricing leverage unavailable to retail segments.
- Training Centers:Fleet-scale deployments with standardized impact ratings drive the highest per-facility equipment spend. These buyers negotiate volume contracts directly with manufacturers, bypassing retail intermediaries to capture margin and secure compliance documentation for liability coverage.
- Schools:Budget-constrained institutional purchasers prioritize certified durability over performance specifications. Procurement cycles align with fiscal year budgeting, creating predictable seasonal demand concentration.
- Athletes:Individual ownership emphasizes portability and aesthetic customization for personal use.
- Events:Temporary installations require rapid-deployment configurations with minimal setup labor.
Training centers concentrate revenue contribution while schools represent the most price-elastic demand pool.
Material:
Supply concentration in petrochemical feedstocks creates margin volatility that propagates differentially across material categories.
- Polyurethane:Dominates multi-density foam construction with tunable compression characteristics. ASTM compression set limits govern qualification timelines, with density stratification from base to top sheet requiring specialized lamination expertise.
- PVC:Primary substrate for inflatable bladder systems where weld seam integrity determines service life. EU REACH compliance adds certification friction for non-European suppliers.
- Rubber:Natural and synthetic variants serve specialty applications requiring extreme temperature resilience.
- Cotton:Outer shell and padding components for budget-tier and vintage-styled products.
Polyurethane commands the installed base while PVC expands most quickly alongside inflatable product adoption.
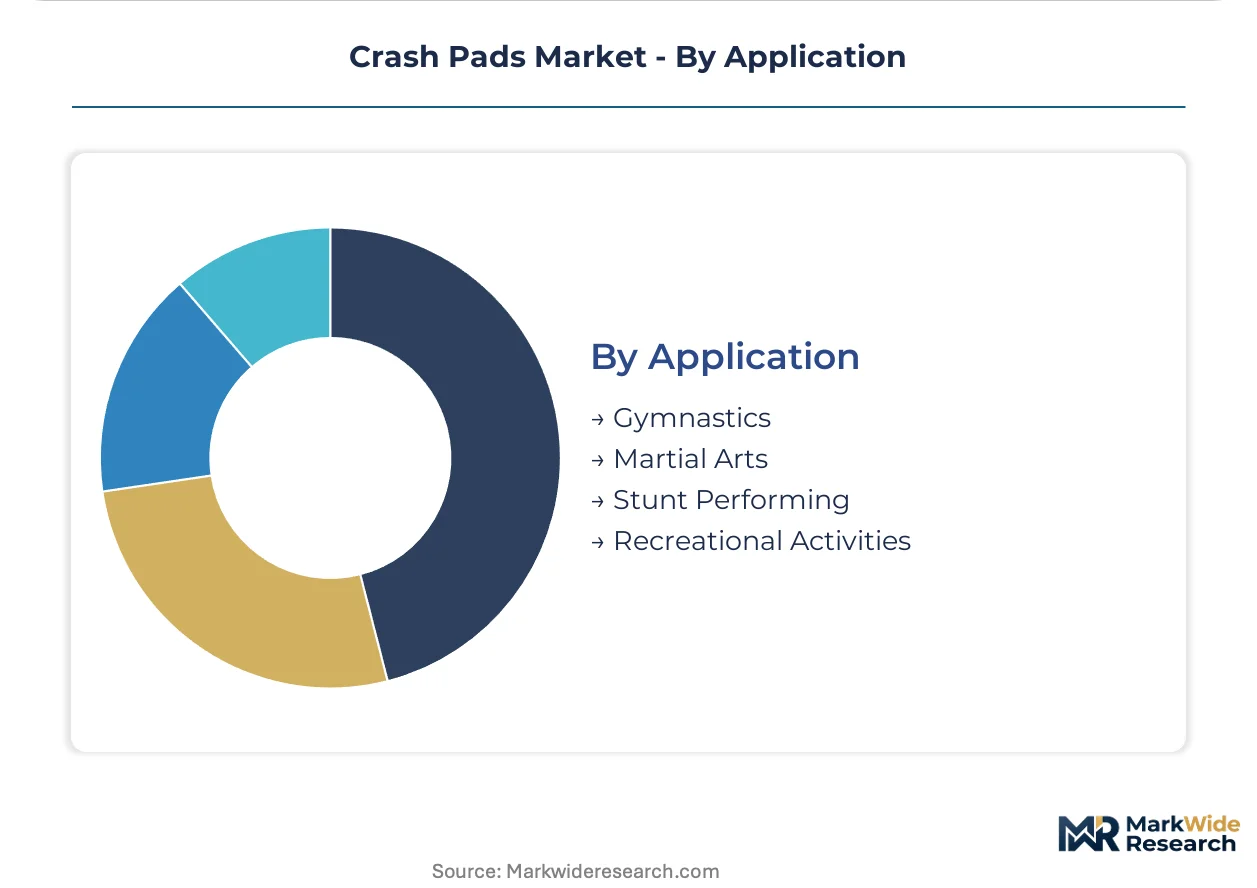
Application:
Maturity gradients separate established competitive disciplines from emerging recreational formats, with regulatory oversight intensity varying accordingly.
- Gymnastics:Federated competition standards mandate precise impact absorption specifications. National governing bodies in Germany and the United States enforce equipment certification protocols that limit supplier qualification.
- Stunt Performing:Film and television production safety coordinators demand documented third-party testing for liability indemnification. OSHA workplace guidelines influence coverage requirements for commercial stunt facilities.
- Martial Arts:Dojo and training hall deployments emphasize surface grip and rapid rebound characteristics for throwing techniques.
- Recreational Activities:Consumer-grade products serve casual climbing walls and adventure park installations with lower certification thresholds.
Gymnastics maintains the most rigid specification environment while recreational applications demonstrate the loosest compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies, with German facility operators absorbing premium-tier certification costs while North American retail buyers drive volume through discount channels.
Germany
Climbing gym construction rates exceed most other national markets, concentrating fleet-scale procurement demand in Munich, Berlin, and Hamburg metropolitan clusters. CE marking under the EU General Product Safety Directive governs all impact-absorbing equipment distribution, with federal state building codes adding layer-specific compliance timelines. The Bavarian Alpine region anchors domestic manufacturing expertise for multi-density foam lamination systems.
United States
OSHA workplace safety guidelines shape commercial gym liability coverage requirements, with underwriters mandating third-party impact testing documentation for policy renewal. ASTM International fall-height ratings and compression set limits accelerate replacement cycles as older pads lose compliance eligibility. The Front Range corridor spanning Colorado and Utah hosts the densest concentration of outdoor retail distribution channels.
Japan
METI industrial standards for recreational safety equipment create certification friction for imported foam systems, favoring domestic assembly partnerships over direct export. JIS-compliant testing protocols govern impact absorption specifications for commercial climbing wall installations. The Kanto region around Tokyo concentrates indoor bouldering facility development with space-constrained urban layouts.
France
Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur combine high outdoor participation rates with emerging indoor gym construction, blending retail and institutional demand pools. ANSM notification requirements intersect with EU CE marking for products claiming medical-grade impact protection. The Chamonix valley cluster sustains alpine heritage brands with technical credibility in high-performance foam systems.
Canada
Health Canada product safety guidelines align with ASTM standards while adding provincial workplace compensation board requirements for commercial gym operators. The Pacific Northwest corridor spanning British Columbia into Washington State shares cross-border distribution infrastructure and climber demographics. Vancouver and Toronto metropolitan areas drive training center construction with standardized fleet procurement specifications.
Crash Pads Market Competitive Landscape
Alpine heritage specialists and domestic manufacturing anchors split the market into distinct credibility vectors. The vendor base concentrates around three strategic archetypes: certification-driven premium positioned players, customization-focused regional fabricators, and volume-scale direct distributors. Consolidation pressure remains muted as brand authenticity and manufacturing proximity sustain fragmentation. Competitive moves center on direct-to-gym distribution partnerships and aftermarket refurbishment service launches.
Among alpine heritage specialists, Petzl and Edelrid exemplify technical credibility positioning through multi-decade climbing equipment lineages. Organic Climbing and Mad Rock occupy contrasting positions within the North American fabricator tier, with the former representing domestic manufacturing authenticity and the latter anchoring aggressive price-positioning strategies. Black Diamond Equipment sits at the scale-driven intersection of retail distribution breadth and institutional contract capability.
| Leading Market Players |
|---|
| Black Diamond Equipment |
| Mad Rock |
| Metolius Climbing |
| Organic Climbing |
| Petzl |
| Evolv |
| Prana |
| Edelrid |
| Evolution Climbing |
| Others |
Value Network & Pricing Analysis
The Bavarian Alpine region anchors multi-density foam lamination capacity for European crash pad supply, with Munich-area fabricators translating specialized manufacturing proximity into pricing leverage over gym operators requiring ASTM-compliant fleet deployments. This geographic concentration enables premium capture for certification-grade products while compressing margins on standardized configurations sourced through distributed retail channels.
Pricing Analysis
Aftermarket refurbishment and recertification services now drive lifetime value capture beyond initial equipment transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale, with training center fleet contracts commanding favorable unit economics versus individual retail purchases. Cost compression in economy tiers is intensifying because polyurethane foam feedstock volatility propagates through multi-layer sandwich construction. Schools demonstrate the highest price elasticity among buyer segments, while German climbing gym operators absorb premium-tier certification costs with minimal volume pushback.
Supply Chain Analysis
Contract manufacturing for inflatable bladder systems concentrates among Taiwanese and South Korean electronics-industry suppliers repurposing PVC welding expertise from consumer goods production. Multi-density polyurethane foam draws from German and US petrochemical feedstock bases, with specialized lamination equipment resting on Bavarian and Colorado manufacturing clusters. Single-source vulnerability in 80 kg/m³ top sheet production creates bottleneck exposure for premium-tier pad assembly. Distribution runs through direct-to-gym partnerships for institutional buyers and outdoor specialty retail for individual athletes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crash pad market economics increasingly favor service-attach revenue models, with refurbishment and recertification programs expanding faster than foam-based hardware unit sales as compliance documentation becomes mandatory for commercial gym liability coverage.
For Market Incumbents:Insulate premium positioning by deepening captive supply of high-density foam lamination capacity in the Bavarian manufacturing cluster, while accelerating certification-tracking software development to capture recurring compliance service revenue. Inflatable pad technology from Asian contract manufacturers threatens to commoditize storage-optimized segments if domestic players cede space-efficient product architecture.
For New Entrants and Emerging Players:Japanese metropolitan bouldering facilities present underpenetrated demand for space-optimized inflatable systems where METI certification friction has slowed incumbent expansion. Target Kanto-region training centers with JIS-compliant testing documentation bundled into direct procurement relationships, bypassing the import partnership structures that constrain established European brands.
For Investors and Strategic Acquirers:Long-term, this sits as a recurring-revenue infrastructure play because climbing gym operator liability requirements are hardening pad inspection and recertification into mandatory ongoing expenditures rather than discretionary replacement cycles. Acquisition candidates should demonstrate established third-party testing documentation relationships and refurbishment service capabilities. Monitor German federal state building code amendments for early signals of accelerated compliance timeline tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Gym Distribution Partnership | Bypasses retail margin extraction while securing facility-level compliance documentation relationships. |
| Aftermarket Refurbishment Service Launch | Captures recurring revenue from ASTM compression set recertification requirements. |
| Inflatable Product Architecture Investment | Addresses urban training center space constraints with 60-70% storage footprint reduction. |
| Third-Party Testing Documentation Integration | Satisfies underwriter mandates for commercial gym liability policy renewal. |
| Domestic Manufacturing Proximity Expansion | Reduces EU CE marking timeline friction for North American producers seeking European access. |
Research Methodology
Cross-validation between primary interviews with climbing gym operators, foam manufacturing engineers, and commercial insurance underwriters anchors the qualitative findings, while secondary validation draws from ASTM International technical standards, EU General Product Safety Directive implementation guidance, and OSHA workplace safety guideline documentation. Bottom-up facility deployment estimates triangulate against top-down petrochemical feedstock consumption patterns across the analysis window.
Calibration against historical replacement cycle data and certification lapse rates shapes the projection framework across product type, end user tier, material substrate, and geographic regulatory cluster dimensions. CAGRs derive from segment-level growth rate reconciliation with macroeconomic climbing participation surveys and gym construction permit filings. Modeled inputs include polyurethane density stratification cost curves and inflatable bladder seam degradation failure distributions.
Practitioners should monitor ASTM foam compression set limit amendments and EU CE marking procedural revisions for early signals requiring forecast adjustment. Cross-checking against regional climbing gym insurance underwriting rate filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
China Camping Tent Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Singapore Camping Equipment Market