
 New Zealand Camping Equipment Market | 2026-2036
New Zealand Camping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Camping Equipment Market Insights
Multi-source procurement among specialty retailers is rebalancing toward direct manufacturer relationships as brands seek margin recovery. Zempire Camping Equipment leverages its domestic manufacturing footprint to control lead times for tent and shelter lines. Johnson Outdoors Inc. anchors its position through R&D intensity in lightweight thermal materials. KMD Brands competes across price tiers via its dual retail and wholesale channel structure.
Camping equipment encompasses portable shelter systems, sleep systems, load-bearing packs, and backcountry cooking apparatus engineered to withstand ultraviolet degradation, moisture ingress, and wind loads exceeding 80 km/h. Products serve recreational users accessing New Zealand's conservation estate and commercial operators running multi-day guided experiences. Tents and sleeping bags dominate volume, with premium four-season shelters capturing the deepest margin pools as alpine tourism expands. Backpacks and cooking gear are growing fastest among ultralight backpackers reducing base weights below seven kilograms. Distribution through specialty shops sustains higher price realization than mass retail, where budget and mid-range lines face compression.
WorkSafe New Zealand enforces product safety standards for gas-powered cooking equipment used in backcountry huts and campsites. The country's Building Act overlaps with commercial campground infrastructure, influencing permanent structure specifications. Biosecurity regulations under the Ministry for Primary Industries restrict certain imported fabrics and untreated natural materials. Stakeholders must monitor evolving fire safety certifications and biosecurity rule changes that could alter sourcing geographies or require reformulation of existing product lines.
Market Dynamics
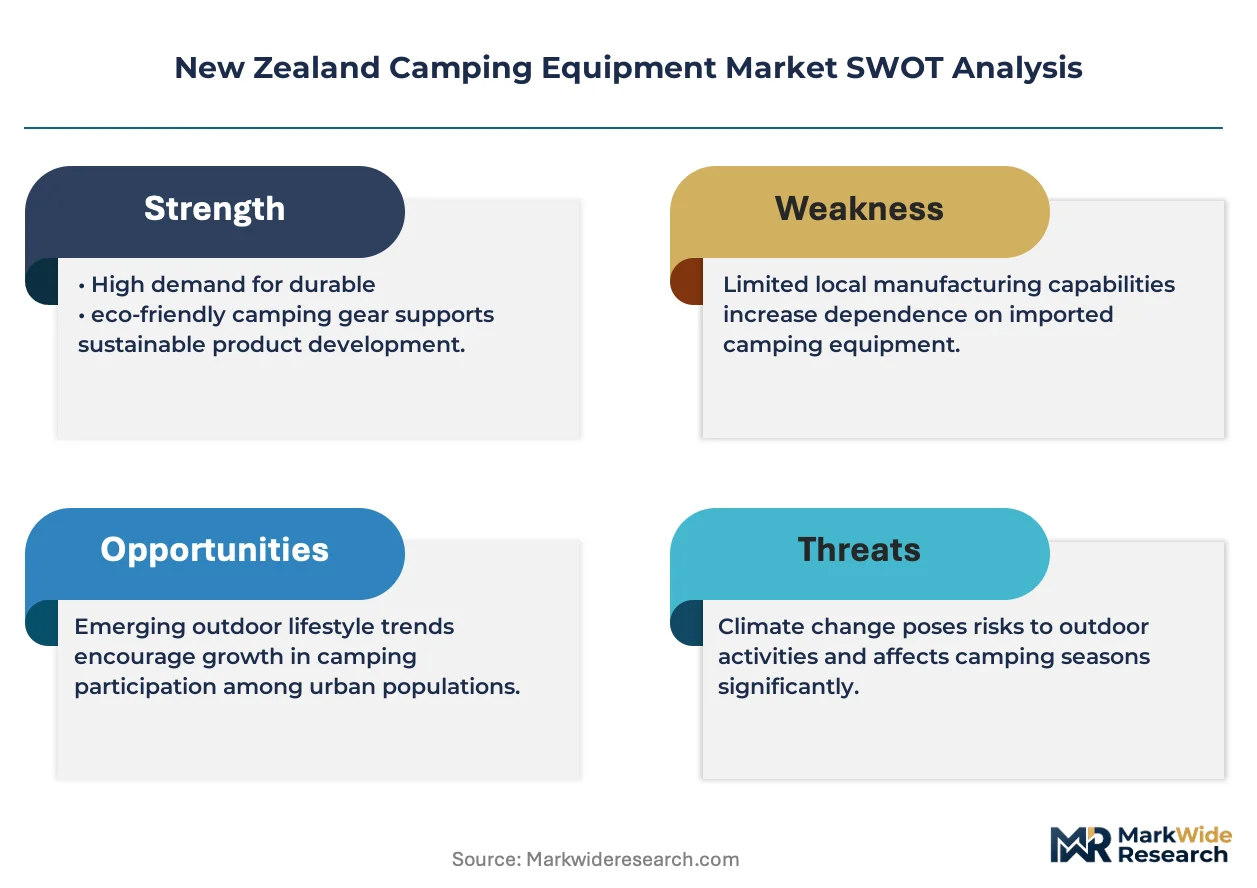
WorkSafe New Zealand's flame-resistant fabric mandates and biosecurity screening under the Ministry for Primary Industries are compressing supplier lead times while elevating compliance costs for tent and shelter imports.
Growth Catalysts
- Alpine Tourism Infrastructure:Queenstown-Lakes district operators are scaling multi-day guided experiences, driving premium four-season shelter procurement from domestic manufacturers.
- WorkSafe NZ Safety Codes:Mandatory certification for gas-powered cooking equipment in backcountry huts is standardizing product specifications and locking in replacement cycles.
- Ultralight Material Adoption:Dyneema composite fabrics and titanium cookware are penetrating the South Island tramping community, expanding addressable spend per trip.
Market Restraints
- Biosecurity Import Friction:Ministry for Primary Industries screening of untreated natural fibers and certain synthetic coatings delays container clearance at Auckland and Tauranga ports.
- Currency-Driven Input Volatility:New Zealand dollar fluctuations against USD and CNY denominated technical textiles compress landed margins for retailers without hedging programs.
- Domestic Manufacturing Scale Ceiling:Zempire's Auckland facility and limited contract sewing capacity constrain rapid volume response to seasonal demand spikes.
Strategic Opportunities
- Conservation Estate Access Expansion:Department of Conservation hut network upgrades create commercial operator demand for durable sleep systems and weather-rated shelters.
- Direct-to-Operator Channels:Bypassing specialty retail to contract with guided experience providers captures recurring bulk procurement and reduces margin leakage.
- Carbon-Neutral Product Lines:Anticipated tightening of New Zealand's emissions trading scheme coverage positions bio-based insulation and recycled shell fabrics for premium positioning.
Industry Challenges
- Fire Safety Certification Timelines:WorkSafe New Zealand's evolving tent fabric flammability standards require reformulation and retesting, extending new product introduction cycles.
- Specialized Repair Technician Scarcity:Technical outdoor gear repair skills concentrate in Christchurch and Wellington, leaving regional retailers dependent on Auckland-based service centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Camping Equipment Market |
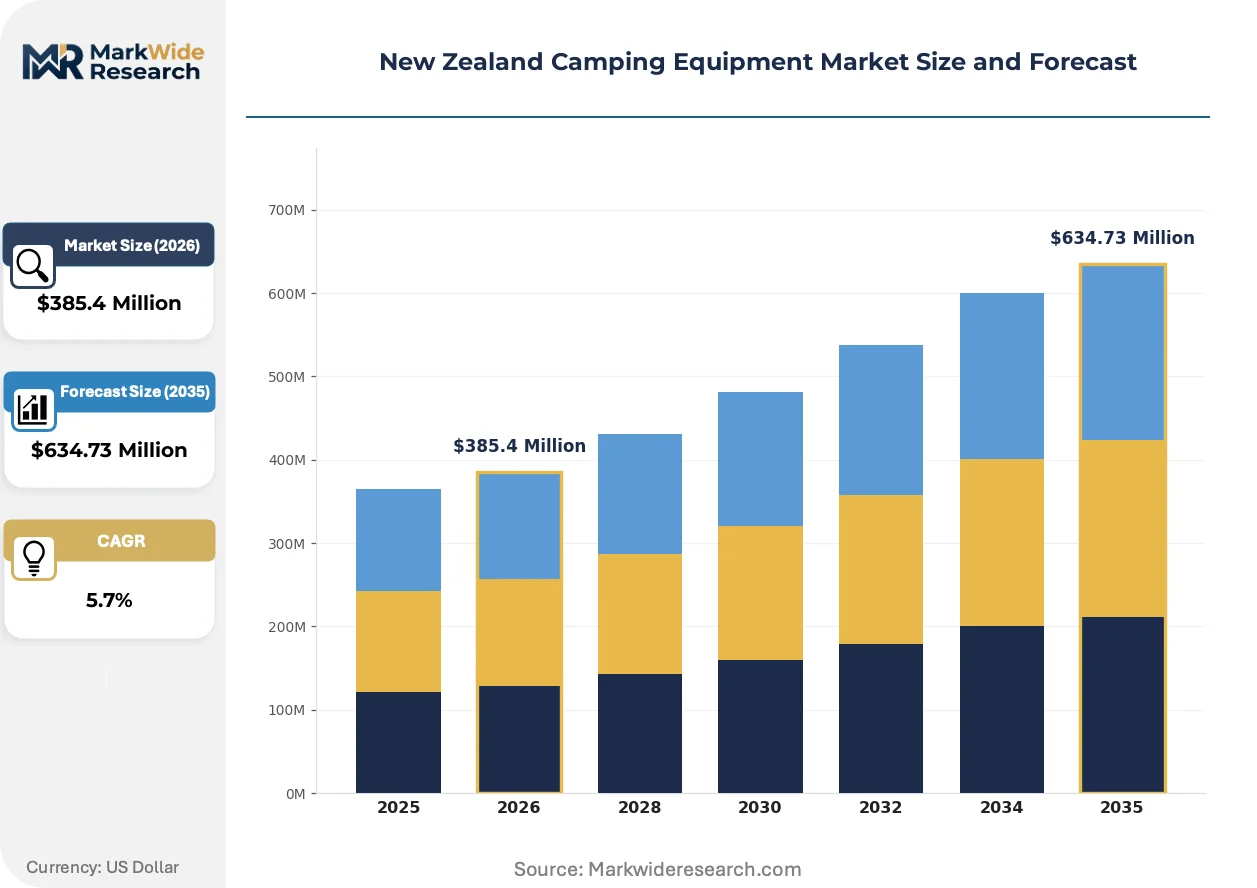
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $634.73 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Sleeping Bags, Backpacks, Cooking Gear End User: Outdoor Enthusiasts, Families, Backpackers, Casual Campers Distribution Channel: Retail Stores, Online Sales, Specialty Shops, Wholesale Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Zempire Camping Equipment, Johnson Outdoors Inc., Briscoe Group Limited, Nemo Equipment Inc., Newell Brands Inc., Tahua Group, MountCraft, Oase Outdoors ApS, KMD Brands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Camping Equipment Market Trends and Innovations
Electrification of backcountry power systems and synthetic insulation advances are reshaping equipment specifications, while regulatory pressure on fire safety and biosecurity is filtering supplier bases.
Solar-integrated battery packs and USB-rechargeable heating elements are electrifying sleep system design, with alpine guide services adopting these systems for client safety protocols. The technology compresses demand for traditional gas canister dependency while opening premium price tiers for integrated power-thermal bundles.
WorkSafe New Zealand's pending updates to portable gas appliance standards are forcing preemptive redesign of stove and lantern product lines. Manufacturers with existing Auckland testing relationships are accelerating certification submissions ahead of rule finalization, locking in compliant inventory positions.
Specialty retailers are ceding ground to direct manufacturer relationships as margin recovery becomes paramount. Domestic operators running guided wilderness experiences now negotiate annual frame contracts for tent, sleep, and cooking system refreshes, concentrating procurement volume with fewer supplier relationships and bypassing traditional wholesale markups in the South Island alpine corridor.
New Zealand Camping Equipment Market Segmentation
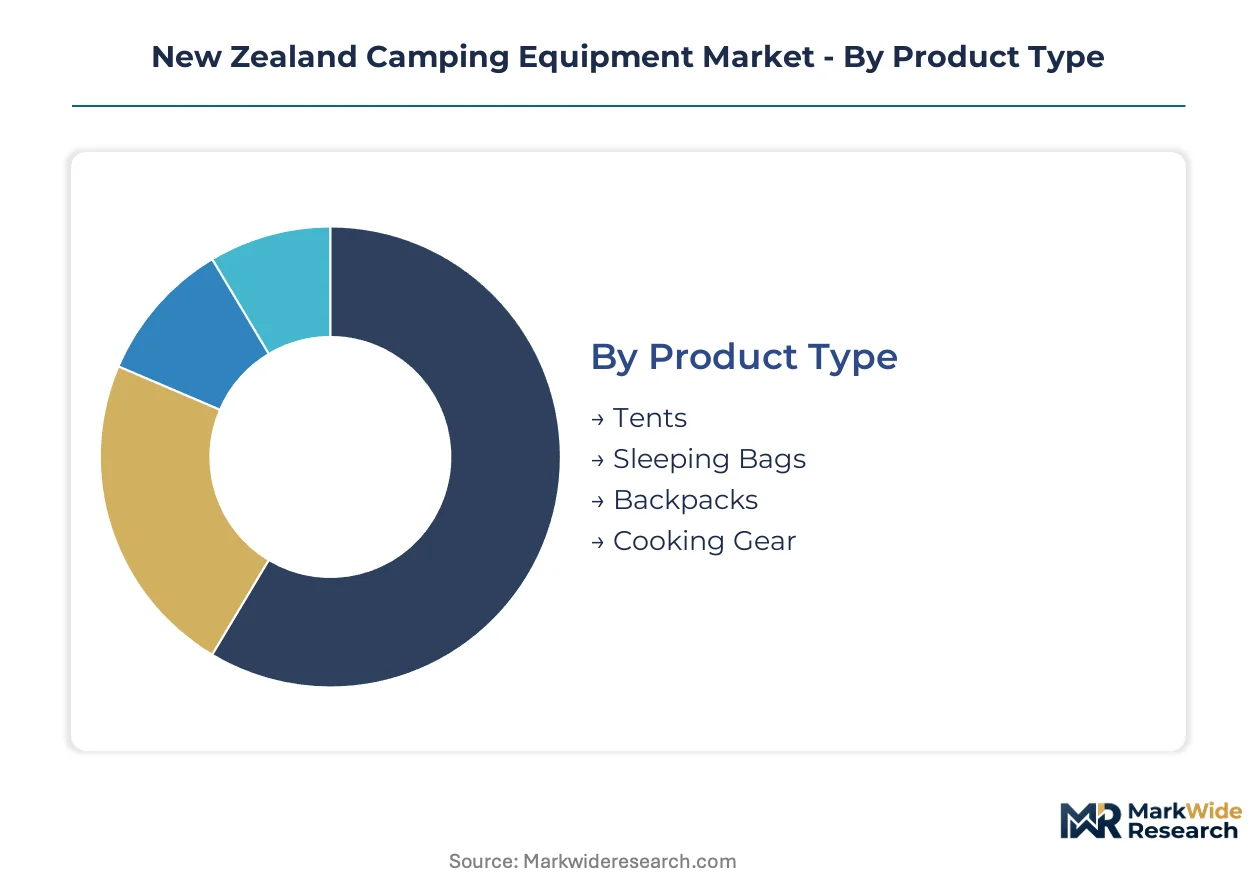
New Zealand's camping equipment segmentation reflects distinct procurement patterns across recreational and commercial use cases. Equipment specifications diverge sharply between Department of Conservation hut network users and guided alpine operators running multi-day experiences.
Product Type:
Standalone shelter and sleep systems dominate procurement volumes, while cooking apparatus increasingly embeds into integrated backcountry kits.
- Tents:Four-season alpine shelters with flame-resistant fabrics meeting WorkSafe New Zealand codes command the deepest margin pools. Queenstown-Lakes district operators drive premium procurement for guided experiences.
- Sleeping Bags:Synthetic and down-filled mummy bags rated to sub-zero temperatures serve the South Island tramping community. Ultralight backpackers are compressing base weights below seven kilograms.
- Backpacks:Load-bearing packs engineered for 80 km/h wind resistance and moisture ingress protection.
- Cooking Gear:Gas-powered systems certified for backcountry hut use under evolving WorkSafe standards.
Tents lead volumes today; cooking gear is gaining share fastest as electrification reshapes backcountry power systems.
End User:
Customer archetypes stratify by trip duration, technical terrain exposure, and gear replacement frequency.
- Outdoor Enthusiasts:Technical users accessing conservation estate with high-frequency equipment turnover and brand loyalty to domestic manufacturers.
- Families:Car-camping segment prioritizing spacious shelters and durability over weight optimization, concentrated in North Island holiday parks.
- Backpackers:International and domestic trampers traversing Te Araroa trail demand ultralight Dyneema composites and titanium cookware.
- Casual Campers:Infrequent users purchasing entry-level equipment through mass retail channels with compressed margin profiles.
Outdoor enthusiasts anchor current revenue; backpackers are expanding most quickly as alpine tourism infrastructure scales.
Distribution Channel:
Channel economics diverge between margin-preserving specialty retail and volume-driving direct manufacturer relationships.
- Retail Stores:Mass-market outlets moving budget and mid-range lines with higher inventory velocity but lower price realization per unit.
- Online Sales:Direct-to-consumer platforms capturing international backpacker demand and regional New Zealand customers outside Auckland-Wellington-Christchurch corridors.
- Specialty Shops:Technical retailers sustaining premium price realization through staff expertise and fitting services for load-bearing packs.
- Wholesale:Bulk procurement channel serving commercial operators with annual frame contracts, bypassing retail markups.
Specialty shops dominate premium tier sales; wholesale channels are climbing the fastest as guided operators consolidate supplier relationships.
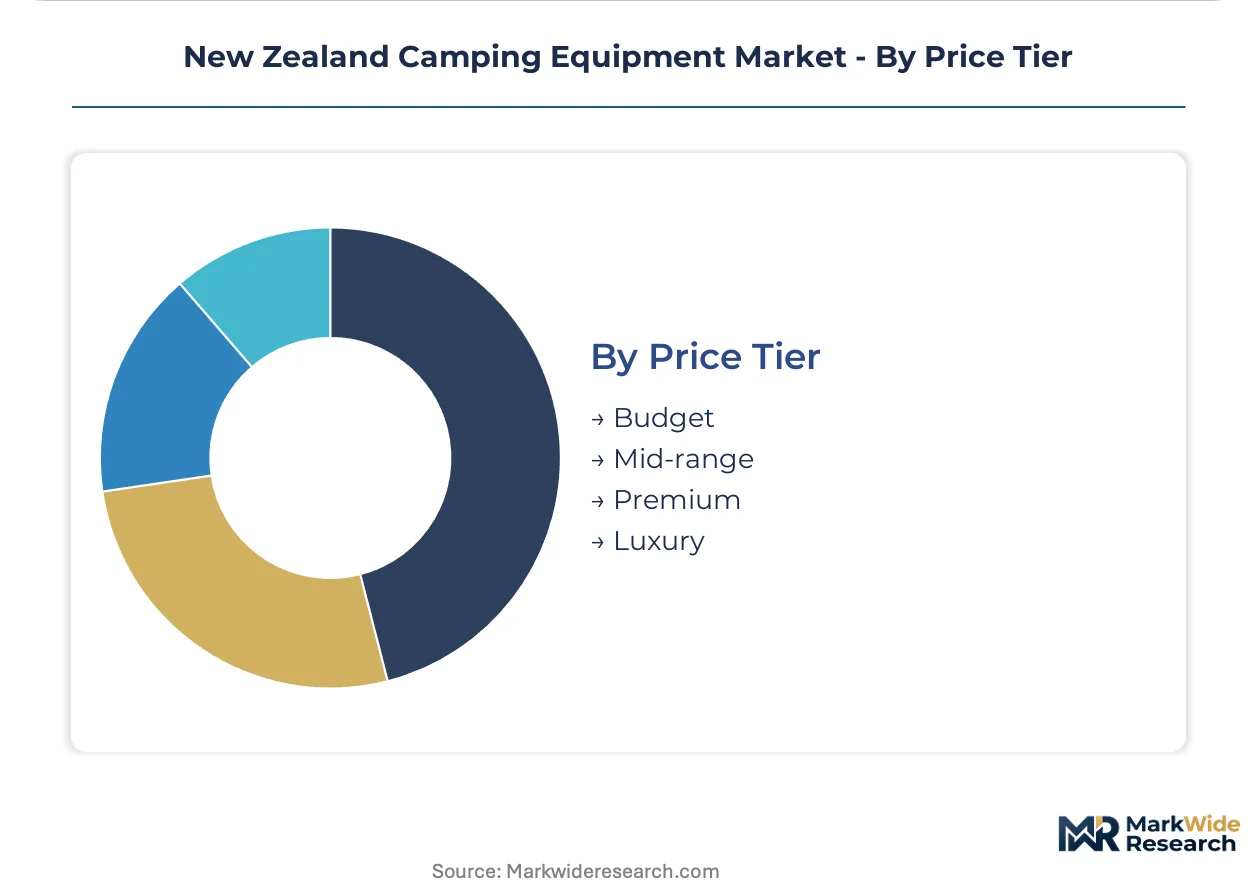
Price Tier:
Pricing stratification maps directly to certification requirements, material specifications, and end-use intensity.
- Budget:Entry-level polyester shelters and synthetic-fill sleep systems serving casual campers with seasonal replacement cycles.
- Mid-range:Technical fabrics and three-season ratings targeting families and occasional trampers balancing performance with cost.
- Premium:Four-season alpine shelters, down-filled sleep systems, and ultralight backpacks with WorkSafe-compliant certifications.
- Luxury:Expedition-grade equipment with integrated power-thermal bundles and carbon-neutral material sourcing for high-net-worth guided clients.
Mid-range captures the broadest customer base; luxury tier shows steepest expansion trajectory as carbon-neutral positioning gains premium traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queenstown-Lakes district anchors equipment demand through alpine tourism infrastructure, while regional procurement patterns diverge across conservation estate access points and commercial operator clusters.
Auckland Region
Domestic manufacturing concentrates in Auckland's industrial corridor, with Zempire's facility controlling lead times for tent and shelter lines. WorkSafe New Zealand certification requirements for flame-resistant fabrics elevate compliance costs for importers clearing goods through Ports of Auckland. The metropolitan retail network serves North Island family camping segments through mass-market and specialty channels.
Canterbury
Christchurch hosts technical repair technician pools supporting South Island equipment servicing, creating regional dependency for warranty fulfillment. The city's specialty retailers sustain premium price realization through staff expertise in load-bearing pack fitting. Biosecurity screening delays at Lyttelton Port compress seasonal inventory windows for untreated natural fiber imports.
Otago
Queenstown-Lakes district operators drive premium four-season shelter procurement for multi-day guided experiences across alpine terrain. Department of Conservation hut network upgrades in Mount Aspiring and Fiordland create commercial demand for durable sleep systems. Local procurement bypasses traditional wholesale markups through direct manufacturer frame contracts.
Wellington Region
The capital's regulatory proximity shapes compliance-focused product development, with manufacturers accelerating WorkSafe certification submissions ahead of pending gas appliance standard updates. Technical outdoor gear repair skills concentrate alongside policy institutions, leaving regional retailers dependent on Auckland-based service centers for complex warranty work.
New Zealand Camping Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ultralight specialization and carbon-neutral positioning. The vendor base stratifies across domestic manufacturers with captive production, multinational outdoor conglomerates with R&D intensity, and specialty importers navigating biosecurity friction. Three archetypes dominate: integrated domestic fabricators controlling lead times, research-heavy multinationals advancing thermal materials, and dual-channel operators spanning retail and wholesale. Competitive moves concentrate on direct-to-operator contracting and preemptive compliance certification ahead of regulatory finalization.
Among New Zealand-based manufacturers, Zempire Camping Equipment and KMD Brands exemplify the integrated domestic archetype, leveraging local production footprints to manage WorkSafe certification timelines and seasonal demand spikes. Johnson Outdoors Inc. represents the multinational R&D-intensive tier, anchoring positioning through materials science investment. These three occupy distinct competitive vectors—captive manufacturing, dual-channel distribution, and technical innovation—without direct segment overlap.
| Leading Market Players |
|---|
| Zempire Camping Equipment |
| Johnson Outdoors Inc. |
| Briscoe Group Limited |
| Nemo Equipment Inc. |
| Newell Brands Inc. |
| Tahua Group |
| MountCraft |
| Oase Outdoors ApS |
| KMD Brands |
| Others |
Pricing and Supply Chain Analysis
Guided alpine operators in the Queenstown-Lakes district concentrate procurement volume through direct manufacturer frame contracts, compressing wholesale markups and anchoring pricing power with domestic fabricators holding WorkSafe certification.
Pricing Analysis
Technical textile costs pass through to landed prices at Auckland and Tauranga ports, with NZD fluctuations against USD and CNY denominated Dyneema composites and flame-resistant coatings compressing margins for unhedged retailers. Pricing stratifies across premium four-season shelters, mid-range three-season family lines, and economy polyester entry tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the budget tier intensifies due to mass retail channel consolidation, while luxury integrated power-thermal bundles show pricing resilience. Casual campers through mass retail exhibit highest price sensitivity; guided operators with annual frame contracts show least.
Supply Chain Analysis
WorkSafe New Zealand's flame-resistant fabric mandates and Ministry for Primary Industries biosecurity screening are reshaping sourcing toward domestic Auckland manufacturing and certified Australian technical textile suppliers. Raw material flows draw from China for synthetic coatings, Vietnam for sewn goods capacity, and Australia for merino insulation and wool-blend fabrics. Single-source vulnerability concentrates in Dyneema composite supply from US and Japanese specialty fiber producers. Distribution runs through specialty retail channels for premium realization, direct-to-operator contracting for commercial volume, and online platforms for regional penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through ultralight material premiums and carbon-neutral product positioning as WorkSafe compliance costs filter out undifferentiated imports.
For Market Incumbents: Deepen captive manufacturing control over flame-resistant fabric finishing to defend against biosecurity-related import delays. Accelerate preemptive WorkSafe certification submissions ahead of pending gas appliance standard updates. Lock in multi-year frame contracts with Queenstown-Lakes guided operators to secure volume visibility and reduce channel margin leakage.
For New Entrants and Emerging Players: Regional family camping segments outside Auckland-Wellington-Christchurch corridors present underserved white-space with limited specialty retail penetration. Carbon-neutral sleep systems targeting high-net-worth guided clients offer the most penetrable premium tier. Pursue direct-to-operator go-to-market positioning with Department of Conservation hut network upgrade contractors.
For Investors and Strategic Acquirers: Domestic outdoor conglomerates with dual retail-wholesale channel structures are the most active acquirer in this space, seeking Auckland-based manufacturing assets with existing WorkSafe testing relationships. Long-term viability hinges on regulatory compliance capability rather than scale alone. Watch for Ministry for Primary Industries biosecurity rule tightening as inflection indicator for domestic manufacturing valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Operator Channel Development | Bypasses wholesale markups and captures recurring bulk procurement from Queenstown-Lakes guided experience providers. |
| Preemptive WorkSafe Certification Investment | Locks in compliant inventory positions ahead of pending portable gas appliance standard finalization. |
| Carbon-Neutral Product Line Launch | Positions bio-based insulation and recycled shell fabrics for premium traction under tightening emissions trading scheme coverage. |
| Ultralight Material Integration | Dyneema composite and titanium cookware adoption expands addressable spend per trip in South Island tramping community. |
| Conservation Estate Access Expansion | Department of Commerce hut network upgrades create commercial operator demand for durable sleep systems. |
Research Methodology
Direct dialogue with equipment procurement managers at guided alpine operators, specialty retail buyers, WorkSafe New Zealand certification officers, and Auckland-based manufacturing operations heads grounded qualitative insights. Secondary validation drew from Department of Conservation infrastructure investment disclosures, Ministry for Primary Industries biosecurity bulletins, WorkSafe regulatory consultation papers, and customs clearance data at Auckland and Tauranga ports. Bottom-up equipment shipment analysis triangulated against top-down tourism expenditure flows.
Top-down macroeconomic anchoring combined with bottom-up segment modeling across product type, end user archetype, distribution channel, and price tier dimensions over the projection horizon. CAGRs derived from equipment replacement cycle analysis, alpine tourism infrastructure investment pipelines, and regulatory-driven standardization effects. Forecast inputs incorporated WorkSafe certification timeline assumptions and biosecurity screening capacity constraints at New Zealand ports.
Underlying measurement precision varies by segment; premium four-season shelter and guided operator procurement data carry tighter precision than casual camper mass retail estimates. Forecasts reflect documented assumptions on regulatory finalization timing and currency trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
Rain Boots Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Picnic Coolers Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
China Camping Tent Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Rooftop Tent Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Camp Fire Tripod Market