
 Natural and Organic Flavors Market | 2026-2036
Natural and Organic Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Natural and Organic Flavors Market Analysis
Beverage production is pivoting toward clean-label formulations as carbonated soft drink makers and functional water brands reformulate with plant-derived flavor systems. Givaudan leverages its botanical extraction platform to supply large beverage multinationals with standardized natural profiles. Symrise anchors its position through deep backward integration into vanilla and citrus supply chains in Madagascar and Brazil. Firmenich differentiates via biotechnology-derived molecules that replicate traditional extraction yields without agricultural volatility.
Natural and organic flavors comprise volatile and non-volatile compounds extracted from plant, animal, or microbial sources through distillation, fermentation, or solvent-free methods, achieving minimum purity thresholds that satisfy regulatory definitions of natural status while delivering reproducible sensory performance in processed foods. Extracts dominate value capture due to premium positioning in organic dairy and confectionery, whereas concentrates represent the fastest-expanding format as beverage producers seek cost-efficient bulk flavor delivery. Essences maintain mature demand in bakery applications where heat stability requirements limit substitution.
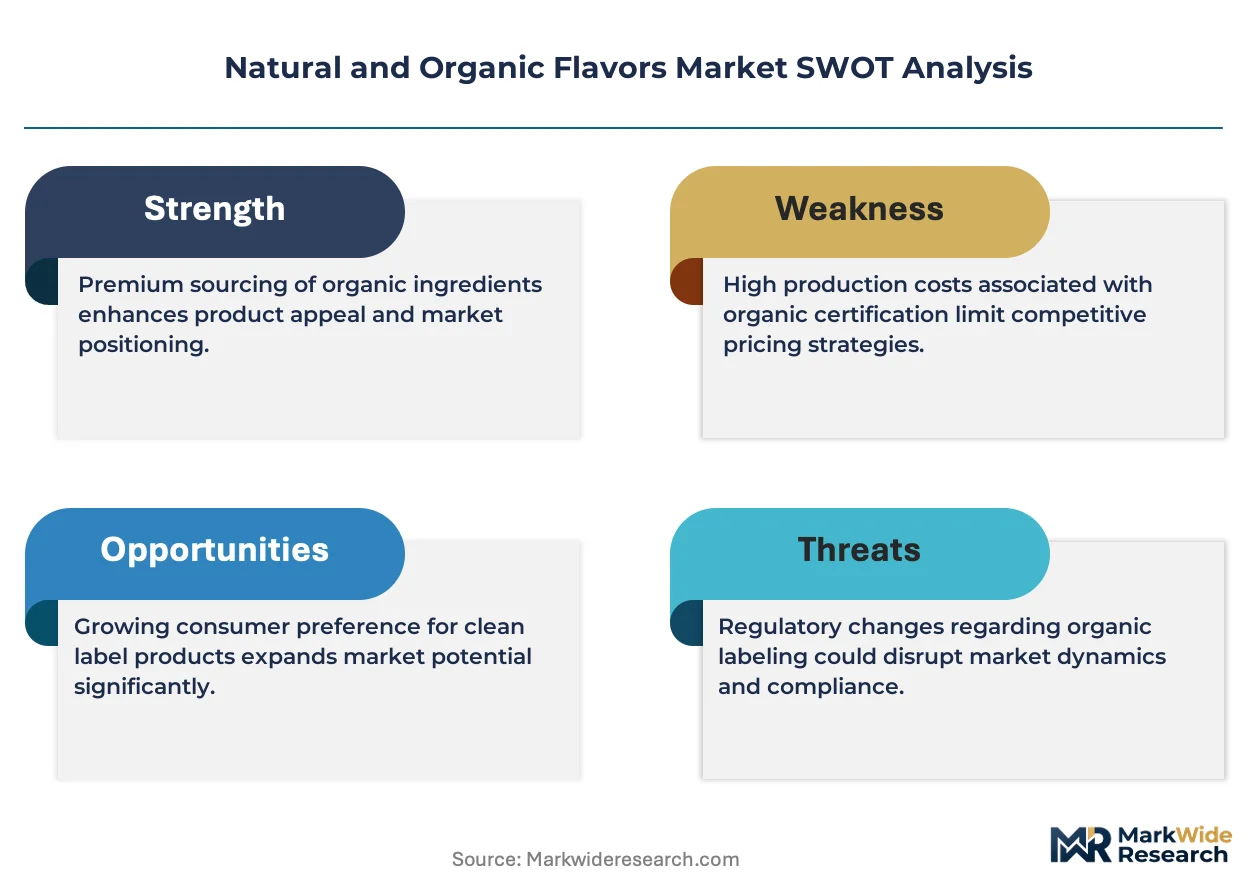
The FDA's natural flavor labeling framework and the EU Green Deal's sustainable sourcing mandates collectively tighten traceability requirements across supply chains, compelling ingredient suppliers to document agricultural provenance and extraction methodology. EFSA's evolving stance on novel botanical extracts creates compliance complexity for European formulators seeking to introduce non-traditional flavor sources. Stakeholders must monitor regulatory divergence between jurisdictions and pre-validate ingredient portfolios against multiple disclosure standards before committing to platform formulations.
Market Dynamics
Beverage manufacturers are accelerating reformulation timelines as clean-label mandates from the EU Green Deal and FDA guidance compress development cycles. This regulatory compression is restructuring supplier relationships and forcing flavor houses to pre-certify ingredient portfolios across multiple jurisdictions.
Growth Catalysts
- EU Green Deal sourcing mandates:The framework's traceability requirements are pulling organic flavor extracts into premium dairy and confectionery formulations across German and French manufacturing.
- Biotechnology platforms:Precision fermentation methods for replicating heat-stable vanilla and citrus profiles are reducing agricultural yield dependency for bakery applications.
- German organic retail channel:Discounters and specialty chains in Germany command premium shelf positioning that rewards certified natural flavor systems with preferential placement.
Market Restraints
- Vanilla bean price volatility:Madagascar's climatic vulnerability and cyclone frequency create input cost instability that compresses margins for extraction-dependent portfolios.
- EFSA novel extract approval timelines:The regulator's evolving stance on non-traditional botanical sources extends time-to-market for innovation pipelines by 18-36 months.
- Natural versus artificial cost gap:Synthetic flavor alternatives maintain 40-60% cost advantages in commodity beverage segments, limiting penetration in price-sensitive categories.
Strategic Opportunities
- India FSSAI organic certification expansion:The regulator's streamlining of import protocols for natural extracts opens formulation partnerships with domestic dairy and snack manufacturers.
- Direct-to-manufacturer digital platforms:B2B marketplaces for certified flavor samples are compressing procurement cycles and reducing distributor markup layers.
- Convergence of extraction and encapsulation:Combined solvent-free extraction with microencapsulation technologies enables heat-stable natural profiles for retort-processed ready meals.
Industry Challenges
- Cross-jurisdiction labeling harmonization:Divergent FDA and EFSA natural flavor definitions force parallel certification tracks that duplicate analytical testing spend.
- Specialized extraction engineering talent:Shortages in supercritical CO2 process design and botanical sourcing expertise constrain capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural and Organic Flavors Market |
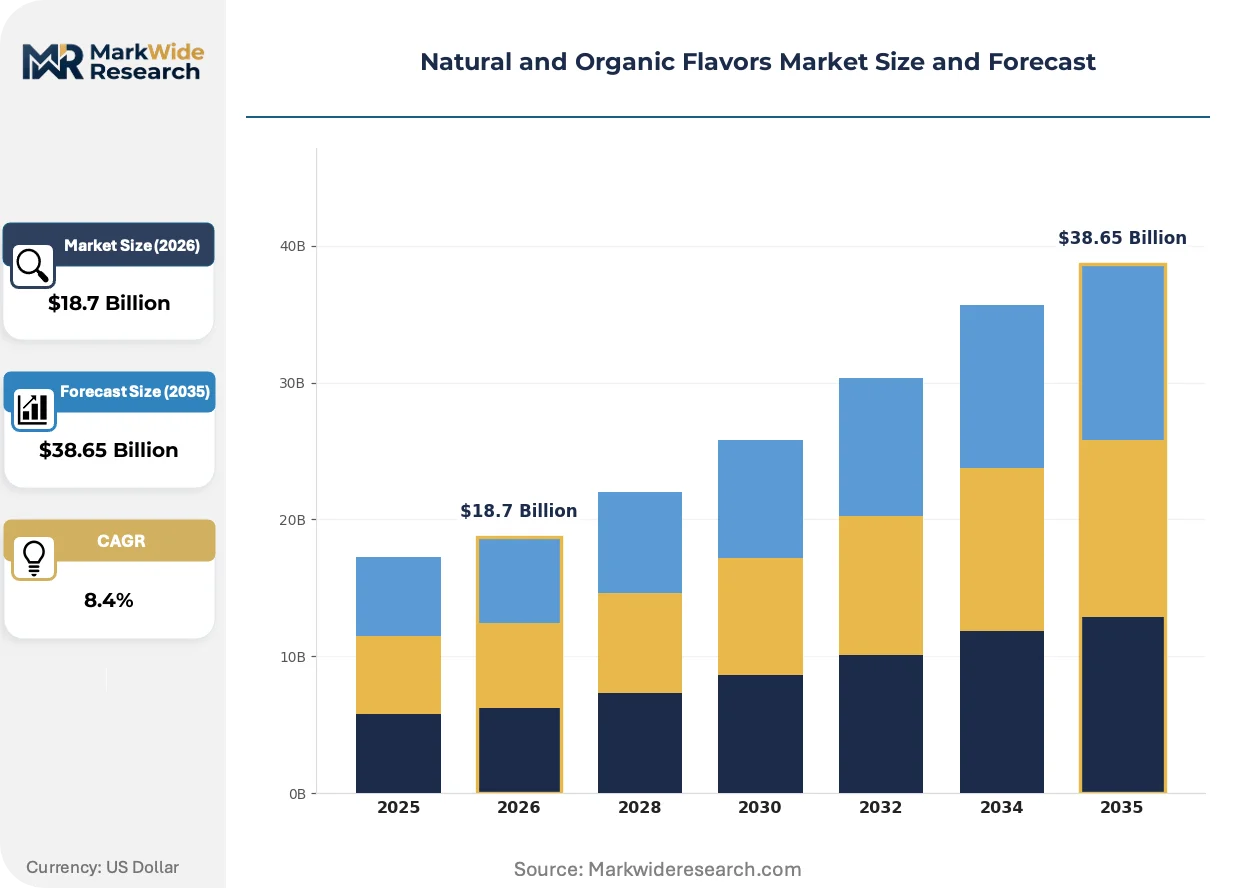
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Essences, Extracts, Infusions Application: Beverages, Bakery, Confectionery, Dairy End User: Food Manufacturers, Beverage Producers, Restaurants, Households Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Givaudan, Firmenich, Symrise, International Flavors & Fragrances, Kerry Group, Sensient Technologies, Robertet, Takasago International Corporation, T. Hasegawa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural and Organic Flavors Market Emerging Trajectories
Flavor technology is pivoting toward reproducible biological production methods that detach sensory performance from agricultural volatility. This shift is compressing traditional supply chain structures and redefining competitive differentiation around biotechnology capabilities rather than raw material access.
Precision fermentation for natural flavor molecules is consolidating the supplier base by enabling standardized output without geographic cultivation constraints. Beverage multinationals in North America and Europe are adopting these biologically-derived profiles at accelerated procurement cycles. The technology is consolidating value capture toward firms with captive biotechnology infrastructure, marginalizing traditional extraction-dependent competitors.
REACH and EU Green Deal combined requirements are mandating full agricultural provenance documentation from field to formulation. European flavor houses must now maintain blockchain-traceable supply chains for all organic-certified inputs. German and French organic food manufacturers face the strictest audit intensity, driving consolidation toward suppliers with pre-validated certification packages.
Direct ingredient sampling platforms are disintermediating traditional distributor networks by enabling manufacturers to test and certify natural flavors through digital procurement portals. Mid-sized beverage and dairy producers in the United States and Germany are adopting these channels to compress supplier qualification timelines. This channel shift is most visible in North America, where regional craft beverage producers bypass legacy distribution tiers entirely.
Natural and Organic Flavors Market Segmentation
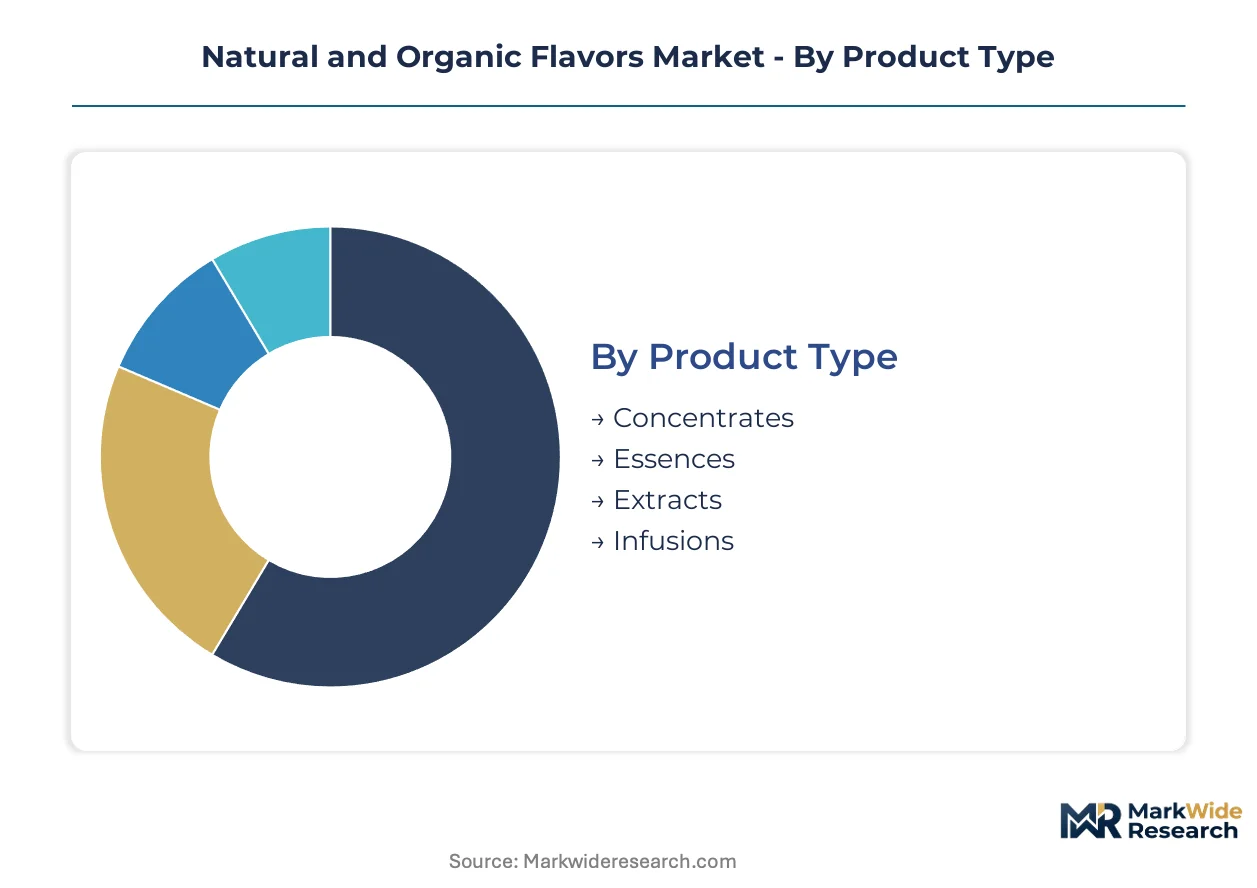
Natural and organic flavors segment across extraction methodology, application intensity, and procurement channel, each dimension carrying distinct margin profiles and certification requirements. Buyer priorities shift from sensory reproducibility in beverage formulations to heat stability in bakery and clean-label compliance in dairy.
Product Type:
Cost tier determines procurement volume and margin structure, with beverage manufacturers optimizing for bulk delivery while premium dairy and confectionery absorb higher per-unit costs for concentrated profiles.
- Concentrates:High-potency flavor systems achieved through vacuum distillation or membrane concentration, reducing transport and storage costs. Beverage producers in Germany and the United States source concentrates at scale to standardize batch-to-batch consistency in carbonated and functional water formulations.
- Extracts:Solvent-based or supercritical CO2-derived compounds capturing complete volatile and non-volatile profiles. Organic-certified extracts command premium positioning in French and German dairy applications where EFSA traceability mandates require documented agricultural provenance.
- Essences:Heat-stable volatile fractions for high-temperature processing.
- Infusions:Cold-processed aqueous extracts preserving delicate aromatic compounds.
Extracts lead on scale; concentrates lead on momentum.
Application:
Application intensity varies by thermal processing requirements and label positioning, with heat-stable formulations commanding engineering premiums and cold-process applications prioritizing freshness markers.
- Beverages:Carbonated soft drinks, functional waters, and ready-to-drink teas require reproducible flavor delivery across variable pH and carbonation levels. FDA natural flavor labeling compliance drives reformulation cycles among North American producers seeking clean-label positioning.
- Dairy:Yogurt, ice cream, and flavored milk applications demand heat-stable profiles that survive pasteurization without degradation. EU Green Deal sourcing mandates pull organic-certified extracts into German and French manufacturing where premium shelf positioning rewards certified inputs.
- Bakery:Oven-stable encapsulation for cookies, breads, and pastries.
- Confectionery:Sugar and chocolate matrices requiring fat-compatible flavor systems.
Beverages lead on scale; dairy leads on momentum.
End User:
Customer type dictates order minimums, technical service intensity, and certification documentation depth, with industrial buyers requiring full regulatory packages and foodservice operators prioritizing speed-to-shelf.
- Food Manufacturers:Snack, sauce, and prepared meal producers sourcing at tonnage scale with embedded quality assurance protocols.
- Beverage Producers:Multinational and regional brands driving standardization requirements for natural flavor profiles across production facilities.
- Restaurants:Commercial kitchens and chain operators seeking consistent flavor delivery in high-volume preparation environments.
- Households:Direct-to-consumer retail purchases for home baking and beverage preparation.
Food manufacturers lead on scale; beverage producers lead on momentum.
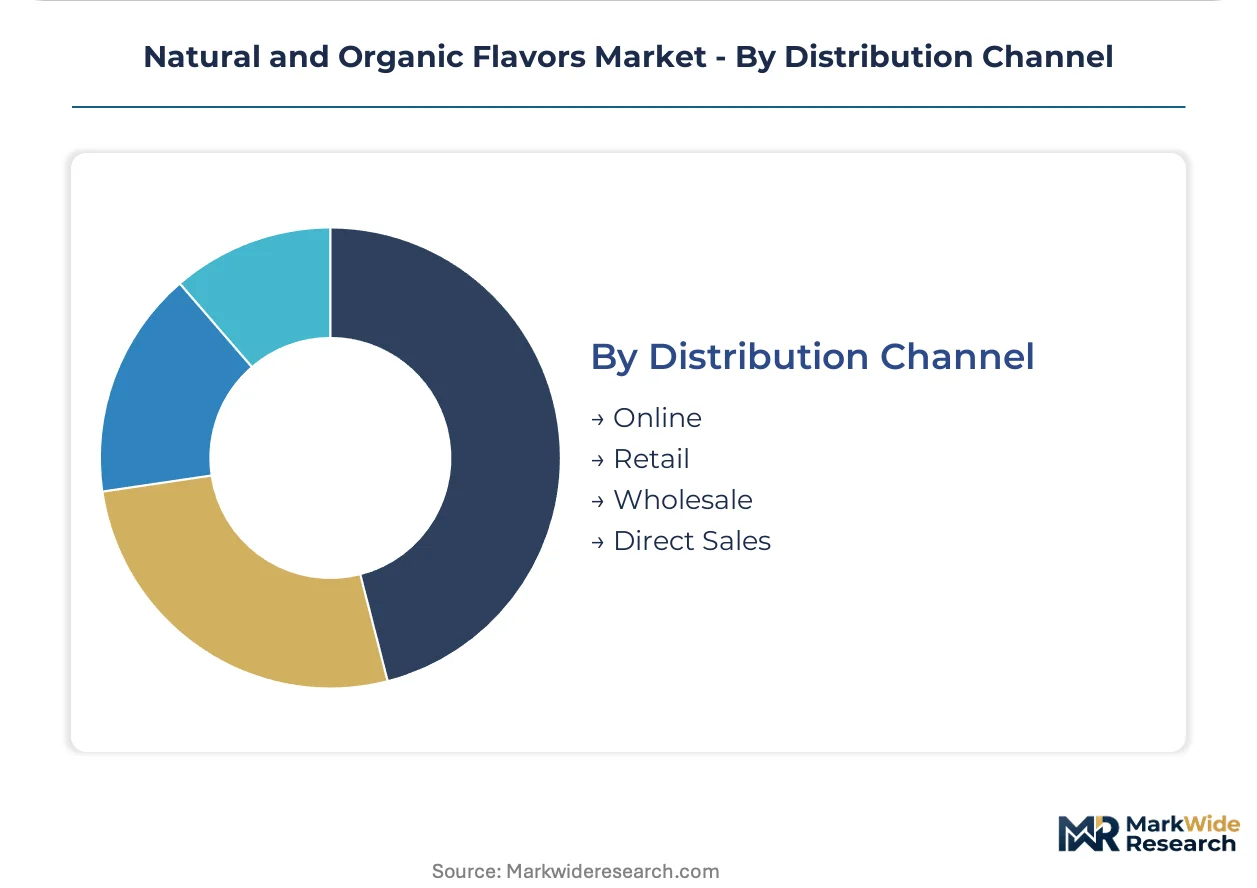
Distribution Channel:
Channel selection determines certification transferability, sampling accessibility, and procurement cycle compression, with digital platforms disintermediating traditional tiered distribution.
- Direct Sales:Flavor houses maintain captive technical service teams for multinational beverage and dairy accounts, embedding formulation scientists within client R&D facilities to accelerate clean-label reformulation timelines.
- Online:Digital sampling platforms enable mid-sized manufacturers to test certified natural flavors without distributor markup, compressing supplier qualification cycles in the United States and Germany.
- Wholesale:Regional distributors aggregating smaller manufacturer orders with consolidated logistics.
- Retail:Specialty ingredient stores and foodservice suppliers serving household and small commercial accounts.
Direct sales lead on scale; online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling natural flavor production toward jurisdictions with streamlined organic certification protocols, as compliance cost gaps between the EU Green Deal framework and emerging-market alternatives reshape supplier location decisions.
United States
Beverage multinationals in Atlanta and Chicago are accelerating clean-label reformulation timelines as FDA natural flavor labeling guidance tightens disclosure requirements. The USDA National Organic Program maintains import parity standards that recognize EU-equivalent certifications, reducing re-certification burdens for German and French extract suppliers. California's organic dairy processors in the Central Valley command premium shelf positioning that rewards documented agricultural provenance.
Germany
Discounters and specialty retail chains in Bavaria and North Rhine-Westphalia anchor European organic flavor demand through preferential shelf placement for certified products. The EU Green Deal's traceability mandates force flavor houses to maintain blockchain-documented supply chains from field to formulation. Hamburg's port infrastructure enables efficient bulk concentrate distribution to Scandinavian and Baltic markets.
France
Premium confectionery manufacturers in Île-de-France and Auvergne-Rhône-Alpes absorb higher per-unit costs for supercritical CO2 extracts to satisfy EFSA documentation requirements. ANSM oversight of novel botanical extracts extends approval timelines for non-traditional flavor sources. Grasse's historical fragrance cluster now hosts biotechnology firms developing precision-fermented flavor molecules.
India
Domestic dairy and snack manufacturers in Maharashtra and Gujarat are expanding procurement of natural extracts as FSSAI streamlines organic import certification protocols. The country's national food regulator has reduced documentation layers for EU- and USDA-certified suppliers. Karnataka's food technology parks near Bangalore attract formulation partnerships with international flavor houses.
Brazil
Citrus and tropical fruit extract producers in São Paulo and Minas Gerais leverage agricultural abundance to supply North American beverage reformulation campaigns. ANVISA's evolving natural ingredient framework creates compliance complexity for European exporters seeking market entry. The São Paulo metropolitan area concentrates flavor application laboratories serving Latin American food manufacturers.
Natural and Organic Flavors Market Vendor Landscape
Backward integration into agricultural supply chains dominates the current landscape as flavor houses secure captive vanilla and citrus sources against climatic volatility. The supplier base concentrates around three strategic tiers: multinational integrated houses with biotechnology platforms, mid-sized extraction specialists with regional certification expertise, and emerging precision-fermentation entrants. Competitive positioning hinges on pre-validated regulatory packages spanning FDA, EFSA, and FSSAI jurisdictions. M&A activity and capacity expansion in supercritical CO2 processing represent the dominant competitive moves.
Within the integrated multinational tier, Givaudan, Firmenich, and Symrise exemplify divergent strategic archetypes. Givaudan anchors the botanical extraction vector through standardized natural profile supply to beverage multinationals. Firmenich occupies the biotechnology-derived positioning, replicating traditional extraction yields without agricultural yield dependency. Symrise exemplifies deep backward integration into geographically specific supply chains. These three Swiss and German-origin entities collectively represent the premium-tier competitive standard against which regional specialists and fermentation entrants measure positioning.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| Symrise |
| International Flavors & Fragrances |
| Kerry Group |
| Sensient Technologies |
| Robertet |
| Takasago International Corporation |
| T. Hasegawa |
| Others |
Supply Flow & Price Mechanics
Beverage multinationals in North America and Europe command pricing leverage through consolidated procurement volumes that compress distributor margins and force tiered certification-based pricing structures across natural flavor suppliers.
Pricing Analysis
Distributor markup layers in traditional wholesale channels face disintermediation pressure from direct-to-manufacturer digital sampling platforms that eliminate intermediary margins. Three-tier pricing structure across premium organic-certified extracts, standard natural concentrates, and economy-grade essences reflects EFSA and FDA certification tiering rather than intrinsic quality gradients. Pricing pressure stems from synthetic flavor alternatives maintaining substantial cost advantages in commodity beverage categories. Small regional craft producers exhibit highest price sensitivity, while multinational dairy manufacturers absorb premium extract costs for clean-label positioning.
Supply Chain Analysis
EU Green Deal domestic-content mandates and traceability requirements are reshaping sourcing patterns toward European-certified extraction facilities with blockchain-documented agricultural provenance. Madagascar, Brazil, and India anchor vanilla and citrus raw material supply, with German and French flavor houses maintaining captive sourcing relationships. Supercritical CO2 extraction equipment and botanical sourcing expertise constitute critical input dependencies. Single-source vulnerability concentrates in Madagascar's climatic-exposed vanilla belt. Distribution runs through Hamburg and Rotterdam port hubs for bulk concentrate redistribution to Scandinavian and Baltic manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural and organic flavors offer geographic-arbitrage value through India's FSSAI certification streamlining, which reduces compliance costs versus EU Green Deal documentation burdens for entrants targeting South Asian dairy and snack formulation partnerships.
For Market Incumbents: Anticipate precision-fermentation entrants displacing traditional extraction-dependent portfolios by securing captive biotechnology infrastructure or partnership access before standardized biological production achieves cost parity. Deepen backward integration into Madagascar vanilla and Brazilian citrus supply chains to buffer agricultural yield volatility. Prioritize pre-validated regulatory packages spanning FDA, EFSA, and FSSAI jurisdictions to defend multinational account relationships against mid-sized certification specialists. For New Entrants and Emerging Players: FSSAI organic certification expansion in India opens a window for formulation partnerships with domestic dairy and snack manufacturers seeking documented natural inputs without EU-equivalent compliance costs. Target mid-sized North American craft beverage producers bypassing legacy distribution tiers through direct digital sampling channels. Lead with heat-stable encapsulation capabilities for retort-processed ready meals where incumbent biotech platforms remain underdeveloped. For Investors and Strategic Acquirers: Food and beverage multinational procurement divisions are the most active acquirer in this space, seeking captive flavor technology to secure clean-label reformulation pipelines. Mid-sized extraction specialists with regional certification expertise and supercritical CO2 processing assets represent prime acquisition targets. Monitor precision-fermentation cost curves as inflection signal for traditional extraction portfolio obsolescence timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Supply Chains | Madagascar vanilla and Brazilian citrus captive sourcing buffers climatic yield volatility for extraction portfolios. |
| Biotechnology Platform Investment | Precision fermentation infrastructure detaches sensory performance from agricultural dependency and geographic cultivation constraints. |
| Pre-Validated Regulatory Certification Packages | Parallel FDA, EFSA, and FSSAI documentation accelerates multinational procurement cycles and defends account relationships. |
| Direct-to-Manufacturer Digital Channel Development | B2B sampling platforms disintermediate distributor markup layers and compress qualification timelines for mid-sized producers. |
| Encapsulation and Heat-Stability Technology Convergence | Combined solvent-free extraction with microencapsulation enables natural profile retention in retort-processed ready meals. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flavor house R&D directors, beverage manufacturer procurement leads, organic certification auditors, supercritical CO2 process engineers, and dairy formulation scientists with secondary validation against EFSA guidance documents, FDA natural flavor labeling frameworks, FSSAI import protocols, EU Green Deal traceability mandates, customs trade data, and flavor industry association technical publications. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Historical reference periods anchored the projection horizon through documented reformulation cycle timing, regulatory implementation phases, and biotechnology platform maturation curves. Segmentation modeling incorporated extraction methodology, application intensity across beverage, dairy, bakery, and confectionery matrices, certification tier, procurement channel structure, and geographic regulatory cluster. CAGRs derived from segment-level growth rate synthesis and end-use demand elasticity analysis. Vanilla bean price volatility indices, organic acreage expansion rates, and precision-fermentation capacity buildout schedules informed industry-specific forecast inputs.
Revisions become necessary when EFSA novel extract approval timelines extend beyond modeled ranges, Madagascar climatic events disrupt vanilla supply, or precision-fermentation cost curves achieve parity with agricultural extraction faster than baseline assumptions. Forecasts reflect documented assumptions about regulatory harmonization progress and biotechnology adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
Flavor Modulators Market
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
Carotenoids Pigment Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Ylang Ylang Extract Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Food Colorants Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Citrus Concentrate Market