
 Beverage Packaging Market | 2026-2036
Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Packaging Market Intelligence
Procurement power among large beverage conglomerates is shifting purchasing decisions toward suppliers with global scale and multi-material capabilities. Ball Corporation leverages its extensive aluminum can manufacturing network to serve major soft drink and beer producers. Amcor plc competes by offering a diversified portfolio of flexible and rigid plastic packaging solutions. Tetra Pak specializes in aseptic carton technology, primarily for dairy and juice products.
Beverage packaging encompasses primary containers designed to hold, protect, and transport liquid consumables. These containers require specific barrier properties against oxygen, moisture, and light to preserve product integrity and extend shelf life. Aluminum cans and PET bottles dominate the market due to their lightweight properties and recyclability, particularly in carbonated drinks. While the alcoholic beverages segment represents a large, mature volume base, the bottled water and functional beverages sectors are showing significant growth.
Regulations from bodies like the US FDA and the European Union's REACH framework dictate material safety standards for food-contact packaging. In parallel, national standards such as China's GB standards for beverage containers influence market access and product design. Future investment decisions will hinge on navigating divergent regional recycling mandates and consumer preferences for sustainable materials.
Market Dynamics
The primary force is the mandate for circularity, driven by regulations like the EU Green Deal, which compels a system-wide shift in material sourcing, design for recyclability, and end-of-life management for all beverage containers.
Growth Catalysts
- Functional Beverage Demand:The expansion of functional and health-oriented drinks creates a need for specialized packaging, including aseptic cartons and smaller, single-serve PET bottles that preserve sensitive ingredients and offer consumer convenience.
- Recycled Content Mandates:Regulations in Europe and certain US states requiring minimum post-consumer recycled content in new bottles are stimulating investment in collection infrastructure and advanced recycling technologies to secure rPET supply.
- Lightweighting Innovations:Continuous advancements in material science and manufacturing processes enable the production of lighter aluminum cans and PET bottles, reducing raw material consumption, lowering transport costs, and improving carbon footprints.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of virgin and recycled raw materials, particularly aluminum ingot and food-grade rPET flakes, create margin pressure and complicate long-term procurement planning for packaging converters.
- Recycling Infrastructure Gaps:The inconsistent availability and quality of post-consumer feedstock in many regions, including parts of North America, hinder manufacturers' ability to meet recycled content goals and scale circular models effectively.
- Material Performance Trade-offs:Incorporating higher percentages of recycled content can sometimes compromise container integrity, clarity, or barrier properties, requiring extensive testing and potential use of performance-enhancing additives that add cost.
Strategic Opportunities
- Bio-based Polymers:The development of commercially viable bioplastics, such as PEF (polyethylene furanoate), presents an opportunity to offer a renewable, high-performance alternative to fossil-fuel-based PET for carbonated and sensitive beverages.
- Smart Packaging Integration:Incorporating digital technologies like QR codes or NFC tags onto packaging allows brands to engage directly with consumers, provide transparency on sourcing, and support deposit-return scheme tracking.
- Emerging Market Expansion:Rapid urbanization and rising disposable incomes in Southeast Asian countries like Vietnam and Indonesia create significant white space for packaged beverages, particularly bottled water and juices.
Industry Challenges
- Capital-Intensive Line Conversion:Adopting new packaging formats, such as tethered caps mandated by the EU's Single-Use Plastics Directive, requires significant capital investment to retool bottling lines and machinery across entire production networks.
- Fragmented Regulatory Compliance:Manufacturers must navigate a complex and divergent web of national and sub-national regulations governing food contact materials, labeling, and recycling, such as the differences between US FDA and China's GB standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Packaging Market |
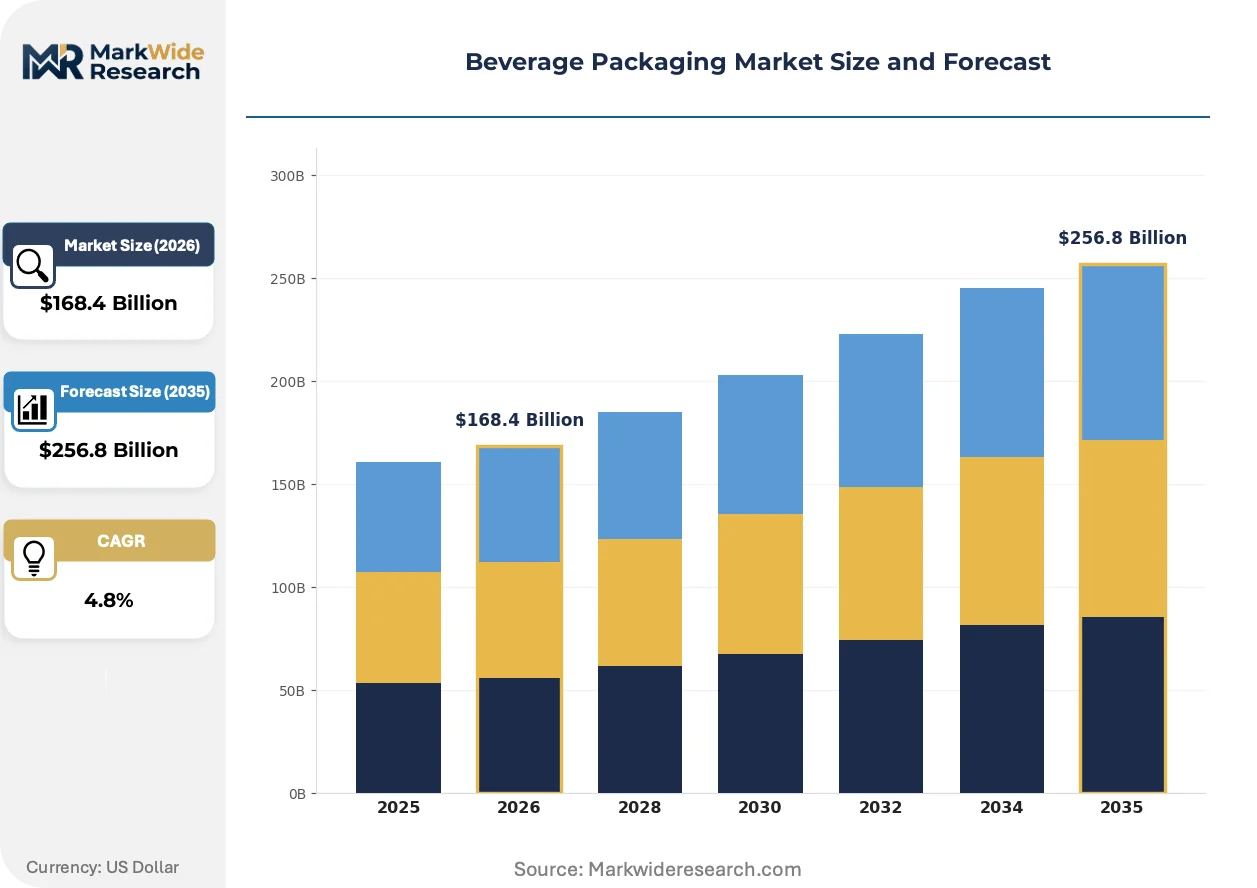
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $256.8 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Aluminum, PET, Paperboard, Bioplastics, Steel Container Format: Bottle, Can, Carton, Pouch, Keg, Drum End Use Sector: Soft Drinks, Alcoholic Beverages, Dairy Products, Juices, Functional Beverages, Water Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Food & Beverage Outlets, Wholesalers, Vending Machines |
| Companies Covered | Ball Corporation, Amcor plc, Crown Holdings, Ardagh Group, Tetra Pak, O-I Glass, Berry Global, Silgan Holdings, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Packaging Market Strategic Shifts & Innovations
Material science advancements are converging with circular economy principles, fundamentally altering how beverage containers are designed, produced, and recovered. This evolution prioritizes resource efficiency and end-of-life value without compromising product protection or consumer appeal.
Advanced chemical recycling provides a method to break down post-consumer plastics into their fundamental monomers. Major beverage producers are pursuing offtake agreements to secure a stable supply of these high-purity materials. This technology is overtaking mechanical recycling for applications requiring virgin-like quality, especially in food-contact PET bottles where clarity and safety are paramount.
The European Union's Single-Use Plastics Directive imposes specific design requirements on beverage containers. A key provision mandates that plastic caps must remain attached to bottles, a change known as tethered caps. This rule directly impacts all beverage manufacturers selling into the EU, forcing widespread packaging redesign for PET bottles and cartons.
Consumer purchasing habits are increasingly moving toward e-commerce and direct-to-consumer (D2C) subscription models for beverage delivery. This shift challenges traditional retail packaging, requiring formats optimized for parcel shipment durability and a premium unboxing experience. The trend is most visible in the specialty coffee, functional drink, and premium bottled water segments across North America.
Beverage Packaging Market Segmentation
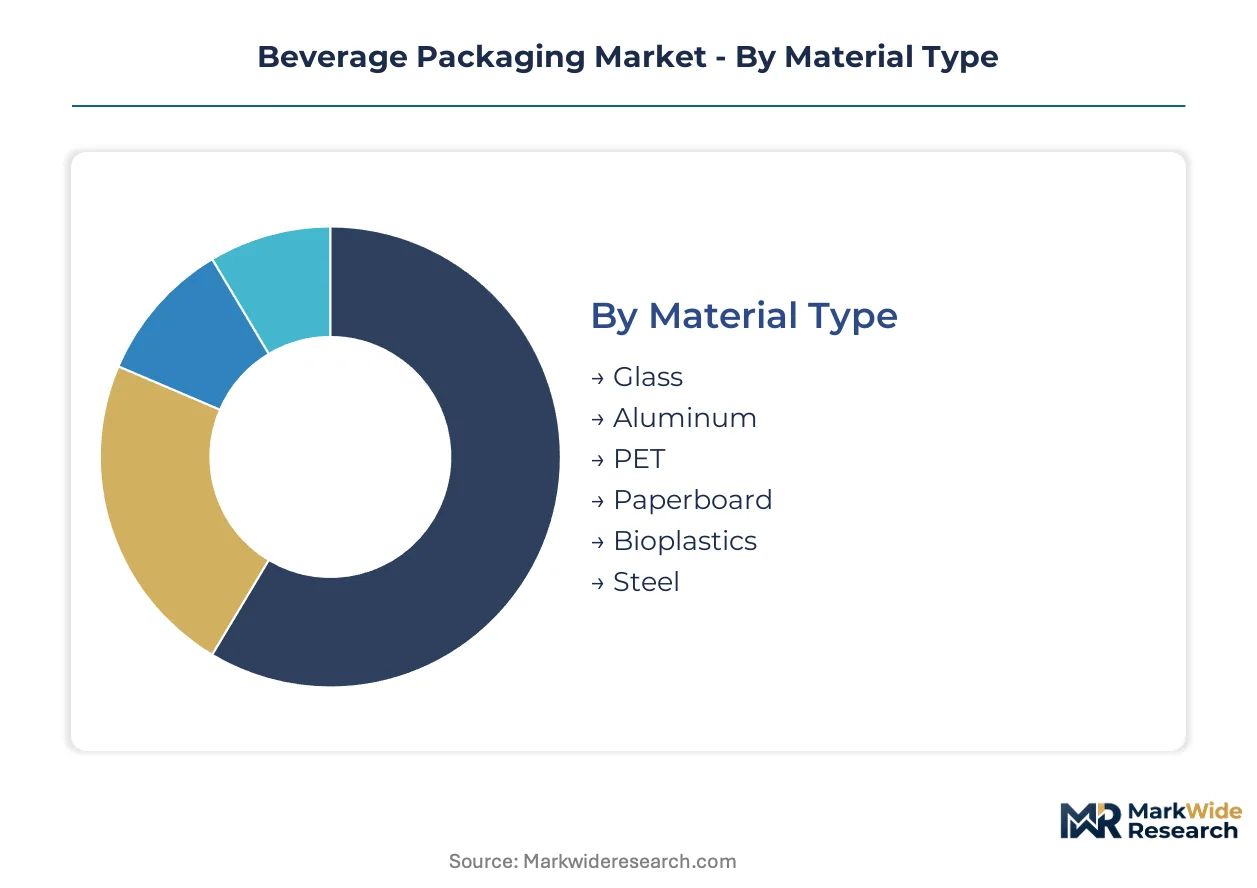
The beverage packaging market's intricate structure reflects diverse product needs and evolving consumer preferences. Understanding these segments is crucial for manufacturers to tailor solutions that meet specific functional demands and sustainability goals. Strategic investment decisions hinge on accurately identifying growth pockets and material shifts across various categories.
Material Type:
The material type segmentation highlights the customization versus standardization spectrum for beverage packaging solutions. Manufacturers often balance material performance requirements with cost-effectiveness and environmental impact considerations for each beverage type.
- Aluminum:These lightweight containers offer excellent barrier properties against light, oxygen, and moisture, preserving product freshness for carbonated soft drinks and beer. Demand concentrates in mature markets like the United States due to established recycling infrastructure and high post-consumer collection rates.
- PET:Polyethylene terephthalate bottles provide clarity, reclosability, and a good barrier for water and various soft drinks. European regulations mandating recycled content are driving investment in rPET supply chains for this material.
- Glass:Glass containers provide premium aesthetics and inertness, suitable for high-end beverages and certain alcoholic products.
- Paperboard:These cartons, often with polymer liners, are widely used for aseptic packaging of milk and juices, particularly in emerging markets like India.
- Bioplastics:Derived from renewable biomass sources, these materials like PEF offer a sustainable alternative with promising barrier properties for sensitive beverages.
- Steel:Steel is primarily utilized for larger volume containers such as kegs and drums in the alcoholic beverage sector, valued for its strength and reusability.
Leading the category by volume: Aluminum. Growing fastest: Bioplastics.
Container Format:
Container formats are primarily dictated by the application requirements of the beverage, influencing convenience, storage, and consumption patterns. Each format addresses distinct market needs from single-serve to bulk distribution.
- Bottle:Versatile and reclosable, bottles are prevalent for bottled water, juices, and functional beverages, with PET and glass being dominant materials. Demand in Southeast Asian countries like Vietnam is high for convenient, single-serve bottled water.
- Can:Cans offer durability, full recyclability, and excellent barrier protection, making them ideal for carbonated soft drinks, beer, and energy drinks. The European Union's focus on circularity supports continued high demand for aluminum cans.
- Carton:Aseptic cartons provide extended shelf life for dairy and juice products without refrigeration, popular in global markets for their efficiency.
- Pouch:Flexible pouches offer lightweight and convenient packaging for juices and children's drinks, minimizing material usage.
- Keg:Large, reusable containers primarily for draft beer, kegs facilitate efficient bulk distribution to food and beverage outlets.
- Drum:Industrial-sized drums are used for bulk transport of beverage concentrates or ingredients, ensuring large-scale supply chain efficiency.
The market exhibits a strong preference for Bottle formats due to their versatility and consumer familiarity, while Pouch packaging is gaining traction for its convenience and reduced material footprint.
End Use Sector:
The end-use sector segmentation highlights where the largest volumes of beverage packaging are consumed and where demand is most dynamic. Each sector places unique demands on packaging for preservation, convenience, and branding.
- Soft Drinks:This sector represents a massive volume base for packaging, primarily utilizing aluminum cans and PET bottles for carbonated beverages and non-carbonated drinks. Global consumption patterns drive continuous innovation in lightweighting and recyclability for this segment.
- Water:Bottled water is a significant and rapidly expanding segment, heavily relying on lightweight PET bottles for single-serve and multi-pack formats. Consumer demand for hydration and convenience, particularly in urban areas, fuels this sector's packaging needs.
- Alcoholic Beverages:This mature sector uses a mix of glass bottles, aluminum cans, and steel kegs for beer, wine, and spirits.
- Dairy Products:Aseptic cartons and plastic bottles are common for milk and other dairy products, focusing on extended shelf life and hygiene.
- Juices:Juices are packaged in cartons, PET bottles, and glass, with a focus on preserving vitamins and natural flavors.
- Functional Beverages:This high-growth segment requires specialized packaging, such as aseptic cartons or smaller PET bottles, to protect sensitive ingredients.
Packaging solutions for Soft Drinks command the largest share, with Functional Beverages expanding most quickly.
Distribution Channel:
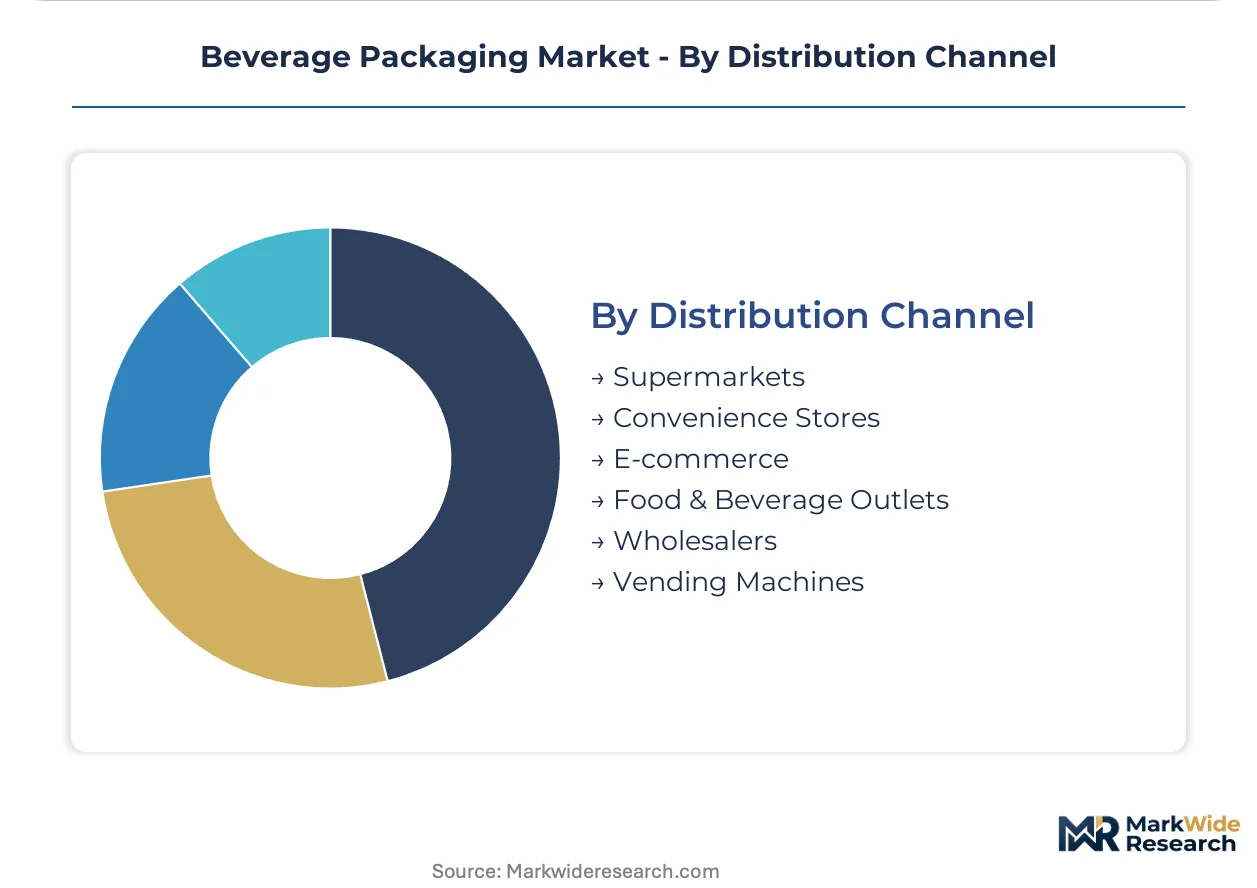
Distribution channels define how beverage packaging reaches the end consumer, influencing package design for shelf appeal, transport durability, and convenience. This category reflects the diverse retail landscape and evolving purchasing habits.
- Supermarkets:These large retail formats require packaging optimized for shelf presence, bulk sales, and efficient logistics. Supermarkets remain a primary channel for mass-market beverage sales across all regions.
- E-commerce:The shift towards online purchasing mandates packaging designed for parcel shipment durability and a positive unboxing experience, particularly for specialty drinks. This channel is seeing significant growth in North America for D2C beverage models.
- Convenience Stores:Packaging for convenience stores emphasizes single-serve formats and immediate consumption, catering to on-the-go consumers.
- Food & Beverage Outlets:Restaurants, cafes, and bars utilize both single-serve and bulk packaging, including glass bottles and kegs, for immediate consumption on-premise.
- Wholesalers:Wholesalers handle large volumes of packaged beverages for redistribution to smaller retailers and food service providers, focusing on efficient bulk packaging.
- Vending Machines:Packaging for vending machines requires specific dimensions and robust construction to withstand automated dispensing.
Traditional retail channels like Supermarkets remain critical, while digital platforms such as E-commerce are seeing rapid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for beverage packaging is particularly pronounced in populous, urbanizing economies. These regions drive significant volume due to expanding consumer bases and evolving lifestyle preferences. Investment decisions across the market increasingly reflect regional regulatory landscapes and local sustainability mandates.
United States
Consumer preferences for convenience and health-oriented beverages propel demand for single-serve PET bottles and aluminum cans. The US FDA regulates food-contact packaging materials, ensuring safety standards for all beverage containers. Major packaging manufacturers operate extensive facilities in the Midwest, serving a broad network of beverage bottlers.
Germany
Sustainability mandates from the EU Green Deal and national deposit-return schemes for bottles and cans influence packaging design and material choices. German consumers prioritize highly recyclable materials like aluminum and rPET for environmental reasons. Berlin's innovation hubs support the development of advanced recycling technologies and bio-based packaging solutions.
India
Rapid urbanization and rising disposable incomes fuel significant demand for bottled water and aseptic cartons for dairy and juices. The Bureau of Indian Standards (BIS) establishes quality and safety benchmarks for beverage containers. Packaging production clusters in Maharashtra and Gujarat serve the country's vast and expanding consumer market.
China
The vast Chinese market drives immense volumes for both traditional soft drinks and newer functional beverages, requiring diverse packaging solutions. China's GB standards for food-contact materials dictate strict compliance for all beverage packaging entering the market. Industrial zones around the Yangtze River Delta concentrate significant packaging manufacturing and R&D capabilities.
Vietnam
Emerging market expansion, particularly in Southeast Asia, creates white space for packaged beverages, especially bottled water and juices. Vietnamese regulations emphasize material safety and waste management for consumer goods packaging. Ho Chi Minh City acts as a key distribution and manufacturing hub for beverage packaging across the country.
Beverage Packaging Market Key Industry Players
North American and European producers anchor one tier, focusing on advanced materials and circular economy solutions; Asian specialists hold another, emphasizing cost-efficiency and scale for high-volume markets. The market structure exhibits consolidation among large, diversified players and fragmentation among niche material providers. Companies pursue portfolio diversification and geographic expansion as dominant competitive moves.
Scale-driven players like Ball Corporation (a US-based corporation) exemplify the global reach required for major soft drink and beer producers. Amcor plc, an Australia-based multinational packaging company, represents the archetype of a diversified provider offering both flexible and rigid plastic solutions. Tetra Pak, a Swedish-Swiss multinational food packaging and processing company, sits within the specialized segment, focusing on aseptic carton technology for dairy and juice products.
| Leading Market Players |
|---|
| Ball Corporation |
| Amcor plc |
| Crown Holdings |
| Ardagh Group |
| Tetra Pak |
| O-I Glass |
| Berry Global |
| Silgan Holdings |
| Sonoco Products Company |
| Others |
Cost & Logistics Intelligence
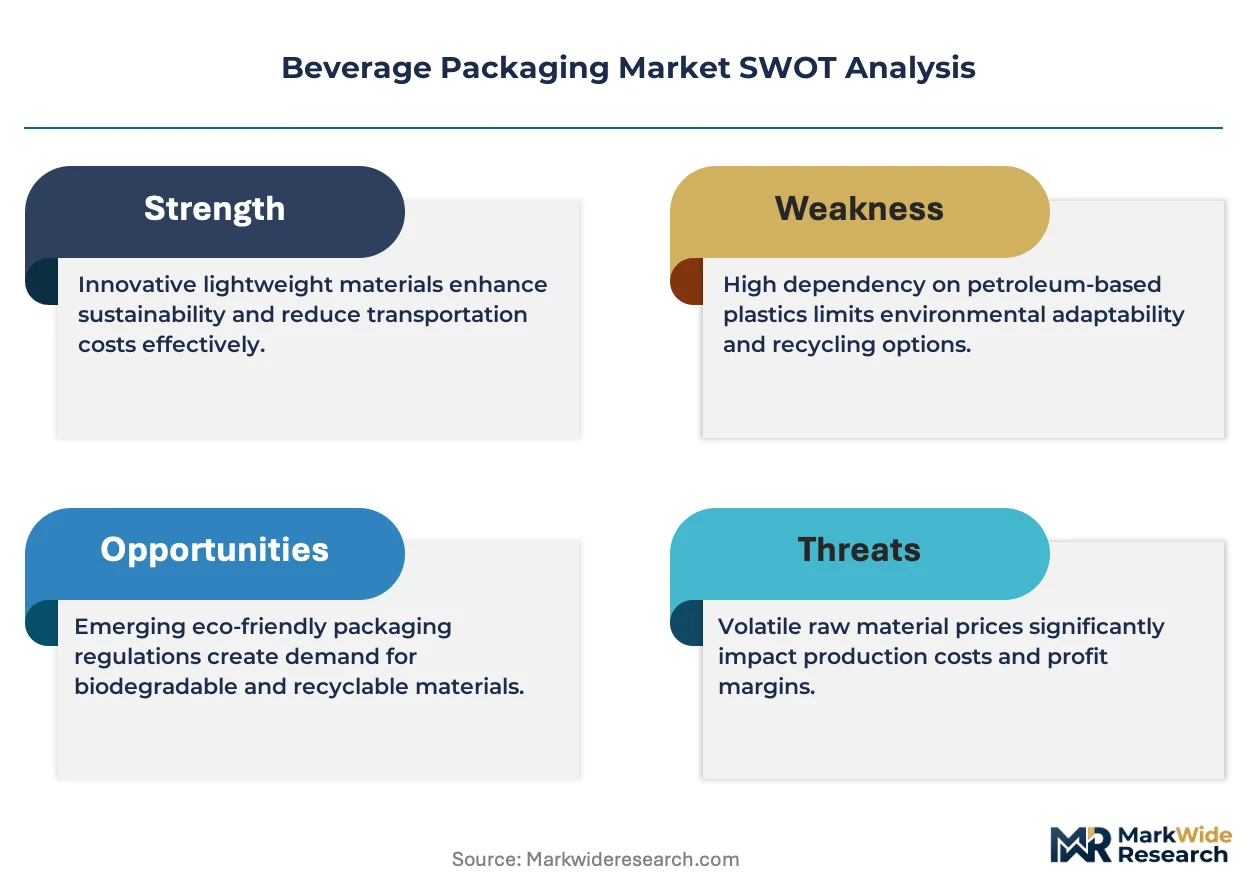
The EU Green Deal's circular economy principles gate access to qualified packaging suppliers, consequently influencing premium-tier pricing for sustainable beverage formats. This mandate compels significant investment in material science and recycling infrastructure, creating a distinct market for compliant solutions.
Pricing Analysis
High-volume commodity packaging operates on thin margins, while specialized functional beverage formats command premium pricing. Pricing stratifies across premium, standard, and economy tiers based on material certification, barrier properties, and geographic delivery costs. Pricing softness stems from volatile raw material costs, particularly for aluminum ingot and rPET flakes. Bottled water and soft drink packaging segments exhibit the highest price sensitivity, whereas functional beverages demonstrate lower sensitivity due to specialized requirements.
Supply Chain Analysis
Food-contact material certifications, such as US FDA and China's GB standards, gate access to the beverage packaging supply chain. The supply base draws from concentrated manufacturing hubs in China, India, and Germany. Raw material dependencies center on aluminum ingot, food-grade rPET flakes, and virgin PET resins. Inconsistent availability of post-consumer feedstock for rPET presents a structural supply chain risk. Distribution runs through large-scale packaging converters and regional logistics networks to beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beverage packaging market presents a significant cost-of-compliance story. The EU Single-Use Plastics Directive, mandating tethered caps, creates a barrier-to-entry moat for manufacturers investing in retooling.
For Market Incumbents: Extend multi-material capabilities to serve diverse beverage segments and mitigate reliance on single material types. Invest in advanced chemical recycling technologies to secure high-purity rPET supply, countering fluctuating virgin material costs. Capacity additions in key regions like India can address rising demand. Certification investment for sustainable materials reinforces market leadership against emerging bio-based alternatives.
For New Entrants and Emerging Players: Capture white space in emerging markets like Southeast Asia, targeting bottled water and functional beverage segments. Focus on bio-based polymers for niche functional drinks requiring unique barrier properties. Partner with innovative beverage startups to offer sustainable, premium products, leveraging agile manufacturing and design-for-recyclability expertise. Smart packaging solutions for D2C brands present a viable go-to-market angle.
For Investors and Strategic Acquirers: Widespread commercialization of PEF bioplastics is the leading indicator that renewable alternatives are displacing fossil-fuel-based PET. The market offers long-term stability driven by essential consumer demand and ongoing sustainability mandates. Target mid-sized specialists in advanced recycling or bio-based material development for acquisition. Increased M&A activity for sustainable packaging technology firms signals market maturation and consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Recycling | Secures high-quality recycled content supply for PET bottles amidst regulatory mandates. |
| Expand Global Manufacturing Footprint | Addresses rising demand in urbanizing economies and optimizes regional supply chain resilience. |
| Develop Bio-based Material Partnerships | Accelerates commercialization of renewable packaging alternatives for sensitive beverages. |
| Optimize Packaging for E-commerce | Enhances parcel shipment durability and consumer unboxing experience for online beverage sales. |
| Achieve Sustainability Certifications | Meets consumer preferences and regulatory requirements for environmentally responsible packaging materials. |
Research Approach
Document review covered regulatory filings, industry association reports, and academic literature, complemented by interviews with packaging engineers, procurement managers, and sustainability officers. Primary insights from brand managers and material scientists informed market dynamics. Bottom-up market sizing was performed, with top-down validation against macroeconomic indicators and regional consumption trends.
Historical market performance data was cross-referenced with expert panel input to establish the forecast framework across the analysis window. Segmentation dimensions modeled included material type, container format, end-use sector, distribution channel, and regional regulatory environment. Compound annual growth rates were derived from projected shifts in consumer preferences and regulatory impacts, with urbanization rates and functional beverage consumption trends as key inputs.
The model holds under current regulatory and economic conditions; deviation in global trade policies or raw material supply would shift market trajectories. Forecasts reflect assumptions regarding stable geopolitical environments and consistent consumer sustainability demands. A model refresh is warranted upon material change in advanced recycling technology adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Skep Bottle Market