
 Twist Caps Market | 2026-2036
Twist Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Twist Caps Market Analytics
Modular closure bundling with smart-sensing liners is hardening as the default procurement specification for premium beverage and pharmaceutical accounts. Crown Holdings leverages captive aluminum supply to anchor its metal twist cap franchise across Latin American beer markets. Tecnocap competes on deep-draw steel technology for carbonated soft drink applications, while Silgan Holdings dominates North American food jar segments through in-house resin compounding and thermoforming integration.
Twist caps are threaded closures that engage with container neck finishes via helical grooves, typically manufactured through injection molding of HDPE or PP resins, compression molding of aluminum, or hybrid composite forming with induction-seal liners to achieve hermetic integrity. Their primary purpose is to enable repeatable opening and resealing while preserving product freshness, preventing contamination, and supporting tamper-evident functionality across liquid and semi-solid packaged goods. Plastic caps sustain the largest volume position globally, though child-resistant caps generate disproportionate margin pools due to pharmaceutical certification requirements and specialized tooling barriers. Metal caps retain structural importance in oxygen-sensitive beverage categories, while composite formats are gaining traction where brand differentiation through custom color matching and embossing commands shelf-space premiums.
FDA 21 CFR Part 211 cGMP requirements and EMA Annex 1 sterile manufacturing guidelines directly shape pharmaceutical closure validation protocols, including extractables-leachables testing and container-closure integrity verification. The EU Green Deal packaging waste directives and emerging U.S. state-level extended producer responsibility frameworks are forcing converters to document recycled content percentages and design for recyclability across twist cap portfolios. Stakeholders must monitor how rapidly evolving mono-material recycling specifications and digital watermark traceability standards will reshape material selection and capital equipment planning across their manufacturing networks.
Market Dynamics
Pharmaceutical serialization mandates and beverage sustainability targets are compressing material selection cycles, forcing converters to validate mono-material recyclability before securing multi-year supply contracts with brand owners.
Growth Catalysts
- FDA 21 CFR Part 211 cGMP:Serialization requirements for tamper-evident closures are expanding validation protocols across US pharmaceutical packaging lines, pulling demand toward certified child-resistant formats.
- EU Green Deal packaging waste directives:Recycled content mandates are accelerating metal-to-plastic conversion programs in German beverage bottling corridors.
- Induction-seal liner integration:Hermetic integrity specifications for oxygen-sensitive categories are driving composite twist cap adoption in premium alcoholic beverages.
Market Restraints
- Aluminum price volatility:Crown Holdings and Latin American beer markets face margin compression from energy-intensive primary metal sourcing.
- Pharmaceutical tooling barriers:Child-resistant certification requires 18-24 month validation cycles that lock out mid-cap converters without captive testing facilities.
- Mechanical substitution:Snap-fit and press-twist alternatives are capturing share in low-carbonation beverage segments where reseal frequency is minimal.
Strategic Opportunities
- India's beverage bottling belt:Local converters scaling metal-to-plastic conversion capacity present white space for HDPE and PP resin compounders with technical service presence.
- Digital watermark traceability:Convergence of sorting infrastructure and packaging design is enabling closed-loop recovery systems for mono-material caps.
- Extended producer responsibility frameworks:Emerging US state-level legislation is creating first-mover advantage for converters documenting full lifecycle carbon footprints.
Industry Challenges
- Extractables-leachables testing capacity:Pharmaceutical closure validation requires specialized analytical chemistry talent that concentrates in Germany, Switzerland, and Massachusetts.
- Legacy thermoforming integration:Silgan Holdings' in-house resin compounding model is difficult to replicate without decade-long customer co-development relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twist Caps Market |
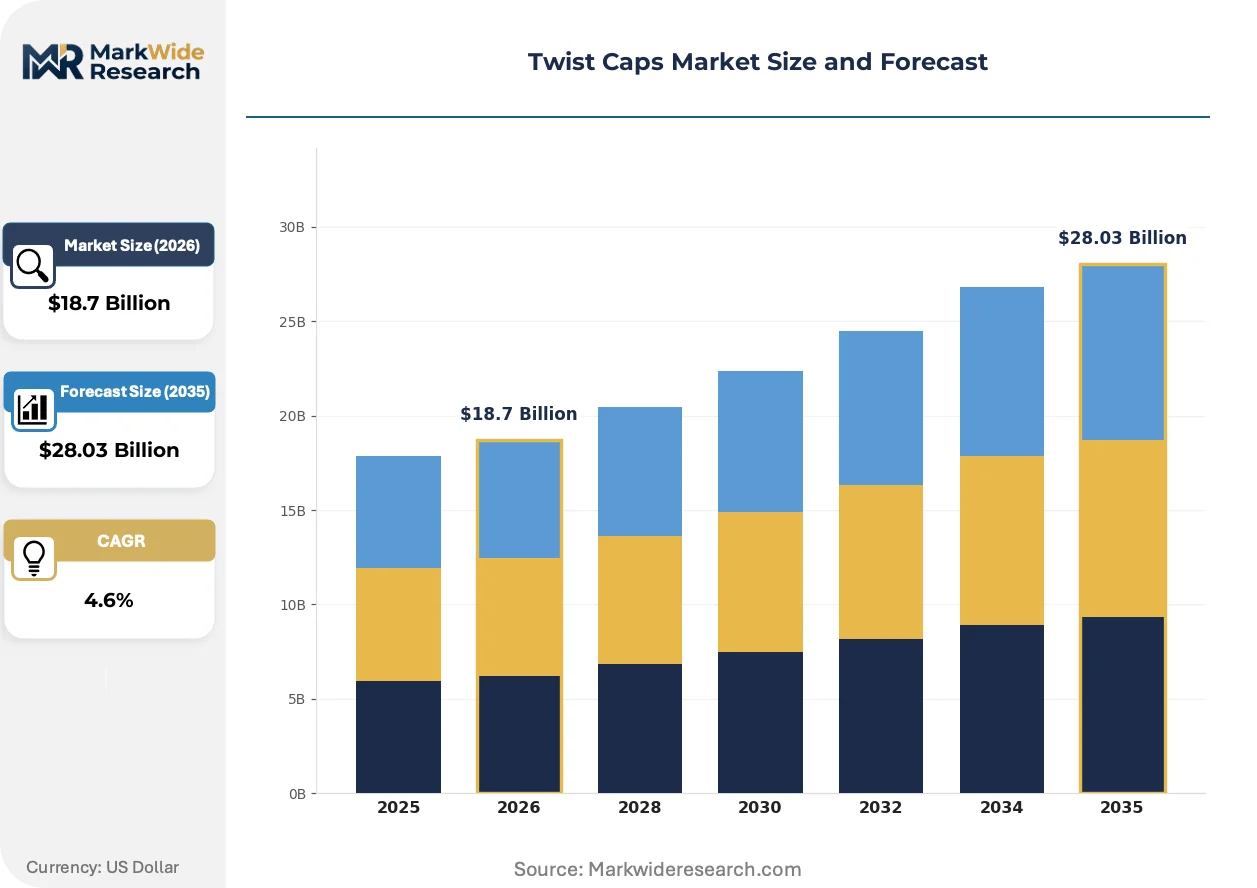
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Caps, Metal Caps, Composite Caps, Child-resistant Caps Application: Beverages, Pharmaceuticals, Cosmetics, Household Products End User: Food & Beverage Industry, Healthcare Providers, Cosmetic Manufacturers, Household Consumers Distribution Channel: Retail Stores, E-commerce Platforms, Wholesalers, Direct Sales |
| Companies Covered | Crown Holdings, Tecnocap, Berry Global Group, Closure Systems International, Guala Closures Group, Silgan Holdings, AptarGroup, BERICAP Holding, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twist Caps Market Evolving Landscape
Smart-sensing liner technology and mono-material design specifications are rewriting procurement criteria, while regulatory pressure on supply chain integrity is collapsing the timeline between material innovation and commercial validation.
Induction-seal liners with embedded RFID tags are converging with blockchain-tracked pharmaceutical supply chains, enabling real-time container-closure integrity monitoring. Tier-one drug manufacturers in Germany and Switzerland are piloting these hybrid formats for high-value biologics. The technology is converging with existing cGMP validation frameworks, compressing the window for competitive differentiation through traceability features.
EMA Annex 1 sterile manufacturing guidelines are tightening extractables-leachables testing protocols for elastomeric closure components used in parenteral packaging. European converters must now document sub-ppm threshold compliance across multiple solvent systems before commercial approval. Pharmaceutical accounts in the Rhine-Ruhr corridor are responding by consolidating supplier bases toward vertically integrated compounders with captive analytical laboratories.
Brand owners are unbundling closure procurement from bottle supply agreements, creating direct sourcing relationships with specialized converters. This disintermediation is displacing traditional co-packing arrangements in North American craft beverage segments. The pattern is most visible in California and Colorado, where regional breweries are specifying custom color-matched embossing through independent cap manufacturers rather than integrated bottle suppliers.
Twist Caps Market Segmentation
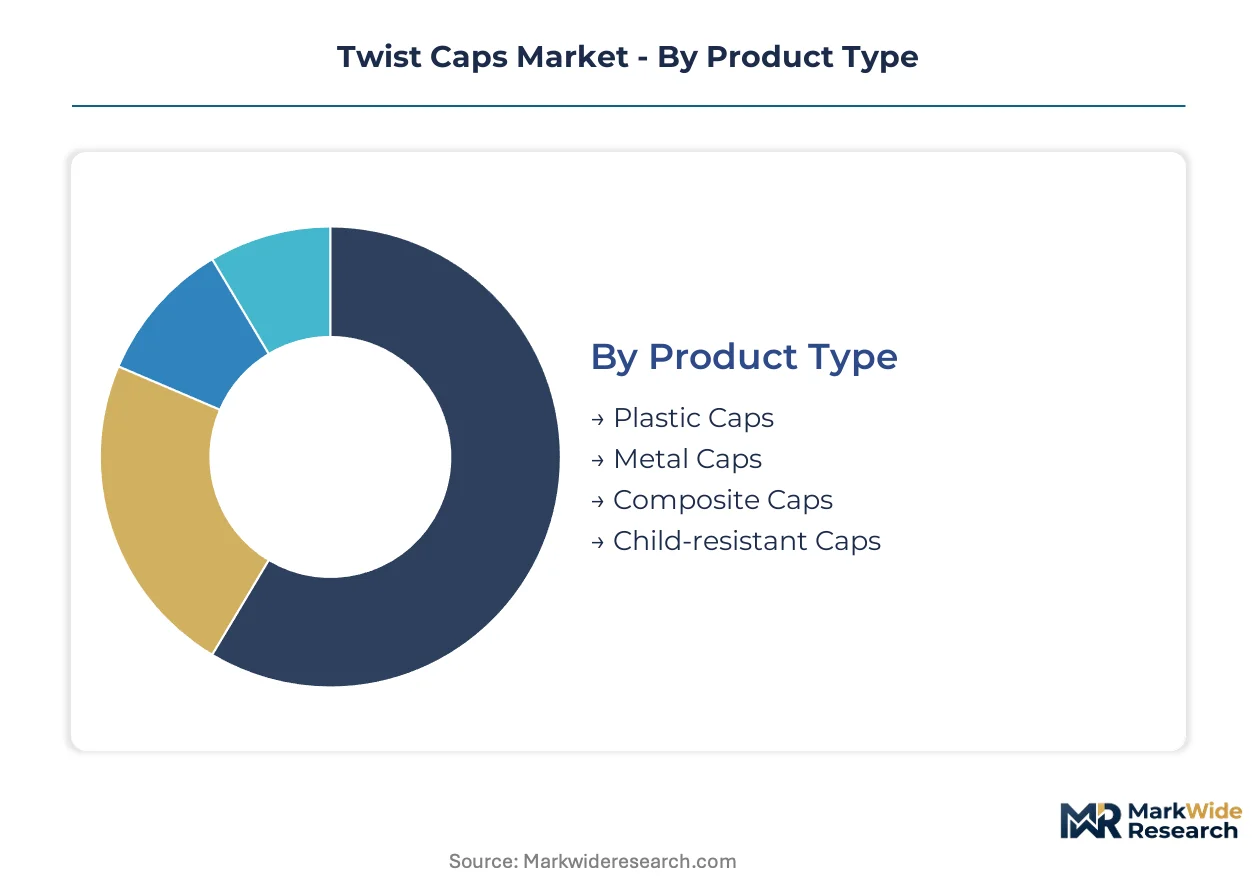
Twist cap procurement specifications diverge sharply across end-use verticals, with pharmaceutical serialization mandates and beverage sustainability targets creating incompatible validation timelines. Material selection, liner integration, and tamper-evident functionality must align with distinct regulatory frameworks governing each application cluster.
Product Type:
FDA 21 CFR Part 211 cGMP and EMA Annex 1 sterile manufacturing guidelines impose tiered certification burdens: child-resistant formats require 18-24 month validation cycles, while standard beverage closures face only internal quality protocols.
- Plastic Caps:Injection-molded HDPE and PP resins dominate volume through metal-to-plastic conversion programs in India's beverage bottling belt and Germany's pharmaceutical corridor. Recycled content mandates under EU Green Deal packaging waste directives are accelerating mono-material specification adoption among brand owners seeking design-for-recyclability documentation.
- Metal Caps:Deep-drawn aluminum and steel formats retain structural importance in oxygen-sensitive beverage categories, particularly Latin American beer markets where Crown Holdings leverages captive aluminum supply. Energy-intensive primary metal sourcing creates margin vulnerability from commodity price volatility.
- Composite Caps:Hybrid constructions with induction-seal liners deliver hermetic integrity for premium alcoholic beverages. Integration of smart-sensing RFID tags is converging with blockchain-tracked pharmaceutical supply chains for real-time container-closure integrity monitoring.
- Child-resistant Caps:Specialized tooling barriers and pharmaceutical certification requirements generate disproportionate margin pools. Extractables-leachables testing capacity concentrates in Germany, Switzerland, and Massachusetts, locking out mid-cap converters without captive analytical facilities.
Leading the category by volume: Plastic Caps. Growing fastest: Child-resistant Caps.
Application:
End-use concentration shapes regional manufacturing footprints, with beverage bottling corridors and pharmaceutical clusters driving divergent material specifications and liner integration requirements.
- Beverages:Carbonated soft drink and premium alcoholic segments demand oxygen-barrier performance, pulling composite format adoption in Germany and California craft brewing markets. Brand owners are disintermediating closure procurement from bottle supply agreements, creating direct sourcing relationships with specialized converters.
- Pharmaceuticals:Parenteral packaging applications face tightening EMA Annex 1 extractables-leachables protocols, forcing European converters toward vertically integrated compounders with captive analytical laboratories in the Rhine-Ruhr corridor.
- Cosmetics:Custom color matching and embossing specifications command shelf-space premiums through brand differentiation strategies.
- Household Products:Standard HDPE and PP formats serve cost-sensitive applications with minimal regulatory validation overhead.
Volume leadership: Beverages. Steepest expansion trajectory: Pharmaceuticals.
End User:
Customer scale determines procurement leverage, with tier-one drug manufacturers and multinational beverage bottlers dictating material innovation timelines through multi-year supply contracts.
- Food & Beverage Industry:Multinational bottlers in Germany and India are scaling metal-to-plastic conversion capacity, creating white space for resin compounders with technical service presence.
- Healthcare Providers:Tier-one drug manufacturers in Germany and Switzerland pilot RFID-enabled hybrid formats for high-value biologics, compressing competitive differentiation windows through traceability convergence.
- Cosmetic Manufacturers:Brand owners specify custom embossing through independent cap manufacturers rather than integrated bottle suppliers.
- Household Consumers:Retail-facing demand channels favor standardized specifications with minimal customization requirements.
Dominant by procurement scale: Food & Beverage Industry. Expanding most quickly: Healthcare Providers.
Distribution Channel:
Channel selection reflects order scale and specification complexity, with direct sales capturing pharmaceutical validation relationships and e-commerce platforms serving fragmented regional beverage segments.
- Retail Stores:Mass-market beverage and household product distribution through established merchandising relationships.
- E-commerce Platforms:Regional craft breweries in California and Colorado access custom color-matched specifications through digital procurement channels.
- Wholesalers:Inventory consolidation for mid-scale cosmetic and household product manufacturers.
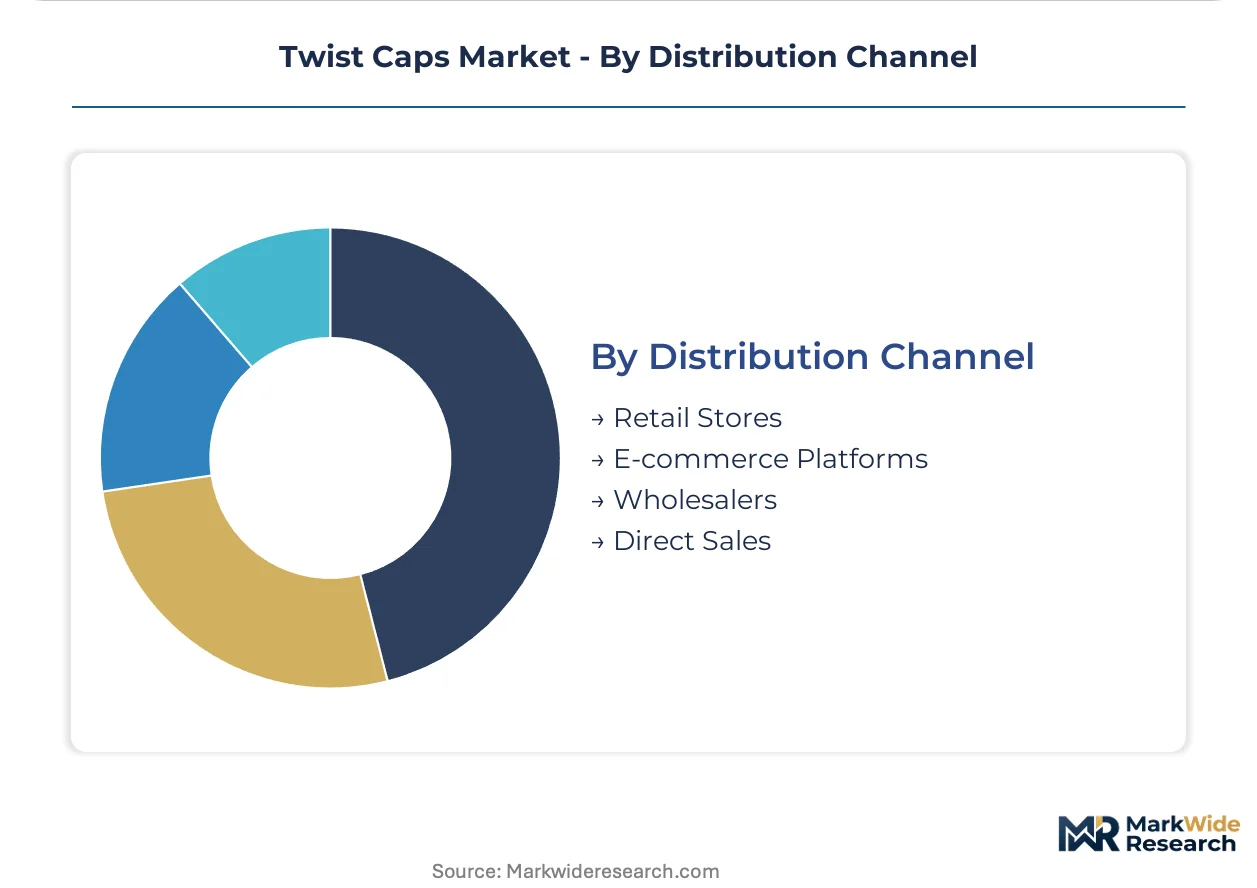
- Direct Sales:Pharmaceutical accounts require 18-24 month co-development relationships for child-resistant certification, locking in supplier consolidation toward vertically integrated compounders.
Highest volume throughput: Retail Stores. Fastest channel shift: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and India while consumption concentrates in North American pharmaceutical corridors and European beverage bottling belts. This geographic split creates trade flows in raw resin compounds and finished closures. Logistics networks must bridge these supply-demand asymmetries.
United States
FDA serialization mandates for tamper-evident closures are expanding validation protocols across pharmaceutical packaging lines in Massachusetts and New Jersey. The 21 CFR Part 211 cGMP requirements pull demand toward certified child-resistant formats with 18-24 month approval cycles. Boston-area analytical chemistry clusters concentrate extractables-leachables testing capacity that locks out mid-cap converters.
Germany
The Rhine-Ruhr pharmaceutical corridor drives demand for high-integrity closures as EMA Annex 1 sterile manufacturing guidelines tighten. EU Green Deal packaging waste directives accelerate metal-to-plastic conversion programs in beverage bottling operations. Bavarian converters with captive resin compounding facilities are consolidating supplier relationships with tier-one drug manufacturers.
India
Maharashtra and Gujarat beverage bottling belts are scaling metal-to-plastic conversion capacity for HDPE and PP resin applications. FSSAI food safety standards and BIS quality certifications shape local procurement specifications. Mumbai-Pune industrial corridor converters present white space for technical service-focused resin compounders.
Brazil
Latin American beer markets sustain structural demand for deep-drawn aluminum closures despite energy-intensive primary metal sourcing. ANVISA pharmaceutical regulations are gradually converging with FDA serialization protocols. São Paulo state packaging converters face margin compression from aluminum price volatility.
Switzerland
Swissmedic oversight of high-value biologics packaging is driving pilot programs for RFID-enabled hybrid closure formats. Geneva and Basel pharmaceutical clusters require sub-ppm extractables-leachables compliance across multiple solvent systems. Vertically integrated compounders with captive analytical laboratories are capturing supplier consolidation benefits.
Twist Caps Market Competitive Landscape
The competitive structure tilts toward vertically integrated resin compounders with captive testing facilities. Tier-one pharmaceutical accounts and multinational beverage bottlers dictate material innovation timelines through multi-year supply contracts. Three archetypes dominate: aluminum suppliers with beverage market anchoring, plastic converters with pharmaceutical certification depth, and hybrid specialists with smart-sensing liner integration. Competitive moves center on backward integration into resin production and geographic expansion into India's beverage bottling belt.
Among North American metal closure specialists, Crown Holdings and Silgan Holdings exemplify divergent strategic positions. Crown leverages captive aluminum supply relationships across Latin American beer markets. Silgan represents the plastic converter archetype with in-house resin compounding and thermoforming integration. Tecnocap occupies a position among European steel closure fabricators with deep-draw technology specialization. These three anchors illustrate how material access and certification depth separate market tiers.
| Leading Market Players |
|---|
| Crown Holdings |
| Tecnocap |
| Berry Global Group |
| Closure Systems International |
| Guala Closures Group |
| Silgan Holdings |
| AptarGroup |
| BERICAP Holding |
| Amcor plc |
| Others |
Value Network & Pricing Analysis
Tier-one pharmaceutical manufacturers and multinational beverage bottlers concentrate procurement leverage, anchoring contract-based long-term offtake pricing with volume-scaled discounts and certification-grade premiums. This buyer concentration forces converters to absorb aluminum commodity volatility and resin compounder margin compression while defending position through captive testing facility investments.
Pricing Analysis
Margin tightening in child-resistant formats reflects 18-24 month FDA validation cycles and extractables-leachables testing capacity scarcity. Three-tier pricing structure across certified pharmaceutical, premium beverage composite, and standard commodity plastic caps separates compliance-grade from performance-grade from economy segments. Cost-down pressure on metal closures accelerates because energy-intensive primary aluminum sourcing exposes Crown Holdings and Latin American beer markets to commodity spikes. Household product manufacturers show highest price sensitivity, while Swiss biologics packers accept premium RFID-enabled hybrid formats.
Supply Chain Analysis
HDPE and PP resin compounders draw from German petrochemical corridors, Indian polymer processors, and US Gulf Coast crackers. Aluminum coil supply rests on Latin American smelters and European rolling mills, while induction-seal liner substrates hinge on Japanese specialty adhesive producers. Single-source vulnerability concentrates in analytical chemistry talent for pharmaceutical validation, clustering in Massachusetts, Germany, and Switzerland. Distribution runs through direct sales channels for pharmaceutical accounts and established wholesaler networks for beverage bottling corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extractables-leachables testing capacity scarcity props pricing power for converters with captive analytical laboratories, creating supply-constrained entry barriers that sustain incumbent margins.
For Market Incumbents: Deepen backward integration into resin compounding to replicate Silgan Holdings' thermoforming model and defend against metal-to-plastic conversion programs. Lock in multi-year supply contracts with tier-one drug manufacturers before EMA Annex 1 validation timelines compress further, leveraging existing FDA certification depth as a switching-cost barrier. For New Entrants and Emerging Players: Regional craft breweries in California and Colorado present the most penetrable white space, as brand owners disintermediate closure procurement from integrated bottle suppliers. Target technical service partnerships with Maharashtra and Gujarat converters scaling metal-to-plastic capacity, offering HDPE and PP formulation expertise as a beachhead entry mechanism. For Investors and Strategic Acquirers: The window for entry favors vertically integrated compounders with captive testing facilities and established pharmaceutical certification relationships. Watch for FDA serialization mandate acceleration as the inflection signal that collapses validation timelines and consolidates supplier bases toward analytical-capability owners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Mirrors Silgan Holdings' model to capture margin pools in North American food jar segments. |
| Captive Analytical Laboratory Investment | Locks out mid-cap competitors from 18-24 month pharmaceutical validation cycles. |
| Smart-Sensing Liner Technology Development | Converges with blockchain-tracked supply chains for high-value biologics in Germany and Switzerland. |
| Metal-to-Plastic Conversion Capacity Expansion | Captures EU Green Deal recycled content mandates in German beverage bottling corridors. |
| Direct Sales Channel Establishment | Disintermediates traditional co-packing arrangements with California and Colorado craft breweries. |
Research Methodology
Independent corroboration across converter plant managers, pharmaceutical packaging procurement leads, beverage bottler technical directors, and resin compounder sales executives underwrites the qualitative findings. Secondary validation draws from FDA 21 CFR filings, EMA Annex 1 guidance documents, EU Green Deal packaging waste directive texts, and SEC 10-K disclosures from Crown Holdings and Silgan Holdings. Bottom-up capacity assessments and top-down demand aggregation triangulate volume estimates.
Comparable-period anchoring linked forward projections to historical pharmaceutical serialization adoption curves and beverage metal-to-plastic conversion rates. The analytical framework segments by material type, end-use vertical, liner integration complexity, and regional regulatory cluster. CAGRs derive from regression against packaging output indices and pharmaceutical production data. Forecast inputs include aluminum commodity trajectory assumptions and recycled content mandate compliance timelines.
Several conditions sit outside the modeled scope, including geopolitical disruption to Latin American aluminum supply, abrupt FDA rulemaking acceleration, and breakthrough snap-fit closure technology displacement. Forecasts reflect documented assumptions about validation cycle duration and testing capacity expansion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Cuvette Caps Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
Global Aluminum Caps and Closures Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Spray Caps Market
Caps and Closures
Shrink Bands Market
Caps and Closures
Metal Closures Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Drum Plugs Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Fez Caps Market
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Sleeve Rubber Stoppers Market