
 Flexible Film Market | 2026-2036
Flexible Film Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Film Market Analysis
Aftermarket recycling and film collection revenue is rewriting profit allocation across the value chain. Amcor Limited leverages backward integration into resin compounding to secure feedstock quality. Berry Global Group anchors North American blown film capacity through multi-site manufacturing scale. Mondi Group competes with specialty kraft-polymer hybrid structures that target paper-reduction mandates.
Flexible film denotes polymer-based sheet materials typically manufactured via blown or cast extrusion, ranging from 12 micrometers to 250 micrometers in thickness, engineered for barrier protection, sealability, and printability across industrial and consumer applications. Polyethylene formulations dominate volume due to cost scalability and heat-seal performance, while polyester films command premium positioning in electronics and medical barrier applications where dimensional stability and optical clarity prove critical. Application segmentation shows packaging absorbing the majority of volume, though medical-grade films generate disproportionate margin contribution due to validation requirements and sterilization compatibility.
FDA food-contact regulations, EPA emissions standards for extrusion operations, and EU REACH chemical authorization collectively elevate compliance costs while accelerating substitution toward recyclable mono-material structures. India's BIS certification requirements for food-grade plastics and the EU Green Deal packaging waste directives are tightening market access for non-compliant imports. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned capital deployment.
Market Dynamics
Mono-material polyethylene structures are compressing multi-layer film architectures as Extended Producer Responsibility mandates in Germany, France, and California force redesign cycles. This regulatory pressure is reallocating capital from barrier coextrusion toward compatibilizer chemistry and mechanical recycling infrastructure.
Growth Catalysts
- EPR Mandates:Germany's Packaging Act and France's AGEC law obligate brands to fund collection and recycling, accelerating mono-material adoption across food and personal care packaging.
- Mechanical Recycling Infrastructure:Advanced sorting and wash technologies in the Netherlands and Belgium are improving post-consumer polyethylene flake quality, enabling food-contact applications.
- Blown Film Extrusion Advancements:Nine-layer and eleven-layer coextrusion lines with inline MDO units allow downgauging without sacrificing barrier performance in snack and frozen food segments.
Market Restraints
- Resin Price Volatility:Ethylene feedstock costs track naphtha and natural gas liquids, compressing converter margins during upstream petrochemical turnarounds.
- Barrier Performance Trade-offs:Mono-material polyethylene structures sacrifice oxygen and moisture barrier versus ethylene vinyl alcohol or aluminum oxide metallized alternatives, limiting shelf-life extension in sensitive applications.
- Collection Infrastructure Gaps:Flexible film capture rates in municipal recycling streams remain below rigid packaging, stranding circular economy commitments.
Strategic Opportunities
- Chemical Recycling Scale-Up:Pyrolysis and depolymerization investments in Texas and Rotterdam address mixed-film waste streams mechanically sorting cannot valorize.
- Pharmaceutical Blister Alternatives:High-barrier polyethylene and polypropylene structures are displacing PVC and aluminum in unit-dose packaging as EU MDR drives material disclosure.
- Digital Watermark Integration:AIM-recognized markers from Digimarc and Polytag enable automated sorting line recognition of food-grade versus non-food polyethylene films.
Industry Challenges
- Food-Contact Certification Timelines:FDA Letter of No Objection and EFSA safety assessments for recycled content applications extend 18-24 months, delaying commercial launches.
- Legacy Equipment Retrofit Costs:Converting cast extrusion or solvent coating lines for water-based or extrusion lamination requires seven-figure capital outlays with uncertain payback periods.
- Recycled Content Traceability:Mass balance accounting for chemically recycled inputs lacks harmonized standards between ISCC PLUS and RSB certifications, complicating customer claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Film Market |
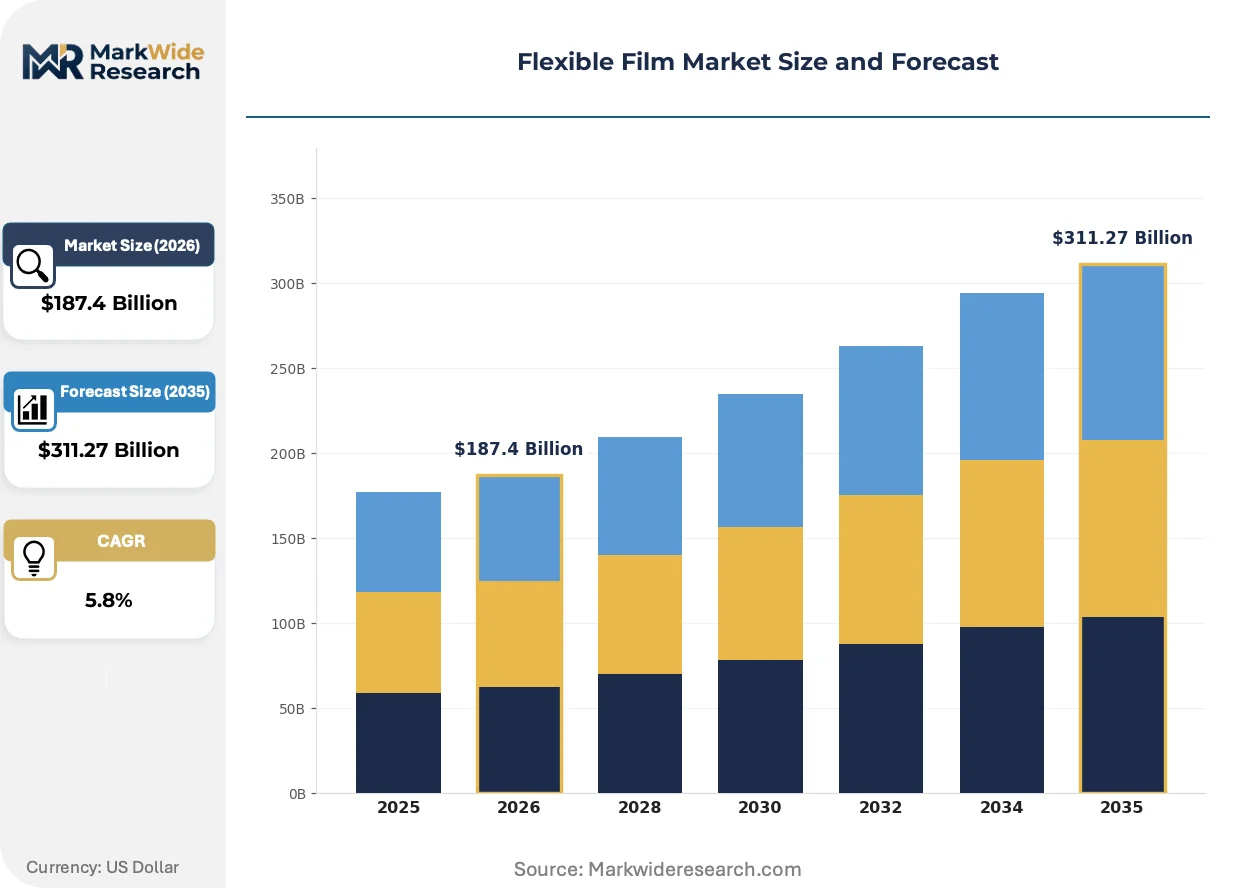
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyester, Nylon Application: Packaging, Electronics, Agriculture, Medical End User: Food & Beverage, Consumer Goods, Pharmaceuticals, Industrial Thickness: Ultra-Thin, Thin, Medium, Heavy-Duty |
| Companies Covered | Amcor Limited, Berry Global Group, Mondi Group, Huhtamaki Oyj, Sealed Air Corporation, Uflex Limited, Sonoco Products Company, Coveris Group, Transcontinental Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Film Market Emerging Trajectories
Barrier technology convergence with sustainability protocols is collapsing traditional film specification hierarchies. Material scientists and brand technical teams are co-developing structures that satisfy both performance validation and recyclability certification.
Polyethylene furanoate and bio-based polyethylene from sugarcane ethanol are collapsing the virgin fossil-derived resin baseline in premium cosmetics and food packaging. L'Oréal and Unilever procurement teams have accelerated qualification timelines from thirty-six to eighteen months for certified bio-based content. This compression is forcing petrochemical suppliers to reconfigure cracker feedslates and secure biomass offtake agreements ahead of competitor lock-ins.
EU REACH authorization for per- and polyfluoroalkyl substances is eliminating fluoropolymer grease barriers in microwave popcorn and fast-food packaging by 2026. Paperboard converters in Sweden and Finland are accelerating silicone and clay coating trials as functional replacements. The snack food segment faces reformulation costs and line speed adjustments as non-fluorinated barriers require thicker deposition weights.
Retailer private-label sustainability scorecards are consolidating supplier bases and unbundling technical service from resin supply contracts. Walmart and Tesco packaging engineers now mandate recycled content percentages and carbon footprint disclosures ahead of price negotiations. This behavioral shift concentrates volume with converters who have invested in lifecycle assessment capabilities and third-party certification maintenance.
Flexible Film Market Segmentation
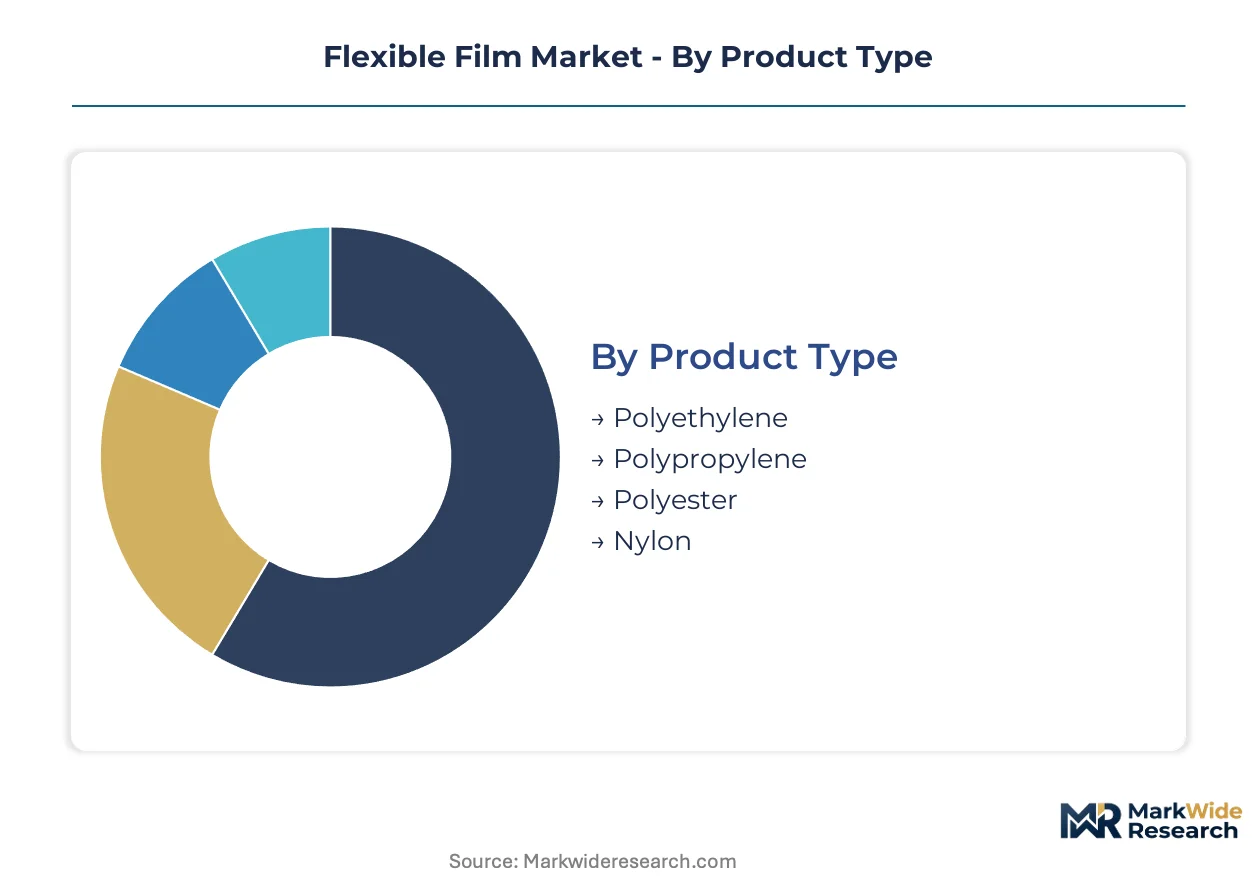
Segmentation in flexible film markets reveals divergent margin structures and service intensity requirements. Converter relationships, technical validation timelines, and regulatory compliance burdens vary sharply across material grades and end-use specifications.
Product Type:
After-sales technical support intensity escalates with material complexity and regulatory exposure, driving converter preference for suppliers with dedicated application engineering teams.
- Polyethylene:Blown and cast extrusion formulations dominate volume through cost scalability and heat-seal reliability. Demand concentrates in North American and European food packaging as EPR mandates force mono-material redesigns, though barrier limitations constrain oxygen-sensitive applications.
- Polypropylene:Biaxially oriented structures deliver stiffness and clarity for snack and confectionery segments. European converters are expanding metallized and ceramic-coated variants to replace aluminum laminates under EU Green Deal packaging waste directives.
- Polyester:PET films command premium positioning through dimensional stability and optical clarity in electronics and medical barrier applications.
- Nylon:Polyamide structures provide puncture resistance and thermoformability for vacuum-packed meats and industrial lidding.
By volume, Polyethylene leads. By growth pace, Polypropylene is ahead.
Application:
Application segmentation tracks directly to capital equipment requirements and validation burden, with medical and electronics demanding specialized cleanroom extrusion assets.
- Packaging:Food, personal care, and industrial wrapping absorb the majority of polyethylene and polypropylene volume. German and French brand owners are accelerating mono-material adoption ahead of EPR compliance deadlines, reconfiguring entire SKU portfolios.
- Electronics:Dielectric films, release liners, and display substrates require ultra-low contamination and precise thickness control. Asian manufacturing clusters in Taiwan and South Korea drive specification intensity for semiconductor and battery applications.
- Agriculture:Greenhouse films, silage wrap, and mulch films prioritize UV stability and mechanical durability over barrier performance.
- Medical:Sterilizable pouches, blister lidding, and fluid bags generate disproportionate margin contribution due to FDA and EU MDR validation requirements.
Packaging captures the largest revenue pool. Medical applications deliver the steepest expansion trajectory.
End User:
End user concentration determines contract structure, with pharmaceutical procurement favoring long-term supply agreements and technical partnership clauses.
- Food & Beverage:Brand technical teams are collapsing qualification timelines for recyclable structures while maintaining shelf-life performance. Major retailers in the United Kingdom and Netherlands now mandate recycled content disclosures ahead of price negotiations.
- Consumer Goods:Cosmetics and household product packaging prioritizes printability and tactile surface finish over barrier specifications.
- Pharmaceuticals:Unit-dose and bulk packaging for solid and liquid dosage forms requires extractables-leachables documentation and stability validation.
- Industrial:Construction membranes, protective films, and logistics wrapping prioritize tear resistance and cost minimization.
Food & Beverage commands the greatest volume. Pharmaceuticals is expanding most quickly.
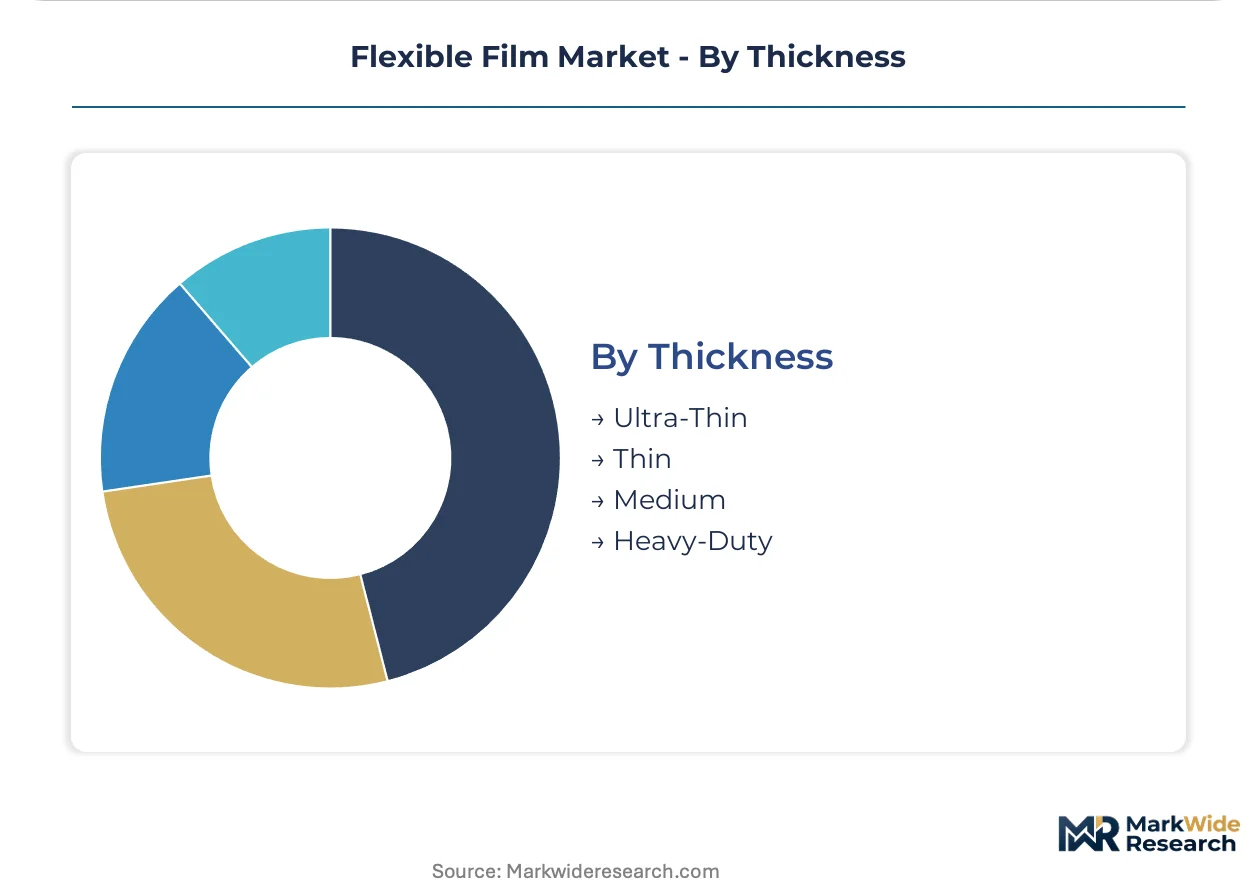
Thickness:
Thickness segmentation governs extrusion line configuration and downstream converting compatibility, with ultra-thin films requiring specialized winding and tension control systems.
- Ultra-Thin:Sub-20 micrometer structures enable material reduction in label and tape applications. Japanese electronics manufacturers are driving specification tightening for capacitor and battery separator films.
- Thin:20-50 micrometer grades balance processability with downgauging economics in snack and confectionery wrapping.
- Medium:50-120 micrometer films serve general-purpose packaging and industrial bundling where puncture resistance matters.
- Heavy-Duty:Above-120 micrometer structures deliver structural integrity for pallet wrap, construction membranes, and agricultural greenhouse applications.
Medium thickness grades dominate current output. Ultra-Thin specifications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion capacity concentrates in manufacturing clusters where feedstock access, converter density, and regulatory proximity intersect. Germany, the United States, China, India, and Vietnam each anchor distinct supply chain configurations shaped by local EPR enforcement and resin import dependencies.
Germany
EPR compliance deadlines under the Packaging Act are forcing mono-material redesigns across food and personal care SKUs. ECHA REACH authorization timelines for recycled content additives extend qualification cycles. The Rhine-Ruhr industrial corridor hosts blown film extrusion lines serving pan-European brand technical teams.
United States
California's SB 54 mandates obligate brands to fund collection infrastructure ahead of federal alignment. FDA food-contact Letters of No Objection for mechanically recycled polyethylene remain the binding constraint on circular packaging launches. The Gulf Coast petrochemical corridor supplies ethylene feedstock to extrusion converters in Texas and Louisiana.
China
Dual carbon goals are accelerating investments in bio-based polyethylene pilot plants alongside mechanical recycling scale-up. SAMR national standards for food-grade recycled plastics are tightening import competitiveness for non-compliant film. The Yangtze River Delta cluster in Jiangsu and Zhejiang provinces concentrates cast film capacity for electronics and display substrates.
India
BIS certification requirements for food-grade plastics are raising technical barriers for imported film structures. PLI scheme incentives for specialty chemicals are attracting compatibilizer investments supporting mono-material adoption. The Gujarat industrial corridor hosts multi-layer coextrusion lines serving domestic FMCG brands and export markets.
Vietnam
Regional converter migration from China is absorbing new extrusion capacity as supply chain density builds. EU Green Deal packaging waste directives are filtering down to Vietnamese export-oriented manufacturers through buyer compliance requirements. The northern manufacturing belt around Hanoi and Hai Phong is accumulating blown film assets for ASEAN-bound food packaging.
Flexible Film Market Vendor Landscape
Integrated resin-to-film conglomerates and specialized converter networks split the market along capital intensity and technical service vectors. The vendor base stratifies into three archetypes: backward-integrated multinationals controlling compounding assets, regional converters scaling through multi-site manufacturing, and specialty players occupying barrier technology niches. Dominant competitive moves include capacity expansion in Vietnam and India to capture regional demand, and strategic partnerships between resin suppliers and recycling technology providers to secure circular feedstock pipelines.
Among backward-integrated multinationals, Amcor Limited and Berry Global Group exemplify the archetype of resin-to-film control. Mondi Group occupies a position bridging specialty kraft-polymer hybrid structures with paper-reduction mandates. These three anchors represent distinct strategic postures: captive feedstock quality assurance, multi-site manufacturing scale, and material hybridization for regulatory substitution.
| Leading Market Players |
|---|
| Amcor Limited |
| Berry Global Group |
| Mondi Group |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Uflex Limited |
| Sonoco Products Company |
| Coveris Group |
| Transcontinental Inc. |
| Others |
Supply Flow & Price Mechanics
Blown film extrusion overcapacity in Vietnam and India is compressing converter margins while simultaneously accelerating supplier consolidation and pricing discipline among integrated resin producers.
Pricing Analysis
Aftermarket recycling and collection service revenue drives lifetime value across converter relationships. Pricing stratifies across premium, standard, and economy tiers based on barrier certification grade and volume commitment scale. Cost compression in standard-grade polyethylene is intensifying because of naphtha feedstock volatility and Asian import competition. Industrial packaging buyers exhibit highest price sensitivity, while pharmaceutical and medical device procurement teams prioritize validation documentation over unit cost.
Supply Chain Analysis
Extended payment terms from resin suppliers to Vietnamese and Indian converters are restructuring working capital requirements across the value chain. Feedstock supply concentrates in Saudi Arabia, the United States, and China for ethylene and polyethylene resin. Raw material sourcing draws from naphtha crackers, natural gas liquids, and emerging bio-ethanol feedstocks. Single-source vulnerability persists for specialty polyamide and EVOH barrier resins. Distribution runs through regional converter hubs in Germany, Texas, and Jiangsu province before final specification to brand technical teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible film procurement is shifting toward platform-based supplier scorecards where digital lifecycle tracking and EPR compliance data interoperability determine contract awards.
For Market Incumbents: Build captive recycling infrastructure moats through mechanical and chemical recycling asset control. Berry Global Group and Amcor Limited anchor defensive positioning via backward integration into resin compounding. Threat from emerging Asian converters with state-subsidized capacity requires response through FDA and EFSA food-contact certification investment in North American and European plants. For New Entrants and Emerging Players: Vietnamese and Indonesian pharmaceutical packaging white-space offers penetrable entry points. Medical-grade barrier films for unit-dose applications face limited domestic competition and extended validation timelines protect early movers. Go-to-market leverage rests on partnering with European brand technical teams seeking ASEAN manufacturing alternatives to China supply concentration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemical recycling and compatibilizer technology sub-segments. Five-to-ten year viability favors converters with integrated recycling pipelines over pure extrusion plays. Acquisition target archetype: regional European converters with EPR compliance infrastructure and established brand relationships. Signal to monitor: FDA Letters of No Objection issuance velocity for mechanically recycled food-contact applications.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Pyrolysis investments in Rotterdam and Texas valorize mixed-film waste streams mechanically sorting cannot process. |
| Backward Integration into Resin Compounding | Amcor Limited secures feedstock quality control and reduces virgin resin price exposure through captive compounding assets. |
| Digital Watermark Integration | Digimarc and Polytag markers enable automated sorting line recognition of food-grade versus non-food polyethylene films. |
| Multi-Site Manufacturing Expansion | Berry Global Group anchors North American blown film capacity through geographic diversification and scale economies. |
| Bio-Based Feedstock Qualification | L'Oréal and Unilever procurement teams compress qualification timelines for sugarcane ethanol-derived polyethylene. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association reports. Conversations with blown film plant managers, resin procurement leads at major converters, distribution channel partners, and brand technical packaging directors inform demand-side validation. Secondary sources include FDA food-contact notifications, ECHA REACH substance dossiers, EU Packaging and Packaging Waste Directive implementation reports, and SEC 10-K disclosures from listed packaging conglomerates. Bottom-up capacity and production estimates triangulate against top-down demand modeling across end-use segments.
Forecast inputs incorporate extrusion line capacity utilization, EPR mandate implementation timelines, and resin price trajectory assumptions across the analysis window. Segmentation dimensions include material type, thickness grade, application category, and regional regulatory cluster. CAGRs derive from slope-intercept modeling of historical production data against projected demand elasticity. Industry-specific inputs include mechanical recycling infrastructure build-out schedules and food-contact certification approval velocities.
Macroeconomic conditions sit as an overlay; deviation in ethylene feedstock costs, currency exchange rates, or trade tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
GCC Flexible Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market