
 Japan POS Terminals Market | 2026-2036
Japan POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Japan POS Terminals Market Foresight
Aftermarket service revenue is reconfiguring profit pools across the Japan POS Terminals Market as hardware margins compress and software subscriptions expand. Toshiba Global Commerce Solutions leverages its installed base in Japanese convenience retail to sustain recurring maintenance contracts. NEC Corporation anchors its position through deep integration with domestic banking networks. Fujitsu competes by specializing in ruggedized terminal designs for high-traffic transportation hubs.
Japan POS terminals encompass electronic payment processing devices featuring EMV chip readers, NFC antennas, thermal printers, and ARM-based processors operating at 1.2–2.0 GHz, engineered to authenticate transactions and transmit encrypted data to acquiring banks. Mobile terminals command premium positioning as ramen chains and food trucks prioritize countertop flexibility over fixed installations. Cloud-based deployment architectures are displacing on-premises server rooms, with hybrid configurations capturing mid-market retailers seeking staged migration paths. Self-service kiosks face slower uptake in Japan's service-oriented hospitality sector where staff-assisted checkout remains culturally preferred.
METI's Cashless Vision policy mandates fee reductions and consumer rebates, directly shaping terminal procurement timelines across retail and food service sectors. JIS standards govern electromagnetic compatibility and physical durability, while PCI-DSS certification requirements filter non-compliant vendors from payment network access. Stakeholders must monitor whether METI extends subsidy programs beyond current expiration frameworks or shifts toward open-architecture specifications that would reshape vendor competitive dynamics.
Market Dynamics
METI's Cashless Vision policy is compressing terminal replacement cycles across Japanese retail, forcing merchants to accelerate EMV and NFC infrastructure upgrades ahead of hardware end-of-life schedules.
Growth Catalysts
- Contactless payment mandates:JIS standards for electromagnetic compatibility are compelling convenience store chains to deploy NFC-enabled terminals at checkout counters nationwide.
- Greater Tokyo retail density:The capital region's concentrated commercial corridor generates disproportionate terminal demand from high-traffic food service and specialty retail operators.
- Cloud-hybrid architectures:Mid-market merchants are adopting staged migration paths that blend on-premises transaction processing with hosted payment gateways.
Market Restraints
- Semiconductor supply concentration:ARM-based processor sourcing remains vulnerable to fabrication bottlenecks concentrated in East Asian foundry networks.
- Legacy infrastructure lock-in:Existing fixed-installation terminals create physical and software integration friction for mobile-first payment platforms.
- Cultural service preferences:Japan's hospitality sector maintains staff-assisted checkout traditions that suppress self-service kiosk penetration.
Strategic Opportunities
- Rural merchant digitization:Prefectures outside Greater Tokyo exhibit underpenetrated terminal coverage, creating whitespace for mobile POS deployment in regional food trucks and festivals.
- Transportation hub specialization:High-traffic rail stations and airports require ruggedized terminal designs resistant to vibration, humidity, and continuous operation cycles.
- Open-architecture specifications:Potential METI shifts toward interoperable payment standards would dismantle vendor-proprietary ecosystems and enable modular hardware procurement.
Industry Challenges
- PCI-DSS certification timelines:Payment card industry compliance audits create 6-12 month vendor qualification delays that bottleneck product launches.
- Legacy system integration:Merchants operating decades-old inventory management platforms face middleware complexity when connecting modern terminals to back-office infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan POS Terminals Market |
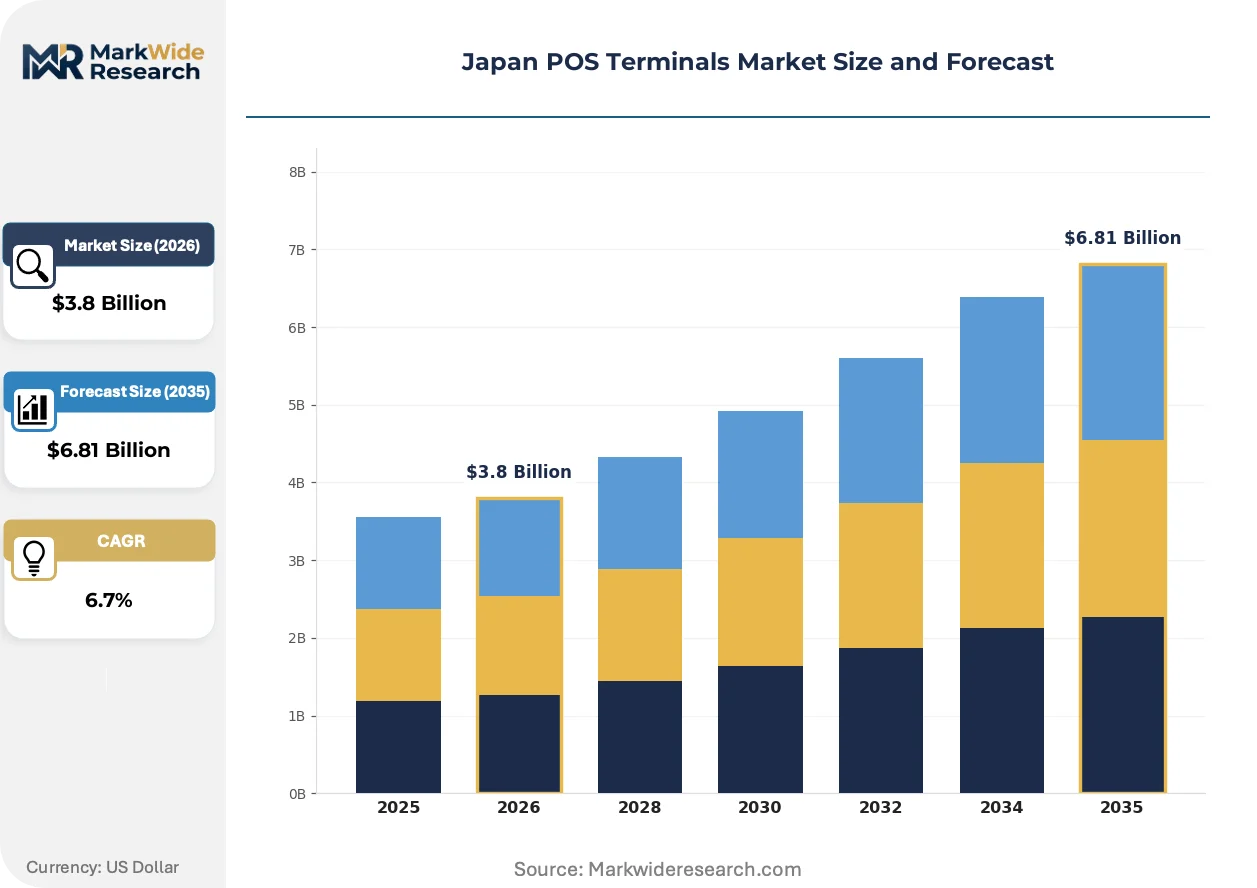
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Terminals, Mobile Terminals, Self-Service Kiosks, Integrated Terminals Technology: Bulletin Boards, NFC, EMV, Cloud-Based End User: Retail, Hospitality, Transportation, Healthcare Deployment: On-Premises, Cloud, Hybrid, Software as a Service |
| Companies Covered | PAX Global Technology, Sunmi, Toshiba Global Commerce Solutions, NEC Corporation, Shenzhen Jassway Infotech, NCR Voyix, Samsung Electronics, Diebold Nixdorf, Fujitsu, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan POS Terminals Market Shifts & Advancements
Payment infrastructure across Japan is undergoing simultaneous hardware miniaturization and software unbundling, with terminal form factors shrinking while backend services fragment into specialized subscription modules.
SoftPOS technology is digitizing smartphone-based transaction acceptance by converting standard mobile devices into payment terminals through downloadable applications and NFC antenna peripherals. Ramen chains and independent food vendors in Osaka and Fukuoka are adopting these platforms faster than fixed-counter alternatives. This shift is digitizing merchant onboarding velocity and collapsing the traditional hardware distribution channel.
METI's Cashless Vision framework mandates interchange fee reductions and consumer rebate programs that directly compress merchant acquisition costs. Retail procurement committees are advancing terminal replacement timelines to capture subsidy windows before program expiration. Convenience store headquarters in Tokyo and Yokohama are consolidating vendor relationships to negotiate volume-based service bundles.
After-sales service unbundling is fragmenting the traditional hardware-maintenance contract model. Mid-tier retailers in Nagoya and Sapporo are separating terminal procurement from technical support, sourcing devices through distributors while contracting independent IT service providers for software updates and troubleshooting. This purchasing pattern is most visible among specialty apparel and cosmetics merchants with limited in-house technical staff.
Japan POS Terminals Market Segmentation
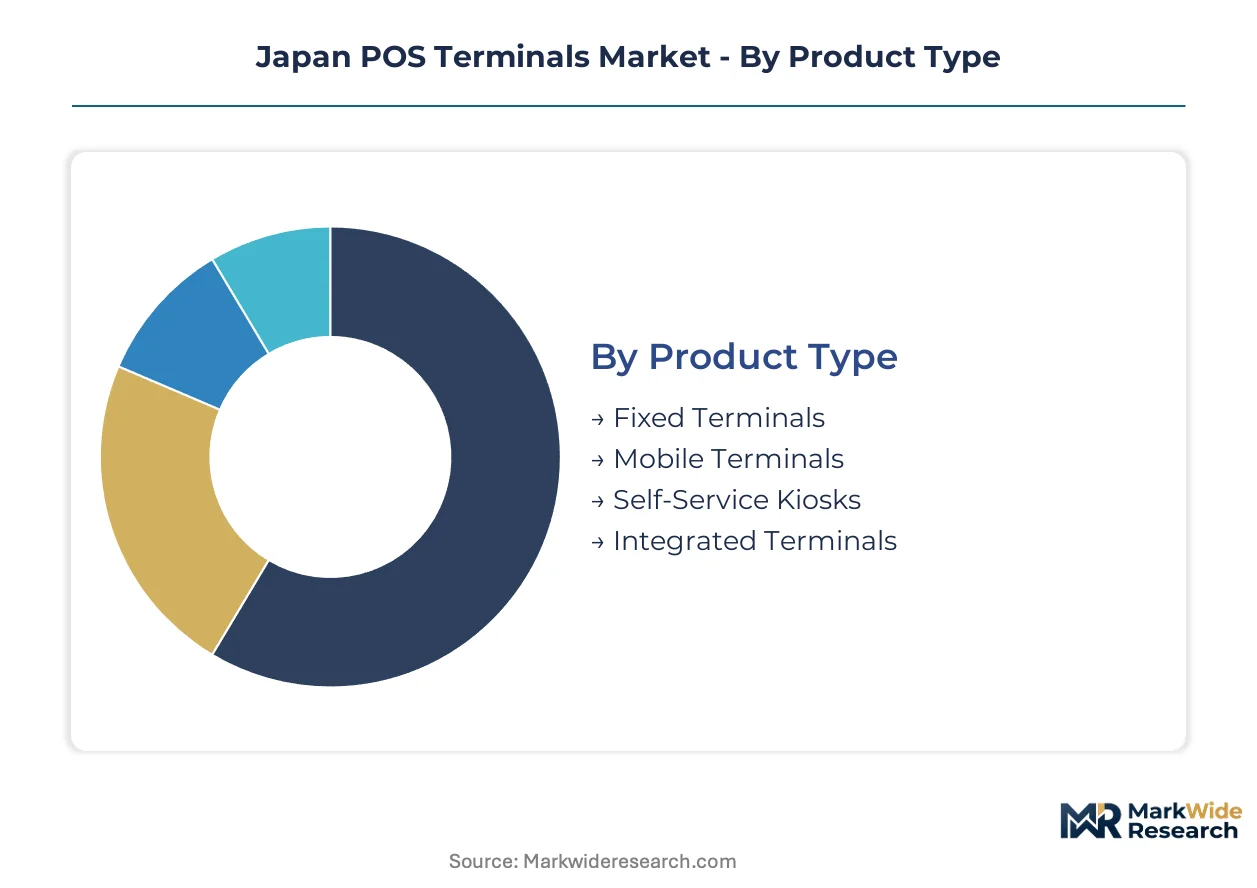
Japan's POS terminal segmentation reveals distinct procurement patterns across hardware form factors, payment protocols, and operational architectures. Understanding these divisions clarifies how METI policy incentives and merchant operational constraints reshape vendor competitive positioning.
Product Type:
Convenience store chains and food service operators deploy terminals across a use-case spectrum from fixed countertop installations to handheld mobile units for queue-busting flexibility.
- Fixed Terminals:Countertop-mounted devices with integrated thermal printers, EMV chip readers, and NFC antennas operate at 1.2–2.0 GHz on ARM-based processors. Lawson and 7-Eleven headquarters in Greater Tokyo specify these for high-throughput checkout lanes where transaction speed dominates procurement criteria.
- Mobile Terminals:Battery-powered handheld units connect via Wi-Fi or cellular networks to enable tableside or curbside payment acceptance. Ramen chains in Osaka and Fukuoka prioritize these for countertop flexibility over fixed installations, accelerating deployment in food truck and festival merchant categories.
- Self-Service Kiosks:Large-format touchscreen units with integrated payment modules face cultural headwinds in Japan's service-oriented hospitality sector.
- Integrated Terminals:All-in-one systems combining payment processing with inventory management and customer loyalty functions target mid-market retailers seeking consolidated vendor relationships.
The dominant share belongs to Fixed Terminals, while Mobile Terminals is closing the gap fastest.
Technology:
Payment authentication protocols stratify across hardware generations, with newer standards displacing legacy magnetic stripe infrastructure under regulatory pressure.
- NFC:Near-field communication antennas enable contactless card and smartphone wallet transactions at distances under 4 centimeters. METI's Cashless Vision mandates drive replacement of non-compliant terminals at convenience store chains nationwide, compressing procurement timelines.
- EMV:Europay-Mastercard-Visa chip card standards govern physical card authentication through cryptographic verification. Domestic banking networks require EMV certification for terminal network access, filtering non-compliant hardware from payment ecosystems.
- Cloud-Based:Hosted transaction processing architectures displace on-premises server rooms, with hybrid configurations capturing mid-market retailers seeking staged migration paths.
- Bulletin Boards:Legacy display systems for transaction confirmation remain embedded in older terminal generations facing replacement cycles.
NFC commands the largest installed base, though Cloud-Based architectures are expanding most quickly among new deployments.
End User:
Merchant sector requirements diverge sharply between high-volume retail corridors and specialized service environments with distinct transaction patterns.
- Retail:Department stores, convenience chains, and specialty merchants in Greater Tokyo's dense commercial corridor generate disproportionate terminal demand. High-traffic food service and cosmetics operators prioritize transaction throughput and receipt printing speed.
- Hospitality:Hotels, restaurants, and cafes maintain staff-assisted checkout traditions that suppress self-service kiosk penetration. Cultural preferences for personal service create friction for automated payment adoption.
- Transportation:Rail stations and airports require ruggedized terminal designs resistant to vibration, humidity, and continuous operation cycles.
- Healthcare:Clinics and pharmacies face distinct PCI-DSS compliance requirements for patient payment data protection.
Retail holds the dominant share, while Transportation is gaining share fastest due to infrastructure modernization at major hubs.
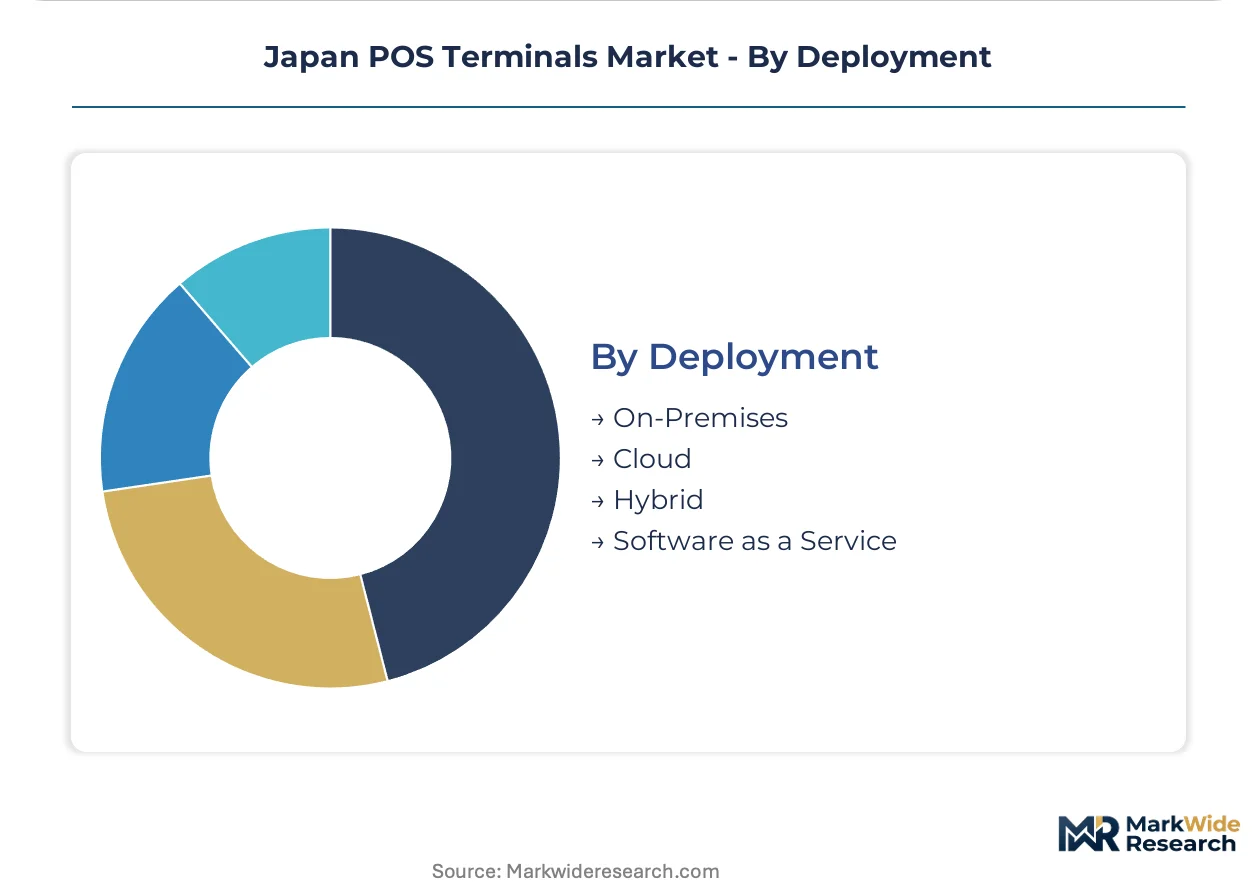
Deployment:
Operational architecture choices reflect merchant technical sophistication, capital constraints, and risk tolerance for data sovereignty.
- Hybrid:Configurations blending on-premises transaction processing with hosted payment gateways capture mid-market retailers seeking staged migration paths. Nagoya and Sapporo specialty merchants with limited in-house technical staff favor this approach.
- Cloud:Fully hosted architectures eliminate local server maintenance but require reliable connectivity and trust in vendor data handling.
- On-Premises:Legacy server-room installations persist among merchants operating decades-old inventory management platforms facing middleware complexity.
- Software as a Service:Subscription-based terminal management bundles hardware, software updates, and technical support into recurring contracts.
Hybrid deployments lead current procurement, though Software as a Service is climbing the fastest as merchants separate device acquisition from support obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's POS terminal consumption concentrates in metropolitan corridors where retail density and policy incentives intersect, while peripheral prefectures exhibit divergent deployment patterns shaped by merchant scale and infrastructure maturity.
Kanto/Tokyo
Convenience store headquarters and high-traffic food service operators in Greater Tokyo drive disproportionate terminal demand. METI's Cashless Vision subsidies compress procurement timelines for EMV-NFC upgrades. Shibuya and Shinjuku retail clusters prioritize transaction throughput and receipt printing speed in lane-heavy configurations.
Kansai/Osaka
Ramen chains and independent food vendors accelerate mobile terminal adoption for countertop flexibility. Osaka's merchant ecosystem favors SoftPOS platforms over fixed installations. Dotonbori and Umeda entertainment districts generate concentrated demand for handheld queue-busting units.
Chubu/Nagoya
Mid-market specialty retailers adopt hybrid cloud-on-premises architectures for staged migration paths. Nagoya-based merchants separate terminal procurement from technical support contracts. Sakae and Nagoya Station retail corridors exhibit growing Software-as-a-Service bundling preferences.
Kyushu
Fukuoka's food truck and festival merchant categories represent underpenetrated whitespace for mobile POS deployment. Regional banking networks require EMV certification for terminal network access. Tenjin and Hakata districts show emerging demand for ruggedized designs resistant to humidity.
Hokkaido
Sapporo's hospitality sector maintains staff-assisted checkout traditions that suppress self-service kiosk penetration. Winter tourism peaks create seasonal terminal demand spikes from temporary retail installations. Susukino entertainment district operators prioritize reliable connectivity for cloud-hosted transaction processing.
Japan POS Terminals Market Competitive Landscape
Capability concentration sits with domestic system integrators; scale advantage sits with international hardware fabricators. The vendor base stratifies across three tiers: banking-network specialists, retail-focused solution providers, and component-scale manufacturers. Two strategic archetypes dominate competitive positioning: installed-base leverage through recurring maintenance contracts, and modular hardware procurement enabled by open-architecture specifications. Competitive moves center on vendor consolidation for volume-based service bundles and cloud-hybrid platform development for mid-market staged migration.
Within the domestic specialist tier, Toshiba Global Commerce Solutions and NEC Corporation exemplify contrasting positioning strategies. Toshiba leverages convenience retail relationships for recurring service revenue. NEC anchors through banking network integration. PAX Global Technology represents the international hardware fabricator archetype with component-scale manufacturing advantages.
| Leading Market Players |
|---|
| PAX Global Technology |
| Sunmi |
| Toshiba Global Commerce Solutions |
| NEC Corporation |
| Shenzhen Jassway Infotech |
| NCR Voyix |
| Samsung Electronics |
| Diebold Nixdorf |
| Fujitsu |
| Others |
Supply & Pricing Matrix
The Yokohama-Osaka freight corridor anchors terminal distribution economics, with containerized shipping rates from East Asian fabrication hubs directly shaping landed cost differentials between domestic banking-network specialists and international hardware fabricators. This logistics backbone compresses margin buffers for vendors lacking scale advantages while enabling volume-based procurement committees at Tokyo convenience store headquarters to extract service bundling concessions.
Pricing Analysis
Long-term service contracts dominate procurement relationships, with three-tier pricing structure across premium, standard, and economy levels anchored by after-sales bundling intensity and PCI-DSS certification grade. Price differentiation separates NEC's banking-integrated premium tier from PAX Global Technology's component-scale standard offerings and Shenzhen Jassway's economy segment. Cost compression in the economy tier is intensifying because SoftPOS platforms eliminate hardware acquisition entirely. Regional food truck merchants in Fukuoka exhibit highest price sensitivity, while Tokyo convenience chains prioritize throughput reliability over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Taiwanese and South Korean foundries holding ARM-based processor capacity, while Japanese domestic assemblers manage final integration and JIS compliance testing. Component sourcing draws from Chinese thermal printer mechanisms, Malaysian NFC antenna substrates, and domestic firmware development. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through authorized domestic system integrators with banking network certification relationships, bypassing direct merchant sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
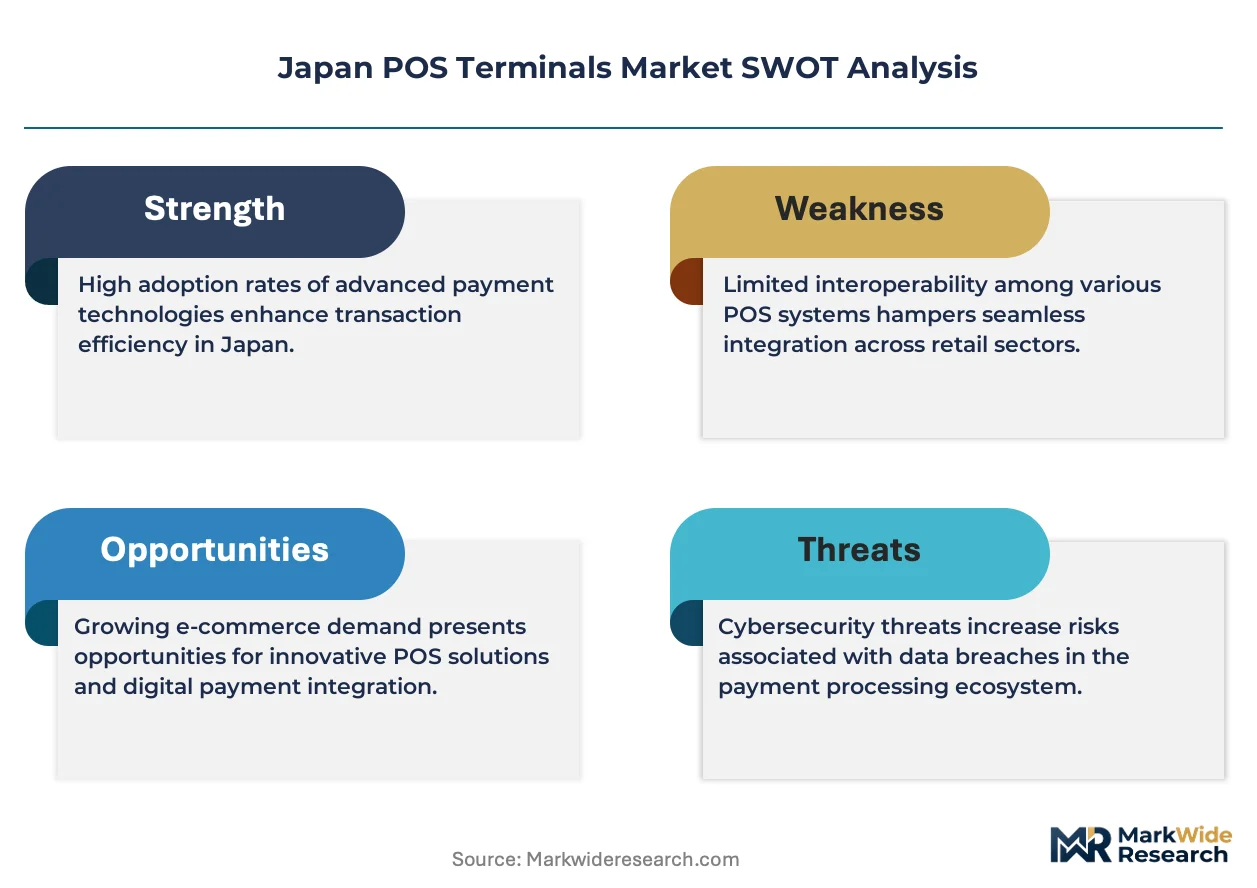
Deep banking network integration and METI compliance navigation constitute scarce capabilities that constrain competitive entry, with only a handful of domestic specialists possessing simultaneous JIS certification authority and acquiring bank relationships.
For Market Incumbents: Insulate recurring revenue streams by embedding software subscription modules deeper into merchant inventory management workflows, defending against SoftPOS disintermediation. Accelerate backward integration into cloud-hosted payment gateway infrastructure to capture mid-market hybrid migration spend. Prioritize PCI-DSS certification investment velocity to maintain vendor qualification timelines that bottleneck emerging competitors. For New Entrants and Emerging Players: Kyushu's festival merchant categories and Hokkaido's seasonal tourism retail installations represent underpenetrated whitespace where mobile-first deployment avoids fixed-infrastructure competition. Target Fukuoka food truck operators with SoftPOS platforms that collapse hardware distribution overhead entirely. Pursue direct relationships with regional banking networks outside the three megabank orbit to circumvent incumbent certification gatekeeping. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with dormant POS terminal divisions lacking standalone scale. Long-term viability hinges on software revenue mix expansion rather than hardware shipment volume. Monitor METI open-architecture specification signals as inflection indicator that would dismantle proprietary ecosystem advantages and enable modular procurement disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Hybrid Platform Integration | Captures Nagoya mid-market merchants seeking staged migration from legacy on-premises infrastructure. |
| SoftPOS Technology Licensing | Enables Osaka ramen chains to convert standard smartphones into payment terminals without hardware distribution. |
| Transportation Hub Specialization | Addresses Shinjuku Station and Haneda Airport requirements for vibration-resistant ruggedized terminal designs. |
| After-Sales Service Unbundling | Matches Sapporo specialty retailer preference for separating device procurement from independent IT support contracts. |
| Rural Merchant Digitization Partnership | Penetrates prefectural banking networks outside Greater Tokyo with mobile POS deployment for festival and food truck categories. |
Research Methodology
A standing panel of terminal procurement managers at convenience store headquarters, acquiring bank technology officers, regional food service operators, and METI policy implementation leads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against PCI-DSS certification databases, JIS standards documentation, and customs records of terminal component imports. Bottom-up merchant deployment estimates triangulated against top-down banking network terminal count disclosures.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning hardware form factor, payment protocol generation, deployment architecture, and end-user sector concentration. CAGRs derived from installed base replacement cycle analysis incorporating METI subsidy program windows and EMV-NFC compliance mandates. Forecast inputs included convenience store expansion timelines, SoftPOS adoption velocity in Osaka and Fukuoka, and transportation hub modernization schedules.
Practitioners should monitor METI subsidy extension decisions, open-architecture specification shifts, and semiconductor foundry capacity allocation for early signals of forecast revision. Cross-checking against acquiring bank terminal certification queue data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
China Forex Cards Market
Payments
China POS Terminals Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Transaction Monitoring Market
Payments
Latin America Mobile Payment Market
Payments
Direct Carrier Billing Platform Market
Payments
Malta POS Terminal Market
Payments
Global Smart Payment Systems Market
Payments
China Payment Gateway Market
Payments
China Payments Market
Payments
Global Payments As a Service Market
Payments
North America Accounts Payable Automation Market
Payments
GCC Mobile Payment Market
Payments
Asia-Pacific Digital Remittance Market
Payments
Egypt Mobile Payments Market
Payments
Cloud Billing Market