
 Bitcoin Payments Market | 2026-2036
Bitcoin Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Bitcoin Payments Market Analysis
ISO 22224 certification for blockchain-based payment interoperability is reorganizing competitive access across the Bitcoin payments landscape. BitPay leverages its first-mover infrastructure to sustain merchant gateway dominance in North American markets. BVNK anchors its position through banking-license-backed settlement rails that bridge fiat and crypto liquidity. Stripe competes by embedding Bitcoin checkout into its existing merchant stack without requiring dedicated crypto wallets.
Bitcoin payments denote value transfer executed on the Bitcoin blockchain using native or layer-2 settlement protocols, typically confirmed through proof-of-work consensus with finality times averaging ten minutes per block and primary commercial purpose of disintermediating cross-border remittance and merchant settlement costs. Online payment gateways command the deepest margin pools due to SaaS-like recurring integration fees, while cross-border transactions represent the fastest-expanding transaction type as correspondent banking delays drive demand for near-instant settlement. Merchant transactions remain the volume backbone, though micropayments show emerging traction in content monetization and machine-to-machine use cases.
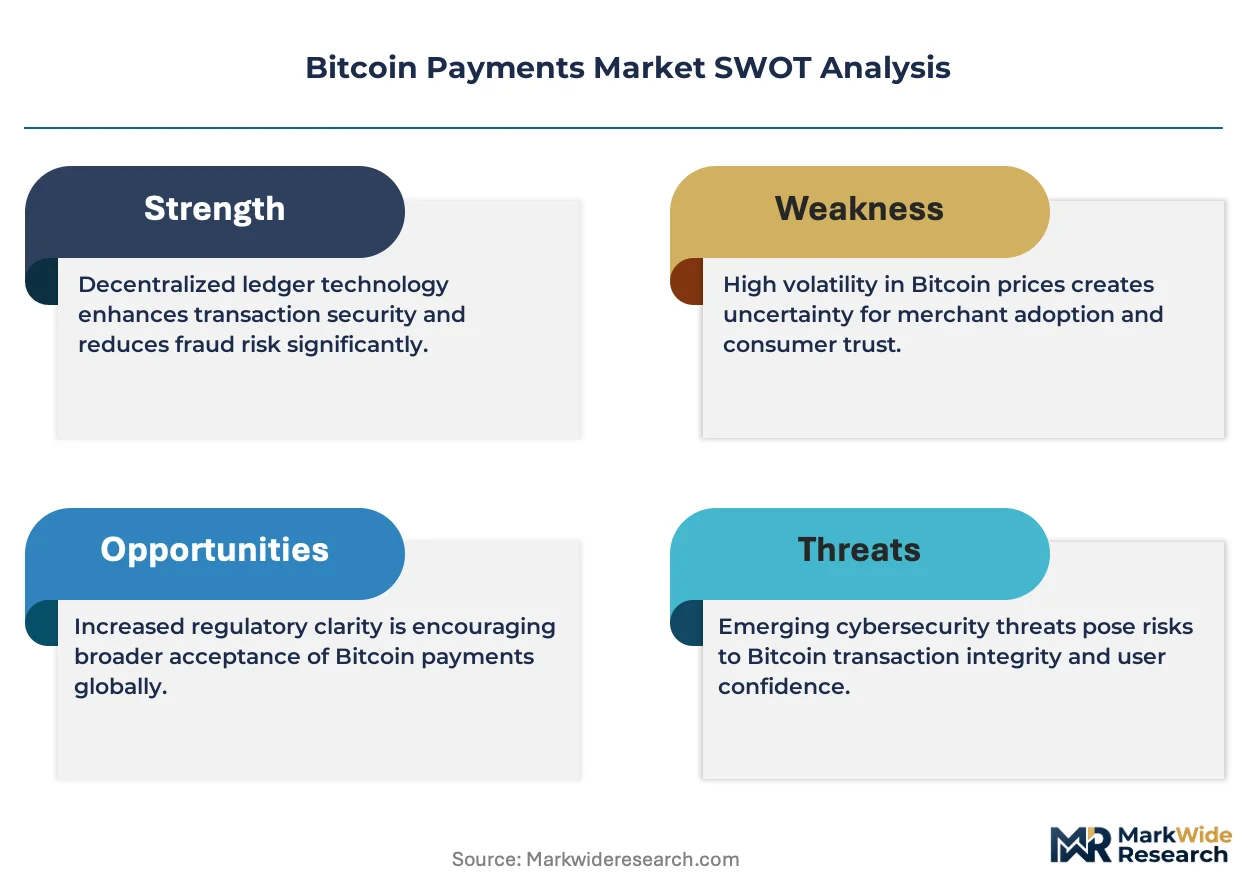
The Financial Crimes Enforcement Network, the European Banking Authority, and the Financial Conduct Authority each impose distinct know-your-customer and anti-money-laundering frameworks that fragment compliance architecture and inflate operational costs for multi-jurisdictional processors. MiCA's uniform licensing regime across EU member states will consolidate market access requirements and disadvantage non-compliant offshore platforms. Stakeholders must monitor evolving central bank digital currency interoperability standards that could either cannibalize or complement Bitcoin settlement demand.
Market Dynamics
ISO 22224 certification for blockchain payment interoperability is fragmenting competitive access by erecting technical barriers that favor established infrastructure providers over emerging entrants, forcing processors to rebuild settlement architectures around standardized messaging protocols.
Growth Catalysts
- MiCA Licensing Regime:The EU Markets in Crypto-Assets regulation consolidates market access requirements across member states, reducing compliance fragmentation for payment processors seeking European expansion.
- Layer-2 Settlement Protocols:Lightning Network integration compresses confirmation times from ten minutes to milliseconds, unlocking micropayment use cases in content monetization and machine-to-machine transactions.
- Cross-Border Remittance Demand:Correspondent banking delays in emerging markets drive merchant and consumer migration toward near-instant Bitcoin settlement rails for international value transfer.
Market Restraints
- Energy Input Volatility:Proof-of-work consensus ties operational costs to electricity price swings in mining-dependent jurisdictions, compressing processor margins during supply shocks.
- Multi-Jurisdictional Compliance Architecture:Divergent know-your-customer frameworks from FinCEN, the European Banking Authority, and the Financial Conduct Authority inflate operational overhead for cross-border platforms.
- Central Bank Digital Currency Substitution:Wholesale CBDC pilots in major economies threaten to cannibalize Bitcoin's cross-border settlement value proposition for institutional payment flows.
Strategic Opportunities
- Machine-to-Machine Payments:Internet-of-Things device integration creates automated settlement demand for autonomous vehicle tolling, smart grid energy trading, and supply chain sensor networks.
- Banking-License-Backed Settlement Rails:EMI and payment institution licensing in jurisdictions like Lithuania and Singapore enables fiat-crypto bridge products with regulatory clarity.
- Embedded Checkout Integration:SaaS platforms without dedicated crypto infrastructure seek white-label Bitcoin payment modules that bypass wallet complexity for end consumers.
Industry Challenges
- Blockchain Forensics Talent Scarcity:Transaction monitoring for anti-money-laundering compliance requires specialized investigators capable of tracing obfuscated on-chain flows.
- Legacy Core Banking Integration:Mainframe-era payment processors face API compatibility failures when connecting Bitcoin settlement rails to decades-old ledger systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitcoin Payments Market |
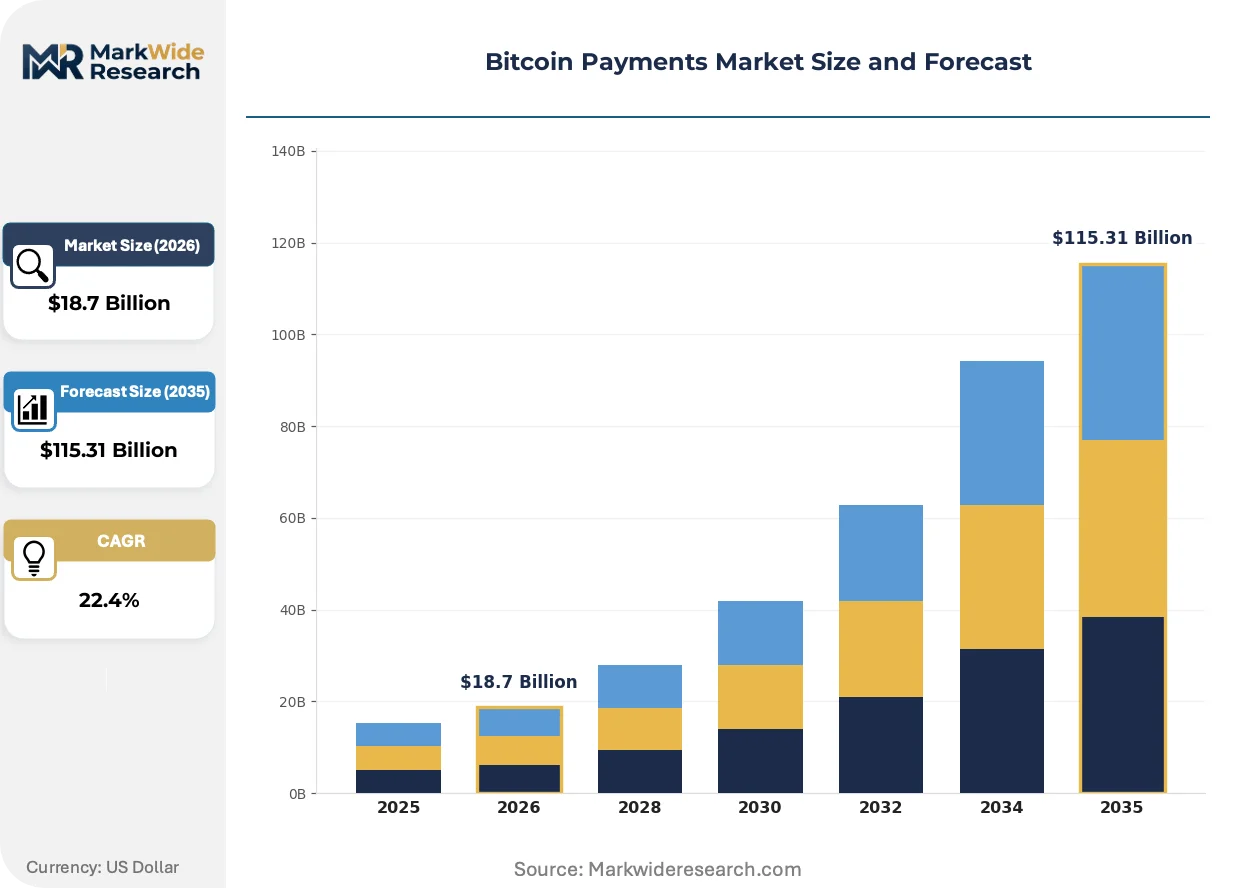
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Digital Wallets, Credit Card, Bank Transfer, Online Payment Gateways Transaction Type: P2P Transactions, Merchant Transactions, Micropayments, Cross-border Transactions End User: Retail Consumers, Online Businesses, Investors, Merchants Integration Type: E-commerce Platforms, POS Systems, Mobile Apps, Payment Processors |
| Companies Covered | Binance Pay, Stripe, BitPay, B2BinPay, Blockonomics, BVNK, Circle, CoinPayments, NOWPayments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitcoin Payments Market Emerging Trajectories
Settlement infrastructure is bifurcating between custodial and non-custodial models, with merchant preferences increasingly shaped by regulatory treatment of private key control rather than transaction speed alone.
Lightning Network channel liquidity management is fragmenting payment routing efficiency across the network. Merchant gateways in high-volume corridors are adopting automated channel rebalancing tools. This technical evolution is compressing the viable operator set to those with substantial bitcoin treasury reserves.
The EU's Markets in Crypto-Assets regulation mandates reserve segregation and operational continuity standards for crypto-asset service providers. Payment processors must restructure custody arrangements and insurance coverage. Large-scale merchant acquirers are absorbing compliance costs through vertical integration of custody functions.
Merchant procurement of Bitcoin payment services is pivoting from standalone gateway contracts toward bundled financial infrastructure. E-commerce platforms are embedding settlement rails into existing treasury management relationships. This consolidation pattern is most visible in the United States, where institutional payment infrastructure investment concentrates platform decision-making.
Bitcoin Payments Market Segmentation
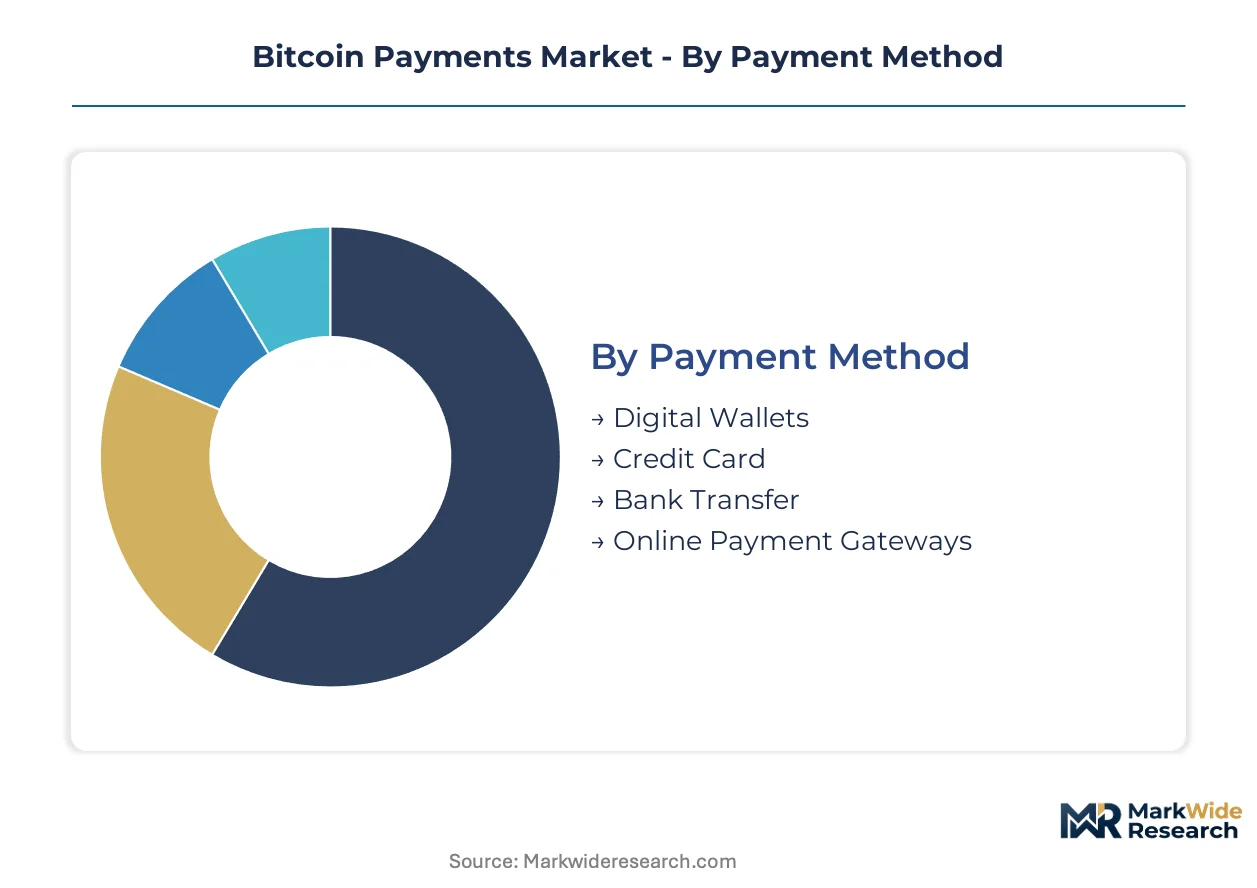
Segmentation in Bitcoin payments reveals how regulatory treatment, settlement speed requirements, and technical integration complexity fragment demand across distinct operational models. Each dimension exposes different margin structures and compliance burdens that reshape competitive positioning.
Payment Method:
FinCEN's money transmitter rules, the EU's MiCA licensing regime, and Singapore's Payment Services Act each impose divergent custody and KYC obligations that reshape how processors architect their payment rails.
- Online Payment Gateways:SaaS-integrated checkout layers that abstract wallet complexity through hosted flows. Demand concentrates among mid-market e-commerce merchants in the United States seeking recurring subscription billing without consumer wallet management. FinCEN's travel rule enforcement elevates compliance costs for cross-border gateway transactions.
- Digital Wallets:Non-custodial and custodial storage applications that initiate Bitcoin transfers through private key signatures or delegated custody. European merchants under MiCA's CASP framework increasingly demand segregated reserve models that disadvantage offshore wallet providers. Self-custody wallets face de-risking by correspondent banks.
- Bank Transfer:Fiat on-ramp rails that settle into Bitcoin through licensed exchanges or banking partners. Lithuania's EMI licensing regime attracts processors seeking euro-denominated bridge products with regulatory clarity.
- Credit Card:Card network rails that convert fiat to Bitcoin at point of sale, subject to chargeback risk and interchange compression. High decline rates from issuing banks limit merchant adoption.
Online Payment Gateways handle the majority of throughput; Micropayments (within Transaction Type) is the fastest mover on share.
Transaction Type:
Settlement finality requirements and value thresholds determine which transaction categories absorb Lightning Network infrastructure investment versus on-chain base layer settlement.
- Cross-border Transactions:International value transfers that bypass correspondent banking delays through Bitcoin settlement rails. Nigerian and Kenyan remittance corridors drive concentrated demand as local currency volatility accelerates merchant migration. Regulatory arbitrage between FinCEN and central bank frameworks fragments compliance architecture.
- Micropayments:Sub-dollar value transfers enabled by Lightning Network channel liquidity. Content monetization platforms and machine-to-machine IoT networks in Germany and South Korea represent emerging demand concentration. Channel rebalancing costs compress viable operator margins.
- Merchant Transactions:Point-of-sale and e-commerce settlements where Bitcoin functions as payment rail rather than speculative holding. Treasury management integration with existing ERP systems determines procurement decisions.
- P2P Transactions:Direct wallet-to-wallet transfers without intermediary processing, typically outside commercial payment processor scope. Regulatory treatment varies sharply across jurisdictions.
Merchant Transactions command the deepest volume base; Micropayments is expanding most quickly as Lightning liquidity management matures.
End User:
Customer sophistication and transaction scale shape procurement patterns from self-serve API integration to bespoke enterprise implementation.
- Merchants:Businesses accepting Bitcoin for goods and services, prioritizing instant fiat conversion to eliminate treasury risk. United States-based retailers with international supplier networks drive gateway procurement decisions.
- Online Businesses:Digital-native enterprises with subscription or marketplace models requiring automated recurring billing. European SaaS platforms under MiCA seek white-label custody solutions.
- Retail Consumers:Individual users initiating Bitcoin payments through mobile applications or browser extensions. Wallet UX friction and private key recovery anxiety suppress conversion rates.
- Investors:Entities utilizing Bitcoin primarily for value storage with incidental payment functionality. Institutional custody requirements diverge from retail payment processor offerings.
Merchants generate the highest transaction throughput; Online Businesses are gaining share fastest as embedded finance models proliferate.
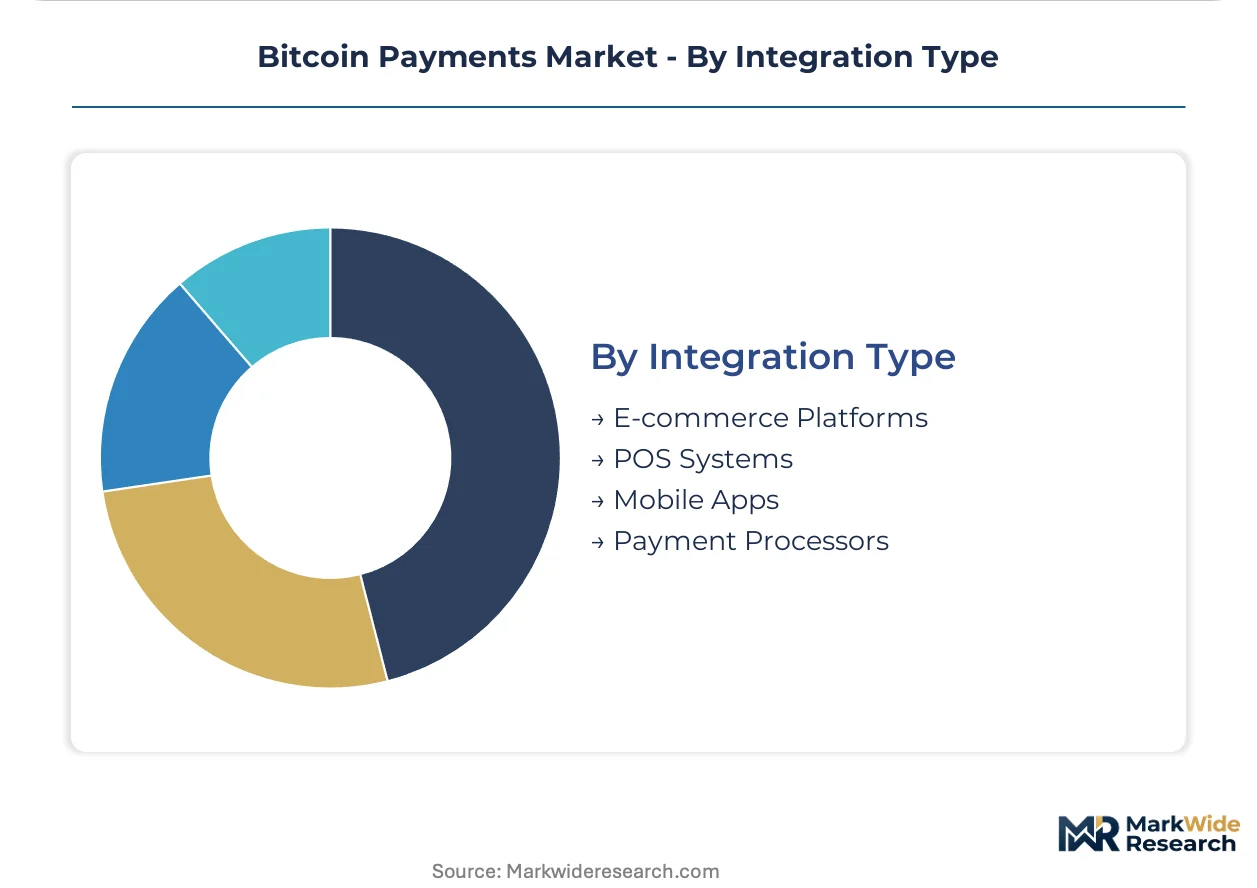
Integration Type:
Technical architecture choices determine whether Bitcoin settlement operates as standalone infrastructure or embedded layer within existing merchant systems.
- E-commerce Platforms:Shopping cart and marketplace integrations that embed Bitcoin checkout without dedicated crypto infrastructure. Shopify and WooCommerce plugin ecosystems in the United States concentrate demand. Platform policy changes on cryptocurrency acceptance create vendor risk.
- Payment Processors:Dedicated Bitcoin-native settlement layers with proprietary custody and compliance stacks. Singapore's PSA licensing attracts processors seeking Asia-Pacific regulatory clarity.
- POS Systems:In-person retail hardware and software accepting Bitcoin through QR codes or NFC. European merchant acquirers under MiCA operational continuity requirements absorb vertical custody integration costs.
- Mobile Apps:Native application SDKs enabling Bitcoin payments within consumer-facing software. Super-app integration in Asian markets diverges from standalone wallet models.
E-commerce Platforms absorb the dominant share of merchant onboarding volume; Payment Processors are climbing the fastest as regulatory licensing consolidates market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant acquirers and e-commerce platforms concentrate procurement decisions in jurisdictions with regulatory clarity on custody and settlement finality. Institutional payment infrastructure investment clusters where central bank frameworks distinguish crypto-asset service providers from traditional money transmitters.
United States
FinCEN's money transmitter rules and state-level BitLicense requirements fragment compliance architecture for cross-border processors. The Financial Crimes Enforcement Network enforces travel rule obligations on virtual asset service providers. New York and California host concentrated gateway provider operations serving mid-market e-commerce merchants.
Germany
BaFin's crypto custody licensing creates regulatory clarity for institutional settlement rails. The Federal Financial Supervisory Authority mandates operational continuity standards under MiCA implementation. Berlin and Frankfurt clusters attract EMI-licensed processors seeking euro-denominated bridge products.
Singapore
The Monetary Authority of Singapore's Payment Services Act consolidates licensing for digital payment token services. MAS frameworks distinguish between custody and non-custodial settlement models. The city-state anchors Asia-Pacific regional operations for processors seeking regulatory passporting across ASEAN markets.
United Kingdom
The Financial Conduct Authority's registration regime for cryptoasset firms imposes anti-money-laundering compliance burdens. FCA operational resilience requirements reshape custody architecture for merchant-facing platforms. London's fintech corridor concentrates white-label payment module providers serving European SaaS platforms.
Switzerland
FINMA's distributed ledger technology guidelines provide interpretive clarity for blockchain-based settlement. The Swiss Financial Market Supervisory Authority distinguishes between payment tokens and asset tokens in regulatory treatment. Zug's Crypto Valley hosts custody infrastructure specialists serving institutional treasury integration.
Bitcoin Payments Market Vendor Landscape
Player mix skews toward banking-license-backed infrastructure providers and SaaS-embedded checkout layers. Market structure concentrates around first-mover gateway dominance in North America and MiCA-compliant licensing plays in Europe. Two strategic archetypes predominate: custody-integrated processors with proprietary settlement rails, and API-first platforms embedding Bitcoin checkout without wallet complexity. Competitive moves center on vertical custody integration and white-label partnership expansion.
Among established infrastructure providers, BitPay exemplifies first-mover gateway dominance through sustained merchant network effects. BVNK occupies a position representing banking-license-backed settlement architecture bridging fiat and crypto liquidity. Stripe sits within the embedded-finance archetype, integrating Bitcoin checkout into existing merchant stacks without dedicated wallet requirements. These three anchors illustrate divergent paths to market access: proprietary custody, regulatory licensing, and platform distribution leverage.
| Leading Market Players |
|---|
| Binance Pay |
| Stripe |
| BitPay |
| B2BinPay |
| Blockonomics |
| BVNK |
| Circle |
| CoinPayments |
| NOWPayments |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with Lightning Network node operators lock in channel liquidity access and fee predictability for high-volume payment processors navigating Bitcoin's volatile on-chain confirmation costs. These arrangements tether settlement pricing to node uptime guarantees while insulating merchants from routing fee spikes during network congestion events.
Pricing Analysis
Cost-plus contracts indexed to mining difficulty adjustments dominate processor-pricing architectures. SaaS-tiered subscription models stratify across premium API tiers with dedicated node infrastructure, standard shared-channel access, and economy self-hosted configurations. Price differentiation rests on settlement speed guarantees and compliance certification level—MiCA-licensed processors command substantial premiums over offshore alternatives. Pricing pressure stems from Lightning Network liquidity commoditization as treasury-rich operators undercut channel leasing rates. Mid-market e-commerce merchants exhibit acute price sensitivity, while institutional treasury departments prioritize regulatory certainty over marginal cost savings.
Supply Chain Analysis
Channel liquidity chokepoints concentrate in United States, Germany, and Singapore node operations where banking-license-backed processors anchor high-capacity payment corridors. Mining hardware supply draws from Taiwan semiconductor foundries, Chinese ASIC manufacturers, and United States energy infrastructure for colocation facilities. Regulatory restriction risk intensifies as FinCEN enforcement and MiCA reserve segregation requirements fragment custody architecture compliance. Distribution runs through API-integrated e-commerce platforms and direct enterprise sales channels serving merchant acquirers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against central bank digital currency settlement rails that threaten to cannibalize Bitcoin's cross-border value proposition for institutional payment flows.
For Market Incumbents: Shield merchant relationships by deepening proprietary custody integration and securing EMI licensing in Lithuania or Singapore to preempt regulatory arbitrage by emerging competitors. Absorb vertical custody costs to maintain gateway dominance as MiCA operational continuity requirements reshape procurement decisions.
For New Entrants and Emerging Players: ISO 22224 certification fast-tracks technical credibility for API-first checkout modules targeting European SaaS platforms underserved by legacy gateway providers. White-label embedded finance partnerships with mid-market e-commerce aggregators represent the most penetrable entry vector.
For Investors and Strategic Acquirers: Capital is best deployed toward banking-license-backed infrastructure providers with established fiat-crypto bridge products and demonstrated regulatory navigation capabilities. Watch wholesale CBDC pilot expansion as the critical inflection signal for Bitcoin settlement demand displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightning Node Infrastructure Expansion | Channel capacity buildout in high-volume corridors compresses settlement latency for merchant gateways. |
| MiCA Compliance Certification | European licensing unlocks passported market access across member state jurisdictions. |
| Banking License Acquisition | EMI authorization enables regulated euro-denominated fiat-crypto bridge products. |
| Embedded Checkout Integration | API partnerships with Shopify and WooCommerce ecosystems bypass wallet complexity friction. |
| Machine-to-Machine Payment Development | IoT sensor network integration captures emerging autonomous settlement demand in smart grid applications. |
Methodological Framework
The analysis maps payment gateway providers, custody infrastructure specialists, and Layer-2 node operators, each validated through payment processor executives, regulatory compliance officers, merchant treasury managers, and blockchain infrastructure engineers. Primary interview findings triangulate against FinCEN guidance documents, MiCA regulatory texts, MAS licensing frameworks, SEC filings from publicly traded crypto service providers, and Lightning Network capacity metrics. Bottom-up merchant adoption estimates reconcile with top-down transaction volume projections.
Consistency checks validate volume and value outputs against node capacity growth trajectories and regulatory licensing expansion patterns across the projection horizon. Segmentation dimensions span payment method, transaction type, end user category, and integration complexity tier. CAGR derivation incorporates mining difficulty adjustment cycles, channel liquidity expansion rates, and merchant onboarding velocity through embedded finance partnerships.
Underlying assumptions cover regulatory enforcement continuity, proof-of-work consensus persistence, and correspondent banking friction persistence, with deviation risk concentrated in wholesale CBDC deployment acceleration and energy input cost volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Netherlands POS Terminal Market
Payments
Digital Payment in Healthcare Market
Payments
Outdoor Payment Terminal Market
Payments
United States Real Time Payments Market
Payments
Bulgaria POS Terminals Market
Payments
Saudi Arabia Buy Now Pay Later Services Market
Payments
United Kingdom Real Time Payments Market
Payments
Latin America Subscription and Billing Management Market
Payments
Consumer Mobile Payment Market
Payments
Wireless POS Terminals Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Enterprise Payment Software Market
Payments
Europe POS Terminal Market
Payments
United States Payment Gateways Market
Payments
Payment Security Software Market
Payments
India Mobile Payments Market