
 Barrel Liner Market | 2026-2036
Barrel Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Barrel Liner Market Outlook
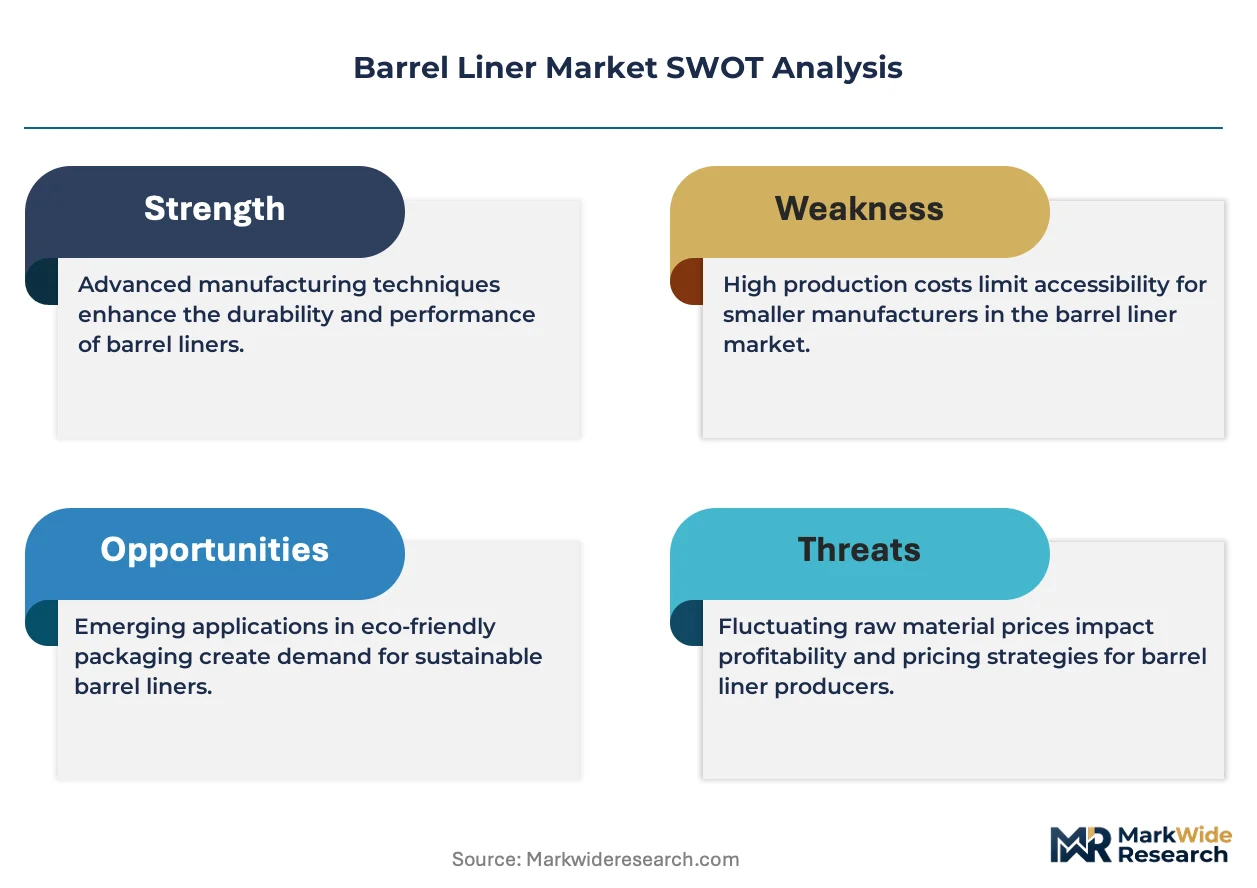
REACH compliance is expanding the cost-of-entry calculus for barrel liner suppliers seeking European chemical accounts. Greif, Inc. leverages its integrated steel drum and liner manufacturing network to control specification consistency across North American industrial channels. Berry Global Inc. anchors its position through blown film extrusion capabilities that sustain tight thickness tolerances for food processing and agricultural end uses. Schütz GmbH & Co. KGaA competes on IBC-to-liner bundling systems that dominate German chemical logistics corridors.
A barrel liner is a flexible, form-fitted insert manufactured from polyethylene, nylon, polypropylene, or PVC, typically extruded or thermoformed to precise thickness tolerances ranging from thin-gauge agricultural grades to extra-heavy chemical containment specifications, designed to protect drum interiors from corrosion, contamination, and product loss during storage and transport. Polyethylene leads product type demand due to its chemical resistance and cost-positioning across industrial and waste management applications, while nylon segments command premium positioning in high-temperature chemical processing where thermal stability determines replacement cycles. Heavy and extra-heavy thickness categories concentrate margin pools as regulatory pressure on hazardous material containment drives specification upgrades across chemical and waste management end uses.
The EPA regulates hazardous waste container requirements under RCRASubtitle C, while REACH governs chemical compatibility and migration testing for European drum-liner combinations, and FDA food contact regulations shape polyethylene and nylon specifications for agricultural and food processing applications in the United States. These frameworks elevate testing documentation burdens and accelerate substitution toward certified material grades that demonstrate compliance traceability. Stakeholders must monitor evolving state-level hazardous waste rules in the US and emerging EU packaging sustainability mandates that could restrict virgin polymer ratios in liner formulations.
Market Dynamics
REACH compliance timelines and EPA Subtitle C enforcement are compressing replacement cycles for barrel liners across chemical processing facilities, forcing specification upgrades that favor certified heavy-gauge polyethylene grades over standard agricultural alternatives.
Growth Catalysts
- RCRA Subtitle C enforcement:US hazardous waste facilities face intensified container integrity inspections, accelerating drum liner procurement for secondary containment compliance.
- German chemical corridor concentration:BASF, Bayer, and Evonik facilities along the Rhine-Ruhr industrial belt generate concentrated demand for extra-heavy nylon liners rated above 120°C processing temperatures.
- Blown film coextrusion advances:Seven-layer barrier films now integrate EVOH and nylon sublayers, extending liner service life in solvent-rich chemical environments by 40-60%.
Market Restraints
- HDPE resin price volatility:Gulf Coast petrochemical feedstock disruptions transmit directly to liner manufacturing costs, compressing margins for non-integrated converters.
- Chinese specialty film concentration:60% of global blown film equipment manufacturing concentrates in Jiangsu and Zhejiang provinces, creating capex access bottlenecks for Western producers.
- Mechanical recycling contamination limits:Post-consumer polyethylene streams fail FDA and EFSA food contact purity thresholds, blocking circular feedstock adoption for agricultural liner segments.
Strategic Opportunities
- India PLI scheme for petrochemicals:Reliance Industries and Indian Oil Corporation are expanding ethylene capacity, creating localized liner resin supply for domestic agrochemical and pharmaceutical packaging growth.
- EU packaging sustainability mandates:Draft regulations capping virgin polymer ratios in industrial packaging above 10,000 units annually incentivize bio-based polyethylene and chemically recycled feedstock development.
- Digital inventory integration:RFID-embedded liners enabling real-time fill-level monitoring are penetrating pharmaceutical cold chain logistics in Switzerland and the Netherlands.
Industry Challenges
- Multilayer film recycling infrastructure gaps:Coextruded barrier liners containing nylon or EVOH layers lack mechanical separation capacity at European recycling facilities, exposing producers to extended producer responsibility fees.
- REACH SVHC testing documentation:Substance of Very High Concern screening now requires third-party certification for each resin batch, extending order fulfillment timelines by 3-4 weeks for European chemical accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrel Liner Market |
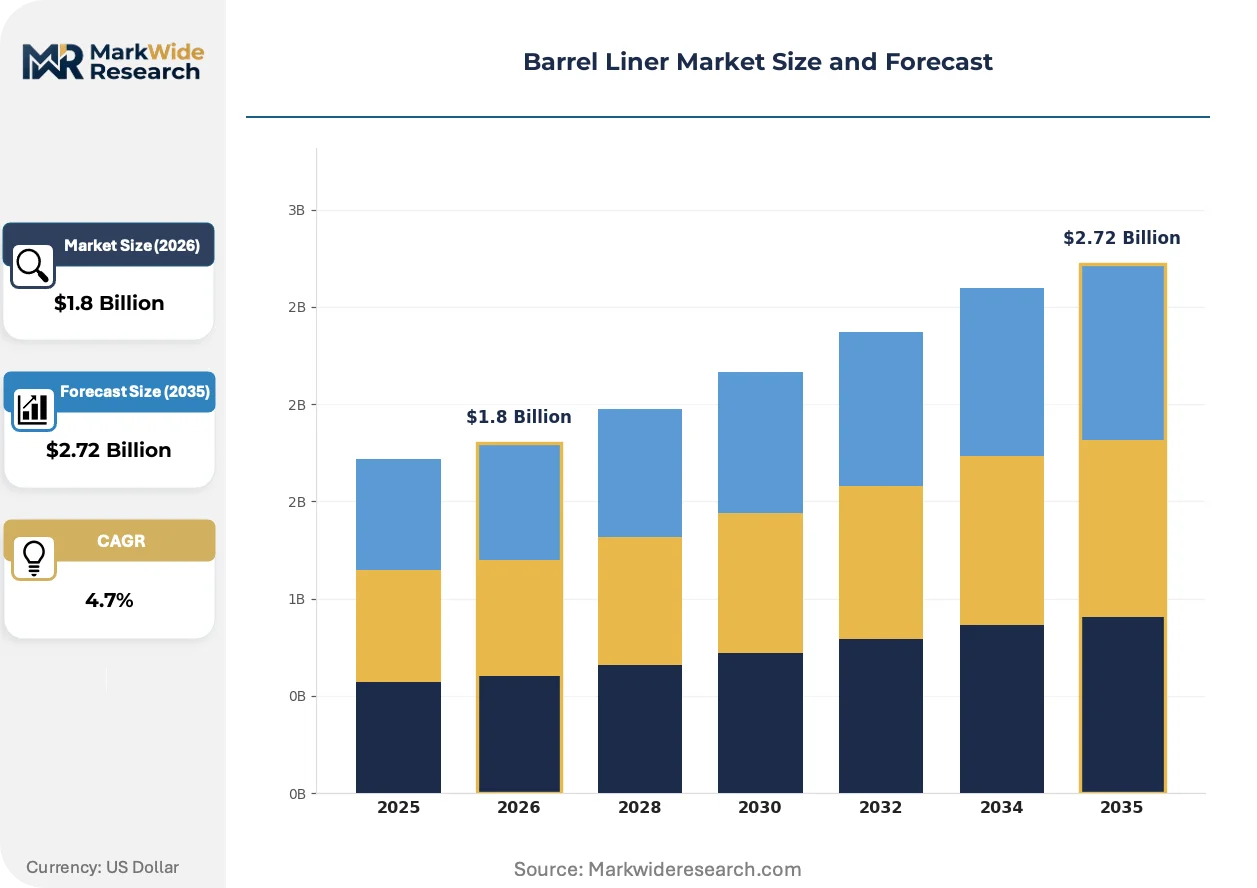
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Nylon, Polypropylene, PVC End Use: Agricultural, Industrial, Chemical, Food Processing Thickness: Thin, Medium, Heavy, Extra Heavy Application: Waste Management, Storage, Transport, Conservation |
| Companies Covered | Greif, Inc., Berry Global Inc., Protective Lining Corp., CDF Corporation, International Plastics, Inc., Amcor Plc, BASCO Inc., Mauser Packaging Solutions, Schütz GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrel Liner Market Strategic Shifts
Material science advances and regulatory traceability requirements are restructuring how barrel liner specifications are negotiated between converters and chemical processors. Three developments are compressing traditional procurement patterns.
Multilayer coextrusion technology is converging with real-time thickness gauging systems to eliminate gauge variation in critical chemical containment applications. German and US Gulf Coast petrochemical facilities now specify maximum 5% thickness tolerance bands for liners handling chlorinated solvents. This precision convergence is displacing single-layer extrusion lines at mid-capacity converters unable to justify seven-layer equipment capex.
REACH Annex XVII restrictions on phthalate plasticizers and short-chain chlorinated paraffins are forcing PVC liner formulations toward bio-based plasticizer alternatives. ECHA substance evaluation timelines compress supplier reformulation windows to 18-24 months. Agricultural and food processing end-uses in France and Italy are responding fastest, substituting toward polyethylene alternatives where thermal constraints permit.
Chemical processors are consolidating vendor lists around integrated drum-and-liner suppliers capable of unified certification documentation. This consolidation pattern disrupts standalone liner converters dependent on third-party drum fabricators for specification alignment. The shift is most visible in German IBC logistics corridors and US Gulf Coast hazardous waste management contracts, where single-source accountability reduces compliance audit burden.
Barrel Liner Market Segmentation
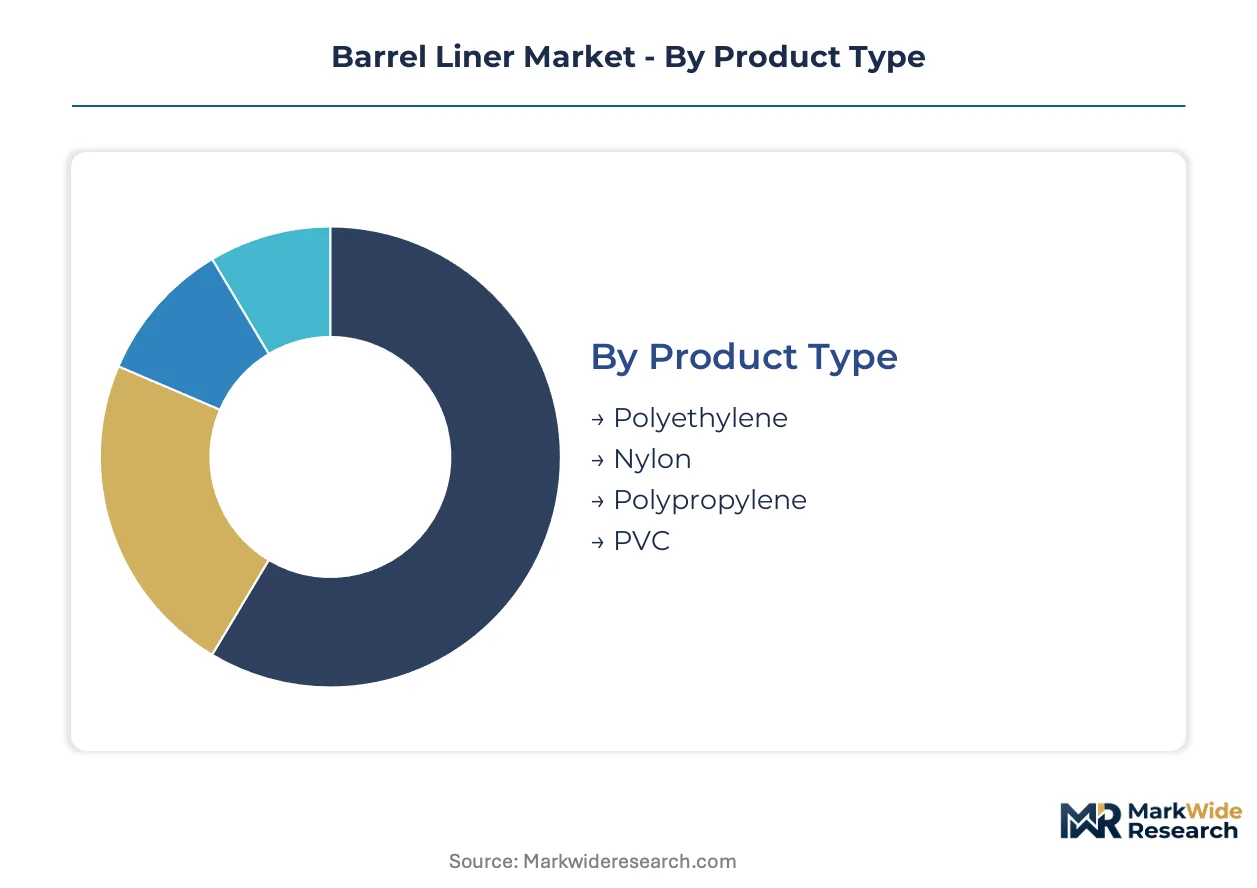
Barrel liner procurement patterns diverge sharply across material chemistry and thickness specifications, with regulatory compliance thresholds acting as the primary sorting mechanism between commodity and premium-grade demand pools. Specification mismatches in hazardous chemical containment drive replacement costs that dwarf initial liner expenditure, elevating material selection to a risk-management decision.
Product Type:
Buyers differentiate primarily by chemical resistance requirements and thermal stability thresholds, with cost-positioning secondary to performance validation documentation.
- Polyethylene:Linear low-density and high-density grades dominate chemical processing and waste management applications through superior solvent resistance and weld-seal reliability. US Gulf Coast petrochemical facilities specify certified heavy-gauge polyethylene for RCRA Subtitle C hazardous waste containment, with EPA inspection protocols driving specification upgrades toward documented batch traceability.
- Nylon:Polyamide 6 and 6/6 formulations command premium positioning in high-temperature chemical processing above 100°C, where thermal deformation resistance determines replacement cycles. Germany's Rhine-Ruhr industrial corridor generates concentrated demand for extra-heavy nylon liners rated to 120°C continuous exposure, with BASF and Evonik facilities mandating REACH SVHC batch certification.
- Polypropylene:Clarified and impact-copolymer grades serve agricultural chemical packaging where moisture barrier and cost-efficiency balance against moderate chemical exposure.
- PVC:Flexible calendered formulations face reformulation pressure from REACH Annex XVII phthalate restrictions, with bio-based plasticizer adoption accelerating in French and Italian food-contact applications.
Polyethylene leads volumes today; nylon is gaining share fastest.
End Use:
Regulatory intensity and containment liability exposure create four distinct procurement profiles with divergent specification documentation burdens.
- Chemical:Chlorinated solvent handling and acid-base containment drive demand for multilayer coextruded liners with EVOH barrier sublayers. Seven-layer blown film systems now integrate real-time thickness gauging to maintain sub-5% tolerance bands for critical containment applications, extending service life in solvent-rich environments.
- Industrial:General manufacturing and coatings applications standardize on medium-gauge polyethylene with basic FDA or REACH compliance documentation, with procurement centralized through integrated drum-and-liner suppliers.
- Agricultural:Fertilizer and pesticide packaging favors cost-optimized polypropylene and thin-gauge polyethylene, though mechanical recycling contamination limits block circular feedstock adoption.
- Food Processing:FDA food contact regulations and EFSA purity thresholds shape polyethylene and nylon specifications, with RFID-embedded liners penetrating pharmaceutical cold chain logistics in Switzerland and the Netherlands.
Chemical end-use commands the highest specification premiums; food processing is climbing the fastest as traceability requirements intensify.
Thickness:
Containment liability and material handling stress determine gauge selection, with regulatory pressure compressing the viable range toward heavier specifications.
- Heavy:8-12 mil polyethylene and nylon grades concentrate margin pools as EPA and REACH enforcement tightens hazardous material containment standards. German chemical logistics corridors and US Gulf Coast waste management facilities now specify heavy-gauge minimums for secondary containment compliance.
- Extra Heavy:15-25 mil formulations serve extreme chemical exposure and high-temperature processing, with IBC-to-liner bundling systems dominating Rhine-Ruhr procurement patterns.
- Medium:4-7 mil specifications retain position in general industrial and agricultural applications where cost sensitivity outweighs containment risk.
- Thin:Sub-4 mil grades face displacement from chemical and waste management segments, concentrating in low-risk agricultural and conservation applications.
Heavy thickness leads volumes today; extra heavy is expanding most quickly.
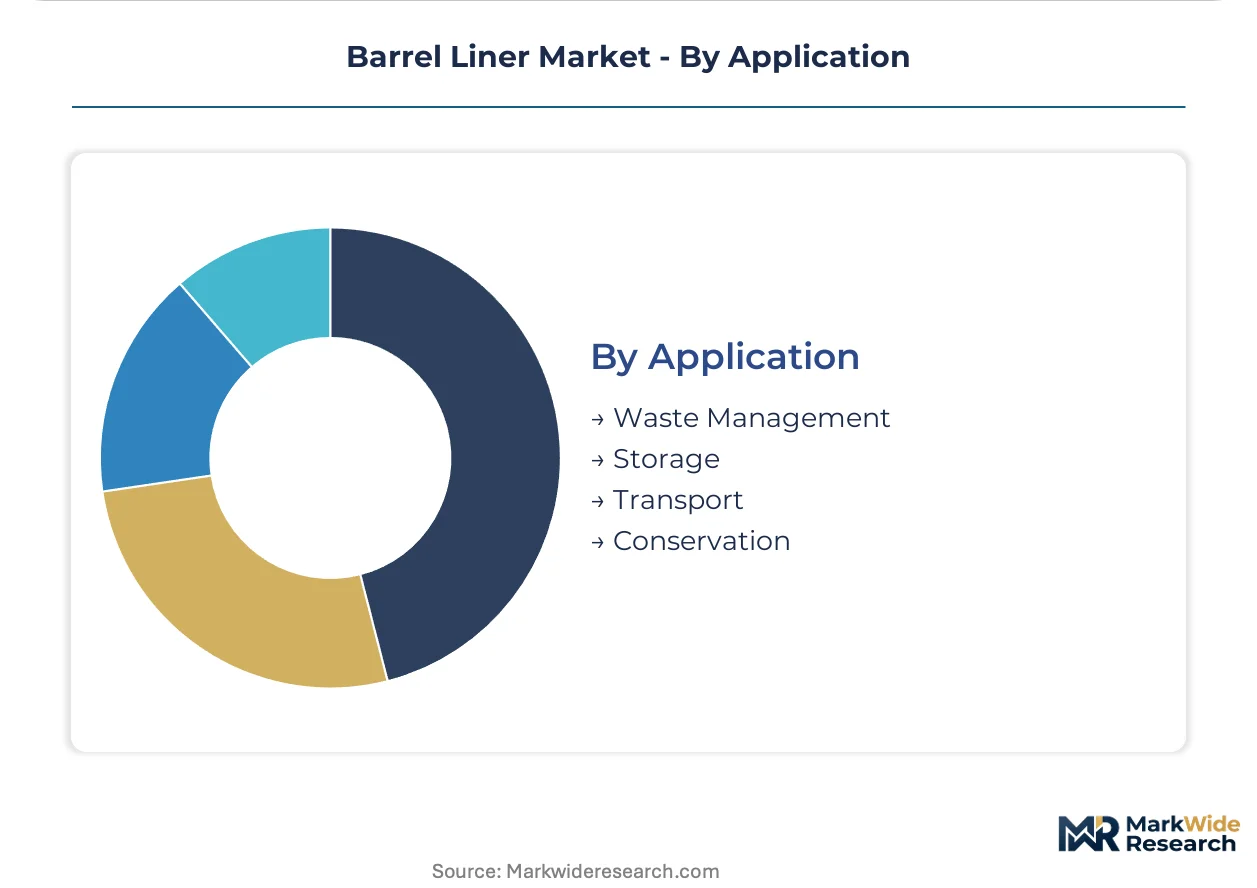
Application:
Operational stress and regulatory scrutiny intensity sort demand across four functional deployment modes.
- Waste Management:RCRA Subtitle C hazardous waste facilities face intensified container integrity inspections, accelerating drum liner procurement with documented compliance traceability.
- Storage:Long-duration chemical containment emphasizes multilayer barrier films and UV-stabilized formulations for outdoor tank farm applications.
- Transport:Dynamic stress and temperature cycling drive specification toward reinforced seam welding and impact-resistant gauge minimums.
- Conservation:Archival and museum applications favor inert nylon and polyethylene formulations with off-gassing certification.
Waste management leads volumes today; storage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and blown film technicians concentrate in Germany's industrial chemical corridor and the US Gulf Coast petrochemical belt, anchoring regional demand for precision-extruded containment solutions.
United States
RCRA Subtitle C enforcement intensifies container integrity inspections across hazardous waste facilities. EPA inspection protocols now mandate documented batch traceability for secondary containment compliance. The Gulf Coast petrochemical hub from Houston to Baton Rouge generates concentrated procurement of heavy-gauge polyethylene liners for chlorinated solvent handling.
Germany
BASF, Bayer, and Evonik facilities along the Rhine-Ruhr industrial belt drive demand for extra-heavy nylon liners rated above 120°C processing temperatures. REACH SVHC screening requires third-party certification for each resin batch, extending order fulfillment timelines. ECHA substance evaluation timelines compress supplier reformulation windows to 18-24 months for PVC alternatives.
India
Reliance Industries and Indian Oil Corporation expand ethylene capacity under the PLI scheme for petrochemicals. The country's national chemical regulator tightens hazardous material containment standards for domestic agrochemical packaging. Gujarat's industrial corridor near Vadodara and Ankleshwar concentrates new liner manufacturing investment.
Switzerland
Swissmedic pharmaceutical cold chain regulations accelerate RFID-embedded liner adoption for real-time fill-level monitoring. The national pharmaceutical regulator mandates traceability documentation for temperature-sensitive biologics transport. Basel's pharmaceutical cluster drives specification premiums for multilayer barrier films.
Netherlands
Rotterdam's chemical logistics hub concentrates IBC-to-liner bundling system demand for European distribution networks. Draft EU packaging sustainability mandates incentivize bio-based polyethylene development for industrial packaging above 10,000 units annually. Eindhoven's advanced manufacturing corridor supports precision coextrusion equipment deployment.
Barrel Liner Market Competitive Environment
The competitive structure tilts toward integrated drum-and-liner suppliers capable of unified certification documentation. Mid-cap standalone converters face displacement as chemical processors consolidate vendor lists around single-source accountability. Three archetypes dominate: integrated packaging conglomerates with captive steel drum manufacturing, specialized blown film extruders with precision gauge control, and regional IBC bundling specialists serving chemical logistics corridors. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers seeking resin supply security and geographic proximity to petrochemical feedstock.
Within the integrated packaging tier, Greif, Inc. and Mauser Packaging Solutions exemplify archetypes combining drum fabrication with liner specification alignment. Berry Global Inc. occupies a position among blown film specialists leveraging seven-layer coextrusion capabilities. Schütz GmbH & Co. KGaA anchors the IBC bundling specialist segment serving German chemical logistics corridors.
| Leading Market Players |
|---|
| Greif, Inc. |
| Berry Global Inc. |
| Protective Lining Corp. |
| CDF Corporation |
| International Plastics, Inc. |
| Amcor Plc |
| BASCO Inc. |
| Mauser Packaging Solutions |
| Schütz GmbH & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap converters along Germany's Rhine-Ruhr corridor and the US Gulf Coast maintain disciplined pricing through long-term resin offtake agreements with regional petrochemical suppliers, insulating them from spot-market volatility while compressing margins for non-integrated competitors dependent on merchant HDPE purchases.
Pricing Analysis
The bundled-versus-unbundled service split separates integrated drum-and-liner suppliers from standalone converters. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and REACH SVHC documentation burden. Cost compression in standard-grade polyethylene is intensifying because Gulf Coast resin price volatility transmits directly to non-integrated converters. Agricultural end-use buyers exhibit highest price sensitivity, while German chemical processors accept premium positioning for batch-traceable extra-heavy nylon grades.
Supply Chain Analysis
Dual-sourcing requirements mandated by BASF, Evonik, and Bayer procurement protocols force liner suppliers to qualify resin streams from at least two petrochemical sources. Supply concentrates in Germany, the United States, and China, with blown film equipment manufacturing drawing from Jiangsu and Zhejiang provinces. Raw material dependencies rest on HDPE resin, nylon 6/6 chip, and EVOH barrier polymers. Single-source vulnerability in Chinese specialty film equipment creates capex access bottlenecks for Western producers. Distribution runs through integrated packaging conglomerates and regional IBC bundling specialists serving chemical logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The barrel liner market functions as a stable compounder, with regulatory compliance timelines for EPA Subtitle C and REACH SVHC screening creating predictable replacement demand cycles across chemical processing facilities.
For Market Incumbents: Hedge against resin price volatility through backward integration into regional ethylene supply or long-term offtake agreements with Gulf Coast and Rhine-Ruhr petrochemical producers. Invest in seven-layer coextrusion capabilities to defend specification premiums as German and US chemical processors consolidate vendor lists around unified certification documentation.
For New Entrants and Emerging Players: E-commerce platforms serving agricultural chemical distributors offer lower customer acquisition costs than direct enterprise sales to integrated chemical processors. Target India's Gujarat industrial corridor where Reliance Industries ethylene expansion creates localized resin supply for domestic agrochemical packaging growth. Pursue private-label partnerships with regional drum fabricators lacking in-house liner extrusion capabilities.
For Investors and Strategic Acquirers: Valuations sit cheapest among standalone blown film converters with precision gauge control but no captive drum manufacturing. The five-to-ten year viability window favors targets with REACH and FDA certification infrastructure already deployed. Acquisition focus should center on mid-cap specialists serving pharmaceutical cold chain logistics in Switzerland and the Netherlands. Watch RFID-embedded liner adoption rates as the inflection signal for next-generation specification premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Supply | Captive resin sourcing from Gulf Coast petrochemical hubs insulates margin pools from HDPE price volatility. |
| Seven-Layer Coextrusion Capacity Addition | Real-time thickness gauging systems meet BASF and Evonik sub-5% tolerance specifications for solvent-rich containment. |
| REACH SVHC Certification Investment | Third-party batch documentation capabilities qualify suppliers for Rhine-Ruhr chemical corridor procurement contracts. |
| RFID-Enabled Liner Development | Swissmedic pharmaceutical cold chain regulations mandate real-time fill-level monitoring for temperature-sensitive biologics transport. |
| Joint Venture with Regional Drum Fabricators | Unified certification documentation reduces compliance audit burden for US Gulf Coast hazardous waste management contracts. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at German and US chemical processing facilities, procurement leads at downstream agrochemical distributors, blown film extrusion equipment specialists, and regulatory affairs directors with secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA enforcement action databases. Bottom-up resin demand modeling and top-down packaging spend analysis were triangulated against facility-level procurement patterns.
The forecast window anchored to historical reference periods across the analysis window, with segmentation dimensions spanning material chemistry, thickness specification, end-use industry, and regional production hub. CAGRs were derived from regression analysis against petrochemical capacity expansion timelines and regulatory enforcement intensity indices. Modeled inputs included REACH SVHC screening cost trajectories and blown film equipment deployment rates in Gujarat and Jiangsu provinces.
Resin price volatility, regulatory enforcement intensity, and multilayer recycling infrastructure development are the dominant revision risks to the projection horizon. Deviation in REACH Annex XVII restriction timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
North America Alcoholic Beverages Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
High-End Baijiu Market
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
Rice Wine Market