
 American Oak Barrels Market | 2026-2036
American Oak Barrels Market Size, Share, and Industry Trends Forecast 2026-2036
American Oak Barrels Market Outlook
Craft spirits production is recalibrating barrel procurement patterns across North America. Independent Stave Company leverages its Missouri-based stave mills to control raw material flows from forest to finished cooperage. The Oak Cooperage sustains a niche position through hand-crafted barrel construction for premium Sonoma and Napa wineries. Brown-Forman Corporation dominates captive barrel supply for its Jack Daniel's and Woodford Reserve distilleries through in-house cooperage operations.
American oak barrels are cylindrical wooden containers constructed from Quercus alba staves, charred or toasted to precise temperature profiles that extract vanillin, lactones, and ellagitannins during liquid aging. The wood's tight grain structure and high tylose content limit oxygen permeation, making it functionally suited for multi-year whiskey maturation. New barrels command premium positioning in bourbon production where regulations mandate first-use oak, while used barrels circulate into Scotch and Irish whiskey programs where reuse is standard practice. Custom barrels represent the fastest-growing product type as craft distilleries specify alternative toast profiles and non-standard dimensions to differentiate flavor signatures.
The Alcohol and Tobacco Tax and Trade Bureau (TTB) enforces strict labeling and aging claims that shape barrel investment cycles across American distilleries. The Environmental Protection Agency (EPA) regulates air emissions from cooperage toasting and charring operations, particularly in concentrated manufacturing zones. Stakeholders must monitor evolving sustainability certification requirements for forest-sourced oak as European Union deforestation regulations extend compliance obligations to exported American spirits.
Market Dynamics
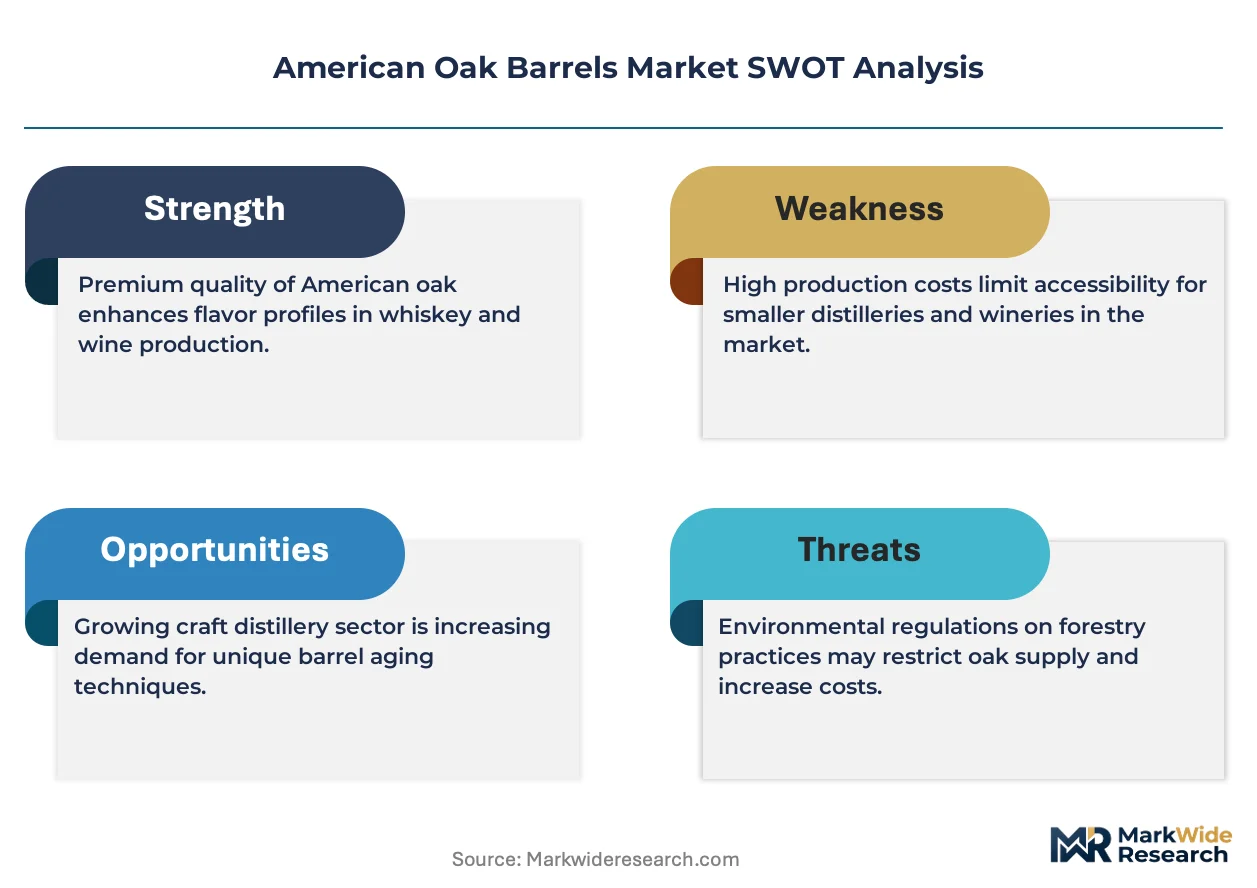
The American Oak Barrels Market pivots on regulatory mandates governing first-use oak in bourbon production, which lock distilleries into continuous new-barrel procurement regardless of price cycles or supply fluctuations.
Growth Catalysts
- Craft Distillery Expansion:Small-batch whiskey programs across Kentucky and Tennessee are scaling aged inventory, pulling premium toasted barrels from Missouri and Arkansas cooperage clusters.
- FDA Traceability Mandates:The Food Safety Modernization Act tightens chain-of-custody documentation for wood-contact materials, advantaging established suppliers with certified sourcing systems.
- Export Program Growth:American spirits shipments to European and Asian markets are accelerating, extending barrel depreciation cycles through secondary-use Scotch and Irish whiskey applications.
Market Restraints
- White Oak Supply Concentration:Quercus alba harvests concentrate in Appalachian and Ozark forests, exposing pricing to climate volatility and timberland ownership consolidation.
- EPA Air Emissions Controls:The Environmental Protection Agency regulates toasting and charring emissions in concentrated manufacturing zones, adding compliance capital requirements to cooperage operations.
- Steel Tank Substitution:Neutral spirits producers and bulk wine operations increasingly specify stainless steel for cost-sensitive maturation, ceding oak to premium positioning only.
Strategic Opportunities
- Alternative Toast Profiles:Craft distilleries are specifying non-standard temperature curves and stave configurations to differentiate flavor signatures from mass-market bourbon.
- European Union Deforestation Regulation:Compliance documentation requirements for exported American spirits create service revenue streams for cooperages offering certified sustainable sourcing.
- Direct-to-Distillery Channels:Bypassing traditional distributor networks, barrel makers are building captive relationships with emerging craft producers through specification consulting and inventory programs.
Industry Challenges
- Master Cooper Skills Gap:Traditional apprenticeship pipelines have collapsed, constraining expansion of hand-crafted production lines even as premium demand accelerates.
- Multi-Year Capital Lockup:Barrel inventory must age in bonded warehouses for tax purposes, tying working capital in depreciating assets through extended maturation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | American Oak Barrels Market |
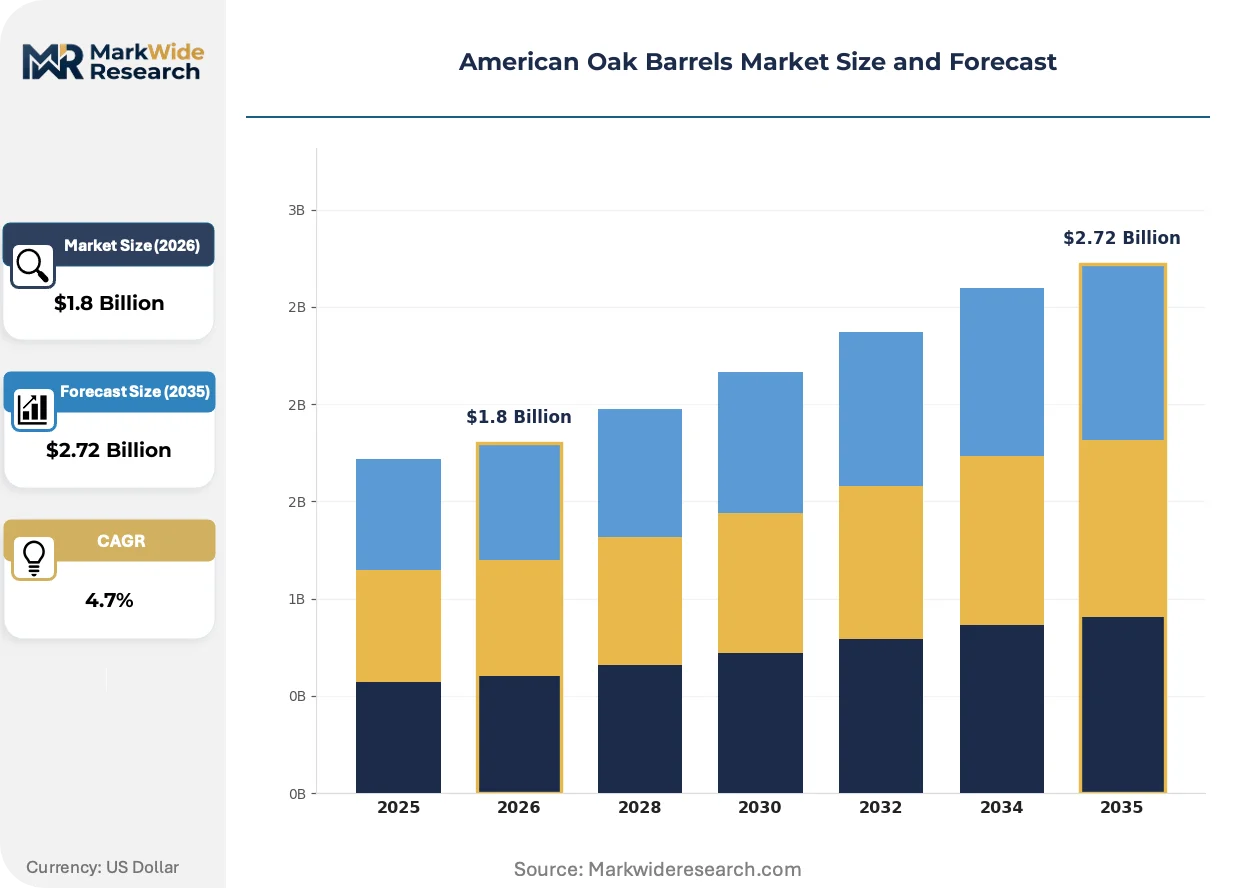
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: New Barrels, Used Barrels, Toasted Barrels, Custom Barrels Application: Wine Production, Whiskey Aging, Beer Brewing, Spirits Distillation Size: 188 Liter, 225 Liter, 300 Liter, 500 Liter End User: Wineries, Distilleries, Microbreweries, Beverage Companies |
| Companies Covered | Nadalie USA, The Oak Cooperage, Independent Stave Company, The Barrel Mill, ZAK Cooperage, Brown-Forman Corporation, Seguin Moreau Napa Cooperage, Thousand Oaks Barrel Co., Tonnellerie Francois Freres, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
American Oak Barrels Market Strategic Shifts
Precision toasting technology and digital supply chain tracking are compressing traditional cooperage timelines while elevating consistency standards for premium spirits producers.
Thermal imaging systems now monitor stave surface temperatures during toasting with real-time feedback loops, replacing manual judgment with repeatable heat profiles. Major bourbon distilleries are retrofitting charring lines with sensor arrays that log every barrel's thermal history. This standardization is unifying quality variance across high-volume production runs, reducing rejection rates and shortening specification negotiation cycles with buyers.
The TTB enforces strict labeling and aging claims that shape barrel investment cycles across American distilleries, requiring bonded warehouse documentation and periodic inventory verification. Distilleries must maintain detailed chain-of-custody records for every barrel entering maturation. Small producers face disproportionate compliance burdens, driving consolidation toward cooperages with integrated tax documentation services.
Specification-driven procurement now dominates craft segment buying patterns, with distilleries requesting sample lots and pilot runs before committing to volume contracts. Traditional catalog-based ordering is yielding to collaborative product development between barrel engineers and master distillers. This shift is most pronounced in Sonoma and Napa winery supply chains, where hand-crafted construction commands premium positioning through direct technical relationships.
American Oak Barrels Market Segmentation
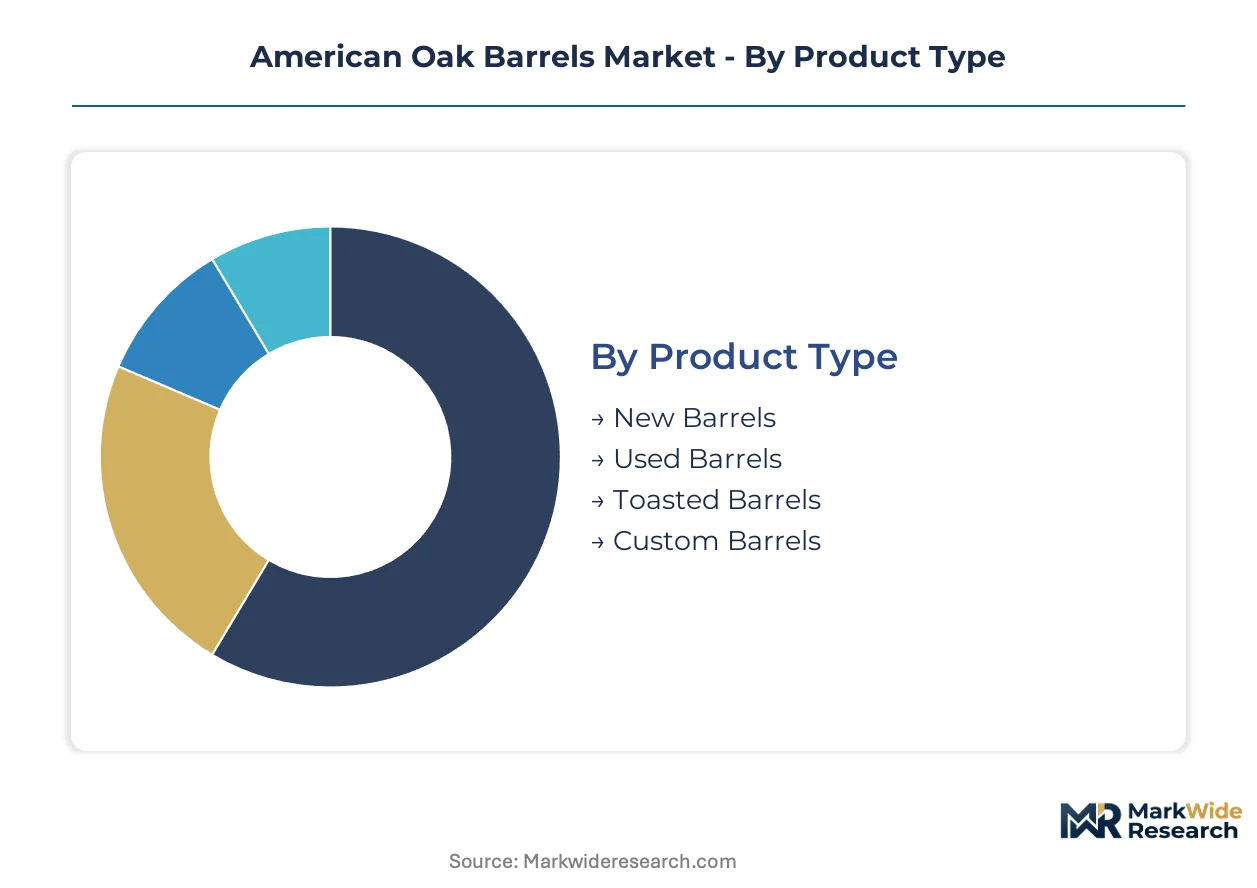
Barrel procurement patterns diverge sharply between regulated first-use mandates and secondary circulation markets. Distilleries, wineries, and brewers each impose distinct specification requirements that reshape manufacturing priorities across American cooperage operations.
Product Type:
Integration depth separates standalone new-barrel programs from embedded reuse systems across spirits supply chains.
- New Barrels:Constructed from virgin Quercus alba staves with standardized char levels, these vessels satisfy TTB mandates for bourbon's first-use oak requirement. Kentucky and Tennessee distilleries maintain continuous procurement pipelines regardless of price cycles, locking suppliers into bonded warehouse documentation systems.
- Custom Barrels:Alternative toast profiles and non-standard dimensions allow craft producers to differentiate flavor signatures from mass-market bourbon. Sonoma and Napa wineries drive specification complexity through direct technical collaboration with cooperage engineers.
- Used Barrels:Previously employed casks circulate into Scotch and Irish whiskey programs where reuse is standard practice, extending depreciation cycles through secondary applications.
- Toasted Barrels:Precision temperature curves replace traditional charring for wine and specialty spirits applications requiring subtler wood extraction.
Volume placements concentrate in New Barrels; the faster expansion belongs to Custom Barrels.
Application:
Cost tier stratification elevates whiskey aging above bulk wine operations that increasingly specify stainless steel alternatives.
- Whiskey Aging:Multi-year maturation in bonded warehouses demands tight grain structure and high tylose content to limit oxygen permeation. The TTB enforces strict labeling claims that shape investment cycles through periodic inventory verification requirements.
- Wine Production:Hand-crafted construction commands premium positioning in Sonoma and Napa supply chains where specification-driven procurement dominates buying patterns.
- Spirits Distillation:Neutral spirits producers face margin pressure from steel tank substitution, ceding oak to premium positioning only.
- Beer Brewing:Sour and barrel-aged programs pull limited volumes from bourbon's secondary barrel stream.
Revenue concentration sits with Whiskey Aging; Wine Production is climbing the fastest.
Size:
Volume scale determines labor intensity and stave yield per log, with smaller formats multiplying handling costs disproportionately.
- 188 Liter:Compact dimensions serve craft distilleries with constrained warehouse footprints and accelerated extraction timelines.
- 225 Liter:The Bordeaux standard dominates Napa and Sonoma winery procurement through established handling infrastructure and proven oxygen transfer rates.
- 300 Liter:Intermediate capacity addresses mid-scale producers seeking efficiency without committing to full-scale bourbon formats.
- 500 Liter:Maximum volume per stave set reduces unit labor costs for high-throughput bourbon distilleries with extensive bonded storage.
Procurement gravity centers on 225 Liter for wine and 500 Liter for spirits; 188 Liter is gaining share fastest among craft entrants.
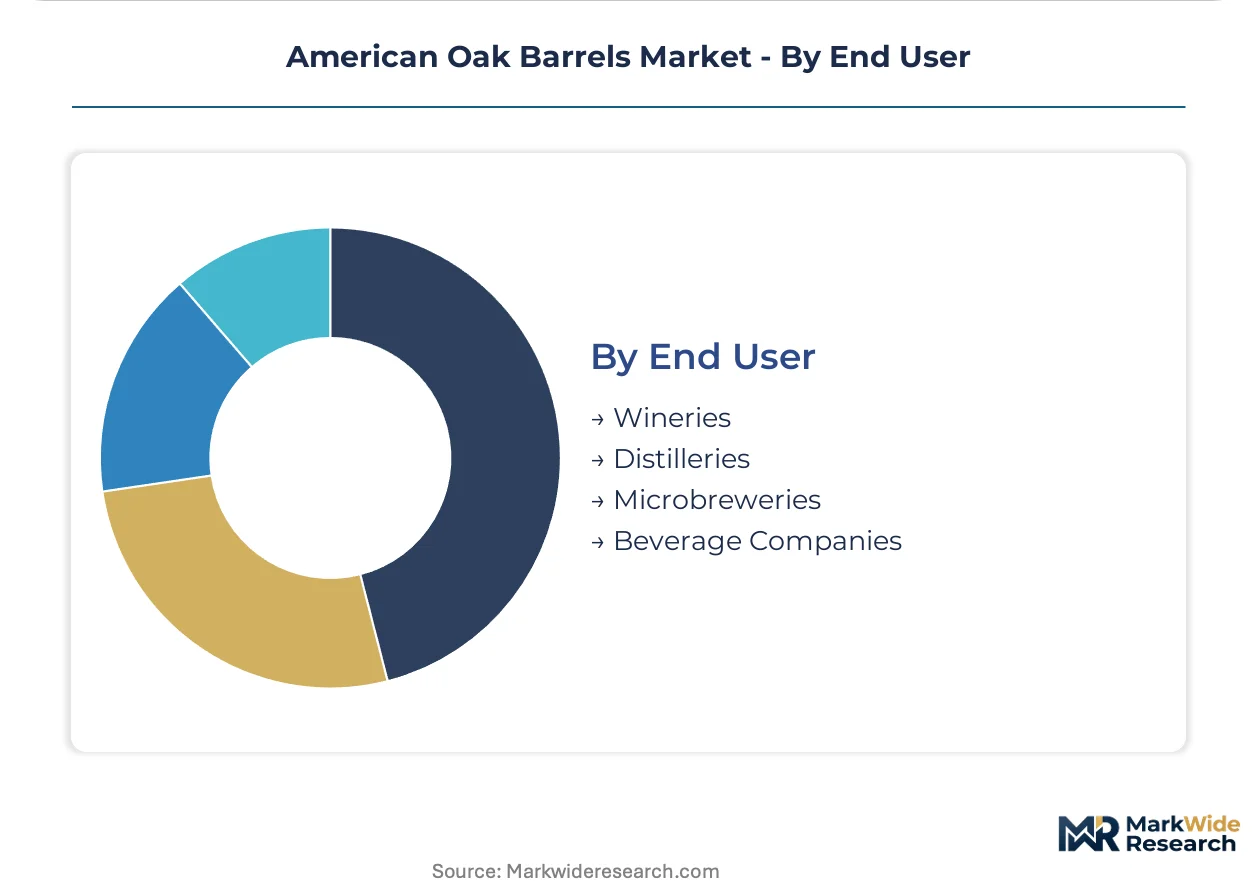
End User:
Customer type fragmentation splits between integrated beverage conglomerates and specification-heavy independent producers.
- Distilleries:Brown-Forman and comparable majors dominate captive barrel supply through in-house cooperage operations, while craft entrants pull from Missouri and Arkansas manufacturing clusters.
- Wineries:Sonoma and Napa operations sustain The Oak Cooperage and comparable specialists through hand-crafted construction premiums and direct technical relationships.
- Microbreweries:Limited-scale barrel programs source opportunistically from bourbon's secondary stream rather than commissioning new construction.
- Beverage Companies:Diversified portfolios balance oak commitment across wine, spirits, and beer divisions with consolidated procurement leverage.
Contract volume concentrates with Distilleries; Wineries are expanding specification complexity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
American oak barrel production concentrates in Missouri and Arkansas forests while consumption clusters in Kentucky and Tennessee distilleries, creating a distinct domestic supply-demand corridor with minimal cross-border trade dependency.
United States
Kentucky and Tennessee distilleries drive demand through bourbon's first-use oak mandate, with Brown-Forman's captive cooperage securing supply chain control. The TTB enforces bonded warehouse documentation requirements that shape procurement cycles. Missouri's stave mill clusters in Lebanon and Higginson supply raw material flows to independent cooperages across the Ozark region.
Canada
Craft whisky programs in Ontario and British Columbia pull limited volumes of American oak for premium aging applications. Health Canada regulates wood-contact materials under the Food and Drugs Act, requiring traceability documentation for imported cooperage. Toronto-area distilleries source opportunistically from secondary barrel streams rather than commissioning new construction.
France
Bordeaux and Burgundy wineries specify American oak alternatives to French oak for specific flavor profiles in premium wines. The EU Deforestation Regulation imposes compliance documentation requirements on imported cooperage, advantaging suppliers with certified sustainable sourcing. Tonnellerie operations in Cognac and Beaune integrate American stave imports into hybrid construction programs.
United Kingdom
Scotch whisky producers absorb used American bourbon barrels as standard maturation vessels, extending depreciation cycles through secondary applications. The Food Standards Agency enforces contact material safety standards for imported cooperage. Speyside and Islay distilleries maintain long-term supply relationships with Kentucky and Tennessee barrel brokers.
Ireland
Irish whiskey distilleries specify ex-bourbon casks for triple-distilled spirit maturation, creating steady demand for American oak's secondary market. The Food Safety Authority of Ireland implements EU-derived traceability requirements for wood-contact materials. Midleton and Dublin distillery expansions are tightening used barrel availability across European sourcing channels.
American Oak Barrels Market Competitive Environment
Top-tier vendors anchor captive supply chains, while mid-tier independents compete on specification flexibility and direct technical relationships. The market structures around three concentration nodes: integrated beverage conglomerates with in-house cooperage, Missouri-Arkansas manufacturing clusters serving bourbon distilleries, and Napa-Sonoma specialists commanding hand-crafted premiums. Strategic moves center on backward integration into stave milling and specification consulting services that lock craft distilleries into multi-year contracts.
Within the integrated conglomerate tier, Brown-Forman Corporation exemplifies captive supply chain control through wholly-owned cooperage operations. Among independent specialists, The Oak Cooperage and Independent Stave Company occupy positions at opposite ends of the craftsmanship spectrum—hand-crafted construction versus scaled manufacturing—while both leverage Missouri-based raw material proximity to manage cost structures.
| Leading Market Players |
|---|
| Nadalie USA |
| The Oak Cooperage |
| Independent Stave Company |
| The Barrel Mill |
| ZAK Cooperage |
| Brown-Forman Corporation |
| Seguin Moreau Napa Cooperage |
| Thousand Oaks Barrel Co. |
| Tonnellerie Francois Freres |
| Others |
Value Chain & Pricing Dynamics
Bourbon's first-use oak mandate locks Kentucky and Tennessee distilleries into continuous new-barrel procurement regardless of price cycles, forcing cooperages to maintain bonded warehouse documentation systems and premium inventory reserves that inflate carrying costs across the supply chain.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as craft distilleries demand accelerated specification cycles. Three-tier pricing structure across premium, standard, and economy levels reflects toast complexity, stave grade, and bonded warehouse documentation bundling. Price differentiation separates hand-crafted construction from scaled manufacturing outputs. Cost compression in standard-tier barrels intensifies because steel tank substitution cedes oak to premium positioning only. Craft entrants exhibit highest price sensitivity; integrated majors with captive cooperage show lowest.
Supply Chain Analysis
EU Deforestation Regulation compliance documentation gates market access for exported American spirits, advantaging suppliers with certified sustainable sourcing systems. Raw material flows draw from Missouri and Arkansas stave mill clusters feeding Ozark-region cooperages. White oak harvests hinge on Appalachian and Ozark forest management. Climate volatility and timberland ownership consolidation create single-source vulnerability for Quercus alba supply. Distribution runs through direct-to-distillery channels bypassing traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over stave milling and bonded warehouse infrastructure determines procurement leverage and margin defense.
For Market Incumbents: Acquire Ozark-region stave mill assets to secure raw material flows from forest to finished cooperage. Brown-Forman's captive cooperage model demonstrates how in-house production of barrels insulates against white oak supply concentration and EPA emissions compliance cost pass-through. Independent Stave Company's Lebanon and Higginson mill clusters illustrate backward integration path for mid-tier players.
For New Entrants and Emerging Players: Sonoma and Napa wineries represent an underserved buyer archetype seeking hand-crafted construction with direct technical relationships. Specification consulting services for alternative toast profiles offer entry wedge against scaled Missouri manufacturers. Direct collaboration with master distillers on non-standard dimensions builds multi-year contract lock-in before volume procurement.
For Investors and Strategic Acquirers: The window for entry favors cooperages with integrated tax documentation services and certified sustainable sourcing credentials. Master cooper skills gap constrains hand-crafted production expansion, creating scarcity premium for apprenticeship pipeline investments. Monitor EU Deforestation Regulation enforcement stringency as inflection indicator for compliance-documentation service revenue growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stave Milling | Independent Stave Company's Lebanon mills demonstrate raw material cost control from forest to finished barrel. |
| Precision Toasting Technology Deployment | Thermal imaging systems at major bourbon distilleries reduce rejection rates through repeatable heat profile standardization. |
| Direct-to-Distillery Channel Development | Bypassing traditional broker networks locks craft producers into specification consulting and inventory program relationships. |
| EU Deforestation Regulation Compliance Certification | Certified sustainable sourcing documentation creates service revenue streams for exported American spirits cooperage. |
| Master Cooper Apprenticeship Pipeline Investment | Traditional skills gap constrains hand-crafted production expansion even as premium Sonoma and Napa demand accelerates. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with master distillers, cooperage engineers, stave mill procurement leads, and bonded warehouse operators combined with TTB documentation requirements and EPA emissions filings. Secondary sources included Forest Stewardship Council certification databases, Alcohol and Tobacco Tax and Trade Bureau labeling enforcement records, and Missouri Department of Conservation timber harvest reports. Bottom-up barrel shipment tallies triangulated against top-down spirits production capacity estimates.
Data-stream reconciliation across product type, application, size format, and end-user category shaped the analytical framework across the analysis window. CAGRs derived from volume shipment trajectories and value per barrel trends. Industry-specific forecast inputs incorporated craft distillery expansion pipelines, EU Deforestation Regulation compliance cost pass-through assumptions, and white oak harvest yield volatility.
Revisions become necessary when EPA emissions enforcement intensifies, EU deforestation documentation requirements expand, or master cooper labor availability shifts materially. Forecasts reflect documented assumptions regarding bonded warehouse capacity expansion and spirits export program growth. A model refresh is warranted upon material change in white oak supply concentration or steel tank substitution rates in neutral spirits production.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Beer Processing Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Low Alcohol Beverages Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Digital Shaker Market