
 Wine Box Market | 2026-2036
Wine Box Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Box Market Analytics
Corrugated fiberboard is consolidating share from rigid wooden crates in mid-premium wine packaging. Smurfit Kappa Group leverages its European recycled-paper supply chain to anchor cost leadership in folding carton production. Mondi plc sustains R&D intensity in barrier-coated kraft solutions for bag-in-box liners. International Paper competes through North American containerboard scale and direct-to-winery distribution contracts.
A wine box is a rigid or semi-rigid container engineered from corrugated board, solid board, or composite materials, typically rated for 1.5 to 10 liter liquid volumes with integrated dispensing fitments or hinged closures, designed to protect bottled or bulk wine during transit, retail display, and cellar storage. Bag-in-Box configurations dominate volume in institutional and retail channels where dispensing convenience and reduced shipping weight outweigh premium aesthetics. Folding Carton variants concentrate margin pools in gift and direct-to-consumer segments where lithographic print quality and structural embellishment command price premiums. Eco-friendly feature claims now shape procurement criteria across Scandinavian and Benelux retail buyers, though insulated specifications retain niche strength in temperature-sensitive export corridors.
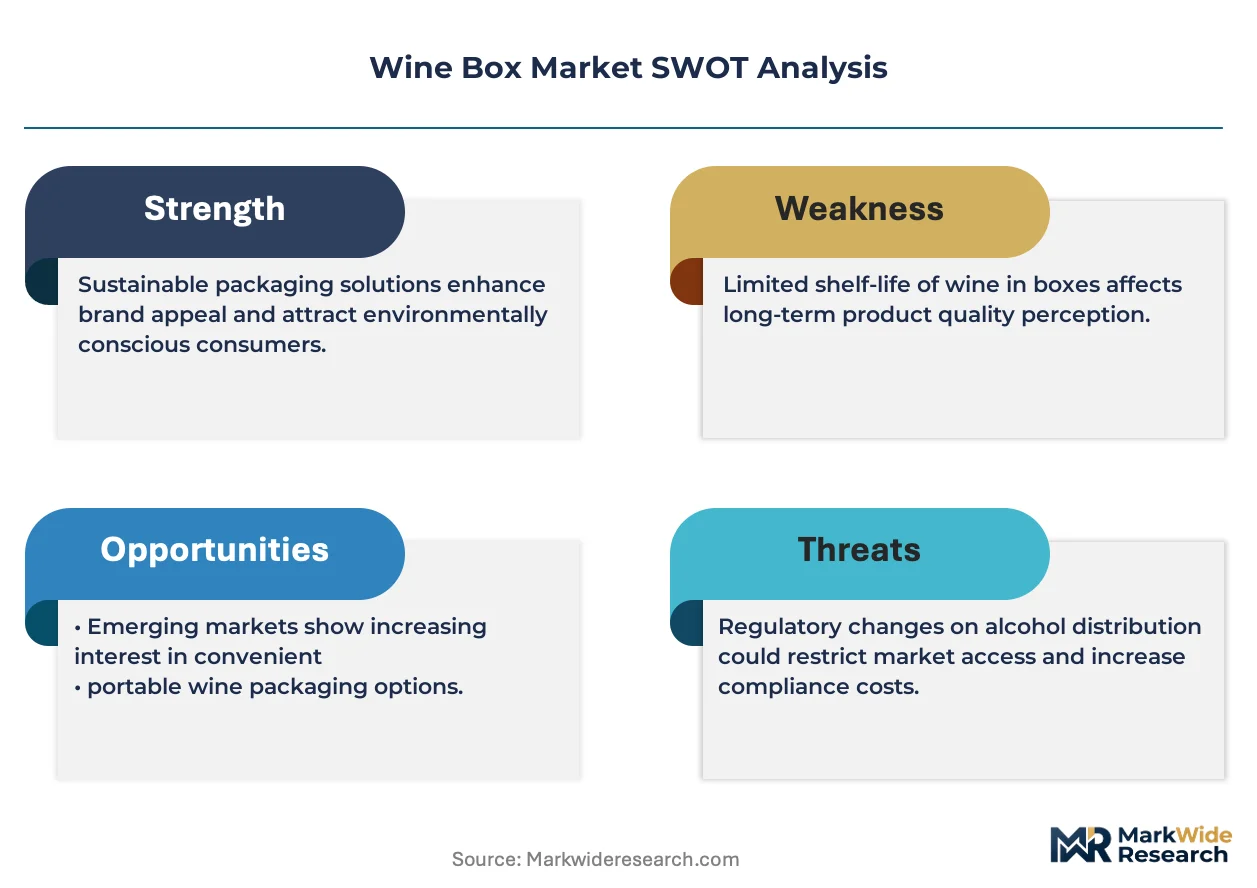
EU REACH and F-Gas Regulation frameworks govern chemical content in barrier films and refrigerant-based insulated boxes, while FDA contact-substance rules constrain liner material exports from European converters into United States distribution. CE marking requirements for food-contact materials create compliance thresholds that favor mid-scale producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving extended producer responsibility schemes in France and Italy, where deposit-return pilots for beverage packaging threaten to recast wine box collection infrastructure and material recovery economics.
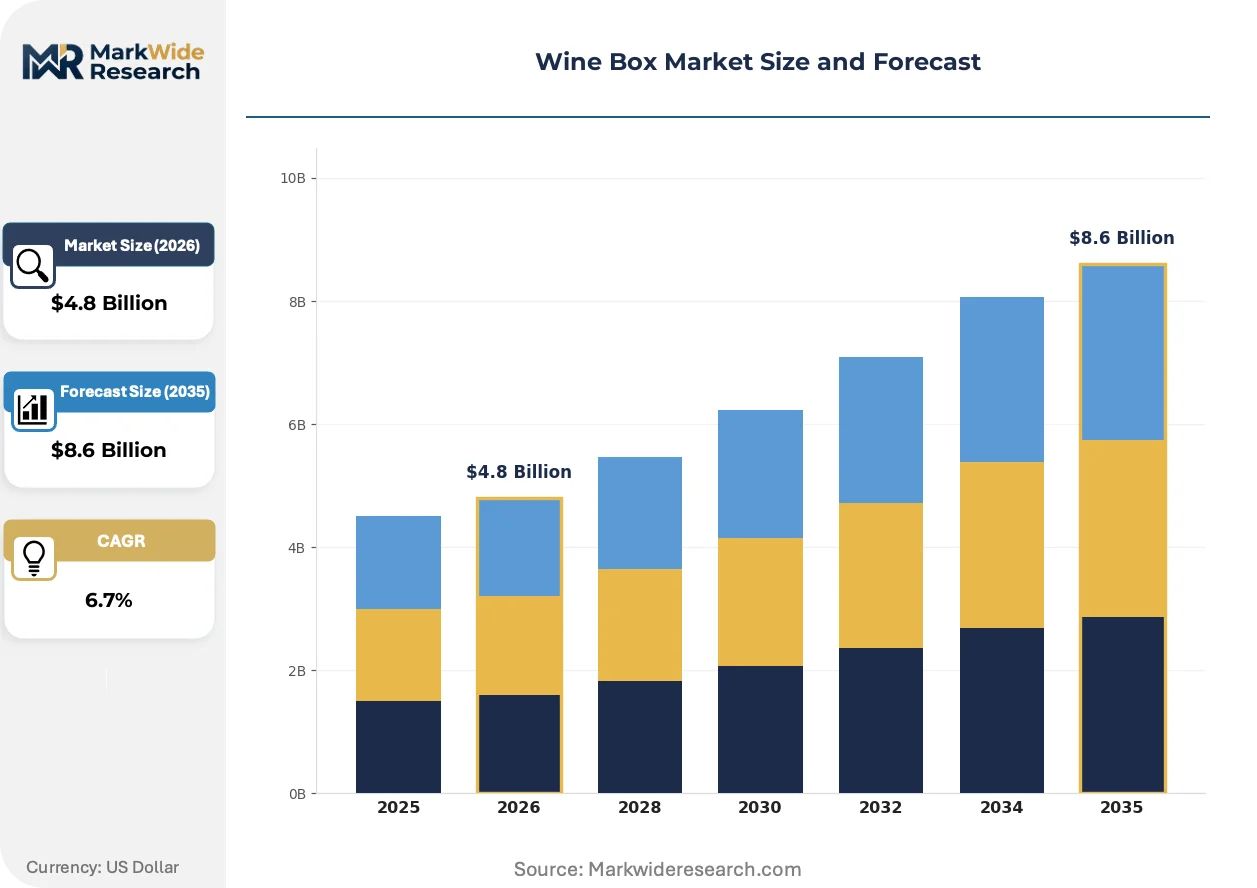
Market Dynamics
EU REACH compliance on packaging recyclability is redirecting material procurement across European wine box converters, compressing lead times for certified fiberboard qualification and elevating compliance costs for barrier film formulations.
Growth Catalysts
- Bag-in-Box Dispensing Convenience:Institutional buyers in hospitality and foodservice sectors prioritize reduced shipping weight and integrated tap systems over traditional bottle formats. Germany's direct-to-consumer subscription channels accelerate procurement volumes.
- REACH-Driven Material Substitution:ECHA chemical restrictions on barrier films push converters toward aqueous-coated kraft liners. French and Italian wineries face compliance deadlines that favor pre-qualified sustainable packaging suppliers.
- Corrugated Fiberboard Scale:Recycled-paper supply chain investments in Benelux and Scandinavia lower unit costs for mid-premium folding carton production. Retail buyers in these markets embed eco-friendly claims into procurement scorecards.
Market Restraints
- Barrier Film Input Volatility:Ethylene-vinyl alcohol copolymer prices fluctuate with petrochemical feedstock costs. European converters lack backward integration into polymer production.
- Wooden Crate Substitution Resistance:Premium estate wineries in Bordeaux and Napa Valley maintain rigid crate specifications for cellar storage and gift positioning. Aesthetic differentiation limits fiberboard penetration at the top tier.
- Extended Producer Responsibility Uncertainty:France and Italy pilot deposit-return schemes for beverage packaging. Wine box collection infrastructure remains undefined, chilling converter investment in closed-loop recycling systems.
Strategic Opportunities
- Temperature-Sensitive Export Corridors:Insulated wine box specifications for ocean freight to Asia-Pacific command margin premiums. Converters with F-Gas-compliant refrigerant-based solutions capture niche share.
- FDA Contact-Substance Compliance:European converters certifying liner materials for United States distribution unlock transatlantic winery contracts. Regulatory arbitrage favors mid-scale producers with dedicated compliance capacity.
- Digital Print Convergence:Combination of inkjet decoration and structural embellishment enables short-run customization for direct-to-consumer channels. United Kingdom subscription services drive demand for variable-data lithography.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:CE marking for food-contact materials, FDA substance notifications, and EFSA migration testing create sequential approval bottlenecks. Smaller converters lack regulatory affairs staffing to parallel-track submissions.
- Legacy Dispensing Fitment Integration:Bag-in-Box tap systems from incumbent suppliers use proprietary interfaces. Wineries face switching costs when evaluating alternative liner and fitment combinations.
- Barrier Performance Validation:Oxygen transmission rate testing for alternative coatings requires extended shelf-life studies. Accelerated protocols lack standardization across testing laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Box Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Box, Folding Carton, Bag-in-Box, Wooden Crate Material: Cardboard, Wood, Plastic, Glass Feature: Eco-friendly, Customized, Insulated, Stackable End User: Retailers, Restaurants, Direct-to-Consumer, Wholesalers |
| Companies Covered | Stora Enso Oyj, Sealed Air, Smurfit Kappa Group, Graficas Digraf, Nordpack GmbH, Mondi plc, International Paper, Golden West Packaging Group, DS Smith plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Box Market Evolving Landscape
Active and intelligent packaging technologies are reshaping wine preservation and supply chain visibility. Converters integrate sensor-enabled barriers and connected dispensing systems to differentiate beyond commodity fiberboard specifications.
Barrier-coated kraft liner technology is modularizing wine box construction. Smurfit Kappa Group and Mondi plc deploy multi-layer aqueous coatings that replicate ethylene-vinyl alcohol gas barrier performance without petrochemical films. Mid-premium wineries in Spain and Portugal adopt these specifications for 3-5 liter bag-in-box formats. The technology is modularizing converter production lines, enabling rapid switching between standard and high-barrier grades without dedicated extrusion equipment.
F-Gas Regulation phase-down schedules are compressing refrigerant choices for insulated wine box specifications. European converters face 2027 deadlines for hydrofluorocarbon replacement in temperature-controlled export packaging. Scandinavian buyers now mandate climate-neutral insulation materials for ocean freight to Asia-Pacific markets. German logistics providers accelerate qualification of vacuum-insulated panel alternatives ahead of regulatory enforcement.
Direct-to-consumer subscription models are fragmenting order patterns and compressing production runs. United Kingdom wine clubs and German online retailers demand lot sizes below 500 units with customized lithography. Folding carton converters respond with digital print investments that eliminate plate costs and reduce makeready waste. This behavioral shift concentrates margin pressure on traditional long-run offset producers while rewarding agile mid-scale specialists with web-to-print workflows.
Wine Box Market Segmentation
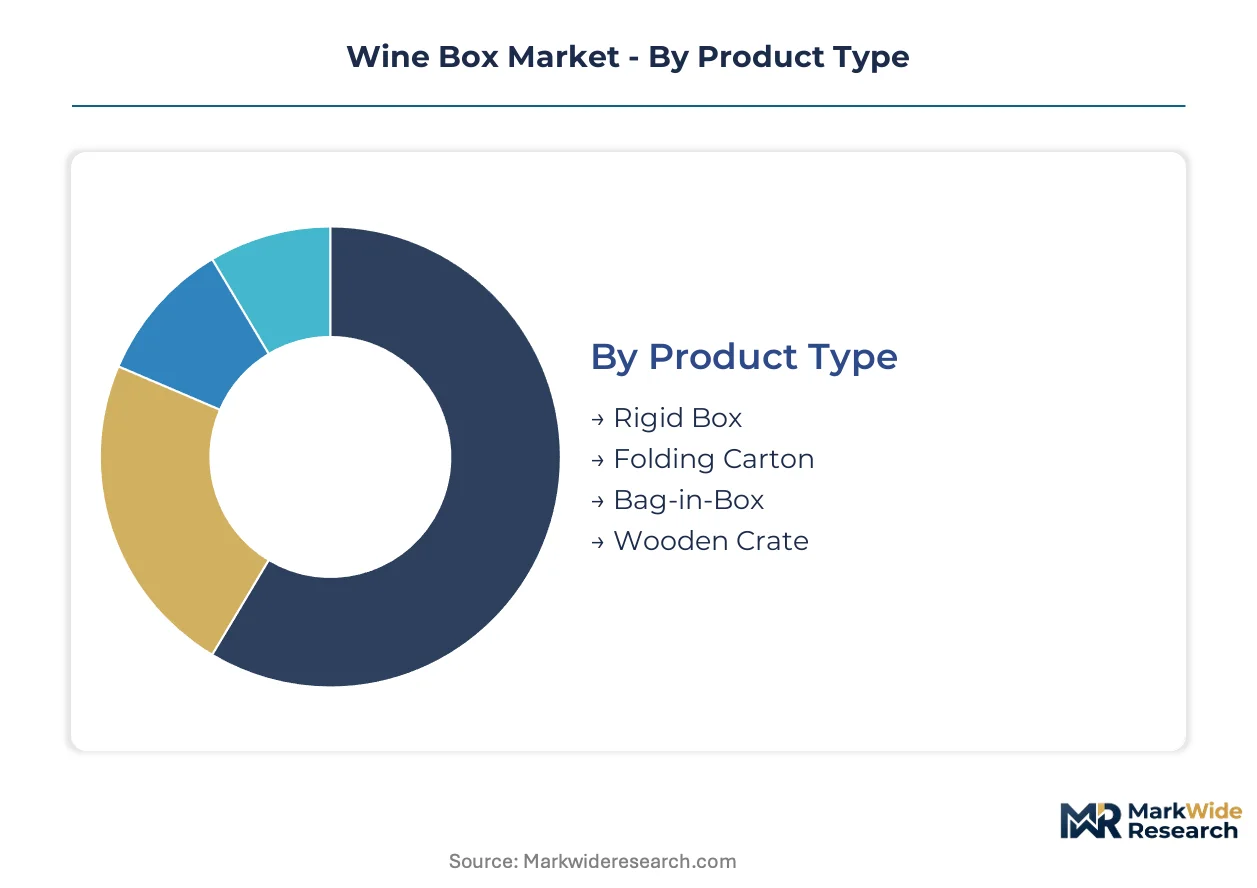
Wine box segmentation reveals divergent procurement logics across channels. Material specifications, dispensing requirements, and sustainability claims reshape supplier selection criteria for wineries and retailers.
Product Type:
Volume scale and dispensing convenience drive buyer selection across formats.
- Bag-in-Box:Multi-layer laminate liners integrated with corrugated fiberboard shells and tap fitments enable 1.5-10 liter dispensing. Germany's direct-to-consumer subscription channels accelerate procurement as wineries prioritize reduced shipping weight over glass bottle logistics.
- Folding Carton:Lithographic-printed solid board constructions with magnetic closures or ribbon handles target gift positioning. United Kingdom wine clubs embed structural embellishment into unboxing experiences for premium direct-to-consumer segments.
- Rigid Box:Thick-wall corrugated or composite board constructions with hinged lids protect bottled formats during cellar storage. Bordeaux estate wineries specify these for mid-tier retail distribution.
- Wooden Crate:Slatted hardwood or plywood assemblies with rope handles maintain heritage aesthetics. Napa Valley premium producers resist fiberboard substitution for collector-grade releases.
Bag-in-Box leads on scale; Folding Carton leads on momentum.
Material:
REACH compliance deadlines redirect converter investments toward certified inputs.
- Cardboard:Recycled-content corrugated and solid fiberboard grades dominate mid-premium production. Smurfit Kappa Group's European recycled-paper supply chain anchors cost leadership for folding carton converters serving Benelux retail buyers.
- Plastic:Ethylene-vinyl alcohol copolymer and polyethylene terephthalate films form bag-in-box liners and dispensing fitments. ECHA chemical restrictions push converters toward aqueous-coated kraft alternatives ahead of compliance deadlines.
- Wood:Hardwood slats and plywood panels sustain niche demand from premium estate positioning. French châteaux specify oak or pine crates for en primeur releases where provenance signaling outweighs material cost.
- Glass:Tempered or borosilicate inserts provide inert containment for high-value single bottles. Italian prosecco producers deploy these for limited-edition sparkling releases in direct-to-consumer channels.
Cardboard commands volume concentration; Plastic faces substitution pressure from regulatory timelines.
Feature:
Retail buyer scorecards embed sustainability and functional claims into procurement decisions.
- Eco-friendly:FSC-certified fiberboard, aqueous coatings, and recyclable mono-material constructions satisfy Scandinavian retail mandates. Swedish and Norwegian supermarket chains now require third-party certification for wine box shelf placement.
- Insulated:Vacuum-insulated panels or phase-change materials maintain temperature stability for ocean freight. German logistics providers qualify climate-neutral alternatives ahead of F-Gas Regulation phase-down deadlines for Asia-Pacific export corridors.
- Customized:Digital print and variable-data lithography enable short-run branding for wine clubs. United Kingdom subscription services drive demand for lot sizes below 500 units with personalized messaging.
- Stackable:Interlocking base designs and uniform footprint dimensions optimize pallet density. Warehouse operators in Spain and Portugal prioritize these specifications for automated storage systems.
Eco-friendly claims shape procurement scorecards most decisively; Customized features expand most quickly with digital print adoption.
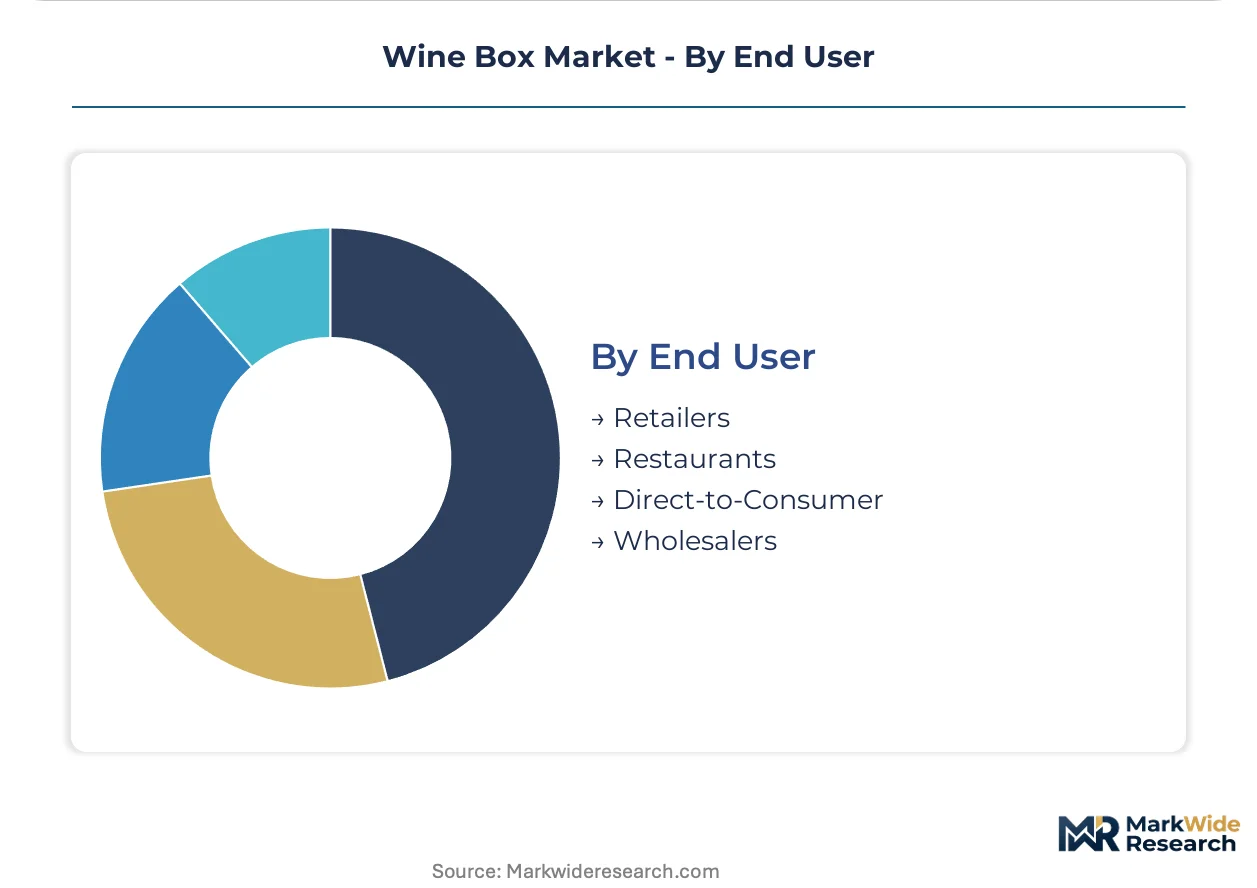
End User:
Channel-specific requirements fragment order patterns and compress production runs.
- Retailers:Supermarket chains and wine merchants prioritize shelf-ready packaging with standard footprint dimensions. French and Italian retail buyers embed extended producer responsibility compliance into supplier audits.
- Direct-to-Consumer:Subscription services and winery e-commerce demand customized lithography and protective inserts for individual bottle shipment. United Kingdom wine clubs fragment order patterns with lot sizes unsuited to traditional offset production.
- Restaurants:Foodservice and hospitality buyers favor bag-in-box tap systems for by-the-glass programs. German institutional procurement prioritizes dispensing convenience and reduced waste handling over premium aesthetics.
- Wholesalers:Distribution intermediaries require bulk palletization and stackable designs for warehouse efficiency. Spanish cooperatives specify these for volume shipments to export markets.
Retailers anchor procurement volume; Direct-to-Consumer channels are climbing the fastest with subscription model expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's direct-to-consumer subscription channels anchor European wine box procurement velocity, with Benelux and Scandinavian retail buyers embedding REACH-compliant fiberboard specifications into procurement scorecards.
Germany
Direct-to-consumer wine subscriptions and institutional foodservice procurement drive bag-in-box volumes. ECHA chemical restrictions on barrier films compress lead times for aqueous-coated kraft qualification. Berlin and Hamburg logistics providers accelerate vacuum-insulated panel adoption for Asia-Pacific export corridors ahead of F-Gas Regulation deadlines.
France
Bordeaux and Burgundy estate wineries sustain rigid box specifications for en primeur releases, while supermarket chains expand certified fiberboard procurement. Extended producer responsibility deposit-return pilots threaten to recast collection infrastructure. The Champagne-Ardenne corridor concentrates folding carton converter capacity for gift positioning.
Italy
Prosecco producers deploy glass-insert rigid boxes for limited-edition sparkling releases in direct-to-consumer channels. CE marking requirements for food-contact materials favor mid-scale converters with dedicated regulatory affairs capacity. Piedmont and Tuscany wine cooperatives specify stackable designs for automated warehouse systems.
United Kingdom
Wine clubs fragment order patterns with lot sizes below 500 units, demanding digital print and variable-data lithography. Subscription services embed structural embellishment into unboxing experiences. London and Southeast England concentrate web-to-print converter capacity for short-run customization.
Spain
Mid-premium wineries in Rioja and Ribera del Duero adopt barrier-coated kraft liners for 3-5 liter bag-in-box formats. REACH compliance deadlines redirect material procurement toward certified inputs. Catalan converters leverage modular production lines for rapid switching between standard and high-barrier grades.
Wine Box Market Competitive Landscape
Global majors compete with regional champions across fiberboard supply chain scale and regulatory compliance capacity. The market structure tiers between scale-driven containerboard producers and agile mid-scale specialists with web-to-print workflows. Three archetypes dominate: integrated paper-packaging conglomerates with recycled-paper supply chains, barrier-technology specialists with aqueous-coating R&D intensity, and digital-print converters serving subscription-channel fragmentation. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters position for REACH-driven material substitution.
Among integrated paper-packaging conglomerates, Smurfit Kappa Group and Mondi plc exemplify scale-driven archetypes with European recycled-paper supply chain anchoring and barrier-coated kraft R&D positioning respectively. International Paper occupies a position as a North American containerboard scale competitor. These three represent the tier of players with dedicated regulatory affairs capacity to parallel-track CE marking, FDA substance notifications, and EFSA migration testing submissions.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| Sealed Air |
| Smurfit Kappa Group |
| Graficas Digraf |
| Nordpack GmbH |
| Mondi plc |
| International Paper |
| Golden West Packaging Group |
| DS Smith plc |
| Others |
Value Network & Pricing Analysis
Backward integration into recycled-paper supply chains anchors both cost leadership and pricing power for European folding carton converters, with Smurfit Kappa Group's captive fiber sourcing insulating margin positions against OCC price volatility while REACH compliance costs get passed through to mid-premium winery buyers.
Pricing Analysis
Input-cost pass-through from ethylene-vinyl alcohol copolymer volatility shapes bag-in-box pricing dynamics, with petrochemical feedstock swings compressing converter margins before contractual adjustments reset. Three-tier pricing structure across premium gift cartons, standard institutional bag-in-box, and economy corrugated formats stratifies by certification grade and lithographic customization depth. Pricing pressure stems from digital print adoption fragmenting order patterns below viable offset thresholds. Direct-to-consumer subscription services exhibit highest price sensitivity, while Bordeaux estate wineries accepting rigid box specifications show lowest elasticity.
Supply Chain Analysis
Freight cost differentials between ocean freight to Asia-Pacific and intra-European trucking reshape insulated wine box procurement geography, with German logistics providers consolidating vacuum-insulated panel qualification ahead of F-Gas deadlines. Raw material sourcing concentrates in Sweden, Finland, and Germany for recycled fiberboard, while barrier film production rests on Belgian and Dutch petrochemical corridors. Single-source vulnerability from proprietary dispensing fitment interfaces locks wineries into incumbent supplier ecosystems. Distribution runs through supermarket chain procurement offices and direct-to-consumer fulfillment centers in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wine box market compounds steadily as EU packaging regulations tighten material specifications and subscription channels fragment order patterns toward agile converters.
For Market Incumbents: Extend barrier-coated kraft R&D pipelines to capture REACH-driven substitution demand before ECHA deadlines harden. Consolidate regulatory affairs capacity to parallel-track CE marking, FDA substance notifications, and EFSA migration testing, insulating against smaller converters choked by sequential approval bottlenecks. Deepen backward integration into recycled-paper supply chains to defend cost leadership as OCC volatility persists. For New Entrants and Emerging Players: Launch via web-to-print workflows targeting United Kingdom wine clubs with lot sizes below 500 units, exploiting digital print infrastructure gaps among legacy offset producers. Penetrate the temperature-sensitive export corridor niche where F-Gas-compliant insulated specifications command margin premiums and incumbent capacity remains constrained. Pursue FDA contact-substance certification as the specific go-to-market angle for transatlantic winery contracts. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale digital-print specialists with regulatory compliance capacity because subscription-channel fragmentation concentrates value in agile production footprints rather than scale-driven containerboard assets. Five-to-ten year viability hinges on capturing the material substitution wave from petrochemical barriers to aqueous-coated kraft. Target acquisition archetype: converters with dedicated regulatory affairs staffing and modular production lines. Watch ECHA chemical restriction timelines as the inflection signal for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coated Kraft Scale-Up | Aqueous coating R&D investments by Mondi plc and Smurfit Kappa Group capture REACH-driven EVOH substitution demand across French and Italian wineries. |
| Digital Print Infrastructure Deployment | Web-to-print workflows enable United Kingdom subscription services to order sub-500 unit lots with variable-data lithography, fragmenting production patterns. |
| FDA Contact-Substance Certification | European converters certifying liner materials unlock transatlantic distribution contracts and bypass regulatory arbitrage constraints on mid-scale competitors. |
| Vacuum-Insulated Panel Qualification | German logistics providers adopting climate-neutral insulation alternatives ahead of F-Gas Regulation deadlines capture Asia-Pacific export corridor premiums. |
| Extended Producer Responsibility Positioning | Converters pre-building collection infrastructure for French and Italian deposit-return pilots hedge against undefined wine box recovery economics. |
Research Methodology
Multiple input streams — primary interviews with packaging procurement managers at supermarket chains and winery supply chain directors, regulatory affairs consultations with ECHA and FDA specialists, and secondary validation through EU packaging directive filings and fiberboard trade association data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured converter capacity utilization, barrier film formulation transitions, and digital print adoption rates. Secondary sources included REACH compliance databases, FSC certification registries, and customs records for corrugated board trade flows.
Data-stream reconciliation across product type, material grade, feature specification, and end-user channel dimensions produced volume and value estimates across the projection horizon. Segmentation modeling incorporated bag-in-box versus folding carton format splits, certified fiberboard versus conventional grades, eco-friendly claims penetration, and direct-to-consumer versus institutional channel dynamics. CAGRs were derived from trend extrapolation of subscription service growth rates, REACH compliance deadline impacts on material substitution velocity, and digital print capacity expansion trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA chemical restriction timelines or stalled deposit-return scheme implementation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Brewing Enzymes Market