
 Rendered Poultry Products Market | 2026-2036
Rendered Poultry Products Market Size, Share, and Industry Trends Forecast 2026-2036
Rendered Poultry Products Market Analytics
REACH compliance in Europe is rebalancing the cost-of-entry calculus for rendered poultry exporters targeting EU animal feed channels. Tyson Foods Inc. leverages its integrated slaughter-to-render infrastructure across the southeastern United States to sustain margin capture. Darling Ingredients Inc. anchors its position through multi-species rendering scale and geographic diversification across North American and European facilities. JG Pears competes in the United Kingdom by specializing in poultry-byproduct valorization for premium pet nutrition brands.
Rendered poultry products encompass fats, protein meals, feather meals, and liver meals derived from the thermal or hydrolytic processing of slaughterhouse byproducts, with protein content in poultry meal typically ranging from 60% to 70% on a dry basis. These outputs serve as foundational inputs for compound animal feeds, organic fertilizers, and specialized pet food formulations where amino acid profiles and digestibility coefficients determine commercial value. Protein Meal dominates volume flows into aquaculture and swine nutrition channels, while Fat commands premium pricing from biodiesel and oleochemical applications. Hydrolysis is displacing conventional dry rendering in feather meal production as enzymatic processing improves digestibility metrics for pet food and aquafeed end users.
The FDA enforces BSE feed rules that prohibit ruminant-derived proteins in cattle feed, creating structural demand for poultry meal as a safe alternative protein source in US livestock nutrition. EFSA and national regulators under the EU Green Deal are tightening sustainability disclosure requirements for rendered products entering circular-economy supply chains. Stakeholders must monitor evolving maximum residue limits for dioxins and PCBs in rendered fats, as regulatory tightening in major import markets could redirect trade flows and reshape supplier qualification protocols.
Market Dynamics
The EU Green Deal's circular-economy mandates are compressing traditional rendering margins while redirecting capital toward higher-value protein fractionation and specialty fat refining. This regulatory pressure is forcing processors to reconfigure plant economics around premium pet nutrition and renewable diesel feedstock channels rather than commodity meal outputs.
Growth Catalysts
- Biodiesel Feedstock Demand:Renewable fuel mandates in Germany and the United States are absorbing rendered poultry fat at price premiums above historical commodity levels. Refiners are locking in multi-year offtake agreements with renderers.
- REACH Compliance Arbitrage:European importers are qualifying non-EU suppliers who can demonstrate full substance registration and traceability documentation. This creates structural advantage for integrated processors with in-house compliance capabilities.
- Hydrolytic Feather Processing:Enzymatic hydrolysis is improving digestibility coefficients for aquaculture and premium pet food applications. The technology unlocks amino acid profiles previously inaccessible through dry rendering methods.
Market Restraints
- Feedstock Cost Volatility:Live poultry slaughter volumes fluctuate with avian influenza cycles and consumer protein demand shifts. Renderers lack pricing power to pass input volatility through to contracted compound feed customers.
- Supplier Concentration Risk:The southeastern United States hosts disproportionate shares of integrated poultry slaughter capacity. Regional disease events or labor disruptions cascade immediately into raw material availability constraints.
- Dioxin Residue Thresholds:EFSA maximum limits for persistent organic pollutants in rendered fats are tightening qualification protocols for EU-bound shipments. Testing and certification burdens fall disproportionately on smaller independent operators.
Strategic Opportunities
- Pet Nutrition Premiumization:Specialty retailers and veterinary channels are demanding certified digestibility and species-specific amino acid profiles. Renderers with laboratory verification capabilities command price premiums in this segment.
- Brazilian Export Expansion:Integrated poultry processing clusters in São Paulo and Paraná states are underutilizing rendering capacity relative to slaughter volumes. Exporters can capture European and Asian demand with appropriate certification investments.
- CSRD Disclosure Alignment:The EU Corporate Sustainability Reporting Directive is mandating supply chain traceability for circular-economy inputs. Early movers in sustainability verification are securing preferred supplier status with multinational feed and food companies.
Industry Challenges
- Process Engineering Talent Scarcity:Hydrolytic and fractionation technologies require specialized expertise in enzymatic biochemistry and thermal processing optimization. The rendering sector competes poorly for this talent against pharmaceutical and food manufacturing employers.
- Legacy Equipment Retrofit Burden:Conventional dry rendering plants require substantial capital redeployment to produce premium-grade protein meals and low-impurity fats. Financing timelines lag regulatory compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rendered Poultry Products Market |
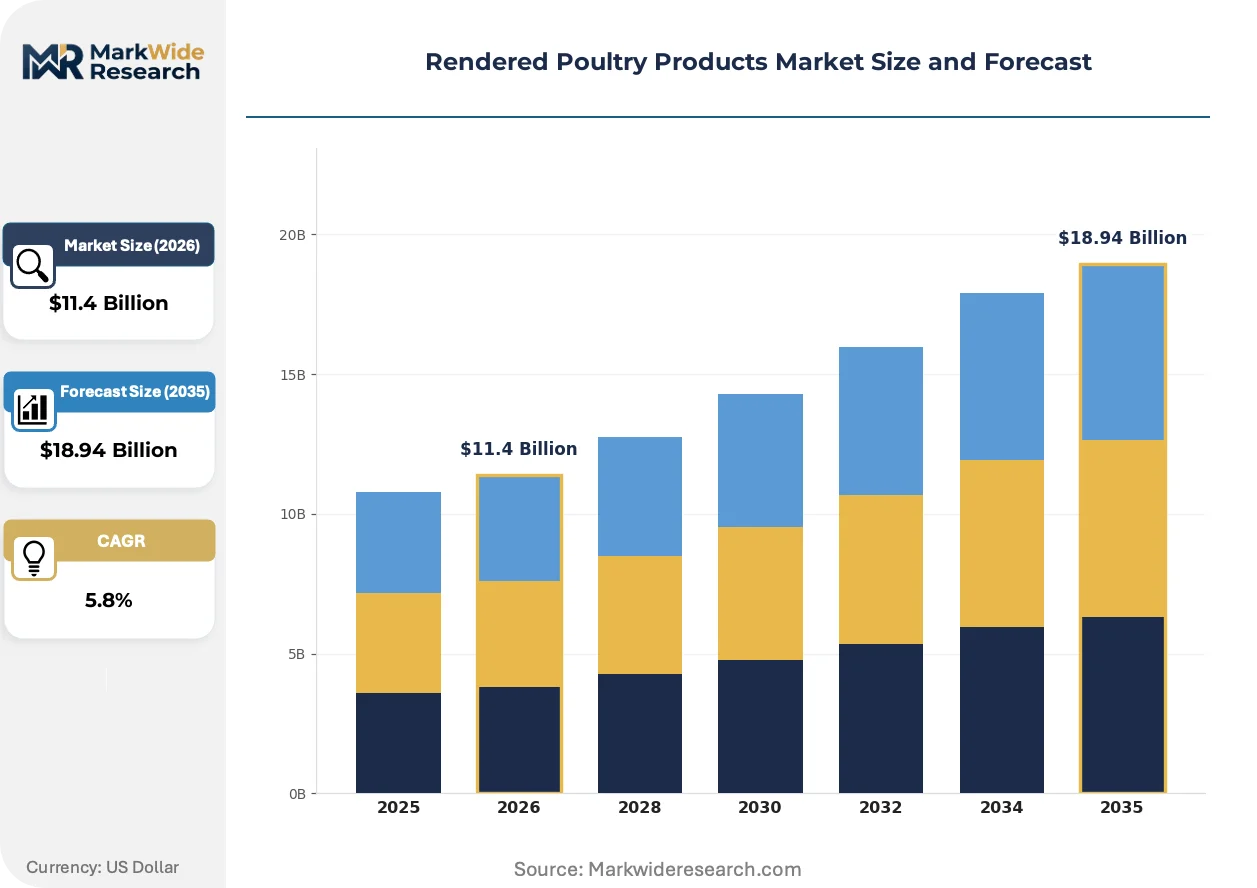
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fat, Protein Meal, Feather Meal, Liver Meal End Use Industry: Animal Feed, Fertilizers, Pet Food, Oils Processing Technique: Hydrolysis, Dry Rendering, Solvent Extraction, Thermal Processing Packaging Type: Sack, Bulk, Drum, Tote |
| Companies Covered | Tyson Foods Inc., Darling Ingredients Inc., JG Pears, West Coast Reduction Ltd., Brazilian Renderers, The Leo Group, The Tonnies Group, Akiolis Group, Allanasons Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rendered Poultry Products Market Evolving Landscape
Processing technology and regulatory disclosure requirements are converging to resegment the rendered poultry value chain. Differentiation is shifting from commodity volume toward verified nutritional specifications and sustainability credentials.
Enzymatic hydrolysis is overtaking conventional dry rendering in feather meal production. The technology cleaves keratin structures into digestible peptides through controlled protease application. Aquafeed manufacturers and premium pet food brands are specifying hydrolyzed feather meal in procurement contracts. This process shift is compressing margins for conventional dry-rendered meal while expanding addressable market size for verified high-digestibility products.
REACH registration requirements are extending substance documentation obligations to imported rendered protein meals and fats. The European Chemicals Agency is enforcing full supply chain disclosure for circular-economy feedstocks entering EU animal nutrition channels. Compound feed manufacturers are demanding batch-level traceability certificates from non-EU suppliers. German and Dutch importers are consolidating procurement around qualified renderers with established registration portfolios.
Direct contracting between renderers and renewable diesel refiners is displacing traditional broker-mediated fat trading. Refiners require consistent quality specifications and volume certainty for continuous processing operations. Long-term offtake agreements with fixed pricing mechanisms are replacing spot market transactions. This pattern is most visible in the United States, where biomass-based diesel capacity expansion is outpacing domestic rendered fat supply growth.
Rendered Poultry Products Market Segmentation
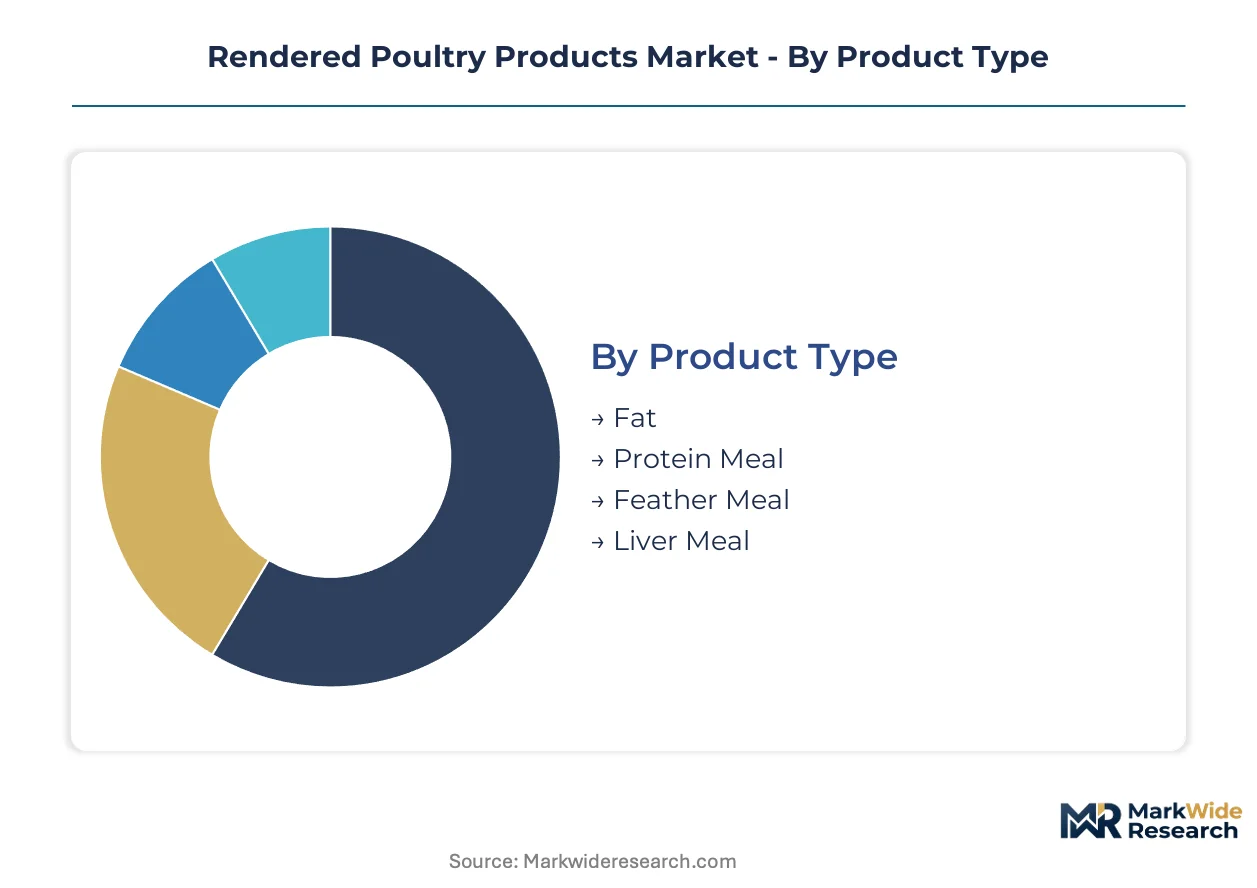
Segmentation in rendered poultry products reveals how processing economics and end-use specifications fragment value capture across the value chain. Buyers prioritize different attributes—protein digestibility coefficients, fat acidity levels, or sustainability credentials—depending on their downstream application.
Product Type:
Buyers in this category differentiate by nutritional specification requirements and pricing power in their respective end markets.
- Fat:Rendered poultry fat contains 90-95% triglycerides with low free fatty acid content, making it suitable for biodiesel and oleochemical applications. Demand concentrates in Germany and the United States where renewable diesel refiners lock in multi-year offtake agreements at premiums above commodity feedstock levels.
- Protein Meal:Poultry meal delivers 60-70% crude protein on a dry basis with balanced amino acid profiles for swine and aquaculture nutrition. Volume flows into compound feed manufacturing in the United States, Brazil, and Germany, with digestibility verification increasingly required for premium formulations.
- Feather Meal:Keratin-derived protein meal processed through enzymatic hydrolysis achieves digestibility coefficients above 75% for pet food applications. Hydrolysis investment separates premium suppliers from commodity dry-rendered output.
- Liver Meal:Organ-specific meal concentrates micronutrients and bioactive compounds for specialized pet nutrition and aquafeed formulations. Niche positioning limits scale but sustains margin premiums in veterinary and specialty retail channels.
Volume sits with Protein Meal; growth tilts toward Fat as renewable fuel mandates expand refinery demand.
End Use Industry:
Application-driven procurement patterns in this category reflect divergent certification requirements and price elasticity across downstream sectors.
- Pet Food:Premium brands specify hydrolyzed feather meal and certified digestibility metrics, with procurement concentrating in North American and European specialty retail channels. EFSA and FDA residue monitoring drives supplier qualification protocols.
- Animal Feed:Compound feed manufacturers represent the foundational demand base for rendered poultry meal, with BSE feed rules in the United States structurally favoring poultry-derived proteins over ruminant alternatives. Volume contracts dominate procurement with limited spot market exposure.
- Fertilizers:Organic agriculture certification programs in Germany and the Netherlands absorb rendered protein meals for soil amendment applications. Sustainability disclosure requirements under the EU Green Deal redirect procurement toward verified circular-economy suppliers.
- Oils:Biodiesel and oleochemical processors require consistent fat quality specifications with low moisture and impurity levels. Direct renderer-refiner contracting is displacing traditional broker-mediated trading in the United States and Germany.
Revenue concentrates in Animal Feed; margin expansion is steepest in Pet Food as premiumization accelerates.
Processing Technique:
Capital intensity and technical expertise requirements in this category stratify competitive positioning between legacy operators and technology-advantaged processors.
- Hydrolysis:Enzymatic processing cleaves keratin structures into digestible peptides for high-value pet nutrition and aquafeed applications. German and Dutch importers specify hydrolyzed products for premium formulations.
- Dry Rendering:Conventional thermal processing remains the volume backbone for commodity protein meal and fat production. Legacy asset bases in the southeastern United States and São Paulo state face retrofit pressure to meet tightening residue thresholds.
- Solvent Extraction:Selective lipid recovery achieves higher purity grades for pharmaceutical and cosmetic applications. Limited deployment due to capital requirements and solvent handling regulations.
- Thermal Processing:Controlled temperature profiles balance energy efficiency with protein denaturation management. Standard configuration for integrated poultry processing facilities with captive rendering operations.
Installed capacity favors Dry Rendering; technology investment flows most heavily into Hydrolysis.
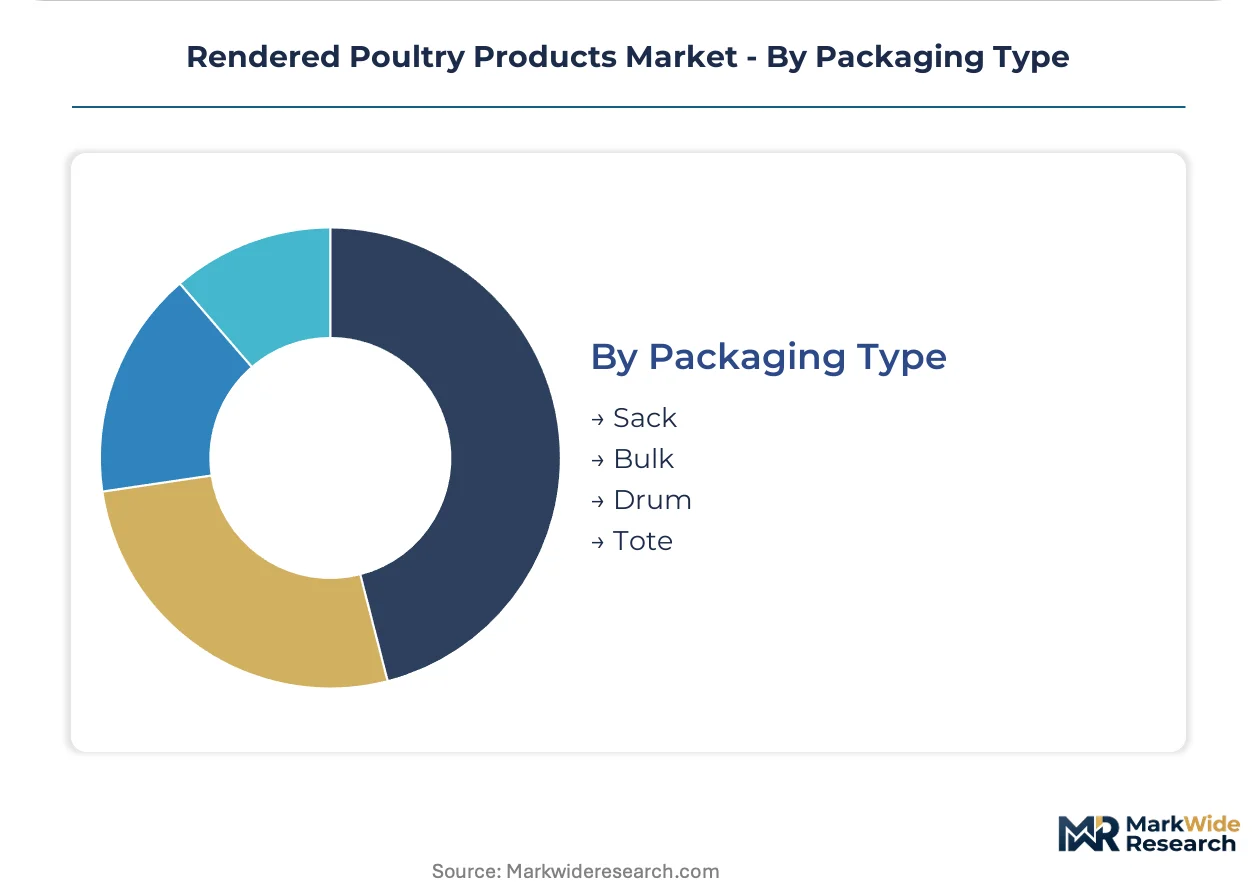
Packaging Type:
Logistics economics and contamination risk management drive packaging selection across customer scale and geographic distribution requirements.
- Bulk:Tanker and pneumatic trailer delivery minimizes unit costs for high-volume compound feed manufacturers with dedicated receiving infrastructure. Concentrated demand in the United States and Brazil where integrated processors operate captive rendering capacity.
- Sack:Multi-wall paper or woven polypropylene bags serve medium-scale feed mills and fertilizer blenders requiring inventory flexibility. REACH documentation obligations extend to packaging materials for EU-bound shipments.
- Drum:Steel or fiber drums protect high-value fats and specialty meals from oxidation and moisture ingress. Premium pet nutrition and pharmaceutical applications specify drum packaging for batch traceability.
- Tote:Intermediate bulk containers balance handling efficiency with contamination control for mid-volume buyers lacking bulk receiving capabilities. Growing preference among regional compound feed manufacturers in Germany and the United Kingdom.
Shipment volume concentrates in Bulk; specification-grade applications drive fastest adoption of Drum and Tote formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated poultry processing clusters in the United States, Germany, and Brazil absorb the majority of rendered poultry output, with renewable fuel mandates and pet nutrition premiumization reshaping regional demand patterns.
United States
Renewable diesel refiners in Iowa and Louisiana lock in multi-year offtake agreements for rendered poultry fat at premiums above commodity levels. The EPA enforces biomass-based diesel mandates under the Renewable Fuel Standard. Tyson Foods operates integrated slaughter-to-render infrastructure across Georgia and Arkansas.
Germany
Biodiesel processors in Hamburg and Rostock prioritize poultry fat for renewable diesel feedstock under national blending quotas. ECHA administers REACH registration requirements for imported protein meals. Darling Ingredients maintains multi-species rendering scale across Lower Saxony and North Rhine-Westphalia facilities.
Brazil
Compound feed manufacturers in São Paulo and Paraná states underutilize rendering capacity relative to slaughter volumes. ANVISA monitors residue limits for exported rendered products. Integrated processors in the São Paulo cluster are certifying for European and Asian export channels.
United Kingdom
Premium pet food brands specify hydrolyzed feather meal with certified digestibility metrics. The Food Standards Agency enforces sustainability disclosure alignment with EU Green Deal circular-economy principles. JG Pears specializes in poultry-byproduct valorization for veterinary and specialty retail channels.
Rendered Poultry Products Market Competitive Landscape
North American producers anchor one tier; European specialists hold differentiated positions in premium protein fractionation. The vendor base spans integrated poultry processors, multi-species rendering conglomerates, and regional byproduct valorization specialists. Strategic archetypes include captive rendering operations at slaughterhouses, independent toll processors, and sustainability-certified specialty suppliers. Competitive moves concentrate on direct refinery contracting for fat offtake and enzymatic hydrolysis investment for pet nutrition grades.
Among North American integrated processors, Tyson Foods Inc. and Darling Ingredients Inc. occupy positions defined by geographic diversification and multi-species scale. Tyson exemplifies the captive-rendering archetype through southeastern United States infrastructure. Darling represents the diversified rendering conglomerate with transatlantic facility networks. West Coast Reduction Ltd. anchors the independent processor tier with Canadian and western United States coverage.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| Darling Ingredients Inc. |
| JG Pears |
| West Coast Reduction Ltd. |
| Brazilian Renderers |
| The Leo Group |
| The Tonnies Group |
| Akiolis Group |
| Allanasons Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Enzymatic hydrolysis investment is simultaneously elevating capital requirements for premium protein meal production and compressing margins for conventional dry-rendered output, concentrating pricing power among technology-advantaged processors in Germany and the United States while fragmenting commodity-tier supply.
Pricing Analysis
Volume concentrates in commodity protein meal and fat contracts; margin expansion accrues to hydrolyzed feather meal and certified pet nutrition grades. Three-tier pricing structure separates REACH-registered specialty suppliers from standard-grade exporters and unregistered economy-tier traders. Cost compression in conventional dry-rendered meal intensifies because European importers are consolidating procurement around qualified renderers with established registration portfolios. Compound feed manufacturers exhibit highest price sensitivity due to fixed formulation budgets, while renewable diesel refiners absorb premiums for consistent fat quality specifications.
Supply Chain Analysis
Direct-to-refinery channels handle renewable diesel demand in Iowa and Louisiana, displacing traditional broker-mediated fat trading. Raw material supply concentrates in the United States, Brazil, and Germany where integrated poultry processing clusters feed captive rendering operations. The supply chain draws from live poultry slaughter volumes, enzyme inputs for hydrolysis, and energy feedstocks for thermal processing. Single-source vulnerability in southeastern United States slaughter capacity exposes renderers to regional disease events and labor disruptions. Distribution runs through bulk tanker networks for compound feed manufacturers, with drum and tote formats penetrating premium pet nutrition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rendered poultry products sector is navigating a technology-transition phase as enzymatic hydrolysis displaces conventional dry rendering for high-digestibility protein applications.
For Market Incumbents: Hedge margin exposure in commodity meal by retrofitting legacy dry rendering assets toward hydrolysis capacity for pet nutrition and aquafeed grades. Deepen backward integration into captive poultry slaughter supply through long-term offtake agreements with processors in São Paulo and Paraná states. Prioritize REACH registration investment to defend European market access against tightening ECHA substance documentation requirements.
For New Entrants and Emerging Players: Enter via underutilized rendering capacity in Brazilian integrated poultry clusters, certifying for EU and Asian export channels where supply gaps persist. Target specialty pet nutrition formulations requiring certified amino acid profiles and digestibility verification. Pursue toll processing partnerships with established brands lacking in-house hydrolysis capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multi-species rendering conglomerates seeking geographic diversification or renewable diesel refiners securing upstream fat supply. Long-term viability favors processors with demonstrated compliance infrastructure and technology-advantaged product portfolios. Monitor EFSA dioxin threshold tightening and EPA renewable fuel mandate expansion as inflection indicators for asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrolysis Capacity Expansion | Enables premium pet nutrition qualification under EFSA digestibility protocols. |
| REACH Registration Investment | Secures EU market access as ECHA enforces full supply chain disclosure. |
| Direct Refinery Contracting | Locks in multi-year fat offtake with renewable diesel producers in Germany and the United States. |
| Brazilian Export Certification | Captures European and Asian demand through ANVISA-aligned residue monitoring systems. |
| CSRD Disclosure Alignment | Qualifies suppliers for preferred procurement status with multinational feed companies under EU Green Deal mandates. |
Research Methodology
Multi-period observation of slaughter volume trends, rendering capacity utilization, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with plant operations managers at integrated poultry processors, procurement leads at compound feed manufacturers, sustainability officers at pet nutrition brands, and regulatory affairs specialists at rendering facilities. Secondary validation drew from FDA BSE feed rule filings, EFSA scientific opinions on dioxin thresholds, EPA renewable fuel standard dockets, and customs trade data for rendered protein meal and fat shipments. Bottom-up facility-level capacity modeling and top-down end-use demand estimation were triangulated against disclosed utilization rates.
Input-output matrices mapped raw material slaughter volumes through processing technique yields to end-use industry absorption across product type, processing method, and geographic production cluster dimensions. CAGRs were derived from segmented growth rate assumptions calibrated to historical volume elasticities and projected regulatory mandate impacts. Forecast inputs incorporated renewable diesel capacity buildout schedules, EU Green Deal circular-economy implementation timelines, and avian influenza cycle patterns affecting feedstock availability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained avian influenza disruptions or accelerated EFSA residue limit tightening. Practitioners should monitor EPA renewable volume obligation announcements, ECHA REACH enforcement actions, and Brazilian ANVISA export certification expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Bacon Flavors Market
Meat Products
Meat-Based FPP Market
Meat Products
North America Edible Meat Market
Meat Products
Europe Poultry Meat Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Brisket Market
Meat Products
Reconstituted Meat Market
Meat Products
Emulsified Meat Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Shark Meat Market
Meat Products
Sausage Premixes Market
Meat Products
Meat Flavors Market
Meat Products
United States Bacon Market
Meat Products
France Meat Products Market
Meat Products
North America Poultry Meat Market
Meat Products
Antibiotic Free Meat Market