
 India Pharmaceutical Contract Sales Organizations Market | 2026-2036
India Pharmaceutical Contract Sales Organizations Market Size, Share, and Industry Trends Forecast 2026-2036
India Pharmaceutical Contract Sales Organizations Market Insights
The PLI scheme for pharmaceuticals is repositioning how domestic and multinational manufacturers build commercial infrastructure in India. Indegene leverages its technology backbone to deliver analytics-driven field force deployment across therapy areas. IQVIA Inc. anchors its India operations through deep relationships with top-tier pharmaceutical manufacturers seeking compliance-ready sales networks. Mednext Pharma Pvt. Ltd. specializes in mid-market generics producers that require flexible, state-level coverage without fixed overhead.
Pharmaceutical contract sales organizations are external service providers that deploy trained medical representatives, execute physician detailing programs, and manage sampling logistics on behalf of drug manufacturers, typically operating under strict CDSCO promotional code guidelines and client-specific standard operating procedures. The service type dimension shows detailing and sales force management commanding the largest share of engagement value, while market access services are expanding fastest as price control negotiations and hospital formulary inclusion grow more complex. Client type segmentation reveals pharmaceutical manufacturers as the established revenue base, with biotech companies representing the fastest-growing contract origin as emerging biologics firms lack in-house commercial scale.
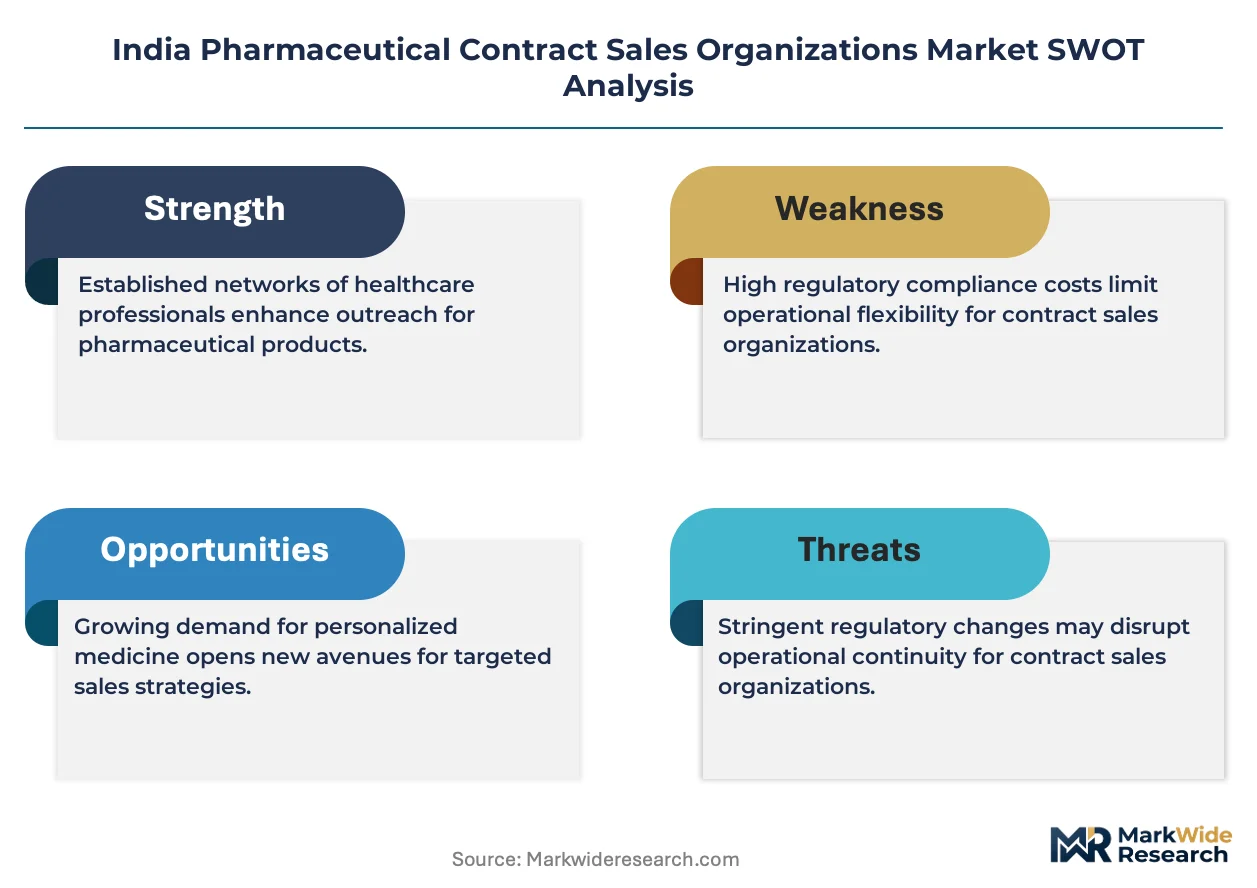
CDSCO promotional regulations, the Drugs and Magic Remedies Act, and state-level pharmacy council licensing requirements collectively shape permissible sales activities, compensation structures, and training protocols for field personnel operating across Indian territories. BIS quality benchmarks for promotional materials and the evolving DCC framework on ethical marketing practices are tightening compliance thresholds for CSO contracts. Stakeholders must monitor how digitization of physician engagement intersects with existing regulatory guardrails to determine capital allocation between traditional field forces and hybrid commercial models.
Market Dynamics
The PLI scheme for pharmaceuticals is restructuring commercial infrastructure decisions across domestic manufacturers, accelerating their shift from captive field forces to outsourced deployment models as compliance thresholds intensify.
Growth Catalysts
- CDSCO promotional code tightening:Manufacturers face escalating training and audit burdens for in-house medical representatives, driving demand for compliance-certified CSO partners with established SOP frameworks.
- Biologics pipeline expansion:Emerging domestic biotech firms lack commercial scale for specialty therapies, creating immediate contract demand for field forces with oncology and immunology detailing expertise.
- Maharashtra cluster density:Mumbai and Pune host concentrated pharma headquarters alongside specialized CSO operations, reducing coordination friction and enabling rapid deployment ramp-ups.
Market Restraints
- Medical representative wage inflation:Trained field personnel command premium compensation in competitive therapy areas, compressing CSO margin structures and limiting price flexibility.
- Single-state licensing fragmentation:Pharmacy council requirements vary across Indian territories, forcing redundant certification investments that constrain national coverage scalability.
- Digital detailing substitution:Tele-detailing platforms and physician portal engagement tools threaten traditional face-to-face sampling models in metro markets.
Strategic Opportunities
- Tier-2 city penetration:Nasik, Indore, and Lucknow exhibit rising specialist physician density without proportional CSO presence, creating first-mover expansion corridors.
- Hospital formulary services:Price control negotiations and institutional procurement committees demand dedicated market access expertise that manufacturers increasingly outsource.
- Analytics-integrated deployment:Convergence of physician prescribing data platforms with field force scheduling algorithms enables outcome-linked contract structures previously unavailable.
Industry Challenges
- CDSCO promotional material clearance timelines:BIS quality benchmarks for visual aids and leave-behind literature extend campaign launch cycles, requiring working capital buffers.
- Legacy CRM integration:Manufacturer-specific sales force automation systems demand costly middleware development for seamless CSO data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Pharmaceutical Contract Sales Organizations Market |
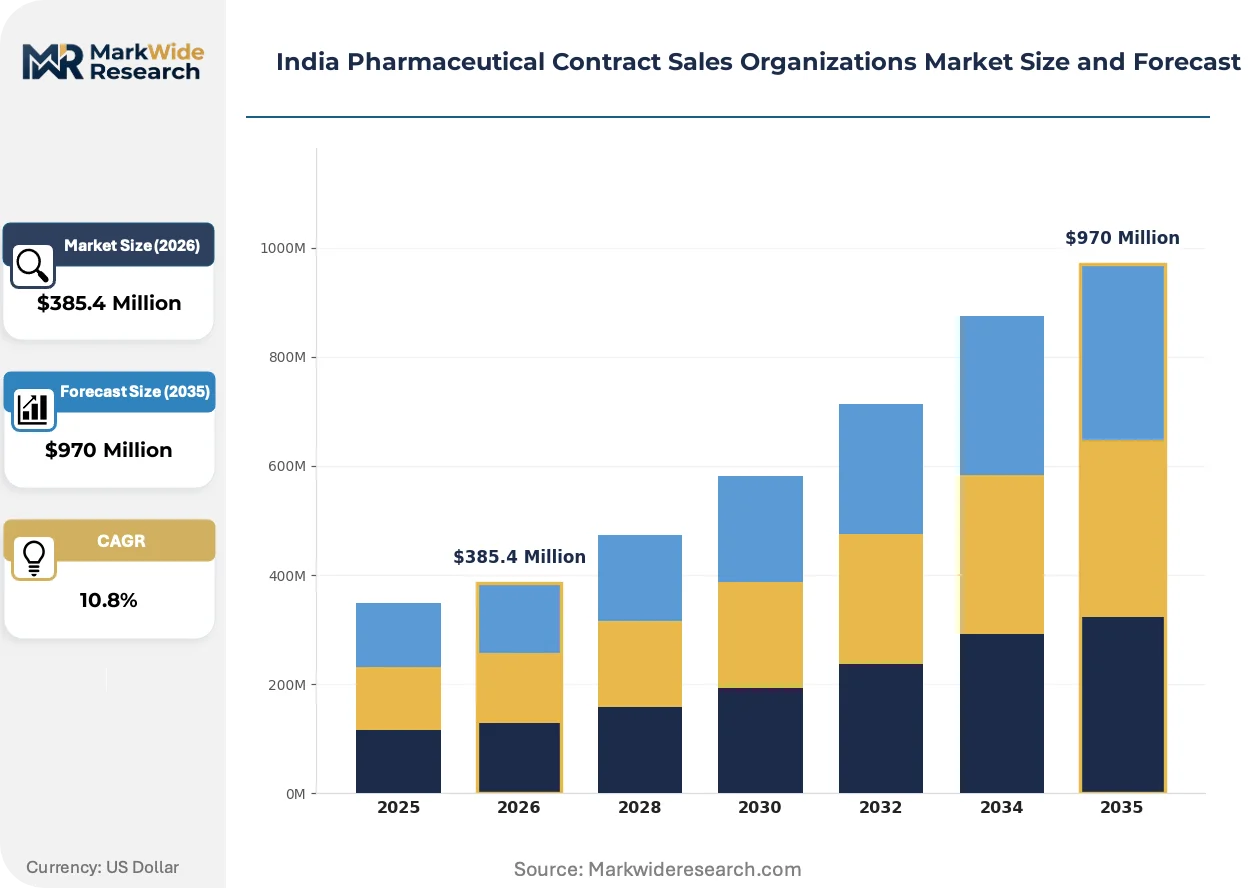
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $970 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Detailing, Sampling, Sales Force Management, Market Access Client Type: Pharmaceutical Manufacturers, Biotech Companies, Generics Producers, Consumer Health Offering: Outsourced Sales, Marketing Support, Training Services, Field Force Solutions Distribution Channel: Direct Sales, Online Platforms, Distributors, Wholesalers |
| Companies Covered | Indegene, Axxelus, IQVIA Inc., Mednext Pharma Pvt. Ltd., EPS Corporation, Syneos Health, ICON plc, QFR Solutions, CMIC Holdings Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Pharmaceutical Contract Sales Organizations Market Trends and Innovations
Digital infrastructure is reconfiguring how physician engagement gets delivered and measured, compressing the traditional field-force model while creating hybrid commercial architectures.
AI-powered physician targeting platforms are decentralizing territory allocation decisions away from static geographic boundaries toward dynamic prescribing-pattern clusters. Mid-market generics manufacturers adopt these tools fastest, replacing intuition-based rep deployment with algorithmic call planning. The structural consequence is decentralizing field force hierarchies into smaller, therapy-specialized pods that report through data science functions rather than regional sales managers.
CDSCO's evolving DCC framework on ethical marketing practices is mandating granular disclosure of promotional expenditure and physician engagement records. Pharmaceutical manufacturers must now maintain audit-ready documentation of every detailing interaction, sampling event, and continuing medical education sponsorship. Biologics-focused CSOs invest most heavily in compliance infrastructure, building dedicated regulatory affairs layers that smaller competitors cannot replicate.
Specialist physicians in cardiology and endocrinology increasingly restrict physical access to industry representatives, preferring digital scientific exchanges and self-service medical information portals. Hospital-owned clinic networks are formalizing these access protocols, replacing open-door policies with scheduled virtual engagement windows. This pattern concentrates most visibly in Delhi-NCR and Bengaluru, where corporate hospital chains dominate outpatient delivery.
India Pharmaceutical Contract Sales Organizations Market Segmentation
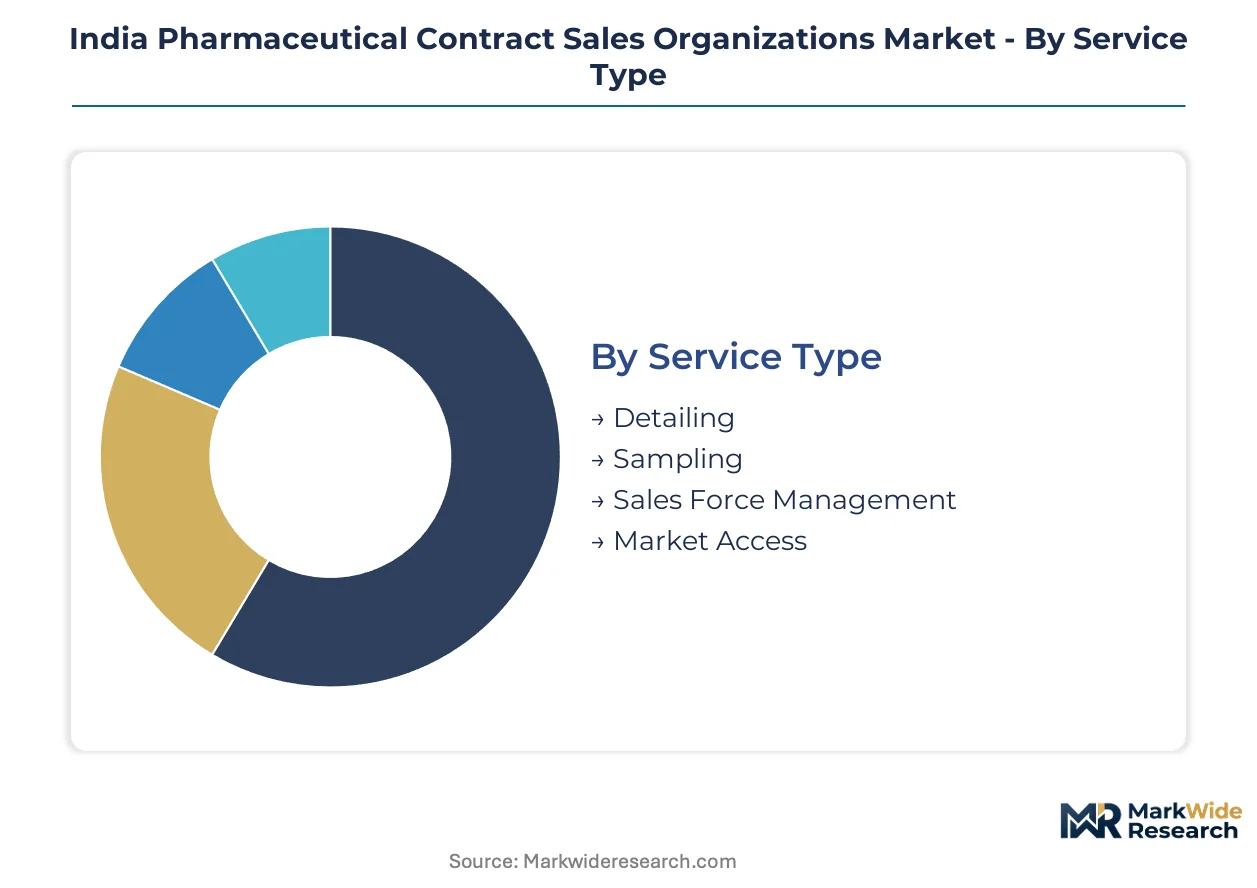
CSO contracts in India fragment across service depth, client sophistication, and deployment architecture. Each dimension reveals distinct margin structures and compliance burdens that reshape vendor selection criteria.
Service Type:
Standalone detailing engagements operate as discrete campaign modules, while sales force management embeds into manufacturer commercial infrastructure.
- Detailing:Physician-facing product education delivered by trained medical representatives under CDSCO promotional code protocols. Maharashtra's Mumbai-Pune corridor concentrates demand as specialty clinics proliferate and compliance audit frequency intensifies.
- Sales Force Management:End-to-end recruitment, deployment, and performance oversight of field personnel integrated with client CRM systems. Biologics manufacturers in Bengaluru and Hyderabad outsource this function to avoid fixed overhead during pipeline commercialization.
- Sampling:Logistics coordination for promotional drug distribution to prescribing physicians.
- Market Access:Hospital formulary inclusion and price negotiation support with institutional procurement committees.
Volume placements concentrate in Detailing; the faster expansion belongs to Market Access.
Client Type:
Cost tiers separate established multinationals from emerging domestic players with constrained commercial budgets.
- Pharmaceutical Manufacturers:Large-scale innovators and established generics houses with national therapy portfolios. These clients demand CDSCO-compliant field forces across multiple states, prioritizing audit-ready documentation over per-call economics.
- Biotech Companies:Emerging domestic biologics firms lacking captive commercial infrastructure. Nascent oncology and immunology specialists in Gujarat and Telangana drive contract growth as PLI scheme incentives accelerate pipeline maturity.
- Generics Producers:Mid-market manufacturers competing on volume and state-level coverage flexibility.
- Consumer Health:Over-the-counter and wellness product companies requiring pharmacy channel penetration.
Contract value concentrates among Pharmaceutical Manufacturers; Biotech Companies are climbing the fastest.
Offering:
Geographic deployment patterns distinguish centralized hub operations from distributed field networks.
- Outsourced Sales:Full commercial function delegation including territory mapping, call planning, and incentive administration. Tier-2 cities such as Indore and Lucknow attract first-mover deployment as specialist physician density rises without proportional CSO presence.
- Field Force Solutions:Modular personnel provision with client-directed activity management. Maharashtra and Karnataka manufacturers embed these arrangements to maintain direct control over physician relationships while shedding employment liability.
- Marketing Support:Promotional material design, campaign analytics, and event management services.
- Training Services:CDSCO-mandated certification programs and therapy area education for medical representatives.
Maharashtra anchors Outsourced Sales deployment; Field Force Solutions gain share fastest in southern states.
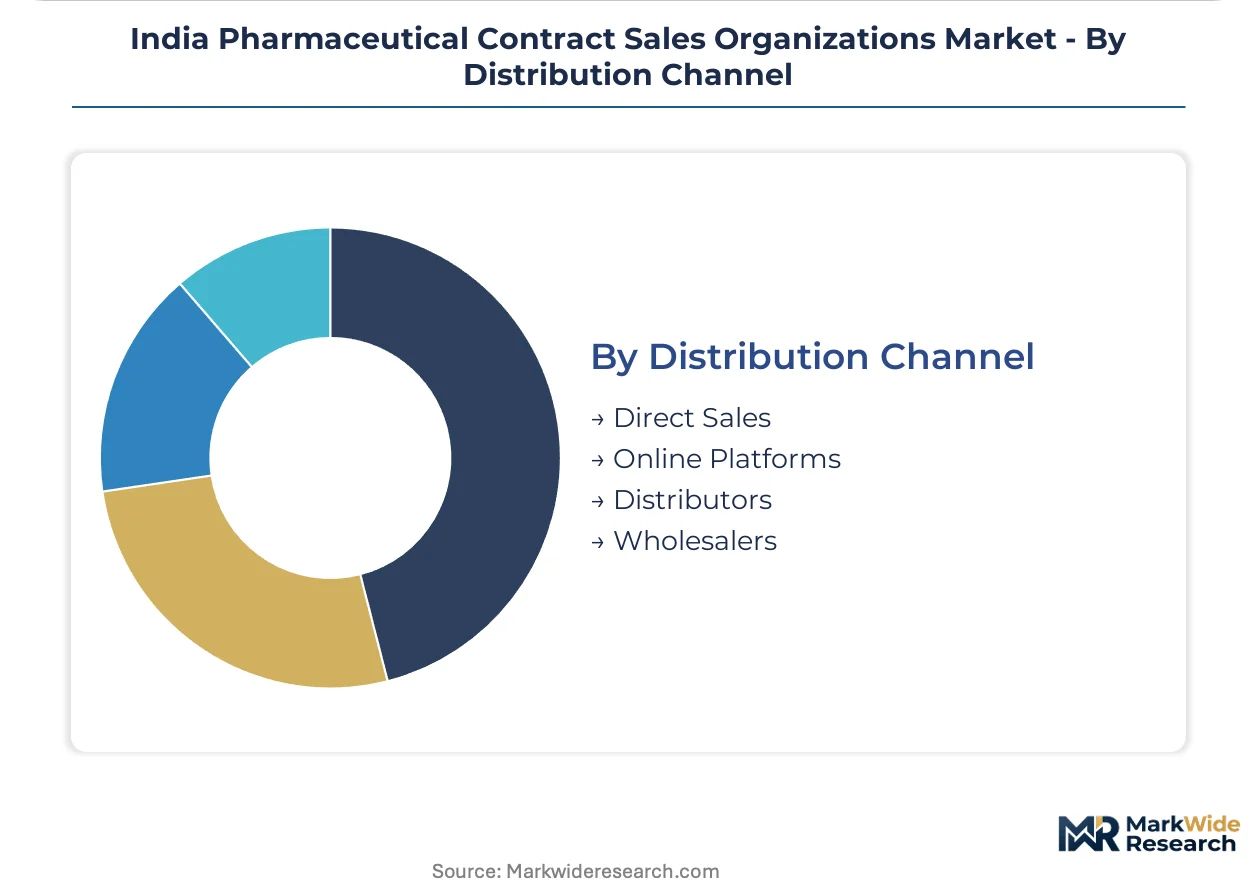
Distribution Channel:
Margin structures vary sharply between direct client relationships and intermediary-mediated contracts.
- Direct Sales:Bilateral contracts between CSO operators and pharmaceutical manufacturers without channel intermediaries. Mumbai and Delhi-NCR headquarters of major manufacturers sustain this channel despite longer sales cycles.
- Distributors:Regional intermediaries aggregating CSO demand from smaller generics producers. Fragmented state-level pharmacy council licensing requirements force distributors to maintain redundant certification infrastructure across territories.
- Online Platforms:Digital marketplaces for CSO service procurement and field force scheduling.
- Wholesalers:Traditional procurement channels for standardized training and marketing support packages.
Direct Sales commands premium pricing; Distributors are expanding most quickly in underserved northern and eastern markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pharmaceutical contract sales services concentrates in states hosting dense pharmaceutical headquarters clusters and emerging biotech corridors. CDSCO compliance requirements and PLI scheme incentives are redistributing field force deployment across India's commercial landscape.
Maharashtra
Specialty clinic proliferation in Mumbai and Pune drives detailing demand as audit frequency intensifies under CDSCO promotional code revisions. The state's pharmacy council maintains stringent medical representative licensing standards that favor established CSO operators with compliance infrastructure. Mumbai anchors the densest concentration of pharma headquarters alongside specialized contract sales operations.
Karnataka
Bengaluru's biologics pipeline expansion creates immediate demand for oncology and immunology field force expertise. Biotech companies lacking captive commercial scale outsource sales force management to avoid fixed overhead during pipeline commercialization. The city's corporate hospital chains dominate outpatient delivery and increasingly restrict physical access to industry representatives.
Telangana
Hyderabad's vaccine and biosimilar manufacturing base generates contract demand for institutional procurement committee navigation. State-level pharmacy council requirements here align with national CDSCO frameworks, reducing certification friction for multi-territory operators. The Genome Valley corridor attracts PLI scheme beneficiaries seeking rapid commercial deployment.
Gujarat
Ahmedabad and Vadodara host mid-market generics producers requiring flexible state-level coverage without fixed overhead. The state's pharmaceutical manufacturing density outpaces proportional CSO presence, creating pricing leverage for early entrants. DGFT export incentive structures here indirectly support contract sales investment through expanded manufacturer revenue pools.
Delhi-NCR
Corporate hospital chains in Gurugram and Faridabad formalize access protocols, replacing open-door policies with scheduled virtual engagement windows. Price control negotiations with central procurement bodies demand dedicated market access expertise that manufacturers increasingly outsource. The region's regulatory proximity to CDSCO headquarters accelerates compliance documentation requirements.
India Pharmaceutical Contract Sales Organizations Market Competitive Landscape
Maharashtra-based operators anchor one tier; southern and western specialists hold differentiated positions in biologics and generics verticals. The vendor base separates into compliance-heavy full-service providers, technology-enabled analytics platforms, and flexible mid-market coverage specialists. Three archetypes dominate: PLI-scheme-aligned biologics partners, legacy generics field force operators, and hybrid digital-physical deployment platforms. Competitive moves concentrate on regulatory certification stacking and therapy-area credential acquisition rather than price-based displacement.
Within the technology-enabled tier, Indegene occupies a position exemplifying analytics-driven field force deployment across therapy areas. IQVIA Inc. anchors the compliance-certified segment through relationships with top-tier pharmaceutical manufacturers seeking audit-ready sales networks. Mednext Pharma Pvt. Ltd. represents the mid-market flexibility archetype, serving generics producers requiring state-level coverage without fixed overhead commitment.
| Leading Market Players |
|---|
| Indegene |
| Axxelus |
| IQVIA Inc. |
| Mednext Pharma Pvt. Ltd. |
| EPS Corporation |
| Syneos Health |
| ICON plc |
| QFR Solutions |
| CMIC Holdings Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
CDSCO's evolving DCC framework on ethical marketing practices gates qualified supply for premium-tier CSO contracts, as compliance-certified field force providers command pricing power while uncertified operators face margin compression from audit liability.
Pricing Analysis
Short lead-time deployment commands premium pricing in the Maharashtra corridor, while spot-market field force availability trades at discounts due to training lag and certification gaps. Three-tier pricing structure across compliance-heavy, standard, and economy levels segments buyers by audit readiness requirements. Cost compression in economy-tier coverage is intensifying because single-state licensing fragmentation forces redundant certification investments. Mid-market generics producers exhibit highest price sensitivity, whereas biologics manufacturers prioritize CDSCO audit-ready documentation over per-call economics.
Supply Chain Analysis
Trained medical representative supply rests on Maharashtra, Karnataka, and Telangana educational infrastructure, with specialized oncology and immunology detailing expertise concentrated in Bengaluru and Hyderabad training institutes. Key inputs include CDSCO-mandated certification programs, therapy-specific educational curricula, and BIS-compliant promotional material production. Single-source vulnerability runs through concentrated biologics-focused training institutes serving the Genome Valley corridor. Distribution runs through direct bilateral contracts with pharmaceutical headquarters in Mumbai and Delhi-NCR, supplemented by regional intermediaries aggregating demand from smaller generics producers in underserved northern and eastern territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-powered physician targeting platforms are displacing intuition-based rep deployment, compressing traditional field-force hierarchies while rewarding analytics-integrated CSO operators with outcome-linked contract structures.
For Market Incumbents: To counter digital detailing substitution in metro markets, incumbents must deepen backward integration into proprietary physician prescribing data platforms and expand compliance infrastructure investments ahead of CDSCO promotional code revisions. Capacity addition in Tier-2 cities such as Indore and Lucknow captures rising specialist physician density without proportional CSO presence.
For New Entrants and Emerging Players: Analytics-first deployment algorithms offer entry wedge against legacy field-force operators entrenched in Maharashtra. Nascent hospital formulary services in Delhi-NCR represent the most penetrable white space, with dedicated market access expertise for price control negotiations commanding premium positioning. Go-to-market should emphasize outcome-linked contract structures tying field force scheduling to prescribing-pattern clusters.
For Investors and Strategic Acquirers: PLI scheme beneficiary announcements are the leading indicator that biologics pipeline commercialization will accelerate contract demand for oncology and immunology field force expertise. Long-term viability favors CSO operators with stacked regulatory certifications and therapy-area credential depth that smaller competitors cannot replicate. Acquisition targets should demonstrate integrated compliance infrastructure with CDSCO audit-ready documentation systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Infrastructure Investment | CDSCO audit-ready documentation systems differentiate premium-tier CSO operators from economy competitors. |
| Analytics Platform Integration | AI-powered physician targeting enables outcome-linked contracts previously unavailable to traditional field-force operators. |
| Tier-2 City Deployment Expansion | Indore and Lucknow specialist physician density rises without proportional CSO presence, creating first-mover corridors. |
| Hospital Formulary Services Buildout | Delhi-NCR corporate hospital chains formalize access protocols, demanding dedicated market access expertise. |
| Biologics Field Force Specialization | Oncology and immunology detailing expertise captures PLI scheme accelerated pipeline commercialization in Genome Valley. |
Research Methodology
Document review covered CDSCO regulatory filings, PLI scheme beneficiary announcements, and state pharmacy council licensing records, complemented by interviews with contract sales executives, regulatory affairs leads, medical representative training directors, and hospital formulary managers. Secondary validation drew from BIS quality benchmark disclosures, DCC framework evolution documents, and pharmaceutical manufacturer CRM procurement records. Bottom-up field force deployment estimates triangulated against top-down pharmaceutical commercial spending allocations.
Cross-referencing historical deployment patterns with panel input from CSO operators and manufacturer procurement heads shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service type depth, client sophistication tier, geographic deployment architecture, and therapy area specialization intensity. CAGRs derived from polynomial trend fitting of contract value trajectories, with biologics pipeline maturity curves and CDSCO compliance cost inflation as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated digital detailing substitution or abrupt PLI scheme restructuring. A small set of named triggers warrants ongoing watch: CDSCO promotional material clearance timeline extensions, medical representative wage inflation spikes, and corporate hospital chain access protocol formalization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Seasonal Influenza Vaccines Therapeutics Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
Global Bispecific Antibody Therapeutics Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Fucosidosis Therapeutics Market