
 MEMS and Sensor Performance and Reliability Test Equipment Market | 2026-2036
MEMS and Sensor Performance and Reliability Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS and Sensor Performance and Reliability Test Equipment Market Insights
Buyer concentration among semiconductor manufacturers is decoupling from traditional electronics OEMs as automotive suppliers and aerospace firms expand their in-house MEMS validation capabilities. Advantest leverages its probe card integration to dominate high-frequency sensor test cells. Teradyne sustains R&D intensity in multi-site parallel testing architectures for cost-sensitive MEMS die.
MEMS and sensor performance and reliability test equipment comprises vibration test systems, thermal chambers, and signal analyzers engineered to subject microelectromechanical devices to temperature cycling between minus 40 degrees Celsius and 150 degrees Celsius, mechanical shock up to 2000 G-force, and electromagnetic interference profiling to verify drift stability and failure thresholds prior to volume integration. Vibration test systems anchor the product portfolio due to ubiquitous accelerometer qualification protocols across automotive and consumer electronics supply chains. Thermal chambers capture expanding margin pools as wide-temperature-range calibration becomes mandatory for lidar and radar sensors deployed in electric vehicle powertrains.
FDA medical device quality system regulation and NHTSA functional safety mandates for automotive sensors shape equipment specifications by requiring traceable calibration records and deterministic failure-mode documentation. The EU AI Act and CE marking directives impose conformity assessment burdens on sensor modules with embedded decision logic, pushing test houses toward automated optical inspection and electromagnetic compatibility verification suites. Stakeholders must monitor how semiconductor export controls and evolving automotive safety standards reshape the addressable customer base for multi-physics test platforms.
Market Dynamics
Automotive electrification and autonomous driving architectures are compressing validation cycles for multi-axis inertial sensors, forcing test equipment suppliers to integrate thermal-vibration-electromagnetic tri-physics capabilities into single platforms.
Growth Catalysts
- NHTSA functional safety mandates:Deterministic failure-mode documentation requirements for automotive sensors expand traceable calibration equipment procurement across Tier 1 suppliers.
- Lidar thermal calibration:Wide-temperature-range validation protocols for electric vehicle powertrain sensors drive chamber specification upgrades in Germany's automotive cluster.
- China's dual carbon goals:Environmental test chamber efficiency standards tighten refrigerant specifications and accelerate replacement demand for legacy thermal systems.
Market Restraints
- Helium supply concentration:Thermal chamber leak detection and cryogenic cooling dependencies expose equipment manufacturers to Qatar and Russia supply disruptions.
- High-frequency probe card costs:RF MEMS test cell capital intensity limits in-house validation adoption among mid-tier sensor module producers.
- EU F-Gas Regulation phase-down:Refrigerant transition timelines compress equipment redesign windows and strand installed base upgrade paths.
Strategic Opportunities
- India BIS certification expansion:Mandatory sensor quality marks for automotive and industrial applications create greenfield test house demand in Pune and Chennai manufacturing corridors.
- Photonics-MEMS convergence:Integrated optical inertial measurement units require hybrid test platforms combining interferometric and electromechanical validation protocols.
- Subscription-based equipment access:Capital-light validation models for startup sensor designers bypass traditional capital expenditure barriers in Israel and Taiwan.
Industry Challenges
- Multi-physics simulation expertise:Cross-functional engineers combining finite element thermal modeling with RF signal integrity analysis command premium compensation and extended recruitment cycles.
- ISO 17025 accreditation timelines:Third-party calibration laboratory certification delays stretch 14-18 months, constraining test house expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS and Sensor Performance and Reliability Test Equipment Market |
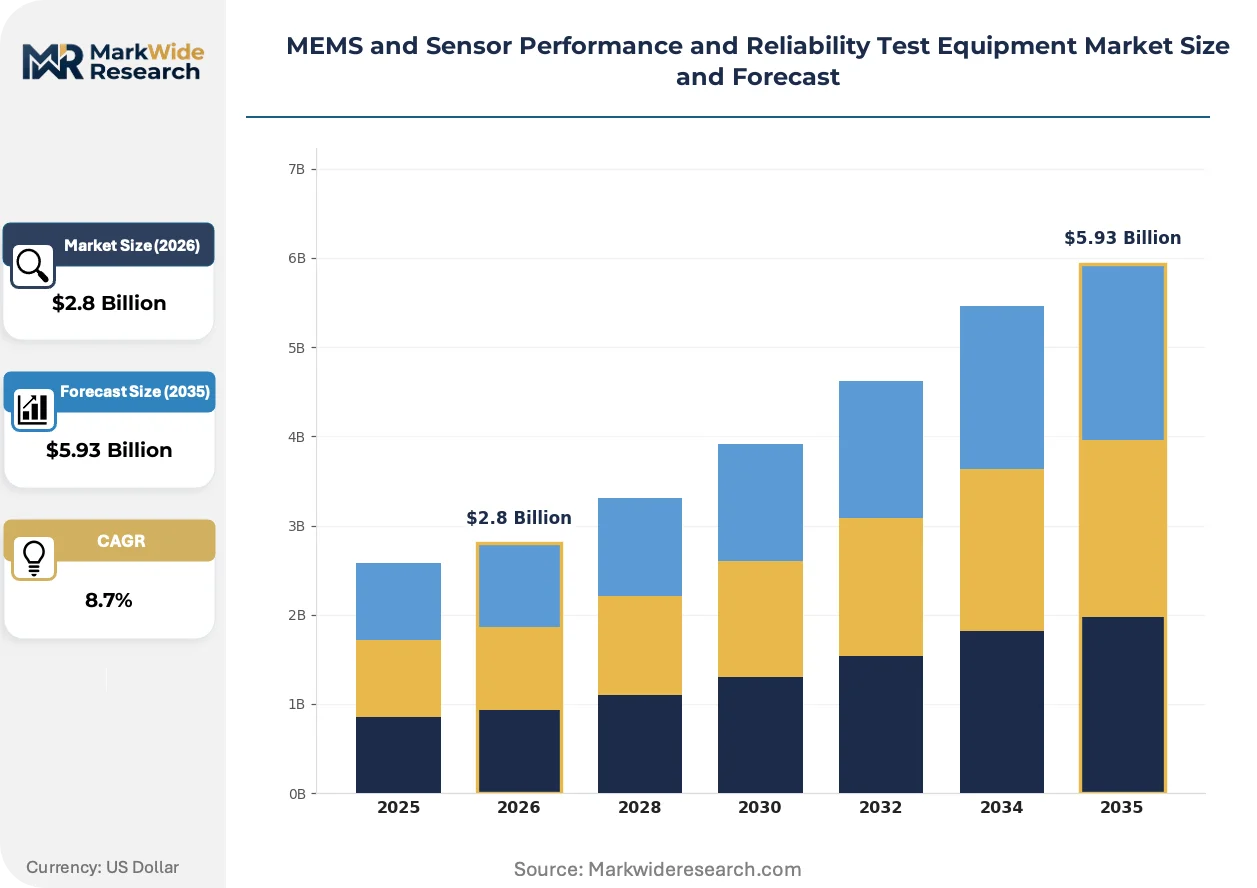
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibration Test Systems, Thermal Chambers, Environmental Test Chambers, Signal Analyzers, Data Acquisition Systems Technology: Acoustic Emission, Accelerometer Testing, Thermal Shock, Electromagnetic Compatibility, Optical Inspection Application: Quality Inspection, Durability Testing, Calibration, Failure Analysis, Sensitivity Assessment End User: Semiconductor Manufacturers, Electronics OEMs, Research Laboratories, Automotive Suppliers, Aerospace Firms |
| Companies Covered | Advantest, Teradyne, Cohu, Keysight Technologies, National Instruments, SPEA, Yokogawa Test & Measurement, FormFactor, Chroma ATE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS and Sensor Performance and Reliability Test Equipment Market Trends and Innovations
Distributed validation architectures and embedded self-test capabilities are fragmenting traditional centralized test floor models, compressing capital deployment patterns and reshaping equipment form factors.
Edge-deployed sensor self-diagnostics is decentralizing reliability verification from end-of-line test cells to in-field continuous monitoring. Automotive OEMs in Stuttgart and Munich are piloting accelerometer drift-tracking firmware that reduces incoming inspection sampling rates by half. This compression of pre-integration validation scope threatens standalone vibration test system replacement cycles.
The EU AI Act conformity assessment framework is mandating electromagnetic compatibility and deterministic behavior documentation for sensor modules with embedded decision logic. Test houses in Germany and France are retrofitting optical inspection suites and RF anechoic chambers to capture expanded certification scope. Lidar and radar sensor suppliers face the steepest compliance burden escalation.
Consolidated procurement consortia among automotive Tier 1s are displacing fragmented equipment purchasing across individual manufacturing sites. Shared validation infrastructure investments in Baden-Württemberg and Bavaria pool thermal chamber and shock test capacity across competing sensor suppliers. This channel concentration favors platform vendors with multi-site service architectures over specialized single-physics equipment providers.
MEMS and Sensor Performance and Reliability Test Equipment Market Segmentation
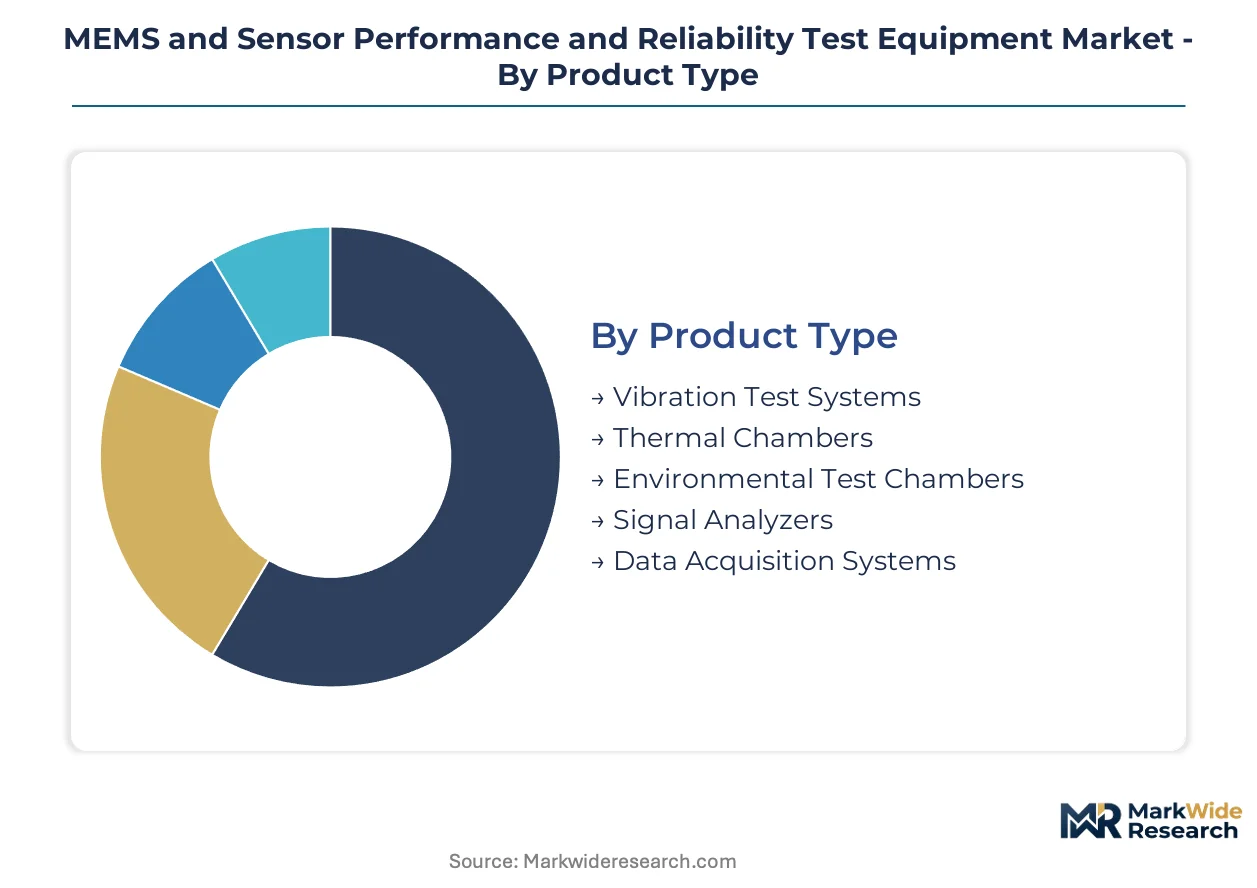
Test equipment configurations diverge sharply between high-mix automotive validation labs and high-volume consumer electronics production floors. Segmentation reveals how thermal-vibration coupling requirements and certification scope determine procurement specifications across customer tiers.
Product Type:
Standardization dominates at the chamber level while vibration systems fragment into application-specific configurations.
- Vibration Test Systems:Electrodynamic and hydraulic shaker platforms deliver sine, random, and shock excitation profiles up to 2000 G-force for accelerometer qualification. Procurement concentrates among Stuttgart automotive suppliers validating multi-axis inertial sensors for ADAS integration.
- Thermal Chambers:Single-zone and multi-zone environmental chambers cycle between minus 40 degrees Celsius and 150 degrees Celsius with programmable ramp rates. Demand clusters in Munich for lidar and radar sensor thermal calibration under EU F-Gas Regulation compliance timelines.
- Environmental Test Chambers:Combined temperature-humidity-altitude systems simulate harsh operational envelopes for aerospace and defense sensor validation.
- Signal Analyzers:Frequency-domain and time-domain instruments capture noise floor, drift, and harmonic distortion in MEMS resonator outputs.
- Data Acquisition Systems:Multi-channel synchronous sampling platforms aggregate sensor telemetry during accelerated life testing protocols.
Leading the category by volume: Vibration Test Systems. Growing fastest: Thermal Chambers.
Technology:
Cost tiers separate established electromechanical methods from emerging photonic and electromagnetic validation protocols.
- Acoustic Emission:Piezoelectric transducers detect micro-crack propagation and delamination in MEMS die during mechanical stress testing. Automotive suppliers in Germany deploy these systems for predictive failure-mode documentation under NHTSA functional safety mandates.
- Accelerometer Testing:Centrifuge and tilt-table platforms verify bias stability, scale factor, and cross-axis sensitivity across temperature excursions. Volume demand tracks consumer electronics OEM procurement for smartphone and wearable inertial measurement units.
- Thermal Shock:Dual-chamber liquid-to-liquid and air-to-air systems induce rapid temperature transitions to identify solder joint fatigue and package stress failures.
- Electromagnetic Compatibility:Anechoic chambers and conducted immunity test setups validate sensor immunity to radiated emissions in automotive powertrain environments.
- Optical Inspection:Interferometric and machine-vision systems measure wafer-level dimensional tolerances and detect particulate contamination on MEMS structures.
Dominant by installed base: Accelerometer Testing. Steepest expansion trajectory: Optical Inspection.
Application:
Customer maturity separates compliance-driven documentation from yield-optimization testing.
- Quality Inspection:Automated optical and electrical parametric screening at wafer and final test stages filters defective units before module integration. Semiconductor manufacturers in Taiwan and Israel sustain highest throughput requirements for consumer MEMS die.
- Durability Testing:Accelerated life test protocols combining thermal cycling, vibration, and humidity exposure establish mean-time-between-failure distributions. Aerospace firms mandate these programs for flight-critical sensor qualification under FAA certification pathways.
- Calibration:Traceable reference standards and adjustment procedures align sensor output to specified accuracy bands across operational temperature ranges.
- Failure Analysis:Destructive and non-destructive diagnostic techniques isolate root causes of field returns and qualification rejects.
- Sensitivity Assessment:Resolution and noise-floor characterization quantifies minimum detectable signals for high-precision navigation and seismic monitoring applications.
Highest volume segment: Quality Inspection. Gaining share fastest: Durability Testing.
End User:
Procurement concentration shifts from semiconductor foundries toward automotive and aerospace captive validation facilities.
- Semiconductor Manufacturers:IDM and foundry test floors deploy high-throughput parallel test cells for wafer-level MEMS screening. Capital intensity constraints favor multi-site architectures from Teradyne and Advantest for cost-sensitive die production.
- Automotive Suppliers:Tier 1 sensor module producers in Baden-Württemberg and Bavaria are building in-house thermal-vibration-electromagnetic tri-physics capabilities to compress ADAS validation cycles.
- Electronics OEMs:Smartphone and wearable device assemblers rely on incoming inspection sampling rather than full validation infrastructure ownership.
- Research Laboratories:University and government facilities pioneer next-generation test methodologies for emerging MEMS architectures.
- Aerospace Firms:Prime contractors and subsystem suppliers maintain dedicated environmental test facilities for flight hardware qualification.
Largest procurement base: Semiconductor Manufacturers. Fastest capability buildout: Automotive Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification and autonomous driving architectures concentrate MEMS test equipment demand in manufacturing corridors where Tier 1 suppliers validate ADAS sensors. Procurement patterns cluster around regulatory compliance deadlines and captive validation facility buildouts.
Germany
Baden-Württemberg and Bavaria host Europe's densest automotive sensor validation infrastructure. The EU F-Gas Regulation accelerates thermal chamber replacement cycles among Stuttgart-based Tier 1s. Munich lidar suppliers are expanding tri-physics test cell capacity under dual carbon transition timelines.
United States
NHTSA functional safety mandates drive deterministic failure-mode documentation requirements across Michigan and California automotive corridors. The FDA medical device quality system regulation shapes traceable calibration protocols for Minnesota-based implantable sensor manufacturers. Arizona and Texas test houses are adding RF anechoic capacity for radar module certification.
China
Dual carbon goals tighten environmental test chamber specifications in Yangtze River Delta manufacturing zones. MIIT sensor quality standards accelerate domestic validation equipment procurement around Shanghai and Suzhou. Shenzhen consumer electronics OEMs sustain high-volume MEMS die screening demand for smartphone accelerometers.
Japan
METI industrial automation standards elevate reliability testing requirements for Chubu region precision sensor manufacturers. Toyota and Honda supplier networks in Aichi Prefecture are consolidating vibration test capacity through shared procurement consortia. Yokohama test houses specialize in automotive gyroscope thermal calibration protocols.
India
BIS certification expansion for automotive sensors creates greenfield test house demand in Pune and Chennai manufacturing corridors. The PLI scheme for electronics manufacturing attracts MEMS module assembly investment requiring incoming inspection infrastructure. Telangana and Karnataka semiconductor packaging facilities are adding wafer-level reliability screening capacity.
MEMS and Sensor Performance and Reliability Test Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue photonics-MEMS convergence and subscription-based equipment access models. The market structure consolidates around platform vendors with multi-site service architectures while fragmenting among specialized single-physics equipment providers. Three archetypes dominate: semiconductor test cell specialists, automotive validation platform integrators, and photonics hybrid test system developers. M&A activity concentrates on probe card integration capabilities and thermal-vibration coupling technology acquisitions.
Within the semiconductor test cell tier, Advantest and Teradyne exemplify scale-driven platform vendors with multi-site parallel testing architectures. Cohu occupies a position among handlers and interface solution providers serving high-volume MEMS die production. These three anchors represent divergent strategic postures: probe card integration dominance, cost-sensitive multi-site R&D intensity, and handler-interface specialization for consumer electronics throughput requirements.
| Leading Market Players |
|---|
| Advantest |
| Teradyne |
| Cohu |
| Keysight Technologies |
| National Instruments |
| SPEA |
| Yokogawa Test & Measurement |
| FormFactor |
| Chroma ATE |
| Others |
Pricing and Supply Chain Analysis
Helium gas costs for thermal chamber leak detection and cryogenic cooling flow from concentrated Qatari and Russian supply sources through three distinct equipment pricing tiers, compressing margins for mid-tier sensor module producers while premium-tier vendors absorb volatility through long-term offtake contracts.
Pricing Analysis
Volume-driven semiconductor test cell procurement separates from margin-rich automotive validation platform sales, with pricing stratifying across premium tri-physics systems, standard single-physics chambers, and economy-grade vibration shakers. Price differentiation rests on NHTSA certification grade and ISO 17025 traceability documentation, with Stuttgart Tier 1 suppliers least sensitive and Taiwan consumer electronics OEMs most cost-constrained. Pricing pressure intensifies in standard-tier thermal chambers as EU F-Gas Regulation refrigerant transitions force redesign costs onto equipment manufacturers.
Supply Chain Analysis
Freight costs for electrodynamic shaker platforms and environmental chamber assemblies from Germany, Japan, and the United States strain working capital cycles for test house operators in India and Southeast Asia. Raw material dependencies span rare-earth magnets for vibration exciters, specialty steel alloys for chamber enclosures, and precision RF components for signal analyzers. Single-source vulnerability concentrates in high-frequency probe card substrates, with distribution running through direct OEM sales for large automotive suppliers and regional distributor networks for mid-tier electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MEMS test equipment market functions as a vertical-integration race where probe card integration capabilities and thermal-vibration coupling expertise determine who captures automotive Tier 1 procurement consolidation.
For Market Incumbents: Anticipate displacement from photonics-MEMS hybrid test platforms by acquiring interferometric measurement specialists and embedding optical validation modules into existing electromechanical chassis. Consolidate service architectures across Baden-Württemberg and Bavaria to match shared procurement consortia channel concentration, while defending against subscription-based equipment access models through captive financing arms.
For New Entrants and Emerging Players: Begin with India BIS certification expansion corridors in Pune and Chennai, where greenfield test house demand outpaces established vendor service coverage. Target photonics-MEMS convergence applications for lidar and optical inertial measurement units, leveraging capital-light subscription models to bypass upfront capital expenditure barriers among Israeli and Taiwanese startup sensor designers.
For Investors and Strategic Acquirers: Consolidated procurement consortia formation among Stuttgart automotive Tier 1s is the leading indicator that platform vendors with multi-site service architectures will outcompete specialized single-physics providers over the coming decade. Prioritize acquisition targets with thermal-vibration-electromagnetic tri-physics integration capabilities and probe card interface IP, monitoring helium supply contract renegotiations as an early warning signal for thermal chamber manufacturer margin stress.
| Strategic Initiative | Industry Significance |
|---|---|
| Probe Card Integration Acquisition | Advantest's dominance in high-frequency sensor test cells demonstrates that probe interface control secures automotive ADAS validation procurement. |
| Thermal-Vibration Coupling R&D Investment | Teradyne's multi-site parallel architectures for cost-sensitive MEMS die reveal compression of validation cycle times as the decisive competitive lever. |
| Photonics-MEMS Hybrid Platform Development | Interferometric validation protocols for optical inertial measurement units capture expanding margin pools from lidar sensor electrification. |
| Subscription-Based Equipment Access Launch | Capital-light models bypass upfront expenditure barriers for startup sensor designers in Israel and Taiwan test corridors. |
| Multi-Site Service Architecture Expansion | Shared procurement consortia in Baden-Württemberg and Bavaria favor vendors with distributed calibration and maintenance capabilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across test equipment engineering directors, automotive Tier 1 procurement managers, semiconductor foundry test floor supervisors, and thermal chamber calibration laboratory accreditation officers. Bottom-up equipment shipment aggregation from Germany, Japan, and the United States combined with top-down semiconductor capital expenditure tracking to triangulate market sizing across vibration test systems, thermal chambers, and signal analyzer categories.
Data-stream reconciliation across supplier shipment disclosures, end-user capital expenditure budgets, and regulatory compliance deadline schedules shaped the analytical framework over the projection horizon. Segmentation modeling incorporated product type, technology protocol, application purpose, and end-user industry vertical dimensions, with CAGRs derived from equipment replacement cycle analysis and automotive electrification content-per-vehicle trajectories.
Underlying measurement precision varies by segment; vibration test systems carry tighter precision than emerging photonics-MEMS hybrid categories where supplier disclosure remains fragmented. Forecasts reflect assumptions about NHTSA functional safety mandate implementation timelines and EU F-Gas Regulation refrigerant transition adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
ESG Sensor Data Quality and Validation Test Platforms Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Curve Tracer Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Calorimeters Market
Test and Measurement
Solar Measuring Device Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Quantum Key Distribution System Performance and Security Test Equipment Market
Test and Measurement
Medical-Grade Flexible Electronics Bending and Fatigue Test Systems Market