
 NPL Servicing Market | 2026-2036
NPL Servicing Market Size, Share, and Industry Trends Forecast 2026-2036
NPL Servicing Market Analysis
Technology-enabled servicing fee structures is recalibrating what buyers purchase in NPL portfolios. Cerberus Capital Management leverages captive analytics platforms to price distressed loan acquisitions. SitusAMC anchors its competitive position through scale advantages in commercial mortgage special servicing. Greystone differentiates via integrated construction and asset management capabilities for transitional real estate debt.
Non-performing loan servicing encompasses the operational administration, workout, and recovery management of defaulted or delinquent credit instruments across secured and unsecured obligations, typically involving loan modification, foreclosure, collateral liquidation, and borrower negotiation protocols governed by servicing-level agreements with defined net operating income targets. The service type dimension shows loan servicing and asset management commanding the principal margin pools given their duration-based fee structures and operational complexity barriers, while AI Solutions within the technology segment is displacing legacy manual underwriting in portfolio due diligence and borrower income verification workflows. Debt type segmentation reveals mortgages sustaining the deepest servicer specialization requirements due to regulatory loss mitigation mandates and collateral valuation dependencies.
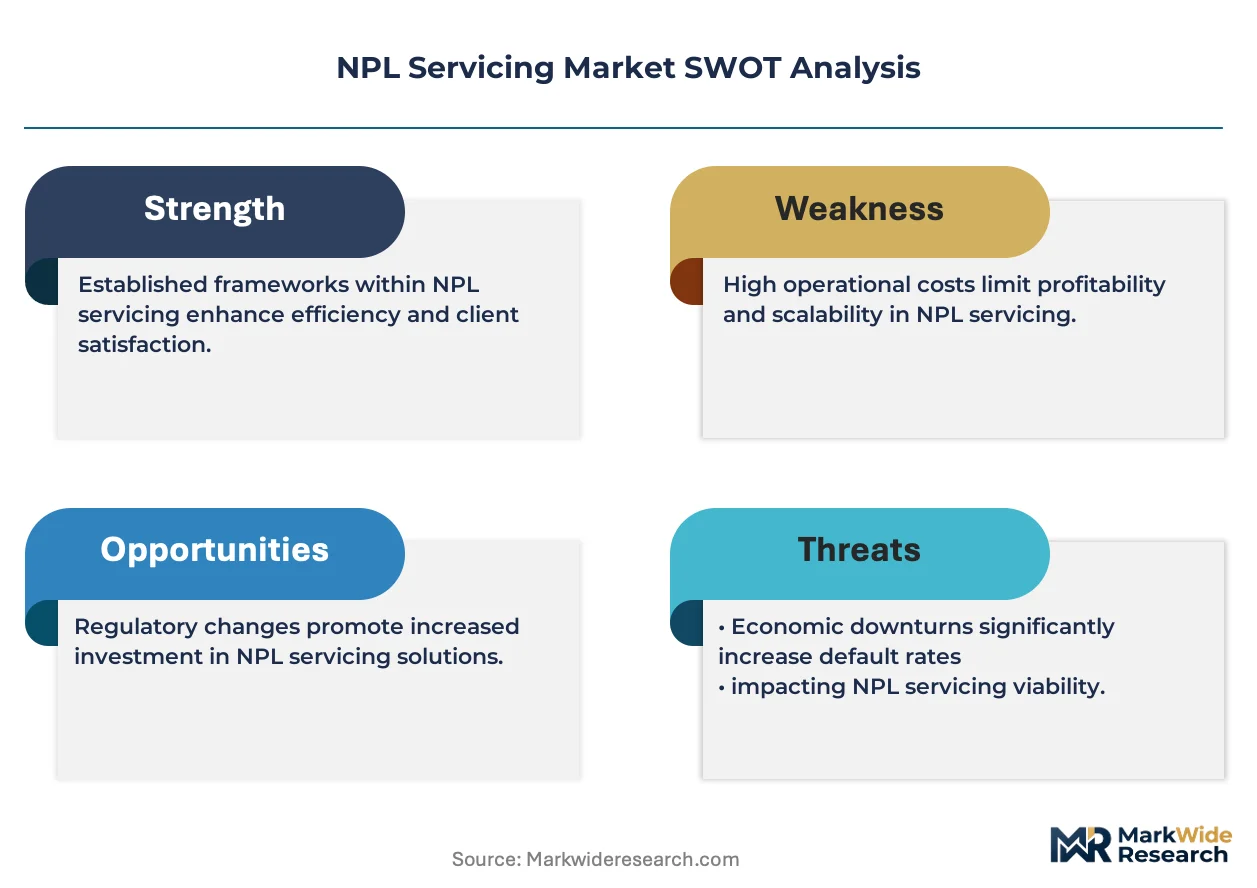
US servicers navigate overlapping oversight from the CFPB, state banking regulators, and FHA loss mitigation protocols that dictate modification timelines and borrower communication standards, while European operators face ECB guidance on NPL reduction targets and national insolvency codes that shape workout strategy permissibility. The EU Green Deal taxonomy is beginning to influence collateral valuation methodologies for energy-inefficient commercial properties in secured NPL pools. Stakeholders must monitor how Basel III endgame capital rules reshape bank retention incentives versus third-party servicing outsourcing decisions.
Market Dynamics
ECB provisioning requirements are compressing bank balance sheet capacity for NPL retention, accelerating third-party servicer intermediation across European distressed credit markets.
Growth Catalysts
- ECB NPL Reduction Targets:Eurozone banks face binding timelines to reduce non-performing exposure ratios, outsourcing workout execution to licensed specialists.
- Securitization Infrastructure:Italy's GACS guarantee scheme requires certified servicer participation for portfolio transactions, creating mandated demand channels.
- AI-Powered Due Diligence:Machine learning platforms compress borrower income verification timelines from weeks to hours, enabling faster portfolio pricing.
Market Restraints
- Servicer Licensing Concentration:Italy and Spain restrict NPL servicing licenses to entities meeting minimum capital thresholds, limiting new entrant supply.
- Collateral Valuation Volatility:Commercial real estate price uncertainty in peripheral Eurozone markets impairs recovery rate forecasting accuracy.
- Insolvency Code Fragmentation:National bankruptcy procedures vary across EU member states, complicating cross-border portfolio workout standardization.
Strategic Opportunities
- Green Collateral Revaluation:EU Green Deal taxonomy criteria are creating valuation discounts for energy-inefficient commercial properties in secured NPL pools.
- Secondary Market Data Monetization:Servicers with longitudinal performance datasets can package analytics as subscription products for institutional buyers.
- Portugal and Greece Penetration:These markets exhibit lower servicer density relative to Italy and Spain, offering first-mover positioning potential.
Industry Challenges
- Specialized Workout Talent Scarcity:Experienced restructuring professionals with dual legal and real estate expertise command premium compensation in Madrid and Milan.
- Legacy System Integration:Bank originators operate on disparate loan administration platforms, requiring costly middleware development for servicer onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NPL Servicing Market |
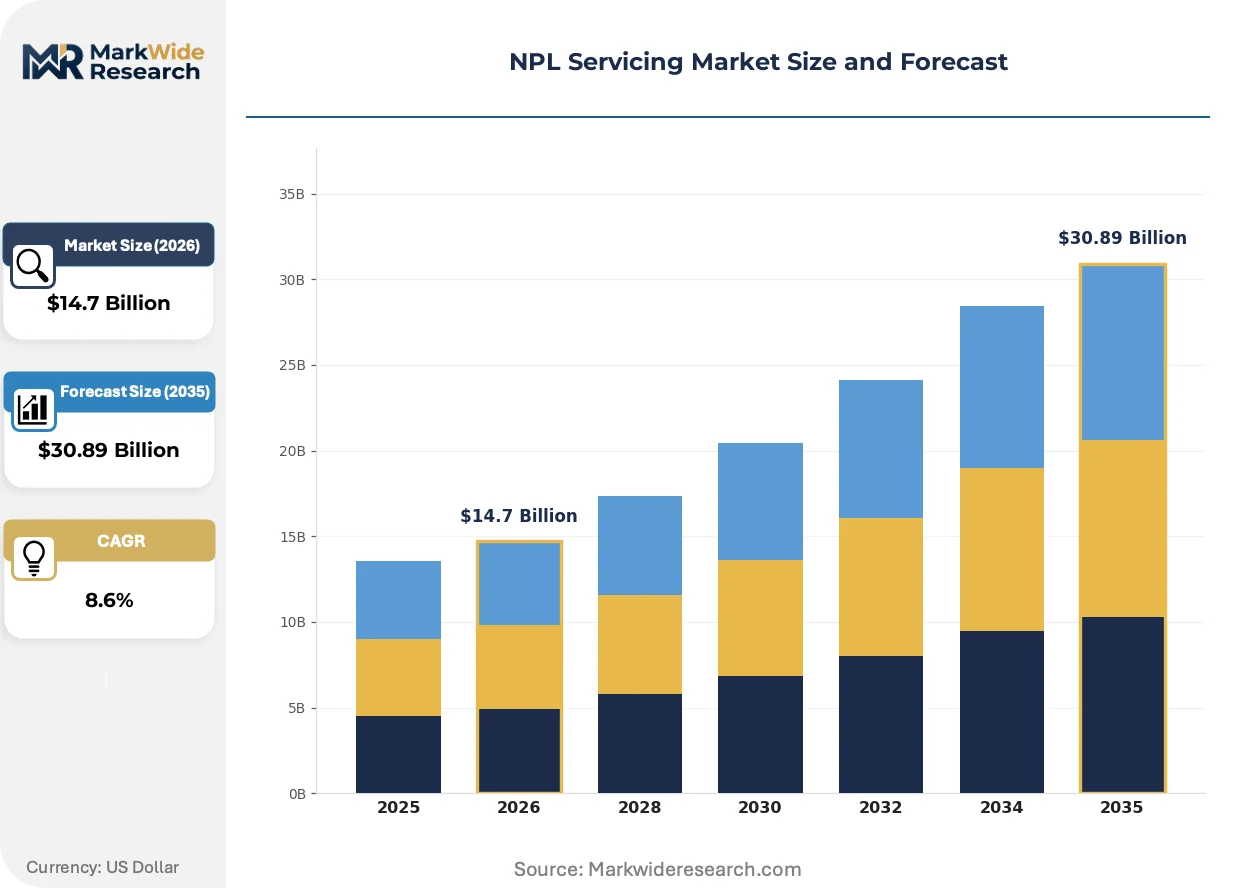
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Asset Management, Debt Collection, Credit Repair, Loan Servicing Client Type: Financial Institutions, Hedge Funds, Private Equity, Individual Investors Debt Type: Secured Loans, Unsecured Loans, Mortgages, Credit Lines Technology: AI Solutions, Cloud Platforms, Analytics Tools, CRM Software |
| Companies Covered | KeyBank National Association, Berkadia Commercial Mortgage, Cerberus Capital Management, SitusAMC, CWCapital Asset Management, Trimont, CBRE Loan Services, Greystone, PNC Real Estate/Midland Loan Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NPL Servicing Market Emerging Trajectories
Technology is restructuring how servicers extract value from distressed loan portfolios, compressing due diligence cycles while expanding recoverable asset categories.
Automated collateral valuation models is overtaking traditional appraisal-dependent workflows in commercial mortgage special servicing. Large institutional buyers now require AI-augmented valuation as a condition of portfolio acquisition. This compression of assessment timelines is enabling same-week bidding on billion-euro NPL pools.
EU Green Deal taxonomy disclosure requirements are reshaping energy performance certification obligations for commercial real estate collateral. Servicers must now integrate EPC rating data into liquidation strategies and borrower modification terms. German and French regulators are enforcing these standards most stringently, with property-level compliance now affecting recovery rate assumptions.
Outcome-based fee structures are replacing flat servicing retainers among top-tier European operators. Institutional sellers increasingly compensate servicers through graduated recovery-sharing arrangements tied to net present value targets. This shift is most pronounced in Italian residential mortgage securitizations, where GACS-eligible transactions mandate performance-linked compensation.
NPL Servicing Market Segmentation
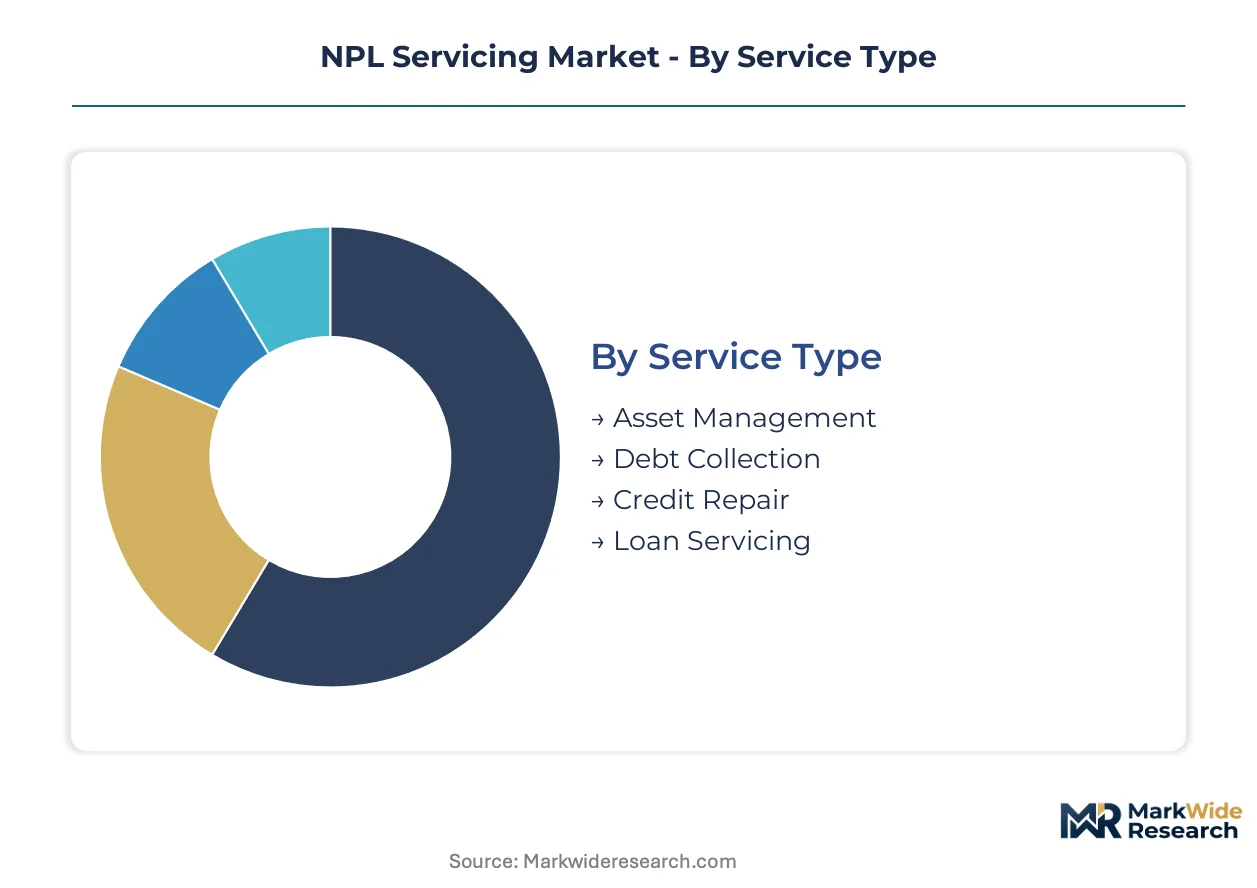
NPL servicing strategies diverge sharply across service types and client profiles, with specialized operators calibrating fee structures and technology stacks to match collateral complexity and regulatory jurisdiction. Segmentation reveals where margin pools concentrate and which technology investments yield measurable workout velocity improvements.
Service Type:
Upgrade cycles in servicing technology are forcing incumbents to replace legacy manual workflows with automated platforms that compress due diligence timelines and expand recoverable asset categories.
- Loan Servicing:Encompasses operational administration of defaulted credit instruments including borrower communication, payment processing, and covenant monitoring under servicing-level agreements. Italian banks concentrate demand here as ECB provisioning requirements accelerate outsourcing of residential mortgage workouts to licensed specialists with proven net operating income track records.
- Asset Management:Covers collateral liquidation, property maintenance, and value preservation for secured obligations through foreclosure-to-sale execution. Spanish commercial banks drive volume in this segment amid tighter timelines for real estate owned disposition mandated by national insolvency code amendments.
- Debt Collection:Focuses on unsecured obligation recovery through structured borrower negotiation and legal enforcement protocols. Demand clusters among hedge fund acquirers of consumer NPL portfolios seeking compliant multi-jurisdiction collection capabilities.
- Credit Repair:Involves borrower rehabilitation programs and modification structuring to restore performing status. Private equity sponsors of distressed loan platforms utilize these services to maximize portfolio recovery rates before securitization exit.
Loan servicing sits at the top of the volume ranking, with asset management climbing the fastest as commercial real estate collateral complexity demands specialized workout expertise.
Client Type:
Cost tier differentiation separates institutional clients with captive analytics capabilities from smaller investors dependent on third-party servicer data feeds and standardized reporting.
- Financial Institutions:Commercial banks and originators outsourcing workout execution to reduce operational burden and comply with regulatory NPL reduction targets. Italian and Spanish banks dominate this client tier given concentrated distressed credit exposure in these jurisdictions.
- Hedge Funds:Distressed debt specialists acquiring NPL portfolios for active management and structured exit through securitization or collateral liquidation. These clients demand real-time performance dashboards and outcome-based fee alignment.
- Private Equity:Sponsors building scaled servicing platforms through consolidation of regional operators and technology-enabled capability expansion. Greece and Portugal attract increasing private equity attention given lower incumbent servicer density relative to mature Italian market.
- Individual Investors:Retail participants in fractional NPL investment schemes requiring simplified servicing interfaces and transparent recovery tracking. Regulatory frameworks for retail participation vary across EU member states, constraining cross-border product standardization.
Financial institutions anchor the client base by volume, with hedge funds expanding most quickly as institutional capital flows into European distressed credit strategies.
Debt Type:
Application-specific workout protocols shape servicer specialization, with mortgage obligations demanding distinct legal expertise and collateral valuation capabilities compared to unsecured consumer credit.
- Mortgages:Residential and commercial property-secured obligations requiring foreclosure navigation, collateral management, and regulatory loss mitigation compliance. Spanish and Italian markets concentrate demand given high residential NPL stocks and GACS guarantee scheme participation requirements.
- Secured Loans:Corporate and SME obligations backed by non-real estate collateral including equipment, inventory, and receivables. Recovery execution demands dual legal and sector-specific asset valuation expertise.
- Unsecured Loans:Consumer and corporate credit without collateral attachment, relying on borrower income verification and legal enforcement for recovery. AI-powered income verification platforms are compressing due diligence timelines for portfolio acquirers in this segment.
- Credit Lines:Revolving facilities and trade finance obligations with complex drawdown histories and multi-creditor interdependency. Workout complexity escalates when collateral pools secure multiple obligation types across syndicated structures.
Mortgages command the largest servicer allocation by portfolio value, with secured loans gaining share fastest as corporate distress rises in peripheral Eurozone economies.
Technology:
Customer type segmentation separates enterprise-grade platform deployments from modular solutions targeting mid-market servicers with constrained integration budgets.
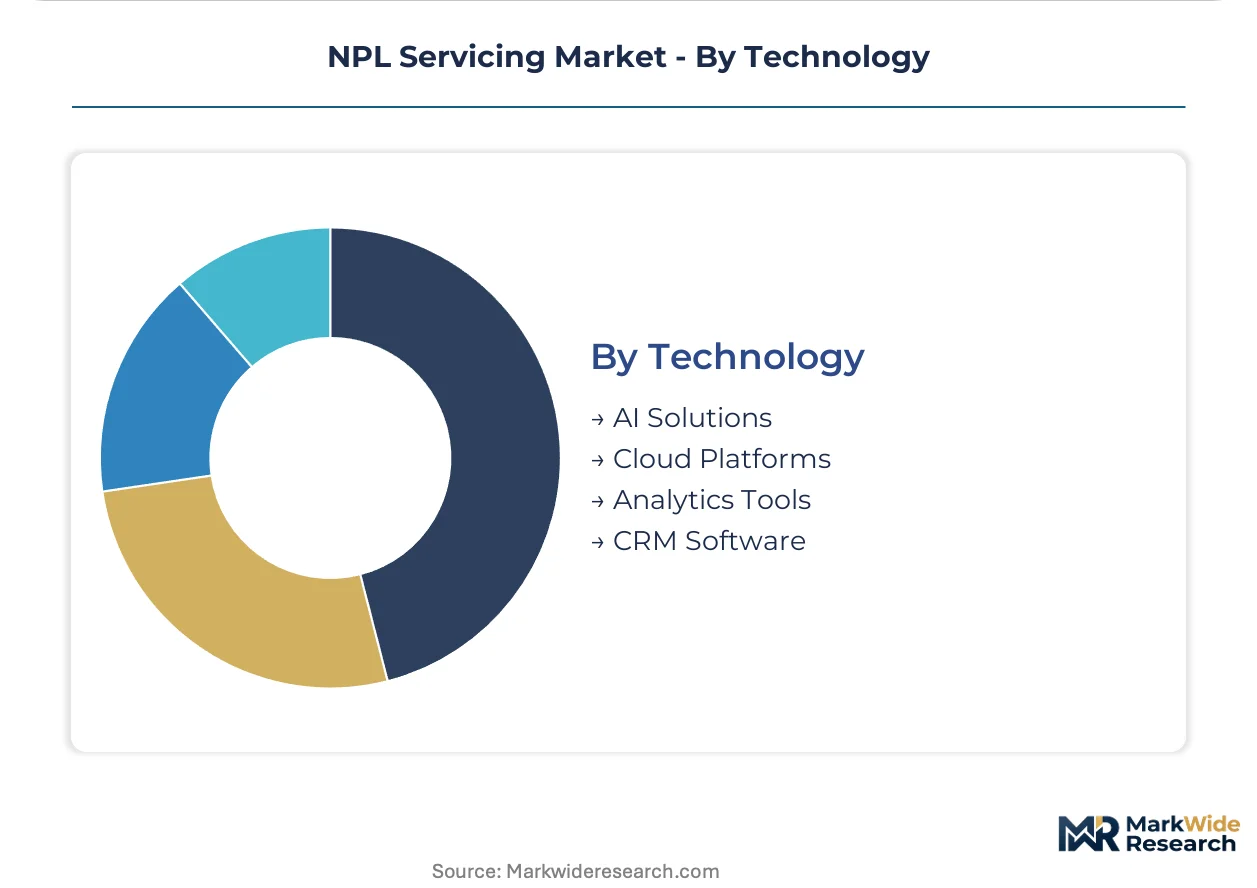
- AI Solutions:Machine learning platforms automating borrower income verification, collateral valuation, and portfolio pricing. Large institutional buyers now mandate AI-augmented due diligence as a condition of billion-euro NPL pool acquisition.
- Cloud Platforms:Scalable infrastructure enabling multi-jurisdiction data residency compliance and real-time portfolio performance monitoring. EU GDPR requirements shape vendor selection for cross-border servicing operations.
- Analytics Tools:Performance dashboards and predictive models for recovery rate forecasting and servicer benchmarking. Longitudinal dataset monetization is emerging as a secondary revenue stream for established operators.
- CRM Software:Borrower communication and case management systems with regulatory audit trail capabilities. CFPB loss mitigation protocols in the US and ECB guidance in Europe dictate specific functionality requirements.
AI solutions lead technology investment intensity, with cloud platforms showing the steepest adoption curve as servicers prioritize infrastructure scalability for portfolio volume spikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy concentrates the deepest servicer specialization in Europe, while Spain's commercial banks are accelerating outsourcing timelines under tighter provisioning mandates from the ECB.
Italy
Residential mortgage securitizations drive sustained demand for licensed servicer intermediation under the GACS guarantee scheme. The Bank of Italy enforces capital adequacy requirements for servicing entities that handle NPL portfolio transactions. Milan anchors the highest servicer density in Southern Europe, with specialized operators clustering around the city's financial district to manage billion-euro distressed loan pools.
Spain
Commercial bank balance sheets carry elevated real estate owned exposure, compressing retention capacity and expanding third-party workout contracts. The Banco de España implements ECB-aligned NPL reduction targets with binding timeline enforcement. Madrid concentrates servicer headquarters and restructuring talent, while Barcelona hosts emerging fintech platforms that automate borrower income verification workflows.
Germany
Corporate distressed debt volumes are rising as insolvency filings increase among mid-sized industrial borrowers. BaFin supervises servicer licensing under national implementation of EU NPL framework directives. The Frankfurt Rhine-Main metropolitan region houses the principal special servicing operations for commercial mortgage-backed securities, with Düsseldorf emerging as a secondary cluster for SME workout specialists.
United States
Commercial mortgage special servicing demands are escalating as office property distress concentrates in gateway markets. The CFPB enforces loss mitigation protocols that dictate modification timelines and borrower communication standards for residential servicers. New York City and Dallas anchor the largest special servicing operations, with Chicago and Los Angeles hosting significant regional platforms for CMBS workout execution.
Portugal
Lower incumbent servicer density relative to Italy and Spain is attracting private equity platform buildouts and first-mover positioning. The Banco de Portugal applies ECB NPL guidance with national insolvency code overlays that shape workout strategy permissibility. Lisbon concentrates emerging servicing operations targeting SME and consumer distressed credit, while Porto develops as a secondary hub for technology-enabled collection platforms.
NPL Servicing Market Vendor Landscape
Top-tier vendors anchor the institutional servicing tier, while mid-market specialists compete on geographic niche coverage and technology-enabled cost structures. The market exhibits tiered consolidation around scale-advantaged platforms with captive analytics capabilities and regional boutiques with localized legal expertise. Three archetypes dominate: integrated real estate servicers with construction management capabilities, technology-anchored platforms with AI-augmented valuation tools, and bank-affiliated servicers with legacy portfolio relationships. Competitive dynamics center on M&A-driven platform consolidation and outcome-based fee structure adoption.
Within the technology-anchored tier, Cerberus Capital Management and SitusAMC occupy positions that exemplify scale-driven competitive positioning, while Greystone represents the integrated real estate servicer archetype with construction and asset management capabilities. These entities illustrate how captive analytics platforms and specialized collateral expertise create differentiation in portfolio pricing and workout execution velocity.
| Leading Market Players |
|---|
| KeyBank National Association |
| Berkadia Commercial Mortgage |
| Cerberus Capital Management |
| SitusAMC |
| CWCapital Asset Management |
| Trimont |
| CBRE Loan Services |
| Greystone |
| PNC Real Estate/Midland Loan Services |
| Others |
Supply Flow & Price Mechanics
ECB-mandated NPL reduction timelines are compressing bank balance sheet capacity and forcing accelerated procurement of third-party servicing capabilities, which in turn is reshaping how specialized servicers structure fee arrangements and where they locate operational infrastructure to capture pricing power.
Pricing Analysis
Capacity additions in Italy and Spain are reshaping price floors for licensed NPL servicing as new entrants compete for GACS-eligible portfolio mandates. Three-tier pricing structure across premium, standard, and economy levels separates outcome-based recovery-sharing arrangements from flat retainers and technology-augmented discount tiers. Price differentiation rests on servicer licensing status and proprietary analytics capabilities. Cost compression in the standard tier is intensifying because bank originators demand faster due diligence cycles. Hedge fund acquirers show the least price sensitivity given their focus on recovery velocity over servicing cost.
Supply Chain Analysis
EU licensing requirements for NPL servicers create a qualification gating mechanism that limits supplier eligibility and concentrates operational capabilities in specific jurisdictions. Geographic supply centers on Italy, Spain, and Portugal where national banking regulators enforce capital adequacy thresholds for servicing entities. Raw material inputs for technology-enabled servicing include cloud infrastructure, machine learning platforms, and borrower data verification systems. Single-source vulnerability runs through concentrated pools of restructuring professionals with dual legal and real estate expertise in Madrid and Milan. Distribution runs through direct contractual relationships with bank originators and institutional portfolio acquirers rather than intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where institutional buyers increasingly mandate AI-augmented due diligence and licensed servicer participation as non-negotiable specifications, compressing margins for undifferentiated operators while rewarding platforms with captive analytics and proven net operating income track records.
For Market Incumbents: Cement competitive position through backward integration into proprietary data platforms and targeted capacity expansion in Portugal and Greece where servicer density remains low. The threat of technology-enabled new entrants with automated valuation tools demands defensive investment in longitudinal performance datasets that can be monetized as subscription analytics products. Certification investment in EU Green Deal taxonomy compliance for commercial real estate collateral represents a critical lever for maintaining pricing power in secured loan servicing. For New Entrants and Emerging Players: GACS guarantee scheme participation requirements in Italy open a window for specialized servicers to capture mandated demand channels in residential mortgage securitizations. Portugal and Greece present the most penetrable geographies given lower incumbent density and accelerating private equity platform buildouts. A go-to-market angle anchored in AI-powered borrower income verification compresses due diligence timelines and addresses the specific procurement preferences of hedge fund portfolio acquirers seeking real-time performance visibility. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-market servicers possessing established licensing in underserved peripheral Eurozone markets and technology-enabled cost structures that can scale across portfolio volume spikes. Long-term viability hinges on regulatory compliance infrastructure that survives successive ECB provisioning requirement iterations. The acquisition target archetype combines regional legal expertise with modular AI platforms capable of cross-border deployment. The signal to watch as an inflection indicator is outcome-based fee structure adoption rates among Italian residential mortgage securitizations.| Strategic Initiative | Industry Significance |
|---|---|
| AI Platform Integration | Machine learning deployment compresses borrower verification timelines from weeks to hours for institutional acquirers. |
| Geographic Expansion | Portugal and Greece licensing positions capture first-mover advantage in lower servicer-density markets. |
| Outcome-Based Fee Structuring | Recovery-sharing arrangements align servicer compensation with net present value targets in GACS-eligible transactions. |
| Green Certification Investment | EU Green Deal taxonomy compliance creates valuation differentiation for energy-efficient commercial real estate collateral. |
| Longitudinal Data Monetization | Performance dataset packaging generates subscription revenue from institutional buyers seeking benchmarking analytics. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with special servicing executives, bank workout officers, hedge fund portfolio managers, regulatory affairs specialists, and technology platform engineers with secondary validation against ECB NPL guidance documents, Bank of Italy servicing regulations, Banco de España circulars, and national insolvency code amendments across Eurozone jurisdictions. Bottom-up servicer capacity modeling and top-down distressed credit stock projections were triangulated for consistency.
Segment-weighting approaches applied differential growth assumptions across service type, client profile, debt category, and technology deployment dimensions over the projection horizon. The analytical framework modeled loan servicing, asset management, debt collection, and credit repair segments alongside financial institution, hedge fund, private equity, and individual investor client tiers. CAGRs were derived from regression analysis of historical NPL reduction trajectories and projected provisioning requirement timelines. Forecast inputs included ECB NPL exposure ratio targets and GACS guarantee scheme participation volumes.
Revisions become necessary when ECB provisioning requirements materially accelerate or decelerate, when national insolvency code amendments alter workout strategy permissibility, or when commercial real estate collateral valuations experience sustained dislocation. A model refresh is warranted upon material change in AI adoption rates among institutional portfolio acquirers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Vehicle Leasing Market
Loans and Leasing
Student Loan Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
United States Digital Lending Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Construction Equipment Finance Market