
 EV Thermal System Market | 2026-2036
EV Thermal System Market Size, Share, and Industry Trends Forecast 2026-2036
EV Thermal System Market Foresight
Automotive thermal engineering talent is rotating from internal combustion cooling expertise toward battery-specific thermal architecture, unlocking design velocity for next-generation EV platforms. Denso Corporation leverages its Toyota-affiliated manufacturing scale to dominate integrated heat pump assemblies for cold-climate performance. Robert Bosch GmbH sustains R&D intensity across refrigerant-based battery cooling circuits and cabin thermal management convergence. Valeo SA anchors European supply relationships through its specialized competence in electric compressor and heat exchanger integration.
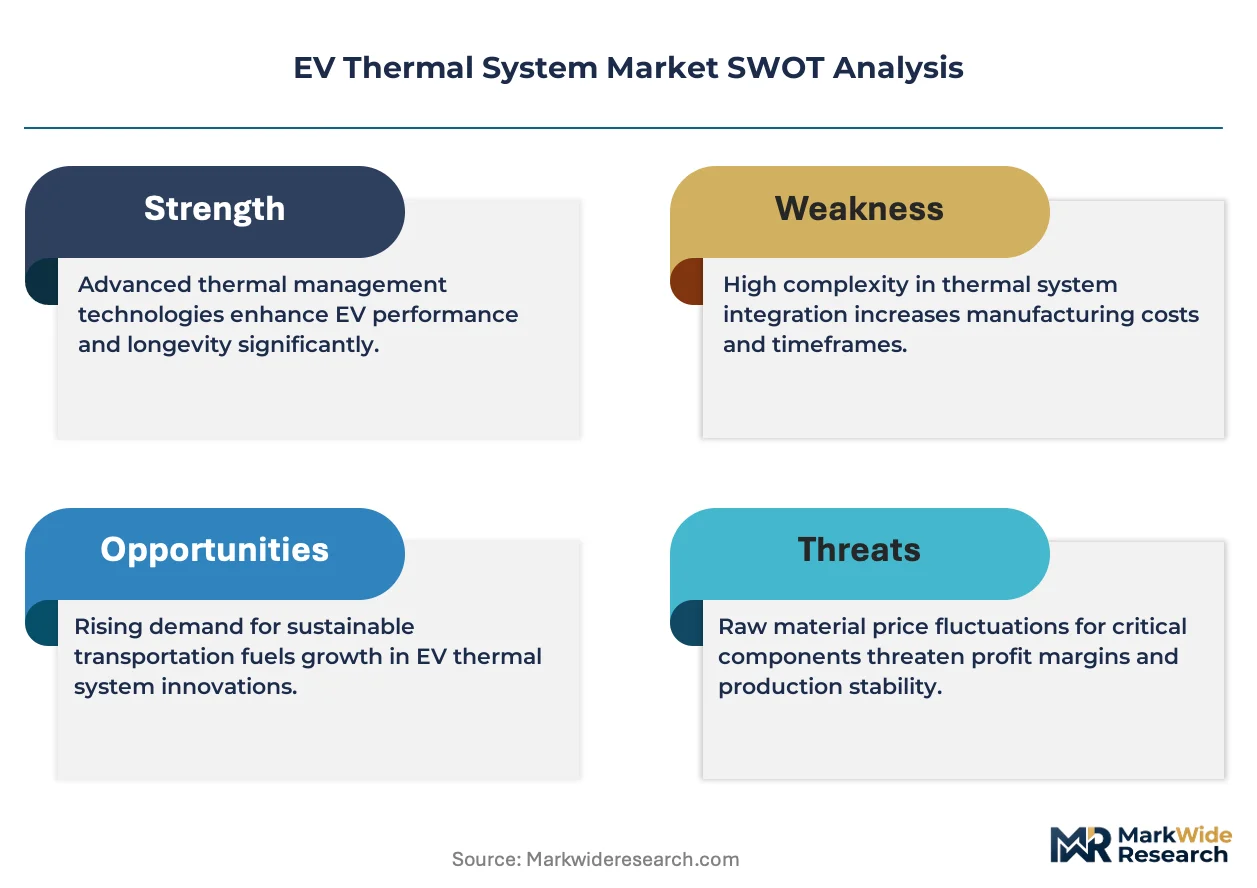
An EV thermal system encompasses the engineered subassemblies that regulate battery pack, power electronics, and cabin temperature through liquid coolant loops, refrigerant cycles, and phase-change interfaces operating between minus forty and one hundred twenty degrees Celsius. Liquid cooling captures the largest margin pool as OEMs specify glycol-water mixtures at flow rates exceeding fifteen liters per minute for fast-charge thermal stability. Heat exchanger technology leads volume shipments while thermoelectric modules represent the fastest-growing category as solid-state heating and cooling eliminates refrigerant dependency in compact architectures.
EPA vehicle emissions standards, the EU F-Gas Regulation, and China's MIIT new energy vehicle technical guidelines collectively mandate thermal efficiency thresholds that determine platform certification and market access eligibility. NHTSA battery safety protocols in the United States and ECHA REACH chemical restrictions in Europe further constrain material selection and coolant formulation pathways. Stakeholders must monitor regulatory divergence between refrigerant-phase-down timelines and solid-state thermal technology readiness to align capital allocation with compliance windows.
Market Dynamics
Liquid cooling architectures are displacing air-cooled designs as OEMs chase faster charging protocols and extended range targets, compressing thermal management into denser battery pack geometries.
Growth Catalysts
- China MIIT new energy vehicle technical guidelines:The MIIT mandates thermal efficiency thresholds that accelerate platform certification cycles for domestic OEMs.
- Fast-charge infrastructure buildout:Ultra-fast charging stations exceeding 350 kW require glycol-water cooling loops at flow rates above fifteen liters per minute.
- Battery electric passenger vehicles:This end-use category commands the fastest design velocity as range anxiety drives consumer preference.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger manufacturers face margin compression from base metal input cost swings.
- Refrigerant supply concentration:Fluorinated gas production clusters in China and Germany, creating geopolitical exposure for Western OEMs.
- ECHA REACH chemical restrictions:Coolant formulation pathways face constrained material selection, limiting thermal fluid innovation.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives attract thermal component localization for domestic EV platforms.
- Thermoelectric-solid state convergence:Solid-state heating and cooling eliminates refrigerant dependency in compact cabin architectures.
- Direct-to-OEM digital channels:Tier-2 suppliers bypass traditional distribution by quoting thermal subassemblies through proprietary configurators.
Industry Challenges
- Battery thermal simulation expertise:Automotive engineering teams lack computational fluid dynamics specialists for multi-physics pack modeling.
- ISO 26262 functional safety certification:Thermal management software requires ASIL-D validation, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Thermal System Market |
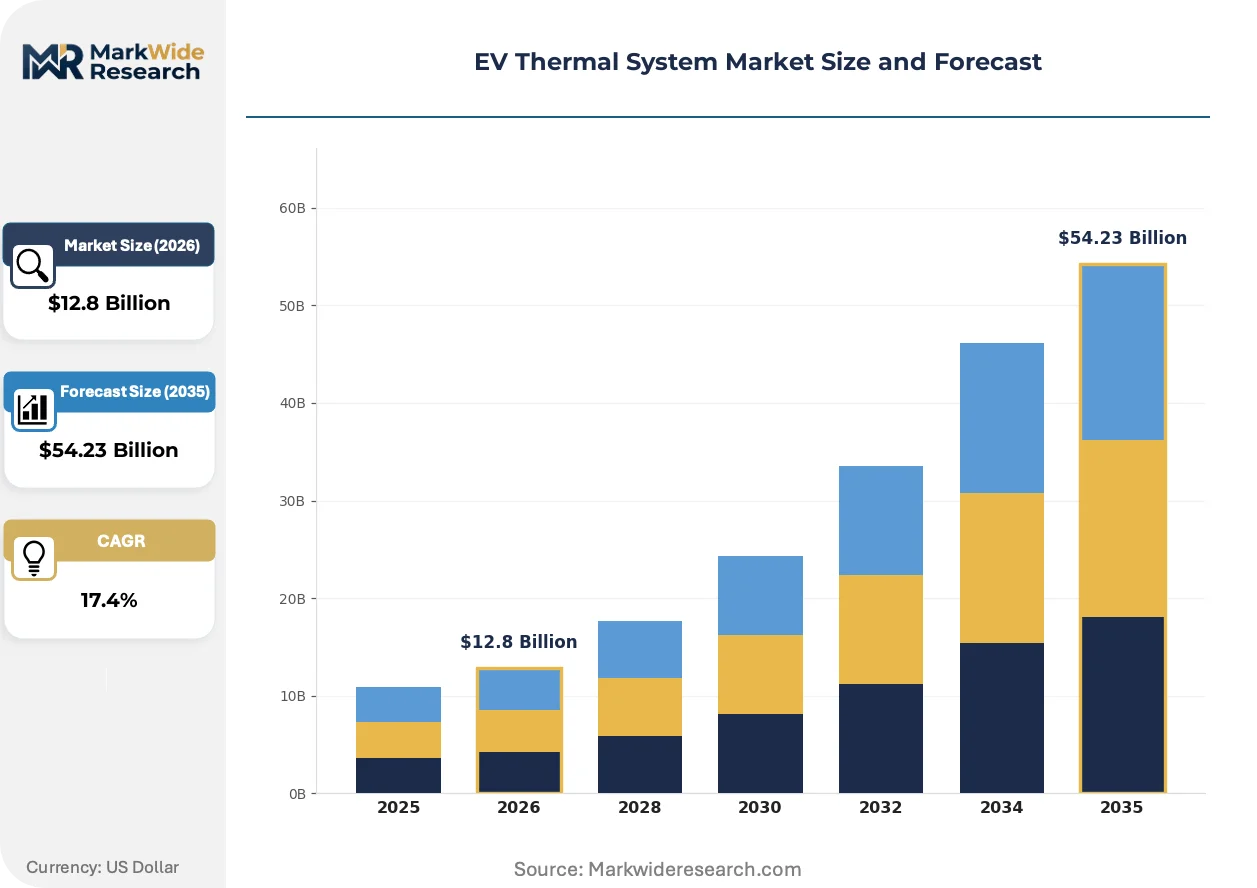
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $54.23 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cooling, Air Cooling, Phase Change Material, Battery Thermal Management Technology: Heat Exchangers, Electric Heaters, Refrigeration Systems, Thermoelectric Modules End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Installation: Integrated Systems, Standalone Units, Retrofitting, Custom Solutions |
| Companies Covered | Denso Corporation, Valeo SA, Robert Bosch GmbH, Continental AG, MAHLE GmbH, Hanon Systems, BorgWarner Inc., Gentherm Incorporated, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Thermal System Market Shifts & Advancements
Thermal engineering is converging around refrigerant reduction, solid-state actuation, and software-defined temperature control loops that unify battery and cabin management.
Thermoelectric modules are miniaturizing across premium EV platforms. These solid-state devices convert electrical current directly into heating or cooling without compressor cycles. Luxury OEMs in Germany and South Korea are integrating them into seat climate systems and battery conditioning loops. The technology is miniaturizing thermal hardware footprints by eliminating refrigerant lines and expansion valves.
The EU F-Gas Regulation mandates phasedown schedules for hydrofluorocarbon refrigerants used in automotive heat pumps. OEMs must certify alternative refrigerants with lower global warming potential by specified compliance windows. European suppliers are accelerating CO2-based transcritical cycles and propane blends to meet certification deadlines.
Fleet operators now specify thermal performance guarantees rather than component procurement. Logistics buyers in the United States demand battery temperature stability contracts covering five-year operating lifecycles. This shifts supplier relationships from unit sales to outcome-based service agreements with penalty clauses for thermal excursion events.
EV Thermal System Market Segmentation
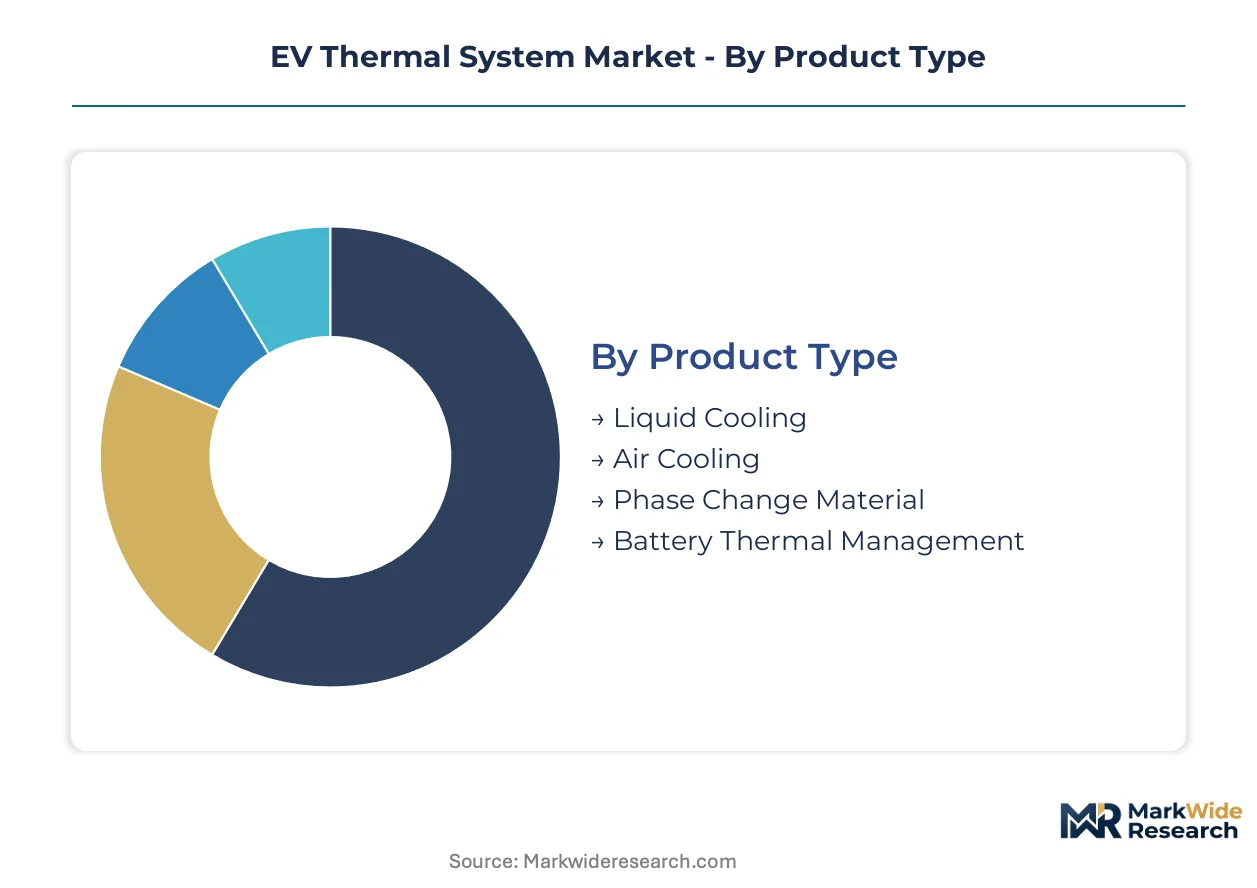
EV thermal system procurement patterns diverge sharply across cooling architectures, technology generations, and supply chain tiers. OEM platform strategies and charging infrastructure deployment timelines reshape segment prioritization continuously.
Product Type:
Margin pools concentrate in liquid-cooled architectures as fast-charge thermal loads intensify battery pack density requirements.
- Liquid Cooling:Glycol-water mixtures circulate at flow rates exceeding fifteen liters per minute through aluminum channel plates bonded to cell surfaces. Battery electric passenger vehicles in China and Germany specify these architectures for 800-volt platforms handling 350 kW charge rates.
- Air Cooling:Forced convection through finned heat sinks serves cost-optimized urban mobility platforms with modest range targets. Indian and Southeast Asian OEMs retain this approach for two-wheeler electrification and entry-level four-wheel segments.
- Phase Change Material:Paraffin and salt-hydrate composites absorb latent heat during thermal spikes without active circulation. German premium OEMs integrate PCM layers as passive backup protection against fast-charge excursion events.
- Battery Thermal Management:Integrated modules combining heating, cooling, and state-of-health monitoring functions. South Korean cell manufacturers specify these for cylindrical cell formats requiring precise temperature uniformity.
The dominant share belongs to liquid cooling, while phase change material is closing the gap fastest as passive safety redundancy gains regulatory attention.
Technology:
Volume shipment leadership sits with mature heat exchange hardware, though solid-state alternatives command technology investment premiums.
- Heat Exchangers:Aluminum brazed plate-and-fin assemblies transfer thermal energy between coolant loops and ambient air. Robert Bosch GmbH and Denso Corporation scale production for European and Japanese OEM platforms.
- Electric Heaters:Positive temperature coefficient ceramic elements provide cabin and battery pre-conditioning without engine waste heat. Cold-climate fleets in the United States and Scandinavia specify these for range preservation.
- Refrigeration Systems:Compressor-driven vapor compression cycles handle cabin cooling and battery heat rejection. Valeo SA and Mahle GmbH supply CO2 transcritical systems meeting EU F-Gas Regulation phasedown timelines.
- Thermoelectric Modules:Bismuth telluride junctions convert electrical current directly into heating or cooling without refrigerant. German luxury OEMs miniaturize these for seat climate and compact battery conditioning loops.
Heat exchangers retain volume leadership, yet thermoelectric modules are climbing the fastest as refrigerant-free architectures attract regulatory preference.
End User:
Procurement authority concentrates with OEMs specifying platform-integrated thermal architectures, while fleet operators increasingly demand outcome-based thermal performance contracts.
- OEMs:Volkswagen Group, BYD, and Tesla define thermal system specifications at vehicle architecture stage-gates. These buyers integrate battery, power electronics, and cabin thermal management into unified control domains.
- Tier-1 Suppliers:Denso, Hanon Systems, and Gentherm procure subassemblies for integration into vehicle-level modules. These intermediaries manage refrigerant handling certification and assembly line sequencing.
- Aftermarket Providers:Independent service channels address thermal system maintenance and collision repair. North American and European channels stock replacement heat exchangers and coolant pumps for legacy EV fleets.
- Fleet Operators:Logistics buyers in the United States and Germany now contract for battery temperature stability guarantees across five-year operating lifecycles. This shifts supplier relationships toward penalty-clad service agreements.
OEMs command specification authority, though fleet operators are gaining share fastest as commercial vehicle electrification accelerates thermal outcome contracting.
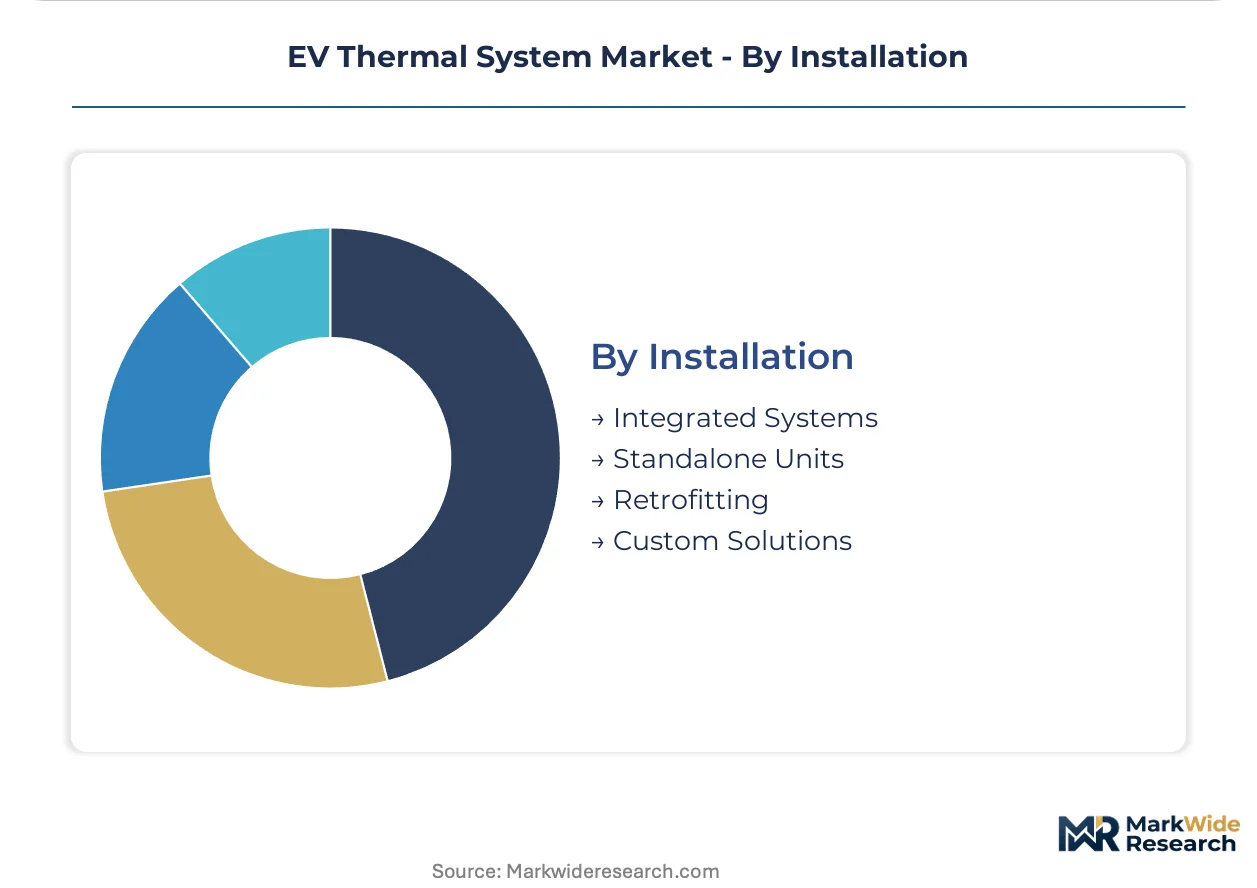
Installation:
Platform economics favor integrated systems designed at vehicle conception, though retrofitting gains relevance as early EV fleets age.
- Integrated Systems:Thermal hardware engineered into battery pack and vehicle body structures from initial CAD release. Chinese and German OEM platforms specify these for weight optimization and assembly automation.
- Standalone Units:Modular thermal packages serving low-volume specialty vehicles and conversion platforms. UK and US upfitters deploy these for commercial van electrification programs.
- Retrofitting:Thermal system upgrades extending operational life or enabling faster charging on first-generation EVs. Japanese and Korean aftermarket channels develop these for aging Leaf and Soul EV populations.
- Custom Solutions:Bespoke thermal engineering for motorsport, defense, and extreme-environment applications. UK motorsport clusters and US defense contractors commission these for performance and survivability specifications.
Integrated systems dominate new vehicle procurement, while retrofitting is expanding most quickly as early battery electric vehicle fleets approach thermal hardware replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys liquid cooling architectures for ultra-fast charging at scale, while Germany prioritizes refrigerant-phase-down compliance through CO2 transcritical systems, and the United States emphasizes fleet-grade thermal performance guarantees. These consumption-mix differentials reflect divergent regulatory timelines and infrastructure maturity across major EV markets.
China
Domestic OEMs specify glycol-water cooling loops exceeding fifteen liters per minute for 800-volt platforms handling 350 kW charge rates. MIIT technical guidelines mandate thermal efficiency thresholds that compress platform certification cycles. The Yangtze River Delta manufacturing corridor concentrates battery pack assembly and thermal component fabrication for BYD and CATL supply chains.
Germany
Premium OEMs integrate phase-change material layers as passive backup protection against fast-charge thermal excursions. The EU F-Gas Regulation drives accelerated CO2 transcritical cycle development to meet refrigerant phasedown deadlines. Bavaria's automotive engineering cluster anchors heat pump assembly and electric compressor integration for Volkswagen Group platforms.
United States
Logistics fleet operators contract for battery temperature stability guarantees spanning five-year operating lifecycles with penalty clauses for thermal excursion events. NHTSA battery safety protocols constrain material selection and coolant formulation pathways. The Midwest manufacturing belt, particularly Michigan and Ohio, hosts thermal system integration facilities serving Detroit Three electrification programs.
South Korea
Cell manufacturers specify integrated thermal management modules for cylindrical cell formats requiring precise temperature uniformity. MFDS chemical safety standards influence coolant additive approval pathways. The Busan-Ulsan industrial corridor concentrates heat exchanger production and electric vehicle component export logistics.
India
Two-wheeler electrification and entry-level four-wheel segments retain air-cooled architectures for cost-optimized urban mobility platforms. The PLI scheme for automotive attracts thermal component localization investments. Gujarat and Tamil Nadu manufacturing zones host emerging EV assembly and thermal subsystem supplier clusters.
EV Thermal System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Japanese and German conglomerates commanding heat pump and refrigerant circuit assembly at scale while mid-cap suppliers concentrate on electric heaters and thermoelectric modules. The market structure rewards manufacturing depth and refrigerant handling certification. Three archetypes dominate: diversified automotive conglomerates with captive thermal divisions, pure-play thermal specialists with regional manufacturing footprints, and battery-cell adjacent suppliers extending into pack-level thermal management. Competitive moves center on capacity expansion in China and India, plus strategic partnerships for CO2 transcritical system development.
Within the diversified conglomerate tier, Denso Corporation and Robert Bosch GmbH exemplify integrated players with manufacturing scale across multiple thermal subsystems. Valeo SA occupies a position among European specialists with concentrated competence in electric compressor and heat exchanger integration. These three anchors represent distinct geographic and capability configurations: a Toyota-affiliated Japanese manufacturer, a German industrial conglomerate with R&D intensity across refrigerant-based circuits, and a French supplier anchoring European OEM relationships through specialized component integration.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo SA |
| Robert Bosch GmbH |
| Continental AG |
| MAHLE GmbH |
| Hanon Systems |
| BorgWarner Inc. |
| Gentherm Incorporated |
| LG Chem |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German premium OEMs and aluminum heat exchanger suppliers lock in both glycol-water coolant loop access and five-year price visibility against copper volatility.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement between Tier-1 suppliers and Chinese battery pack assemblers, with pricing stratifying across premium, standard, and economy tiers based on ISO 26262 certification grade and flow rate performance. Cost compression in air-cooled architectures is intensifying because Indian OEMs prioritize entry-level urban mobility platforms. Fleet operators in the United States show least price sensitivity due to outcome-based thermal performance guarantees, while Southeast Asian two-wheeler manufacturers exhibit highest sensitivity to unit component costs.
Supply Chain Analysis
Fluorinated gas production concentration in China and Germany creates single-source vulnerability for Western OEMs seeking refrigerant-compliant heat pump assemblies. Manufacturing draws from aluminum brazing facilities in Japan, electric compressor plants in South Korea, and precision valve machining in Germany. Distribution runs through Tier-1 integrators who manage refrigerant handling certification and just-in-time sequencing to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV thermal system market represents high-growth disruption as solid-state thermoelectric modules displace compressor-driven architectures under EU F-Gas Regulation phasedown mandates.
For Market Incumbents: Fortify refrigerant circuit assembly capacity in China and India to capture MIIT and PLI scheme procurement windows. Denso Corporation and Robert Bosch GmbH should deepen backward integration into bismuth telluride sourcing for thermoelectric module cost control against emerging pure-play specialists. For New Entrants and Emerging Players: ISO 26262 ASIL-D certification fast-track enables white-space entry into battery thermal management software for South Korean cylindrical cell manufacturers. Target Indian air-cooled subsystem localization where PLI incentives reduce landed cost disadvantage against established Chinese suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward battery-cell adjacent thermal management specialists extending into pack-level integration, with long-term viability hinging on refrigerant-phase-down compliance readiness. Watch EU F-Gas Regulation enforcement intensity as the signal for accelerated CO2 transcritical cycle adoption tipping point.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical System Development | EU F-Gas Regulation compliance secures European OEM platform certification eligibility. |
| Thermoelectric Module Miniaturization | Solid-state architectures eliminate refrigerant dependency for German luxury seat climate systems. |
| India Manufacturing Localization | PLI scheme incentives attract thermal component fabrication for domestic EV platforms. |
| Fleet Performance Contracting | Outcome-based agreements with penalty clauses shift US logistics buyer relationships to service models. |
| 800-Volt Platform Thermal Integration | Chinese OEMs specify glycol-water loops exceeding fifteen liters per minute for fast-charge stability. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement leads, thermal subsystem R&D directors, and fleet operations managers provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation from MIIT technical guideline filings, EU F-Gas Regulation compliance databases, NHTSA battery safety protocol submissions, and vehicle production registration data. Bottom-up component demand modeling triangulated against top-down OEM platform thermal content estimates.
Consistency checks validated volume and value outputs against IHS Markit vehicle production forecasts and disclosed supplier capacity expansion announcements across the projection horizon. Segmentation modeling captured cooling architecture, technology generation, end-user procurement authority, and installation type dimensions. CAGRs derived from fitted growth curves incorporating fast-charge infrastructure deployment timelines and regulatory compliance window constraints.
Underlying assumptions cover MIIT certification acceleration, EU refrigerant phasedown adherence, and NHTSA safety protocol stability, with deviation risk concentrated in copper price volatility and thermoelectric material supply concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Platform Market
Electric Vehicles
Used EV Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
EV Coolants Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
Nordic E-Bike Market