
 Baby Changing Tables and Stations Market | 2026-2036
Baby Changing Tables and Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Changing Tables and Stations Market Insights
The premium and commodity tiers in baby changing tables and stations is rebalancing around safety certification depth and material sourcing transparency. Delta Children leverages its manufacturing scale to occupy the mid-market with certified nursery furniture lines. Pottery Barn Kids differentiates through design-forward, solid-wood constructions that command higher price points. IKEA anchors the accessible tier with flat-pack, particleboard-based units distributed through its global retail network.
Baby changing tables and stations are fixed or portable furniture units engineered with weight-rated surfaces, restraint straps, and guardrails to support infant diapering in domestic and commercial environments. Wall-mounted variants typically incorporate steel or aluminum frames with polyethylene surfaces rated for loads exceeding standard infant weights, while free-standing units integrate storage compartments and changing pad systems. Wood and plastic materials dominate procurement volumes, with plastic surfaces gaining preference in hospitals and daycares for sanitization compliance. The end-user split shows hospitals and daycares driving replacement cycles through stringent hygiene protocols, whereas retail stores represent a faster-growing installation category as family-friendly amenities become competitive differentiators.
The Consumer Product Safety Commission enforces stability and structural integrity standards for nursery furniture sold in the United States, while the Americans with Disabilities Act mandates accessible changing station heights and clear floor space in public facilities. ASTM International publishes voluntary standards for changing table performance that many retailers require for shelf placement. Stakeholders must monitor evolving state-level building codes that increasingly mandate family restroom provisions in new commercial construction.
Market Dynamics
The Baby Changing Tables and Stations Market is experiencing structural compression as building code mandates in the United States force rapid infrastructure retrofitting across airports, shopping malls, and municipal facilities. ADA accessibility guidelines now function as a de facto procurement standard, reshaping competitive positioning toward certified compliance rather than discretionary purchase.
Growth Catalysts
- ADA Accessibility Mandates:The Americans with Disabilities Act requires compliant changing station heights and clear floor space in all new public restroom construction, creating non-discretionary demand across commercial facilities.
- Airport Infrastructure Expansion:Major US aviation hubs including Hartsfield-Jackson Atlanta and Dallas-Fort Worth International are installing family restrooms with dual-height changing stations as passenger experience differentiators.
- Polyethylene Surface Technology:Non-porous plastic changing surfaces with antimicrobial integration are displacing wood in hospitals and daycares where sanitization protocols drive replacement cycles.
Market Restraints
- Steel Input Cost Volatility:Wall-mounted station frames rely on cold-rolled steel and aluminum extrusions, exposing manufacturers to commodity price swings from Chinese and South Korean mill suppliers.
- Contractor Installation Bottlenecks:ADA-compliant mounting heights and structural wall reinforcement requirements create skilled labor dependencies that extend project timelines in commercial retrofit applications.
- Particleboard Substitution Pressure:Free-standing nursery furniture faces displacement from solid-wood and metal alternatives as durability expectations rise among institutional buyers.
Strategic Opportunities
- Texas and Florida Suburban Retail:Rapid commercial construction in Houston, Dallas, Miami, and Orlando corridors outpaces national family restroom penetration rates, creating white-space installation demand.
- Smart Restroom Integration:IoT-enabled occupancy sensors and usage analytics are converging with changing station hardware, enabling facility managers to optimize cleaning schedules and inventory replenishment.
- California Title 24 Extensions:The state's building energy efficiency standards are expanding to cover universal restroom provisions in retail and hospitality, creating regulatory tailwinds for compliant station procurement.
Industry Challenges
- ASTM F2388 Certification Timelines:Third-party testing for changing table stability and structural integrity extends product launch windows by four to six months, compressing competitive response speed.
- Multi-State Code Fragmentation:Municipalities in Illinois, Massachusetts, and Washington maintain diverging family restroom mandates that complicate SKU standardization for national distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Changing Tables and Stations Market |
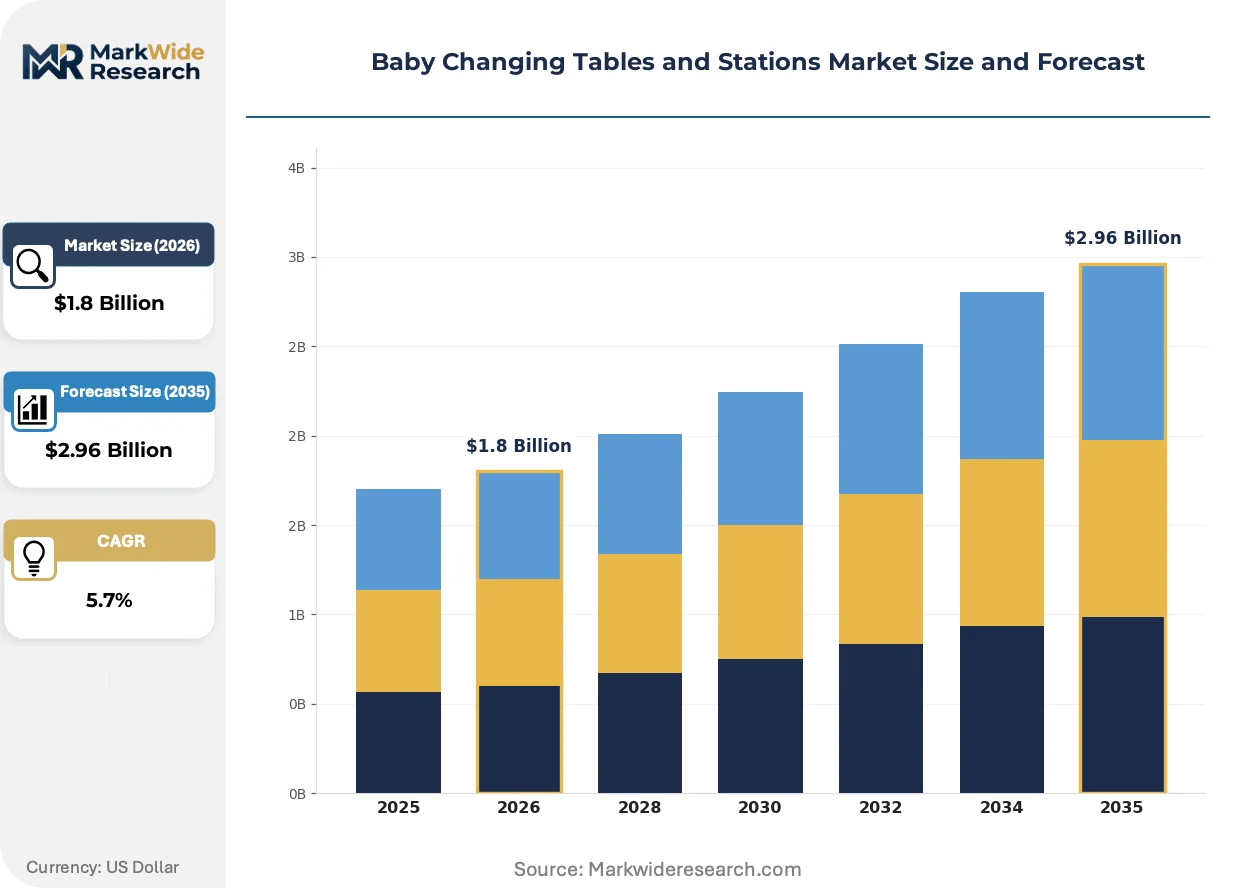
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Portable, Foldable, Free-Standing Material: Wood, Plastic, Metal, Fabric Design: Modern, Classic, Rustic, Minimalist End User: Hospitals, Daycares, Home, Retail Stores |
| Companies Covered | DaVinci, Ubbi, Delta Children, Pottery Barn Kids, Dream On Me, Graco, Storkcraft, IKEA, Babyletto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Changing Tables and Stations Market Trends and Innovations
Antimicrobial surface engineering and modular installation systems are restructuring procurement specifications across institutional and commercial buyer segments. Manufacturers are responding with hardware that reduces field labor while exceeding evolving hygiene standards.
Antimicrobial copper-infused polyethylene surfaces are overtaking standard high-density plastic in hospital and airport installations where pathogen transmission liability drives specification decisions. Johns Hopkins Medicine and Cleveland Clinic facilities have adopted copper-alloy changing surfaces in pediatric departments. The technology is compressing replacement cycles as facilities prioritize infection control over capital expenditure minimization.
The Consumer Product Safety Commission's nursery furniture stability standards are tightening enforcement timelines for tip-over prevention hardware. Retailers now require ASTM F2388 certification documentation before shelf placement, forcing smaller manufacturers to absorb third-party testing costs. Daycare chains and hospital procurement departments are responding by consolidating vendor lists toward pre-certified suppliers with documented testing histories.
Facility managers are consolidating restroom fixture procurement through integrated service contracts rather than discrete capital purchases. Aramark and Compass Group are bundling changing station maintenance, sanitization supply replenishment, and hardware replacement into multi-year agreements. This shift is most visible in US airport concession contracts where passenger volume guarantees align vendor incentives with uptime performance.
Baby Changing Tables and Stations Market Segmentation
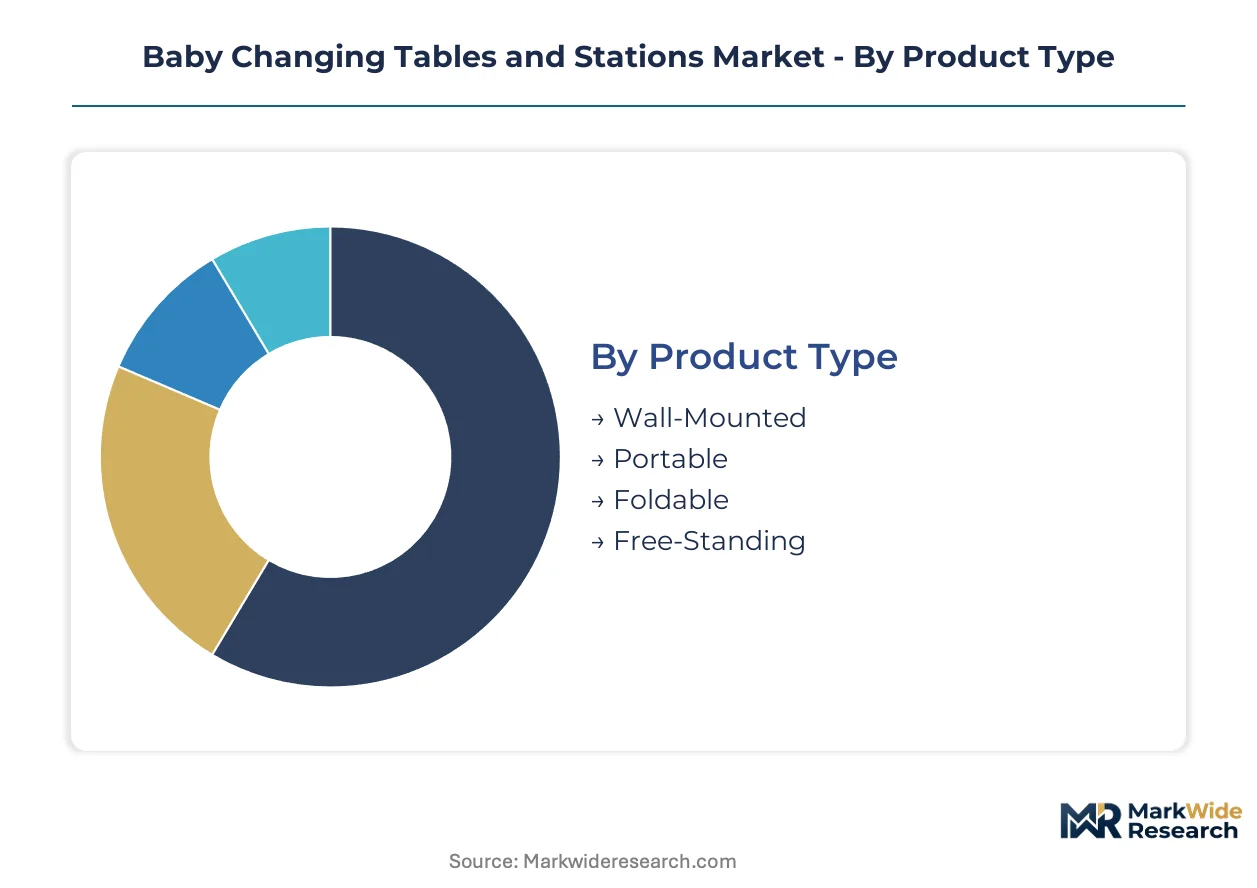
Baby changing tables and stations fragment across installation permanence, surface materials, aesthetic positioning, and institutional versus domestic procurement. Each dimension carries distinct specification requirements, compliance obligations, and replacement cycle patterns that reshape vendor priorities.
Product Type:
Wall-mounted units embed directly into restroom infrastructure, while portable and free-standing alternatives serve transient or residential applications with varying permanence expectations.
- Wall-Mounted:Steel or aluminum frames with polyethylene surfaces anchor permanently to structural walls. ADA-compliant mounting heights at 34 inches drive specification in US airports and municipal facilities where retrofit mandates concentrate procurement.
- Portable:Lightweight foldable frames with fabric or plastic surfaces deploy for travel and temporary care environments. Demand clusters in home-based daycare licensing requirements and parental mobility preferences.
- Foldable:Hinge mechanisms enable compact storage in space-constrained residential settings. IKEA and mass-market retailers dominate distribution through flat-pack logistics.
- Free-Standing:Integrated storage compartments and changing pad systems serve nursery furniture applications. Particleboard construction faces displacement pressure from solid-wood durability expectations.
Volume placements concentrate in Wall-Mounted; the faster expansion belongs to Portable.
Material:
Surface composition determines sanitization protocol compatibility, structural load ratings, and replacement frequency across institutional and domestic buyer segments.
- Wood:Solid-wood constructions command premium positioning in Pottery Barn Kids and design-forward nursery lines. Natural material sourcing transparency increasingly influences purchase decisions.
- Plastic:High-density polyethylene with antimicrobial integration dominates hospital and daycare procurement where non-porous surfaces support infection control protocols. Johns Hopkins Medicine and Cleveland Clinic pediatric departments specify copper-infused variants.
- Metal:Cold-rolled steel and aluminum extrusions form wall-mounted station frames. Chinese and South Korean mill supply exposes manufacturers to commodity price volatility.
- Fabric:Collapsible changing pads and portable unit surfaces prioritize packability over durability. Replacement cycles run shorter than rigid alternatives.
Plastic captures the highest institutional volume; antimicrobial surface engineering is climbing the fastest.
Design:
Aesthetic positioning stratifies procurement between specification-driven commercial installations and taste-driven residential purchases.
- Modern:Clean lines and neutral palettes align with contemporary restroom fixture standards in airports and hospitality chains. Delta Children occupies this tier with certified nursery lines.
- Classic:Traditional profiles with ornamental detailing persist in heritage hospitality and residential segments. Maturity limits growth velocity.
- Rustic:Distressed wood finishes and farmhouse styling target regional aesthetic preferences in suburban US markets. Texas and Florida retail construction shows concentrated demand.
- Minimalist:Stripped-down forms reduce visual clutter in compact urban dwellings. Younger demographic cohorts drive specification.
Modern design holds the largest commercial footprint; Minimalist is gaining share fastest in residential channels.
End User:
Buyer type dictates compliance depth, replacement urgency, and contract structure from capital purchase to integrated service agreements.
- Hospitals:Stringent sanitization protocols and liability exposure drive premium antimicrobial specifications. Copper-alloy surfaces and documented ASTM F2388 certification filter vendor eligibility.
- Daycares:Licensing requirements and high-frequency use accelerate replacement cycles. State-level family restroom mandates in Illinois and Massachusetts reshape facility investment priorities.
- Home:Discretionary purchase patterns respond to nursery furniture aesthetics and space constraints. Flat-pack distribution through IKEA anchors accessible pricing tiers.
- Retail Stores:Family-friendly amenities become competitive differentiators in shopping mall and big-box environments. Aramark and Compass Group bundle maintenance into multi-year service contracts.
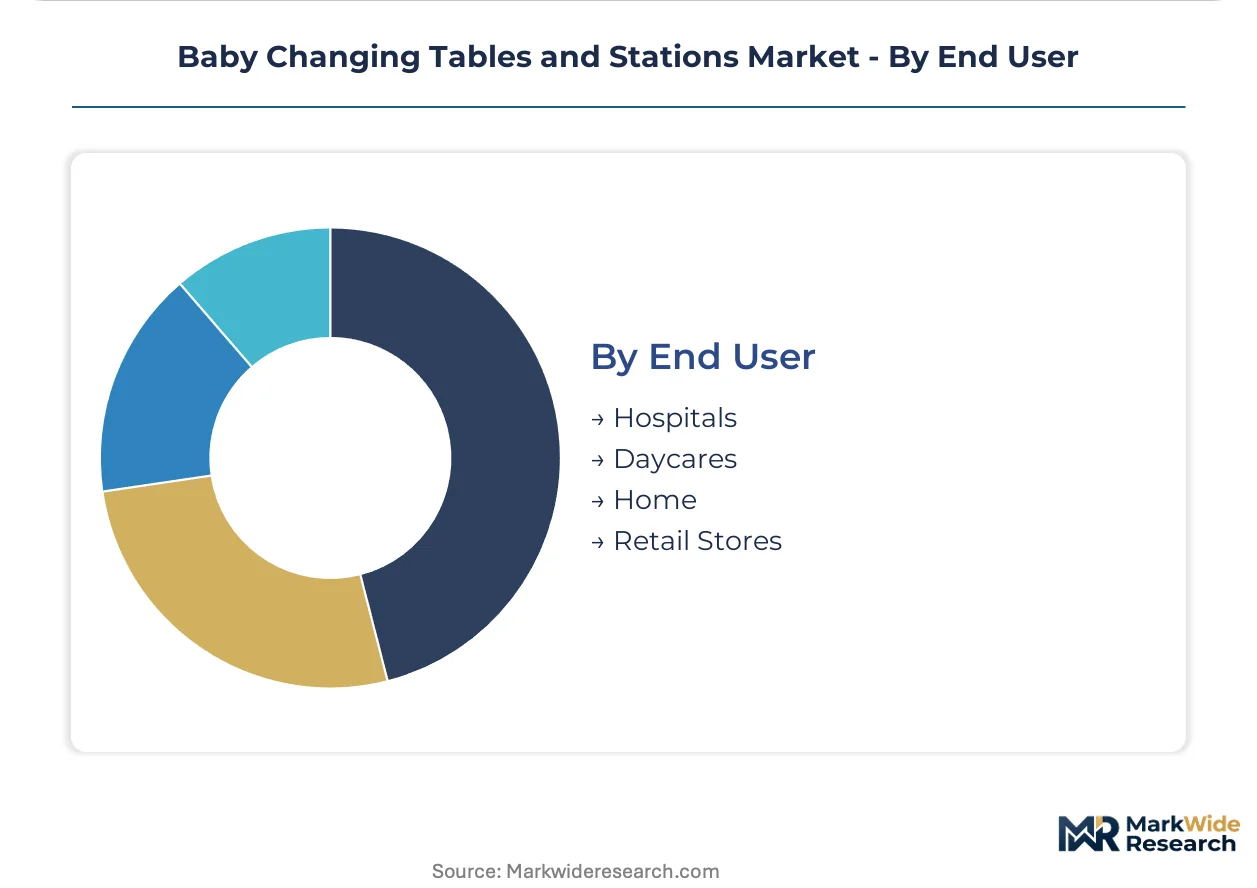
Hospitals anchor institutional volume; Retail Stores show the steepest expansion trajectory as passenger experience investment intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hartsfield-Jackson Atlanta International Airport anchors North American demand for ADA-compliant changing station installations, with Dallas-Fort Worth International and Chicago O'Hare following similar passenger experience investment trajectories. The United States concentrates retrofit mandates across municipal facilities, airports, and retail corridors. Four additional national markets demonstrate distinct procurement patterns shaped by local building codes and commercial construction cycles.
United States
Texas and Florida suburban retail corridors in Houston, Dallas, Miami, and Orlando outpace national family restroom penetration rates. The Americans with Disabilities Act mandates compliant changing station heights at 34 inches and clear floor space in all new public restroom construction. Johns Hopkins Medicine and Cleveland Clinic pediatric departments in Maryland and Ohio specify copper-alloy antimicrobial surfaces.
Canada
Airport Authority procurement in Toronto Pearson and Vancouver International drives institutional-grade wall-mounted station demand. Health Canada guidelines align with ASTM F2388 stability standards for nursery furniture imports. Retail construction in Calgary-Edmonton corridor and Greater Toronto Area shows concentrated family amenity investment.
Germany
Frankfurt Airport and Munich International expand family restroom infrastructure as passenger experience differentiators. CE marking requirements and EU accessibility directives shape procurement specifications for commercial installations. Industrial fabrication clusters in North Rhine-Westphalia produce cold-rolled steel frames for wall-mounted systems.
United Kingdom
Heathrow Airport and Gatwick family restroom retrofits concentrate demand in London aviation corridor. UK building regulations mandate baby changing provision in new commercial construction above certain floor areas. Retail development in Manchester and Birmingham follows similar amenity investment patterns.
Japan
Haneda and Narita International Airports lead Asia-Pacific passenger experience investment in family care infrastructure. METI guidelines and JIS standards influence product safety certification requirements for imported nursery furniture. Tokyo-Osaka commercial corridor shows concentrated retail amenity deployment.
Baby Changing Tables and Stations Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base stratifies between institutional-grade fabricators supplying steel-frame wall-mounted systems and residential furniture specialists delivering particleboard nursery units. Three archetypes dominate: certified compliance specialists serving hospital and airport procurement, mass-market flat-pack distributors leveraging global retail networks, and design-forward premium brands commanding solid-wood price premiums. Competitive moves concentrate on ASTM F2388 certification acquisition and geographic expansion into Texas-Florida commercial construction corridors.
Within the mass-market tier, IKEA anchors accessible pricing through flat-pack particleboard distribution. Delta Children occupies mid-market positioning with certified nursery furniture lines. Pottery Barn Kids exemplifies premium-tier differentiation through design-forward solid-wood constructions. These three companies represent distinct competitive vectors—scale efficiency, certification depth, and aesthetic positioning—rather than overlapping market contests.
| Leading Market Players |
|---|
| DaVinci |
| Ubbi |
| Delta Children |
| Pottery Barn Kids |
| Dream On Me |
| Graco |
| Storkcraft |
| IKEA |
| Babyletto |
| Others |
Pricing and Supply Chain Analysis
California Title 24 building energy efficiency extensions now mandate universal restroom provisions in retail and hospitality construction, gating qualified supply to manufacturers with documented antimicrobial surface certification and premium-tier pricing access for compliant hardware. This regulatory filter concentrates procurement toward pre-certified suppliers while compressing margins for uncertified competitors.
Pricing Analysis
Uptime-based service contracts anchor value-based pricing as facility managers bundle changing station maintenance, sanitization replenishment, and hardware replacement into multi-year agreements with Aramark and Compass Group. Three-tier pricing structure across premium, standard, and economy levels separates copper-alloy antimicrobial surfaces from standard polyethylene and particleboard alternatives. Cost compression in the economy tier intensifies because IKEA flat-pack distribution erodes margin headroom for particleboard nursery furniture. Daycare chains show highest price sensitivity, while hospital procurement departments prioritize infection control outcomes over capital expenditure minimization.
Supply Chain Analysis
Cold-rolled steel and aluminum extrusion supply rests on Chinese and South Korean mill producers, exposing wall-mounted station fabricators to commodity price volatility and tariff exposure. High-density polyethylene resin draws from Gulf Coast petrochemical complexes and Asian polymer producers, while copper-alloy antimicrobial surface treatments hinge on specialty metal suppliers in Germany and Japan. Single-source vulnerability concentrates in steel frame production, where limited domestic mill capacity forces dependency on Asian imports. Distribution runs through integrated service contractors rather than discrete capital equipment channels, with Aramark and Compass Group consolidating procurement across airport and retail portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASTM F2388 certification timelines extending product launch windows by four to six months force consolidation as smaller manufacturers absorb unsustainable third-party testing costs. This regulatory pressure eliminates marginal players unable to maintain documented testing histories.
For Market Incumbents: Deploy certification depth as a competitive moat by accelerating ASTM F2388 documentation for full product lines before state-level family restroom mandates expand in Illinois and Massachusetts. Backward integration into cold-rolled steel frame production mitigates Chinese mill supply volatility, while exclusive service contracts with Compass Group and Aramark lock out challenger brands from airport concession opportunities.
For New Entrants and Emerging Players: Suburban retail developers in Texas and Florida corridors represent the most penetrable buyer archetype, where rapid commercial construction outpaces national family restroom penetration rates. Smart restroom integration with IoT-enabled occupancy sensors offers a technical wedge against established hardware suppliers, while direct contracting with Houston and Orlando mall developers bypasses incumbent distributor relationships.
For Investors and Strategic Acquirers: Consolidation of vendor lists by Johns Hopkins Medicine and Cleveland Clinic pediatric departments is the leading indicator that pre-certified suppliers with antimicrobial surface portfolios will command acquisition premiums. The five-to-ten-year viability window favors asset-light designers with ASTM F2388 documentation over capital-heavy fabricators exposed to steel input volatility. Watch for Texas and Florida municipal code adoptions mirroring California Title 24 extensions as the signal for accelerated installation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Surface Certification | ASTM F2388 documentation unlocks hospital and airport procurement eligibility. |
| Smart Restroom Integration | IoT sensor partnerships with facility managers optimize cleaning schedules and inventory. |
| Texas-Florida Geographic Expansion | Houston and Orlando retail corridors outpace national family restroom penetration rates. |
| Integrated Service Contracting | Multi-year agreements with Aramark align vendor incentives with uptime performance. |
| Backward Integration into Steel Supply | In-house frame production mitigates Chinese and South Korean mill price volatility. |
Research Methodology
Document review covered ASTM International standards filings, ADA accessibility guideline updates, and state-level building code revisions, complemented by interviews with hospital procurement managers, daycare facility directors, airport concession planners, and commercial restroom contractors. Secondary validation drew from municipal construction permit databases, GPO contract disclosures, and customs records for steel and aluminum extrusion imports. Bottom-up installation forecasts triangulated against top-down commercial construction spending projections.
Segmented outputs across product type, surface material, design positioning, and end-user category fed into analytical framework spanning wall-mounted, portable, and free-standing hardware configurations. CAGRs derived from regression analysis of historical retrofit cycles and forward projection of regulatory mandate adoption curves. Key inputs included ADA compliance penetration rates in US airport infrastructure and antimicrobial surface replacement frequency in hospital pediatric departments.
Revisions become necessary when steel input cost volatility exceeds historical bands or when multi-state code fragmentation accelerates beyond baseline assumptions. Forecasts reflect documented regulatory trajectories and construction cycle patterns. A small set of named triggers warrants ongoing watch: California Title 24 extension adoption in additional states, copper-alloy surface certification standardization, and integrated service contract renewal rates with major facility management groups.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
India Steam Rooms Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
North America Toilet Seat Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market