
 Plumbing Fixtures and Fittings Market | 2026-2036
Plumbing Fixtures and Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Plumbing Fixtures and Fittings Market Intelligence
Premium-grade brass and ceramic specification tiers is redrawing competitive boundaries across the Plumbing Fixtures and Fittings landscape. Kohler Co. leverages in-house foundry capacity to control alloy quality from melt to finish. Toto Ltd. anchors its position through advanced ceramic engineering and automated kiln controls. LIXIL Corp. dominates Southeast Asian distribution through localized manufacturing hubs and direct retail partnerships.
Plumbing fixtures and fittings encompass valves, connectors, outlets, and drainage apparatus fabricated from brass, stainless steel, engineered polymers, or vitreous ceramic, with pressure ratings typically spanning 15 to 80 psi and flow coefficients calibrated to regional plumbing codes. These components regulate water delivery, temperature mixing, and waste evacuation across building systems. The material dimension shows brass commanding durable-margin positions in commercial specification channels while plastic compounds penetrate volume residential segments through cost-optimized injection molding. Application segmentation reveals institutional projects as the most specification-intensive channel, where engineered performance documentation and extended warranty terms determine vendor selection.
EPA WaterSense certification in the United States, the EU Ecodesign framework under the EU Green Deal, and China's GB standards enforced by SAMR collectively mandate flow-rate ceilings and lead-content thresholds that reshape product portfolios. India's BIS marking requirements for plumbing goods add another compliance layer for manufacturers targeting infrastructure builds. Stakeholders must track which regulatory convergence between efficiency mandates and material safety standards will determine factory retooling priorities and geographic sourcing strategies.
Market Dynamics
Water-efficiency mandates across the United States, European Union, and China are compressing flow-rate tolerances and forcing alloy reformulations, while Southeast Asian residential construction absorbs mid-tier brass and ceramic output at accelerating velocity.
Growth Catalysts
- EPA WaterSense:United States federal flow-rate ceilings below 1.28 gallons per flush for toilets and 1.5 gallons per minute for faucets are retiring legacy inventory and triggering replacement cycles in commercial and residential buildings alike.
- Brass foundry consolidation:Captive in-house melting capacity at major manufacturers is compressing lead times and insulating specification-grade production from spot copper volatility.
- India infrastructure builds:National urban housing missions and sanitation campaigns are concentrating demand for BIS-marked ceramic fixtures and chrome-plated brass fittings in tier-2 and tier-3 cities.
Market Restraints
- Copper and zinc input volatility:Brass alloy feedstock costs fluctuate with London Metal Exchange pricing, squeezing margin stability for non-integrated fabricators serving price-sensitive residential channels.
- Lead-content threshold compression:California AB 1953 and forthcoming federal amendments to the Safe Drinking Water Act are forcing expensive alloy substitutions and foundry retooling for exporters targeting North America.
- Polymer substitution in drainage:PVC and PPR compounds are capturing volume share in non-pressurized waste evacuation applications where pressure ratings and thermal cycling demands remain minimal.
Strategic Opportunities
- Vietnam and Indonesia residential:Underpenetrated plumbing fixture saturation in Southeast Asian urban peripheries offers expansion terrain for localized manufacturing hubs serving cost-optimized ceramic and plastic-molded segments.
- EU Ecodesign framework:The EU Green Deal's expanding scope for water-related product categories will privilege early movers with documented lifecycle assessments and circular-design credentials.
- Sensor-integrated faucets:Convergence of piezoelectric sensors with low-flow aerators is opening specification channels in healthcare and hospitality where touchless operation intersects with efficiency compliance.
Industry Challenges
- Master foundry technician scarcity:Precision brass casting and lead-free alloy formulation require skills concentrated in aging workforces across Ohio, Guangdong, and North Rhine-Westphalia foundry clusters.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of EPA WaterSense, EU CE marking, and China GB standard approvals extends product launch cycles and fragments engineering resources.
- Legacy galvanized steel integration:Retrofit projects in North American commercial buildings demand compatibility adapters that add SKU complexity and installation labor cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plumbing Fixtures and Fittings Market |
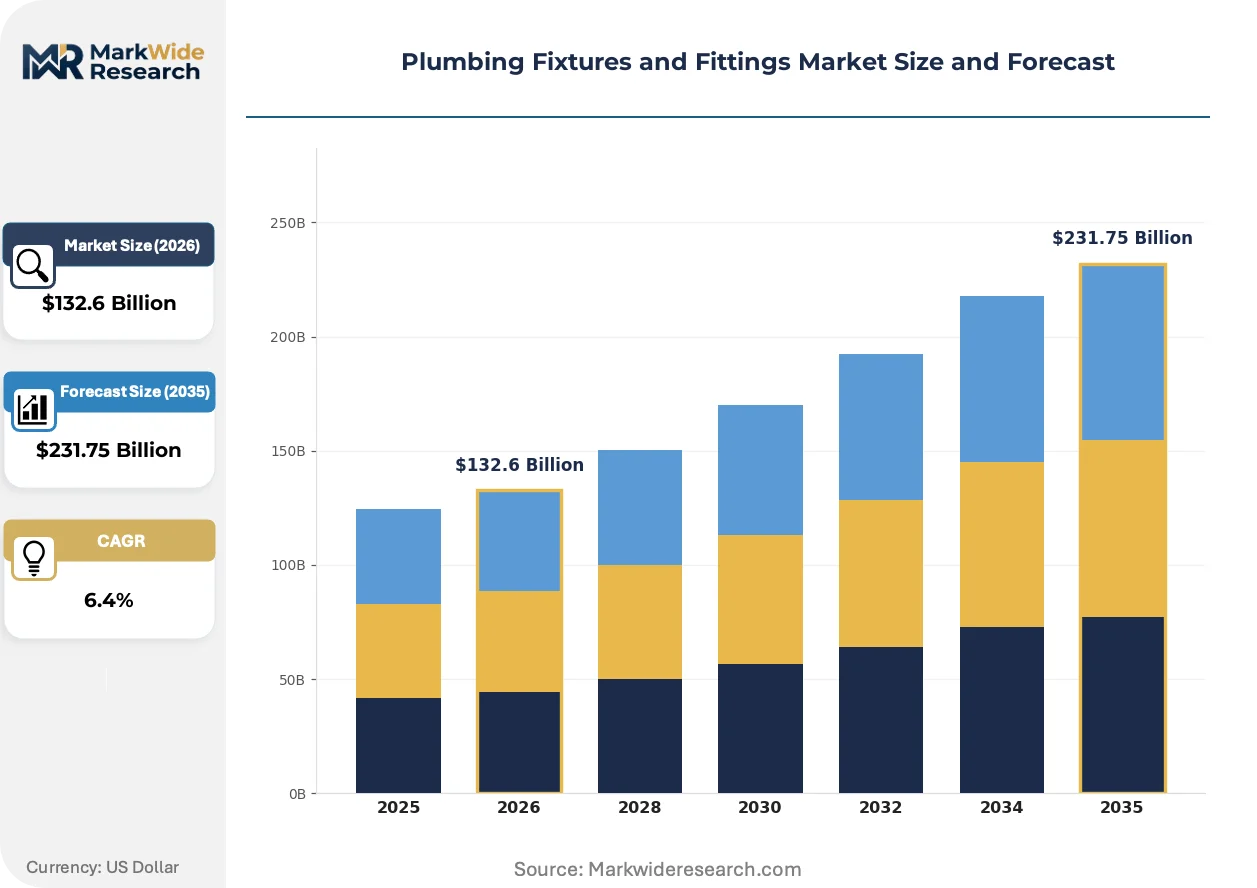
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $231.75 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Faucets, Toilets, Showers, Sinks Material: Plastic, Stainless Steel, Brass, Ceramic Application: Residential, Commercial, Industrial, Institutional Distribution Channel: Retail Stores, Online Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | LIXIL Corp., Toto Ltd., Masco Corp., Kohler Co., Delta Faucet Co, Roca Sanitario SA, Geberit International AG, American Bath Group, Gerber Plumbing Fixtures LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plumbing Fixtures and Fittings Market Strategic Shifts & Innovations
Digital manufacturing controls and material science advances are compressing the performance gap between specification-grade brass and cost-optimized alternatives, while regulatory convergence across major economies is standardizing efficiency baselines.
Advanced ceramic engineering with automated kiln atmosphere control is displacing traditional vitreous china in premium fixture segments. Hospitality and healthcare specifiers in Japan and South Korea are specifying these grades for durability and stain resistance. The technology is displacing conventional two-piece toilet platforms in projects where lifecycle cost documentation determines vendor selection.
The EU Ecodesign framework under the EU Green Deal is extending mandatory water-efficiency requirements to previously exempt product categories. Manufacturers serving European commercial channels must now submit technical documentation for washbasin taps and showerheads previously regulated only by national codes. German and Dutch distributors are consolidating supplier rosters around vendors with pre-validated EU compliance packages.
Specification-driven procurement through certified installer networks is consolidating influence over product selection in institutional construction. Master plumbers and mechanical contractors in California and Texas increasingly source through preferred vendor programs tied to warranty administration. This pattern concentrates volume with manufacturers maintaining direct field service infrastructure and certified training programs.
Plumbing Fixtures and Fittings Market Segmentation
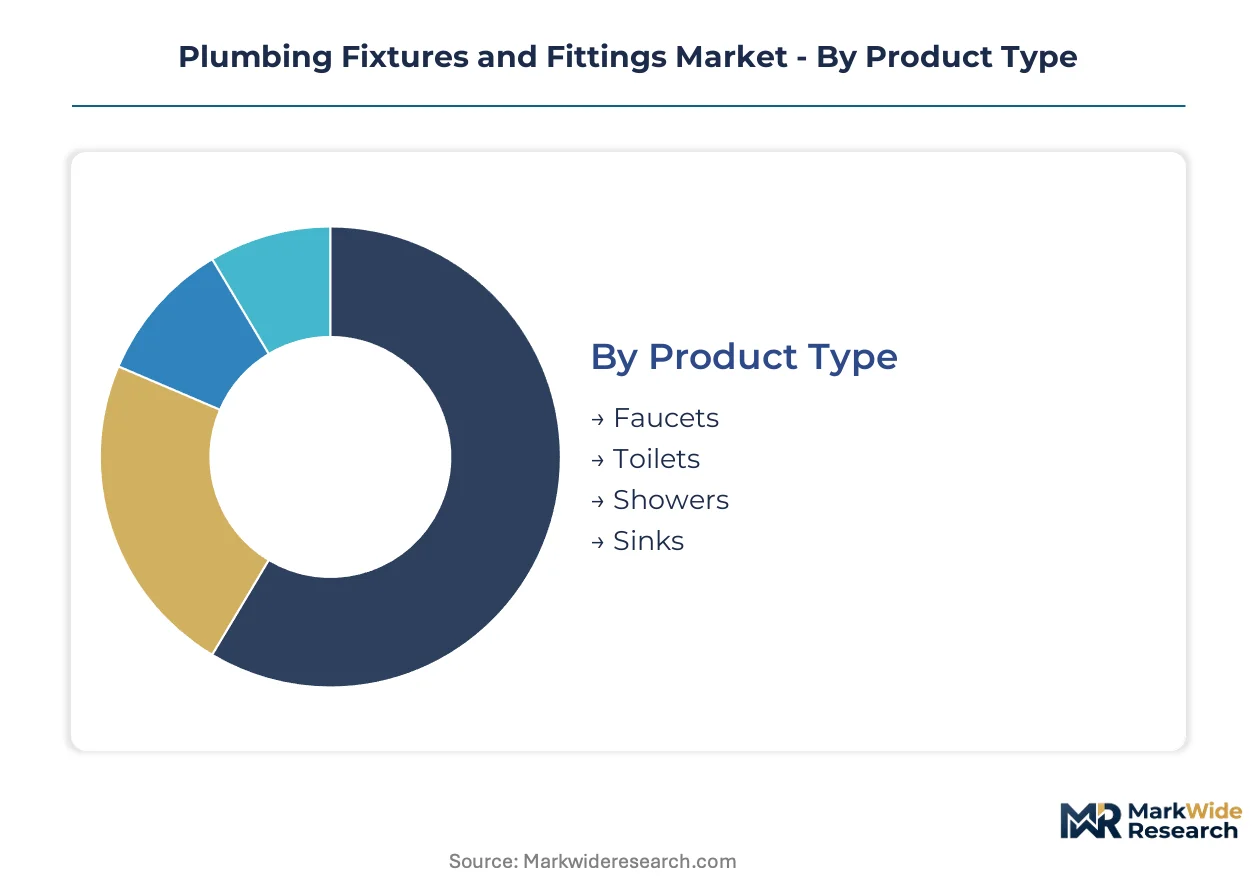
Plumbing fixture and fitting manufacturers navigate divergent certification requirements, material cost structures, and channel economics across product categories. Segmentation clarity determines where alloy reformulation investments yield compliance advantages and which distribution configurations capture replacement-cycle velocity.
Product Type:
EPA WaterSense mandates in the United States enforce distinct flow-rate ceilings across fixture categories, creating tiered compliance burdens that reshape product development priorities.
- Faucets:Aerator-integrated designs with 1.5 gallons-per-minute maximums dominate specification channels. Demand concentrates in California and Texas commercial retrofits where touchless sensor integration intersects with efficiency mandates.
- Toilets:Single-flush and dual-flush platforms rated below 1.28 gallons per flush capture replacement volume in North American municipal housing upgrades. India's urban sanitation campaigns absorb mid-tier ceramic gravity-tank units in tier-2 cities.
- Showers:Thermostatic mixing valves with flow restrictors address thermal safety and water conservation simultaneously.
- Sinks:Vitreous china and stainless steel basins span pedestal, wall-mounted, and undercounter configurations.
Established volume favors toilets; emerging adoption favors sensor-integrated faucets.
Material:
Cost tier differentiation separates specification-grade commercial procurement from residential volume channels.
- Brass:Lead-free alloy formulations meeting California AB 1953 and pending federal amendments command premium positioning. Foundry-integrated manufacturers in Ohio and Guangdong control melt-to-finish quality for institutional specification channels.
- Ceramic:Advanced vitreous china with automated kiln atmosphere control displaces conventional platforms in Japanese and South Korean hospitality projects. Lifecycle cost documentation drives vendor selection in premium segments.
- Plastic:PVC and PPR compounds penetrate residential drainage applications where pressure demands remain minimal.
- Stainless Steel:304 and 316 grades serve commercial kitchen and healthcare environments requiring corrosion resistance.
Brass commands specification margins; plastic compounds gain share fastest in volume residential drainage.
Application:
Customer type determines documentation intensity, warranty terms, and field service requirements.
- Residential:New construction and replacement cycles in Southeast Asian urban peripheries absorb cost-optimized ceramic and plastic-molded output. Vietnam and Indonesia construction velocity outpaces fixture saturation rates.
- Commercial:Office and retail fit-outs in Germany and the Netherlands consolidate procurement around vendors with pre-validated EU Ecodesign compliance packages.
- Institutional:Healthcare and education projects in the United States require engineered performance documentation and extended warranty terms.
- Industrial:Process water and sanitation systems demand pressure-rated components with documented material traceability.
Residential channels drive unit volume; institutional projects concentrate margin capture.
Distribution Channel:
Supply concentration varies sharply between specification-driven procurement and consumer-direct transactions.
- Wholesale Distributors:Master plumber and mechanical contractor networks in California and Texas consolidate volume through preferred vendor programs tied to warranty administration. Direct field service infrastructure determines supplier selection.
- Retail Stores:Big-box and specialty showroom channels serve homeowner replacement cycles with visible inventory and immediate availability.
- Direct Sales:Large-scale project contractors source factory-direct for institutional builds requiring custom specifications.
- Online Stores:E-commerce penetration accelerates in standard-replacement categories with established compatibility standards.
Wholesale distributors anchor commercial specification influence; online channels expand fastest in residential replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major plumbing fixture markets. The United States absorbs specification-grade brass imports while running deficits in ceramic sanitaryware. China maintains surplus positions in mid-tier metal fittings. Germany and Japan export premium engineering to Southeast Asian construction markets.
United States
Commercial retrofit cycles and municipal housing upgrades drive specification-grade demand. EPA WaterSense mandates enforce flow-rate ceilings below 1.28 gallons per flush for toilets. Ohio foundry clusters supply lead-free brass alloys to institutional specification channels.
China
Urban sanitation campaigns and tier-2 city construction concentrate mid-tier ceramic absorption. SAMR enforces GB standards for flow efficiency and material safety. Guangdong manufacturing hubs export brass fittings to Southeast Asian residential markets.
Germany
Healthcare and hospitality specification channels demand engineered performance documentation. EU Ecodesign framework under the EU Green Deal mandates lifecycle assessments for washbasin taps. North Rhine-Westphalia foundry clusters maintain precision casting capacity for lead-free alloys.
India
National urban housing missions and sanitation infrastructure builds absorb BIS-marked ceramic fixtures. BIS marking requirements add compliance layers for chrome-plated brass fittings. Tier-2 and tier-3 cities concentrate demand growth for cost-optimized gravity-tank units.
Japan
Hospitality and healthcare specifiers demand advanced ceramic engineering for durability and stain resistance. METI oversees JIS standards alignment with international efficiency benchmarks. Automated kiln atmosphere control facilities in Chubu region displace conventional vitreous china platforms.
Plumbing Fixtures and Fittings Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and specification access. The vendor base separates into foundry-integrated manufacturers, ceramic engineering specialists, and regional distribution consolidators. Three archetypes dominate: captive alloy producers controlling melt-to-finish quality, automated kiln operators capturing premium ceramic margins, and hub-and-spoke distributors penetrating Southeast Asian peripheries. M&A activity concentrates among distribution assets, while capacity expansion targets localized manufacturing in Vietnam and Indonesia.
Within the foundry-integrated tier, Kohler Co. and Masco Corp. exemplify capital-intensive positioning through captive melting capacity. Toto Ltd. occupies a specialist position in advanced ceramic engineering. LIXIL Corp. anchors the distribution-consolidator archetype through Southeast Asian hub strategies. These three represent distinct competitive vectors rather than overlapping market contests.
| Leading Market Players |
|---|
| LIXIL Corp. |
| Toto Ltd. |
| Masco Corp. |
| Kohler Co. |
| Delta Faucet Co |
| Roca Sanitario SA |
| Geberit International AG |
| American Bath Group |
| Gerber Plumbing Fixtures LLC |
| Others |
Cost & Logistics Intelligence
Foundry scale economies in Guangdong and Ohio compress unit costs for lead-free brass alloys while simultaneously elevating price floors for specification-grade output. Captive melting capacity insulates integrated manufacturers from London Metal Exchange volatility, forcing non-integrated fabricators into cost-optimized polymer alternatives or margin-eroding spot market exposure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on EPA WaterSense certification grade and foundry integration depth, with specification-grade brass commanding substantial premiums over injection-molded residential alternatives. Cost compression in mid-tier ceramic segments is intensifying because Vietnamese and Indonesian construction velocity outpaces localized supply expansion. Residential replacement channels exhibit highest price sensitivity; institutional specification buyers prioritize lifecycle documentation over unit cost.
Supply Chain Analysis
Inventory cycles for brass alloy feedstock extend lead times by 8-12 weeks during copper price volatility episodes. Supply concentrates in China, Vietnam, and Germany, with Guangdong hubs dominating mid-tier metal fabrication and North Rhine-Westphalia foundries serving premium European specification channels. Raw material dependencies center on copper-zinc alloys, engineered ceramic clays, and chrome-plating chemicals. Single-source vulnerability pervades precision casting technician pools across aging workforces in Ohio and Guangdong. Distribution runs through wholesale distributor networks anchored by master plumber preferred vendor programs in California and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—EPA WaterSense, EU Ecodesign, and India BIS marking requirements—erects compliance barriers that favor incumbents with pre-validated certification packages and field service infrastructure.
For Market Incumbents: Secure specification-grade positioning by deepening backward integration into captive brass foundry capacity and expanding certified installer training programs. Polymer substitution in drainage applications and emerging Vietnamese manufacturing clusters threaten margin stability in residential volume tiers. Prioritize alloy formulation R&D for pending federal Safe Drinking Water Act amendments. For New Entrants and Emerging Players: Anchor in Vietnam and Indonesia residential construction peripheries where fixture saturation rates trail construction velocity. Mid-tier ceramic gravity-tank toilets and cost-optimized PPR drainage compounds represent the most penetrable white-space. Pursue direct retail partnerships with localized manufacturing hubs rather than distributor intermediation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors foundry-integrated manufacturers with demonstrated EPA WaterSense and EU Ecodesign pre-validation. Long-term viability hinges on regulatory compliance scalability across multi-jurisdiction certification timelines. Monitor master foundry technician pipeline development in Guangdong and Ohio as inflection signal for supply constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Insulates Kohler and Masco from London Metal Exchange copper volatility while compressing lead times. |
| EU Ecodesign Pre-Validation Investment | German and Dutch distributors consolidate supplier rosters around vendors with documented lifecycle assessments. |
| Southeast Asian Manufacturing Localization | Vietnam and Indonesia construction velocity outpaces fixture saturation, rewarding hub-and-spoke distribution models. |
| Sensor-Integrated Faucet Development | Piezoelectric sensor convergence with low-flow aerators opens healthcare and hospitality specification channels. |
| Lead-Free Alloy Formulation R&D | California AB 1953 and pending federal amendments force expensive retooling that favors integrated manufacturers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade customs data, EPA WaterSense certification registries, EU Ecodesign technical documentation, and SEC 10-K filings from listed plumbing fixture manufacturers. Primary interviews engaged product development directors at foundry-integrated manufacturers, procurement leads at wholesale distributors, master plumber network coordinators, and regulatory affairs specialists navigating multi-jurisdiction compliance. Bottom-up unit economics triangulate against top-down construction spend allocations across residential, commercial, and institutional application segments.
Segmentation dimensions modeled encompass product type, material grade tier, application channel, and distribution configuration across the projection horizon. CAGRs derive from regression analysis of historical replacement cycle velocity, regulatory mandate implementation timelines, and construction spend elasticity. Industry-specific forecast inputs include EPA WaterSense inventory retirement schedules and India urban housing mission sanctioning velocity.
Material uncertainties—commodity price volatility, regulatory amendment timing, and master foundry technician availability—sit outside the modeled envelope. Forecasts reflect assumptions about certification convergence and construction cycle continuity without guaranteeing specific trajectory realization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Artificial Stone Bathtubs Market
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
India Steam Rooms Market