
 Global FPGA in Telecom Sector Market | 2026-2036
Global FPGA in Telecom Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Global FPGA in Telecom Sector Market Foresight
High-performance tier silicon is rotating toward the center of carrier procurement decisions. Intel Corporation leverages its foundry-scale manufacturing to dominate data center-class FPGA supply for packet inspection workloads. Advanced Micro Devices, Inc. sustains technology leadership in adaptive SoC architectures that merge programmable logic with hardened AI engines. Lattice Semiconductor Corporation specializes in low-power FPGA designs that anchor power-constrained edge computing deployments.
Field-programmable gate arrays in the telecom sector comprise reconfigurable semiconductor devices built on SRAM-based or flash-based lookup table fabrics with logic densities spanning thousands to millions of system gates, enabling post-manufacturing hardware reconfiguration for protocol-specific acceleration. Their primary commercial purpose centers on offloading computationally intensive telecom functions—baseband processing, signal modulation, and deep packet inspection—from general-purpose processors to dedicated parallel logic fabrics. High-performance FPGA and mid-range FPGA categories capture the dominant margin pools as 5G massive MIMO and Open RAN architectures drive silicon complexity upward. Edge computing and hybrid systems deployment models represent the fastest-growing configuration segments as operators distribute intelligence closer to radio access network endpoints.
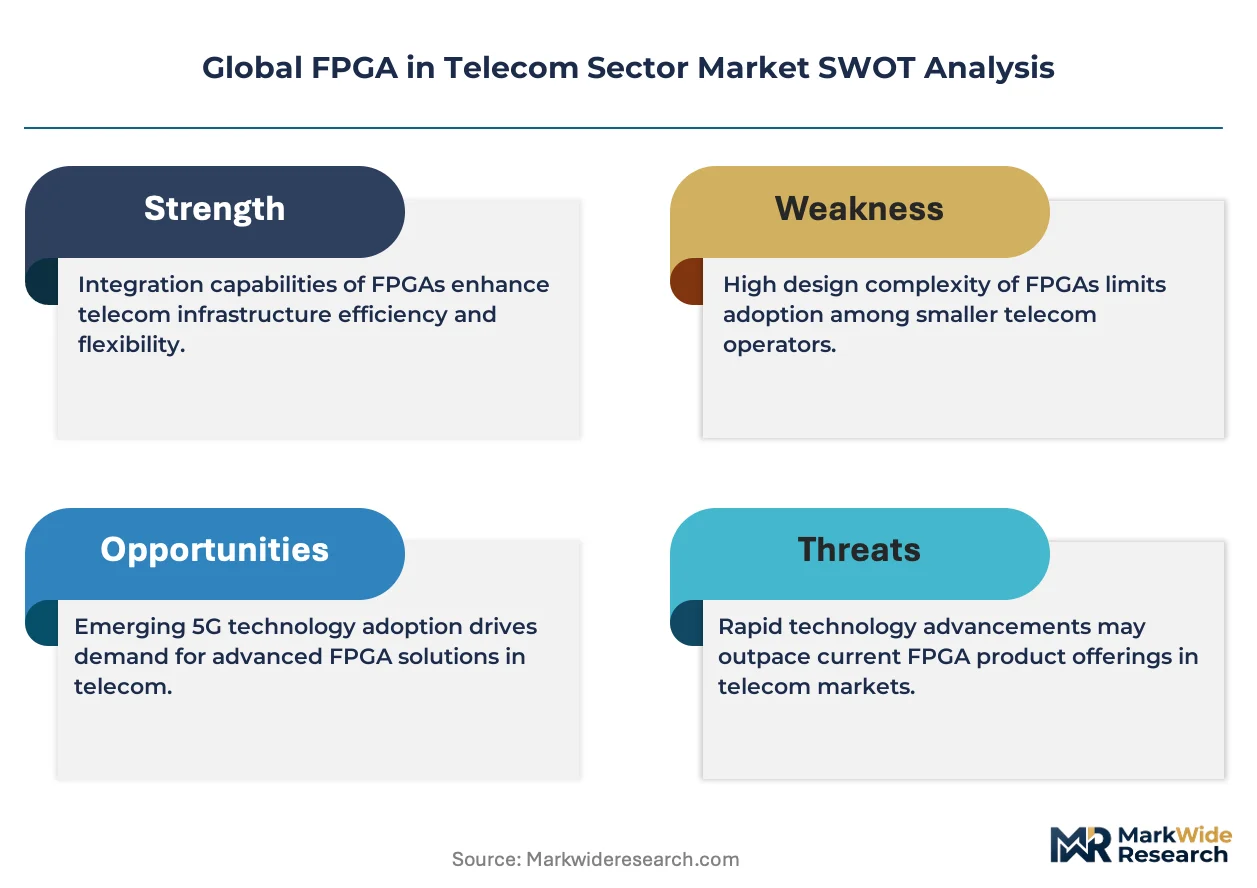
FCC equipment authorization rules, ETSI network function virtualization standards, and China's GB/T national encryption compliance frameworks collectively shape product qualification timelines and geographic market access for FPGA vendors. REACH substance restrictions and RoHS material directives constrain substrate and packaging chemistry choices across European-bound shipments. Stakeholders must monitor Open RAN interoperability certification evolution and sovereign cloud mandates as determinants of future silicon specification roadmaps.
Market Dynamics
5G massive MIMO rollouts and Open RAN disaggregation are forcing carrier procurement toward reconfigurable silicon architectures that can absorb protocol volatility without hardware swaps.
Growth Catalysts
- EU AI Act hardware certification:Telecom operators in Germany and France now mandate explainable AI inference at the network edge, accelerating FPGA deployment for deterministic packet processing.
- China's GB/T encryption compliance:Domestic carriers must embed government-approved cryptographic modules, creating captive demand for flash-based FPGA designs with tamper-resistant key storage.
- Low-latency edge computing clusters:Distributed baseband hotels in South Korea and Japan require programmable logic for real-time signal conditioning closer to radio heads.
Market Restraints
- Advanced packaging substrate shortage:Organic substrate capacity constraints at Taiwanese OSATs extend lead times for high-pin-count FPGA modules bound for base station line cards.
- REACH substance restrictions:ECHA limitations on halogenated flame retardants force redesign of laminate materials for European-bound telecom equipment, compressing gross margins.
- ASIC substitution at volume scale:Chinese tower operators with predictable traffic patterns are migrating massive MIMO baseband to custom silicon once FPGA validation completes.
Strategic Opportunities
- India's PLI scheme for telecom gear:Domestic manufacturing incentives attract FPGA vendors to establish local programming centers for Reliance Jio and Bharti Airtel supply chains.
- Convergence of programmable logic with photonic interconnect:Co-packaged optics integration enables 800G coherent DSP acceleration in disaggregated RAN fronthaul.
- Direct-to-carrier distribution bypass:Lattice and smaller vendors now sell through Arrow's embedded solutions division rather than traditional broadline distribution, capturing design-win margin.
Industry Challenges
- RTL-to-bitstream talent scarcity:Carrier engineering teams lack sufficient Verilog and VHDL specialists to optimize power-performance for 7nm FPGA fabrics.
- Open RAN 7.2x split certification timelines:O-RAN Alliance interoperability testing adds 9-14 months to product qualification, freezing silicon roadmaps mid-development.
- Legacy TDM backhaul integration:European incumbents Deutsche Telekom and BT Group maintain SDH/SONET fringe networks that resist packet-native FPGA migration without costly gateway equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global FPGA in Telecom Sector Market |
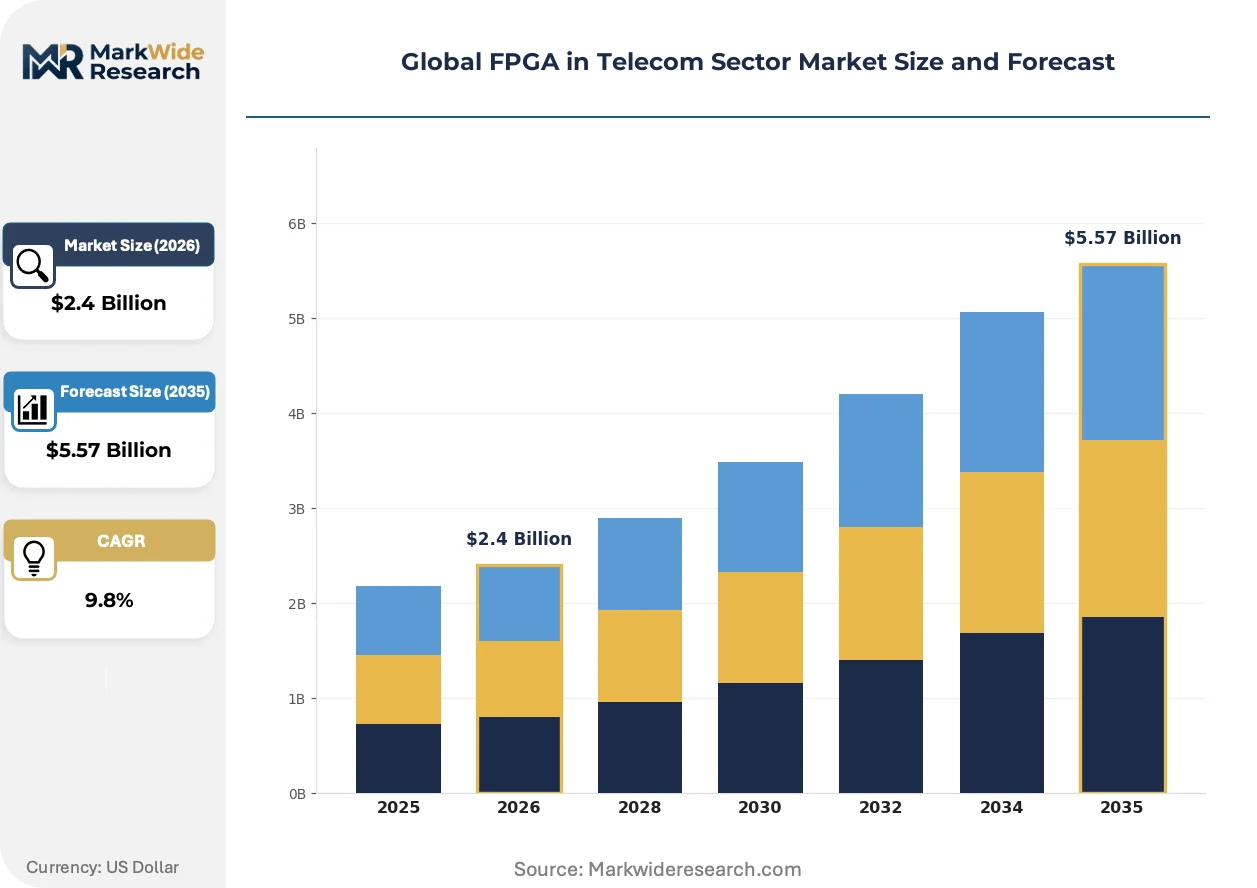
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.57 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Power FPGA, High-Performance FPGA, Mid-Range FPGA, Analog FPGA, Mixed-Signal FPGA Application: Baseband Processing, Signal Modulation, Network Security, Data Acceleration, Packet Inspection Deployment: On-Premise, Cloud Integration, Edge Computing, Hybrid Systems End User: Telecom Operators, Network Equipment Providers, Data Centers, Cloud Service Providers |
| Companies Covered | Advanced Micro Devices, Inc., Intel Corporation, Lattice Semiconductor Corporation, Microchip Technology Inc., Achronix Semiconductor Corporation, QuickLogic Corporation, Efinix Inc., Flex Logix Technologies, Inc., GOWIN Semiconductor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global FPGA in Telecom Sector Market Shifts & Advancements
Hardware programmability is becoming the primary hedge against spectrum fragmentation and protocol churn as carriers deploy across sub-6 GHz, mmWave, and unlicensed bands simultaneously.
Adaptive SoC architectures with hardened AI engines are decomposing the traditional discrete DSP-plus-FPGA board layouts in 5G baseband units. Samsung and Nokia radio access teams now specify single-chip solutions for 64T64R massive MIMO digital front ends, collapsing bill-of-materials complexity while preserving field-upgrade paths for 3GPP Release 18 features.
ETSI network function virtualization standards and the FCC's revised equipment authorization procedures are compressing hardware certification cycles for software-defined radio platforms. The EU AI Act's risk-classification framework now captures base station management systems, forcing FPGA bitstreams to document algorithmic decision paths for notified body review.
Carrier engineering organizations are consolidating vendor relationships around silicon-plus-software subscription bundles rather than discrete component procurement. Verizon and AT&T infrastructure teams now negotiate three-year adaptive compute capacity agreements with automatic technology refresh clauses, displacing traditional spot-buying of individual FPGA SKUs through distribution.
Global FPGA in Telecom Sector Market Segmentation
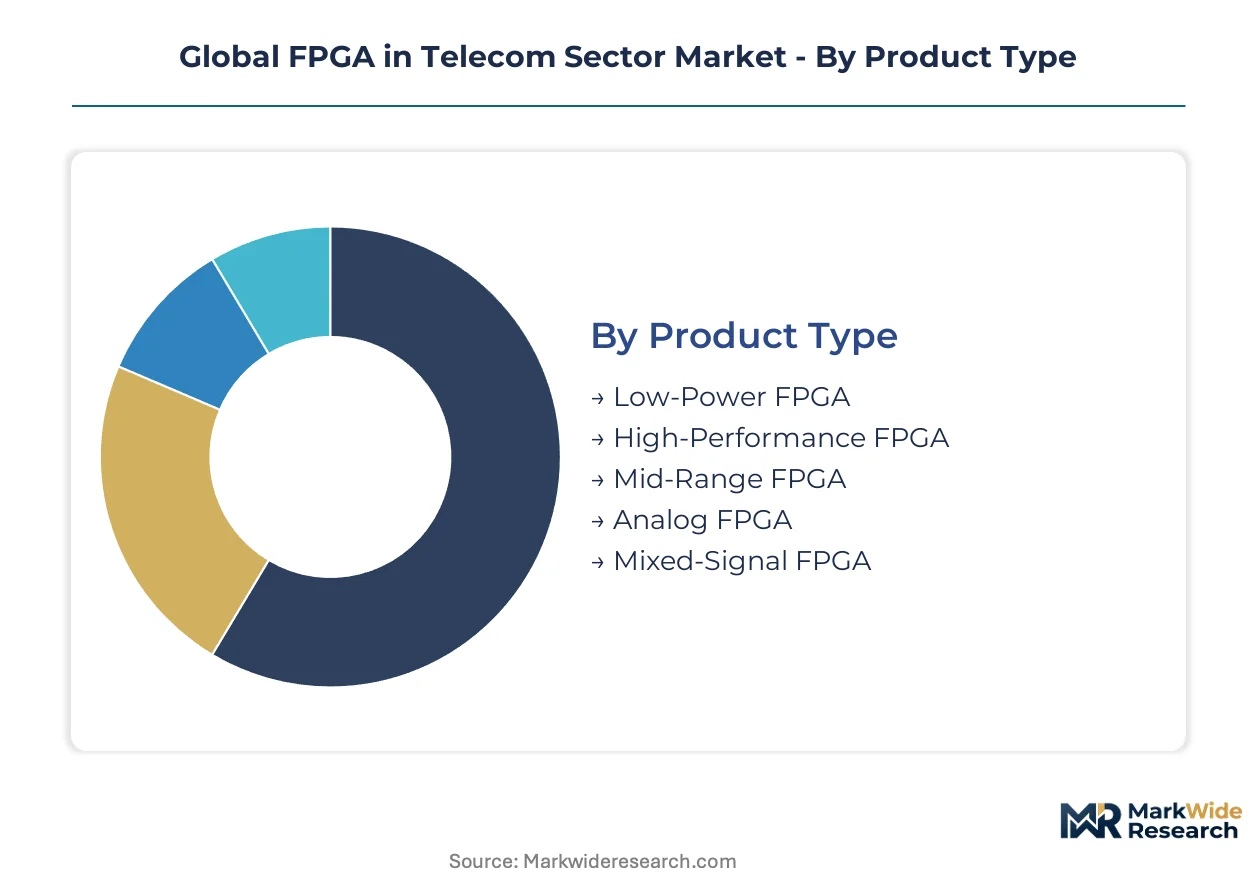
Segmentation in the telecom FPGA market reveals how regulatory pressure and deployment architecture reshape silicon procurement. Carriers now specify programmable logic by power envelope and certification tier rather than raw gate density alone.
Product Type:
REACH substance restrictions and FCC equipment authorization rules create divergent qualification pathways across power-performance tiers.
- High-Performance FPGA:Built on 7nm FinFET processes with millions of system gates and hardened AI engines for massive MIMO baseband. Deutsche Telekom and Verizon procurement teams prioritize these for central office packet inspection where thermal budgets permit active cooling. EU AI Act documentation requirements extend bitstream verification timelines.
- Mid-Range FPGA:SRAM-based fabrics with 100K-500K logic cells balance reprogrammability against unit economics. South Korean carriers deploy these for 5G fronthaul aggregation where protocol flexibility matters more than peak throughput. GB/T encryption compliance in China favors flash-based variants with tamper-resistant key storage.
- Low-Power FPGA:Sub-watt static power consumption enables battery-backed remote radio head deployments.
- Analog FPGA:Continuous-time programmable analog blocks support RF signal conditioning without external data converters.
- Mixed-Signal FPGA:Integrated ADC/DAC channels reduce component count in software-defined radio platforms.
Established volume favors High-Performance FPGA; emerging adoption favors Low-Power FPGA.
Application:
Functional segmentation tracks where programmable logic offloads workloads from general-purpose processors in disaggregated RAN architectures.
- Baseband Processing:Digital front-end functions including FFT/iFFT, precoding, and resource mapping execute on parallel logic fabrics. Nokia and Samsung radio teams specify adaptive SoCs for 64T64R arrays where 3GPP Release 18 upgrade paths must survive hardware refresh cycles. Open RAN 7.2x split certification adds 9-14 months to qualification.
- Packet Inspection:Deep packet inspection engines at 100Gbps line rates require programmable parsing of encrypted traffic headers. German and French operators now mandate explainable AI inference at the edge, accelerating deterministic FPGA deployment over black-box ASIC alternatives. ETSI NFV standards constrain software-hardware interface specifications.
- Signal Modulation:Digital upconversion and crest factor reduction for multi-carrier waveforms.
- Network Security:Hardware root-of-trust implementations with side-channel attack resistance.
- Data Acceleration:Compression and encryption offload for telco cloud storage tiers.
Carrier procurement concentrates on Baseband Processing; security mandates are expanding Packet Inspection fastest.
Deployment:
Physical distribution of compute determines power envelope, environmental hardening, and software update mechanisms.
- Edge Computing:Micro data centers within 10km of radio heads demand fanless designs operating across -40°C to 85°C. Japanese and South Korean tower operators deploy these for ultra-reliable low-latency communication slices where 1ms round-trip is mandatory. India's PLI scheme for telecom gear attracts local programming center investment.
- Hybrid Systems:Split processing across centralized cloud and distributed edge nodes. BT Group and Deutsche Telekom maintain this architecture to bridge legacy SDH/SONET backhaul with packet-native 5G cores. Co-packaged optics integration enables 800G coherent DSP acceleration in fronthaul links.
- On-Premise:Central office deployments with controlled environments and maintenance access.
- Cloud Integration:FPGA-as-a-service models for network function virtualization workloads.
Hybrid Systems anchor current infrastructure spend; Edge Computing climbs the fastest as operators distribute intelligence toward radio access network endpoints.
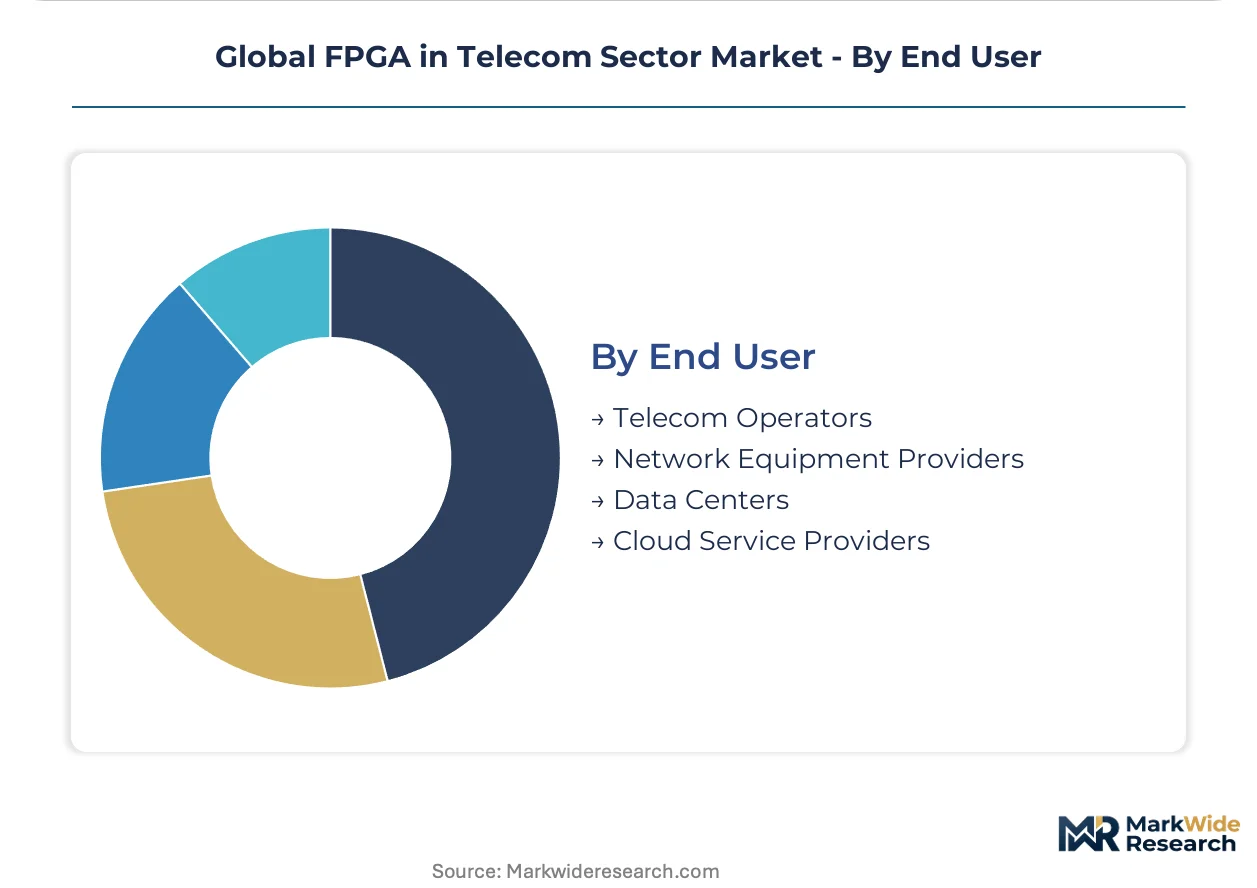
End User:
Buyer type dictates contract structure, volume scale, and technical support expectations across the value chain.
- Telecom Operators:Verizon and AT&T infrastructure teams negotiate three-year adaptive compute capacity agreements with automatic technology refresh clauses. These subscription bundles displace discrete component procurement through traditional distribution. RTL-to-bitstream talent scarcity within carrier engineering organizations drives preference for vendor-provided reference designs.
- Network Equipment Providers:Ericsson, Nokia, and Samsung radio access divisions specify silicon for integration into base station line cards. Advanced packaging substrate shortages at Taiwanese OSATs extend lead times for high-pin-count modules bound for these customers.
- Data Centers:Hyperscale facilities seeking programmable acceleration for telco cloud workloads.
- Cloud Service Providers:AWS, Azure, and GCP offering FPGA-enabled network function virtualization to enterprise tenants.
Direct operator relationships concentrate design-win margin; equipment provider channels still dominate physical shipment volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese carriers exhibit the lowest price elasticity for high-performance silicon, while European operators demand rigorous certification documentation that compresses margins. Indian procurement teams show acute sensitivity to unit economics amid PLI scheme localization requirements. German and South Korean buyers prioritize deterministic latency over cost optimization in edge computing clusters.
China
Domestic 5G massive MIMO deployments drive captive demand for flash-based FPGA designs with tamper-resistant key storage under GB/T encryption compliance. MIIT spectrum allocation rules mandate government-approved cryptographic modules in all carrier-grade hardware. Shenzhen and Shanghai host concentrated programming centers serving China Mobile and China Telecom procurement pipelines.
United States
Verizon and AT&T infrastructure teams negotiate multi-year adaptive compute capacity agreements with embedded technology refresh clauses. FCC equipment authorization rules compress hardware certification cycles for software-defined radio platforms. Dallas-Fort Worth and Seattle metro areas concentrate vendor engineering support facilities for direct operator relationships.
Germany
Deutsche Telekom procurement prioritizes explainable AI inference at the network edge under EU AI Act risk-classification frameworks. REACH substance restrictions on halogenated flame retardants force laminate material redesigns for European-bound shipments. Munich and Berlin anchor radio access network testing facilities for Open RAN interoperability certification.
South Korea
SK Telecom and KT Corporation deploy distributed baseband hotels for ultra-reliable low-latency communication slices requiring sub-millisecond round-trip times. METI-aligned standards guide NFV interface specifications for disaggregated RAN architectures. Seoul Capital Area and Busan-Ulsan corridor concentrate edge computing micro data center deployments.
India
Reliance Jio and Bharti Airtel supply chains attract FPGA vendor investment in local programming centers under PLI scheme manufacturing incentives. TRAI regulatory frameworks shape equipment authorization timelines for imported silicon. Bengaluru and Hyderabad host emerging design-win engineering hubs for mid-range FPGA customization.
Global FPGA in Telecom Sector Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the telecom FPGA sector. Foundry-scale integrated device manufacturers dominate data center-class supply for packet inspection workloads, while fabless specialists anchor power-constrained edge deployments. The competitive structure separates into three strategic archetypes: integrated silicon foundries with captive manufacturing, adaptive SoC architects merging programmable logic with hardened compute engines, and low-power programmable logic specialists. Dominant competitive moves include backward integration into substrate packaging and direct-to-carrier distribution bypass of traditional broadline channels.
Within the integrated foundry tier, Intel Corporation and Advanced Micro Devices, Inc. occupy positions defined by manufacturing scale and adaptive architecture portfolios respectively. Lattice Semiconductor Corporation exemplifies the low-power specialist archetype targeting fanless edge computing specifications. These three entities collectively represent the spectrum of competitive positioning from central office thermal budgets to remote radio head power constraints.
| Leading Market Players |
|---|
| Advanced Micro Devices, Inc. |
| Intel Corporation |
| Lattice Semiconductor Corporation |
| Microchip Technology Inc. |
| Achronix Semiconductor Corporation |
| QuickLogic Corporation |
| Efinix Inc. |
| Flex Logix Technologies, Inc. |
| GOWIN Semiconductor Corporation |
| Others |
Supply & Pricing Matrix
FCC equipment authorization rules and EU AI Act certification tiers gate both supply qualification and price differentiation simultaneously. Carriers now pay premiums for bitstream documentation packages that satisfy notified body review, while flash-based variants with tamper-resistant key storage command spreads in China under GB/T mandates.
Pricing Analysis
After-sales engineering support and multi-year adaptive compute subscriptions now drive lifetime value capture. Three-tier pricing structure across premium certification-grade, standard interoperability-tested, and economy reference-design tiers separates procurement pools. Cost compression in mid-range SRAM fabrics is intensifying because Chinese tower operators are migrating validated designs to custom silicon. Network equipment providers show acute price sensitivity compared to direct operator relationships that prioritize technology refresh guarantees.
Supply Chain Analysis
Extended lead times for high-pin-count organic substrates at Taiwanese OSATs are compressing gross margins across high-performance tiers. Manufacturing gravity centers on Taiwan, South Korea, and the United States for 7nm FinFET wafer starts, while substrate lamination draws from Japan and Germany for REACH-compliant materials. Single-source vulnerability in advanced packaging capacity exposes vendors to allocation freezes during foundry loading spikes. Distribution runs through Arrow's embedded solutions division for direct-to-carrier bypass, displacing traditional broadline channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RTL-to-bitstream engineering talent scarcity constrains carrier self-sufficiency and creates vendor dependency. The gap between hardware specification and optimized bitstream deployment opens margin capture opportunities for firms controlling reference design IP.
For Market Incumbents: Shield data center-class packet inspection share by deepening captive substrate packaging capacity in Taiwan and South Korea. Secure Open RAN 7.2x split certification pre-qualification to freeze competitor roadmap development. Prioritize backward integration into tamper-resistant key storage modules for China-bound flash-based portfolios.
For New Entrants and Emerging Players: FPGA-as-a-service subscription gaps in Indian and Southeast Asian carrier procurement present white-space entry points. Target Reliance Jio and Bharti Airtel supply chains through PLI scheme-compliant local programming centers. Pursue direct embedded solutions distribution partnerships rather than broadline channel stacking.
For Investors and Strategic Acquirers: The EU AI Act's risk-classification expansion reshapes the acquisition landscape toward bitstream auditability assets. Five-to-ten year viability favors adaptive SoC architects with hardened AI engine roadmaps over discrete FPGA pure-plays. Monitor O-RAN Alliance interoperability certification timelines as the inflection signal for silicon specification freezes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Packaging | Captive organic laminate capacity at Taiwanese OSATs insulates against allocation shocks. |
| Open RAN Interoperability Pre-Certification | Early O-RAN Alliance 7.2x split qualification freezes competitor silicon roadmaps mid-development. |
| Direct-to-Carrier Distribution Bypass | Arrow embedded solutions partnerships capture design-win margin from traditional broadline channels. |
| Adaptive SoC Architecture Roadmap | Hardened AI engine integration collapses discrete DSP-plus-FPGA board complexity for 64T64R massive MIMO. |
| GB/T Encryption Compliance Localization | Flash-based FPGA designs with tamper-resistant key storage unlock China Mobile and China Telecom procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ETSI NFV standards documentation, FCC equipment authorization filings, SEC 10-K semiconductor segment disclosures, and O-RAN Alliance interoperability test results. Interviews with carrier infrastructure procurement directors, baseband hardware engineering leads, and FPGA vendor product marketing executives grounded demand-side assumptions. Bottom-up unit shipment estimates triangulated against top-down silicon content per base station line card.
Segmentation dimensions modeled span performance tier, deployment architecture, application function, and geographic regulatory cluster across the analysis window. CAGRs derive from carrier capex trajectory analysis, 5G massive MIMO deployment schedules, and Open RAN disaggregation penetration curves. Co-packaged optics integration timelines and AI Act documentation burden estimates inform edge computing adoption velocity.
Forecasts assume regulatory continuity in FCC equipment authorization, EU AI Act risk-classification, and China's GB/T encryption compliance regimes; material policy shifts would require re-modeling. Supply-side assumptions rest on foundry capacity expansion schedules and OSAT substrate allocation protocols. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
United States Set-Top Box Market
Telecom Hardware
Land Mobile Radio System Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Communication Base Station Equipment Pcb Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Point-To-Point Microwave Antenna Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Asia Pacific Enterprise Routers Market