
 Telecom Electronic Manufacturing Services (EMS) Market | 2026-2036
Telecom Electronic Manufacturing Services (EMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Electronic Manufacturing Services (EMS) Market Intelligence
Vietnam is reconfiguring its northern industrial corridor into a primary assembly hub for telecom EMS, drawing final-stage integration away from higher-cost manufacturing zones. Foxconn anchors this shift through massive facility investments in Bac Ninh and Bac Giang provinces. Jabil Inc competes by leveraging its vertical integration into RF testing and precision machining for 5G base station enclosures. Celestica Inc differentiates through specialized cleanroom operations serving North American telecom equipment manufacturers with ITAR-compliant workflows.
Telecom Electronic Manufacturing Services encompasses the outsourced design, fabrication, assembly, testing, and fulfillment of electronic systems and subsystems purpose-built for telecommunications infrastructure, typically involving multi-layer PCBs with controlled impedance specifications, conformal coating processes, and thermal management integration for continuous operation in base station environments. The primary commercial purpose centers on enabling telecom original equipment manufacturers to scale production without capital-intensive captive manufacturing while accessing specialized process capabilities for high-frequency signal integrity. Contract Manufacturing currently occupies the largest value share within Service Type as tier-one vendors consolidate box-build and system-integration responsibilities under single-source agreements. 5G Technology within the Technology dimension represents the fastest-expanding demand vector, driven by massive MIMO antenna deployment and open RAN hardware qualification programs that require EMS partners with mmWave testing competencies.
FCC equipment authorization requirements in the United States, combined with CE marking obligations under the EU Radio Equipment Directive, shape product validation roadmaps and limit market access for EMS providers lacking accredited testing laboratories. REACH substance restrictions and RoHS hazardous material limits further constrain solder alloy formulations and PCB laminate selections across European-bound production lines. Stakeholders must monitor open RAN interoperability certification timelines and corresponding shifts in OEM qualification criteria for contract manufacturing partners.
Market Dynamics
Open RAN hardware qualification programs are compressing OEM qualification timelines for contract manufacturers while simultaneously fragmenting supplier ecosystems across multi-vendor interoperability requirements.
Growth Catalysts
- Massive MIMO antenna deployment:Telecom operators in Germany, South Korea, and the United States are procuring high-density antenna arrays that demand EMS partners with mmWave signal integrity testing capabilities.
- REACH substance restrictions:European-bound production lines are accelerating adoption of halogen-free PCB laminates and lead-free solder alloys to maintain market access under evolving hazardous material limits.
- Vietnam tariff-advantaged export routes:Contract manufacturers are relocating final-stage integration capacity to Bac Ninh and Bac Giang provinces to capture preferential trade terms with North American telecom equipment vendors.
Market Restraints
- RoHS hazardous material limits:Solder alloy formulations containing legacy tin-lead compositions face exclusion from EU-bound shipments, forcing costly metallurgy transitions at contract manufacturers.
- Concentrated rare earth processing:Neodymium and dysprosium supply for RF component magnetics concentrates in Chinese refining operations, creating single-source vulnerability for base station power amplifier assemblies.
- Thermal management material scarcity:Vapor chamber and heat pipe substrates require controlled-impedance copper alloys with limited qualified suppliers in Southeast Asia.
Strategic Opportunities
- ITAR-compliant cleanroom operations:North American defense-adjacent telecom infrastructure creates captive demand for EMS providers with security-cleared manufacturing workflows and controlled facility access protocols.
- EU F-Gas Regulation phase-down:Thermal interface material suppliers can capture share by qualifying fluorinated gas-free phase change materials for base station outdoor enclosure cooling systems.
- AI-driven predictive maintenance integration:EMS partners embedding sensor networks and edge analytics into 5G base station power supplies can differentiate through lifecycle service revenue streams.
Industry Challenges
- mmWave test engineering talent scarcity:Qualified RF technicians capable of calibrating vector network analyzers for 28 GHz and 39 GHz antenna patterns command premium compensation in Vietnam and Mexico manufacturing corridors.
- FCC equipment authorization timelines:Certification bottlenecks at accredited telecommunication certification bodies extend product launch windows for open RAN radio units targeting US carrier procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Electronic Manufacturing Services (EMS) Market |
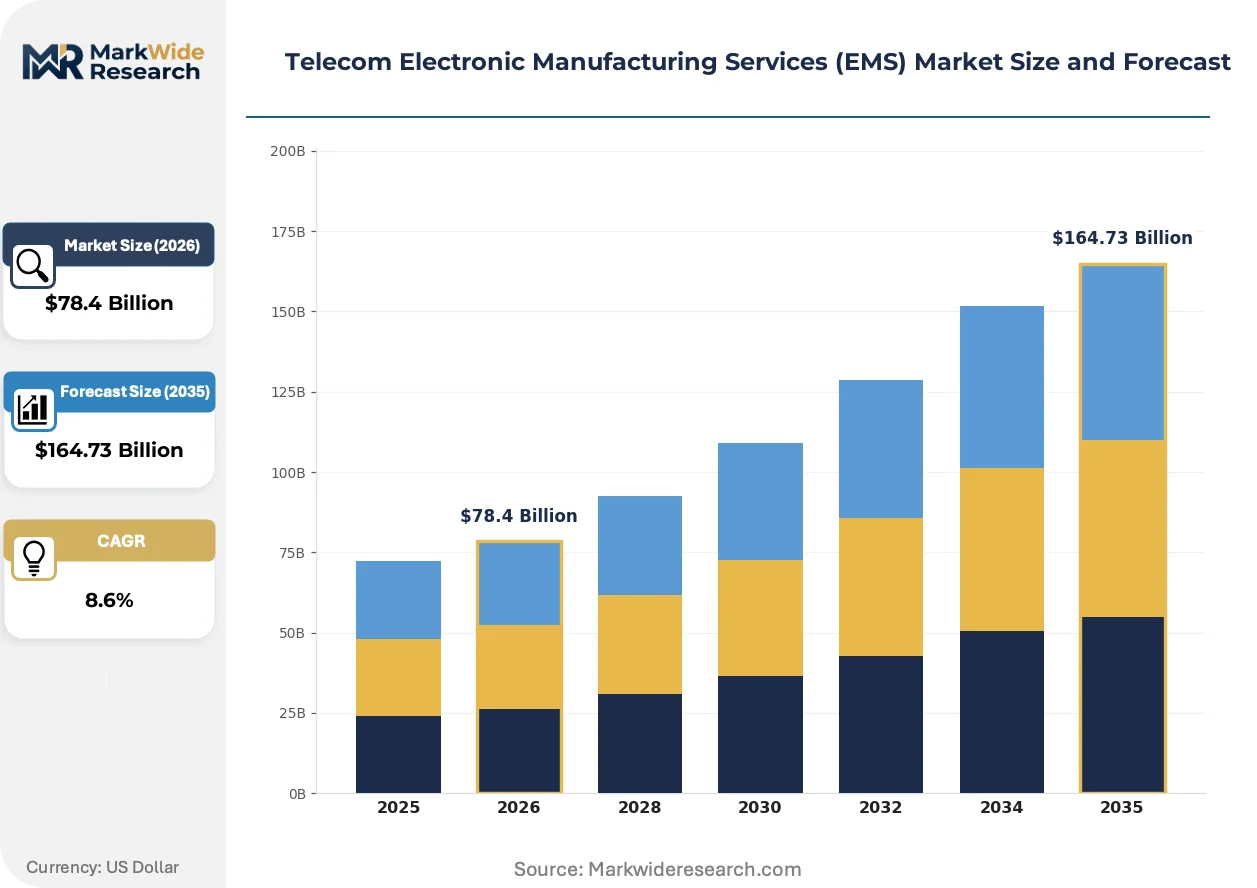
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Original Design Manufacturing, Contract Manufacturing, Testing Services, Prototyping Services End User: Telecom Operators, Equipment Manufacturers, Aftermarket Providers, IoT Device Companies Technology: 5G Technology, LTE, Edge Computing, Wireless Communication Product Type: Network Equipment, RF Components, Access Points, Signal Processors |
| Companies Covered | Sanmina Corporation, Wistron Corporation, Foxconn, Plexus Corp, Pegatron Corporation, Flex Ltd, Celestica Inc, Universal Scientific Industrial Co., Ltd, Jabil Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Electronic Manufacturing Services (EMS) Market Strategic Shifts & Innovations
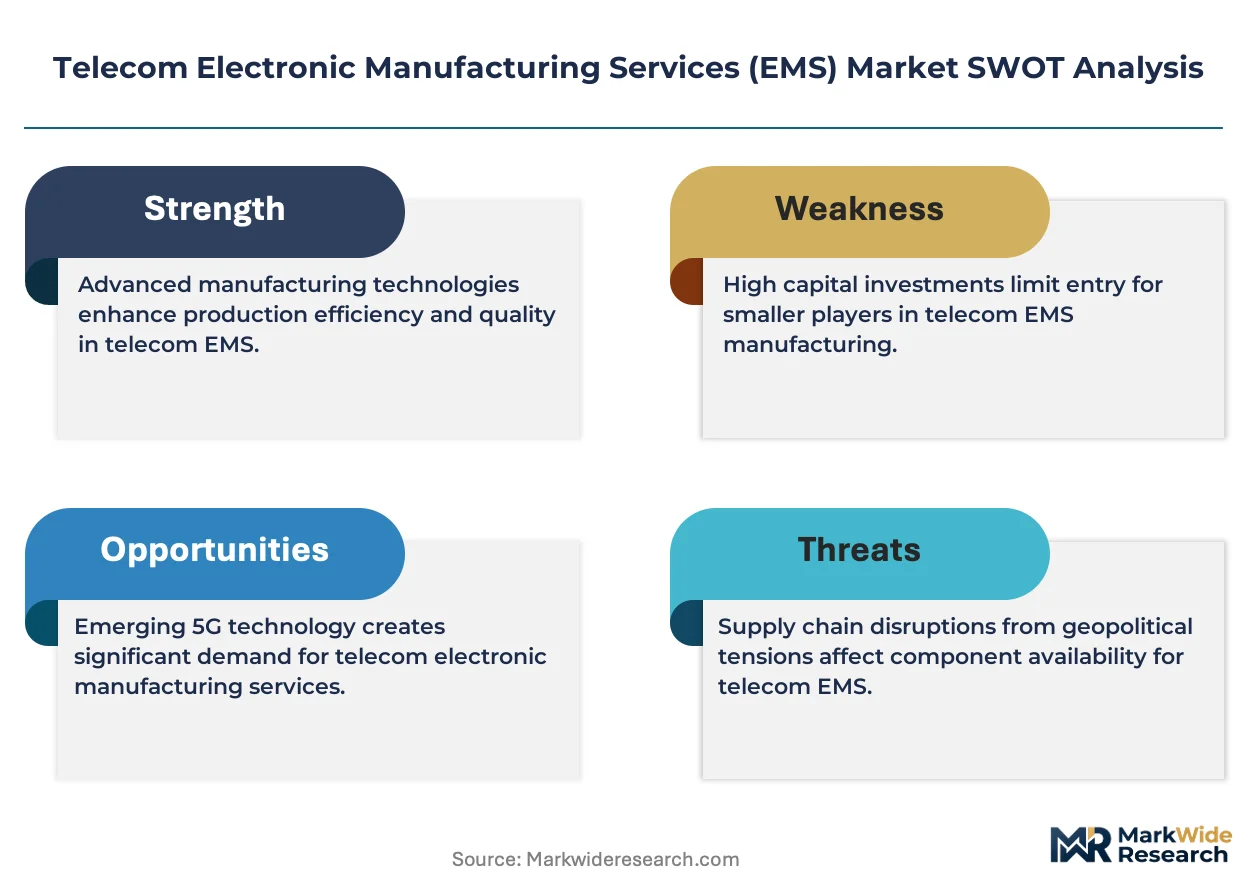
Signal integrity engineering and thermal management architectures are converging as 5G base station power densities escalate, forcing EMS providers to co-develop substrate and cooling solutions rather than assemble discrete components.
Halogen-free FR-4 PCB laminates with enhanced glass transition temperatures are migrating from niche automotive applications into telecom infrastructure assemblies. European OEMs are qualifying these materials ahead of anticipated REACH substance list expansions. The shift is compressing incumbent laminate suppliers' pricing power while elevating EMS partners with in-house material characterization laboratories.
REACH substance restrictions on persistent organic pollutants are forcing solder paste reformulations across European-bound production lines. EMS providers with captive metallurgy development capabilities are qualifying bismuth-silver-copper alloys that maintain wetting performance under reduced peak reflow temperatures. German and French telecom equipment manufacturers are prioritizing contract manufacturers with demonstrated RoHS compliance audit trails.
Carrier procurement departments are consolidating box-build and system-integration responsibilities under single-source EMS agreements that bundle design-for-manufacturing services. Tier-one vendors are displacing fragmented component sourcing with turnkey subsystem deliveries. This concentration is most visible in US and Japanese markets where open RAN interoperability certification costs favor scaled manufacturing partners with dedicated regulatory affairs teams.
Telecom Electronic Manufacturing Services (EMS) Market Segmentation
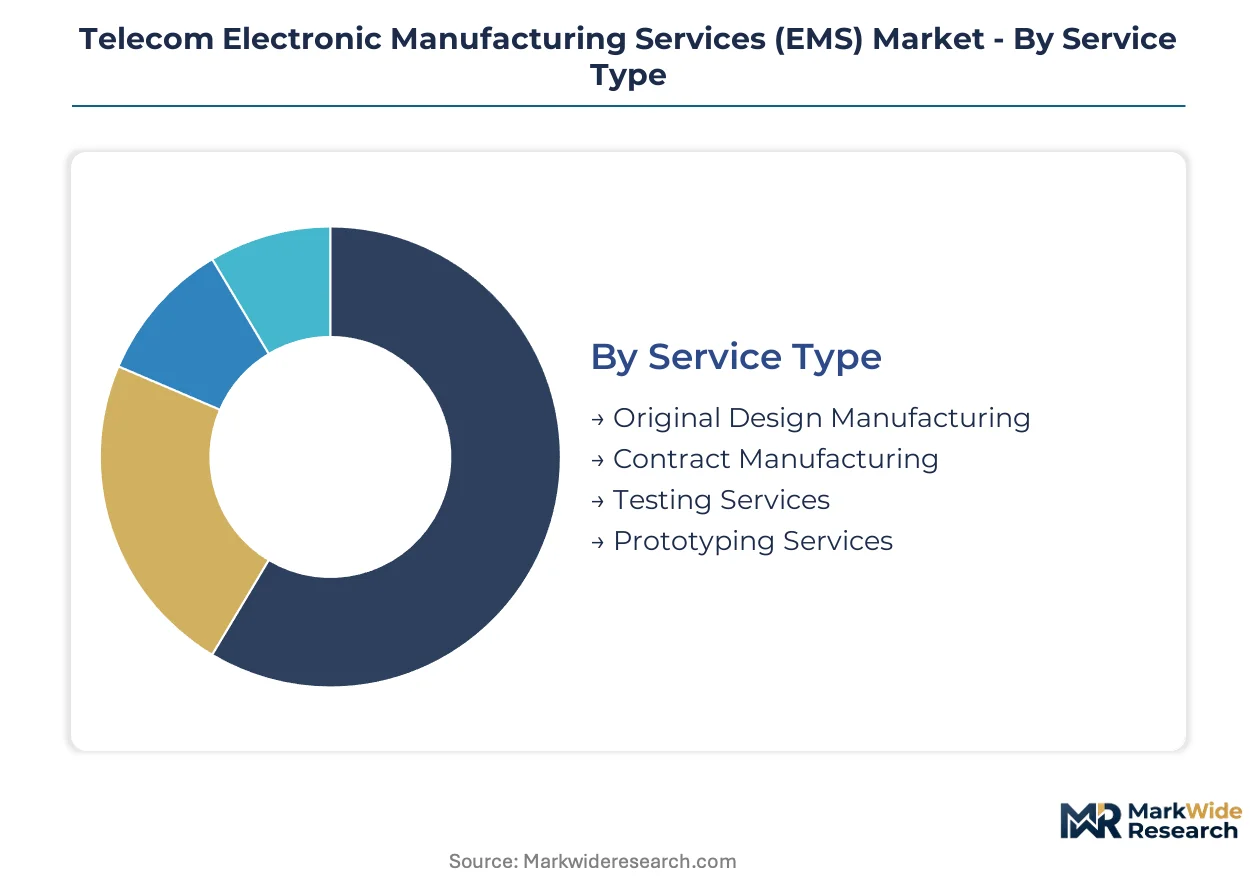
Segmentation in telecom EMS reveals divergent margin profiles across service tiers. After-sales service intensity varies dramatically by engagement model, with design-centric contracts demanding sustained engineering support versus transactional manufacturing relationships.
Service Type:
After-sales service intensity escalates from build-to-print assembly toward design-captive partnerships, reshaping contract structures and working capital requirements.
- Contract Manufacturing:Tier-one vendors consolidate box-build and system-integration under single-source agreements. Demand concentrates in Vietnam's Bac Ninh corridor as Foxconn and competitors relocate final-stage integration to capture tariff-advantaged export routes to US telecom equipment vendors.
- Original Design Manufacturing:EMS partners co-develop substrate and cooling solutions with OEM engineering teams, embedding RF testing competencies and thermal management expertise. German and South Korean telecom operators prioritize ODM partners with demonstrated mmWave signal integrity capabilities for massive MIMO antenna programs.
- Testing Services:FCC equipment authorization and CE marking under EU Radio Equipment Directive drive captive demand for accredited laboratory capacity.
- Prototyping Services:Rapid qualification cycles for open RAN hardware compress development timelines at North American and Japanese OEMs.
By volume, Contract Manufacturing leads. By growth pace, Original Design Manufacturing is ahead.
End User:
Customer procurement sophistication stratifies across direct network operators versus indirect hardware vendors, altering EMS qualification protocols.
- Telecom Operators:German, South Korean, and US carriers procure high-density 5G infrastructure directly, mandating mmWave testing competencies and REACH-compliant material traceability from EMS partners.
- Equipment Manufacturers:Tier-one vendors bundle design-for-manufacturing with box-build delivery, displacing fragmented component sourcing. Japanese and US markets show strongest concentration toward turnkey subsystem procurement.
- Aftermarket Providers:Lifecycle service revenue streams emerge from AI-driven predictive maintenance integration into base station power supplies.
- IoT Device Companies:Low-volume, high-mix requirements favor EMS partners with flexible SMT lines and rapid changeover capabilities.
Equipment Manufacturers command the largest contract values. Telecom Operators are climbing the fastest as direct procurement of open RAN hardware accelerates.
Technology:
RF performance specifications and thermal density requirements segment EMS capabilities by frequency band and compute architecture.
- 5G Technology:Massive MIMO antenna deployment and mmWave testing competencies define vendor selection. EU F-Gas Regulation and REACH compliance reshape material sourcing for PCB substrates and solder alloys in European-bound production.
- Edge Computing:Baseband processing units with integrated AI inference demand precision machining and cleanroom assembly for semiconductor packaging.
- LTE:Mature infrastructure refresh cycles sustain volume in Southeast Asian manufacturing corridors.
- Wireless Communication:Multi-protocol testing requirements favor EMS partners with captive RF laboratory investments.
LTE retains volume leadership through installed base maintenance. 5G Technology shows the steepest expansion trajectory as massive MIMO deployment accelerates.
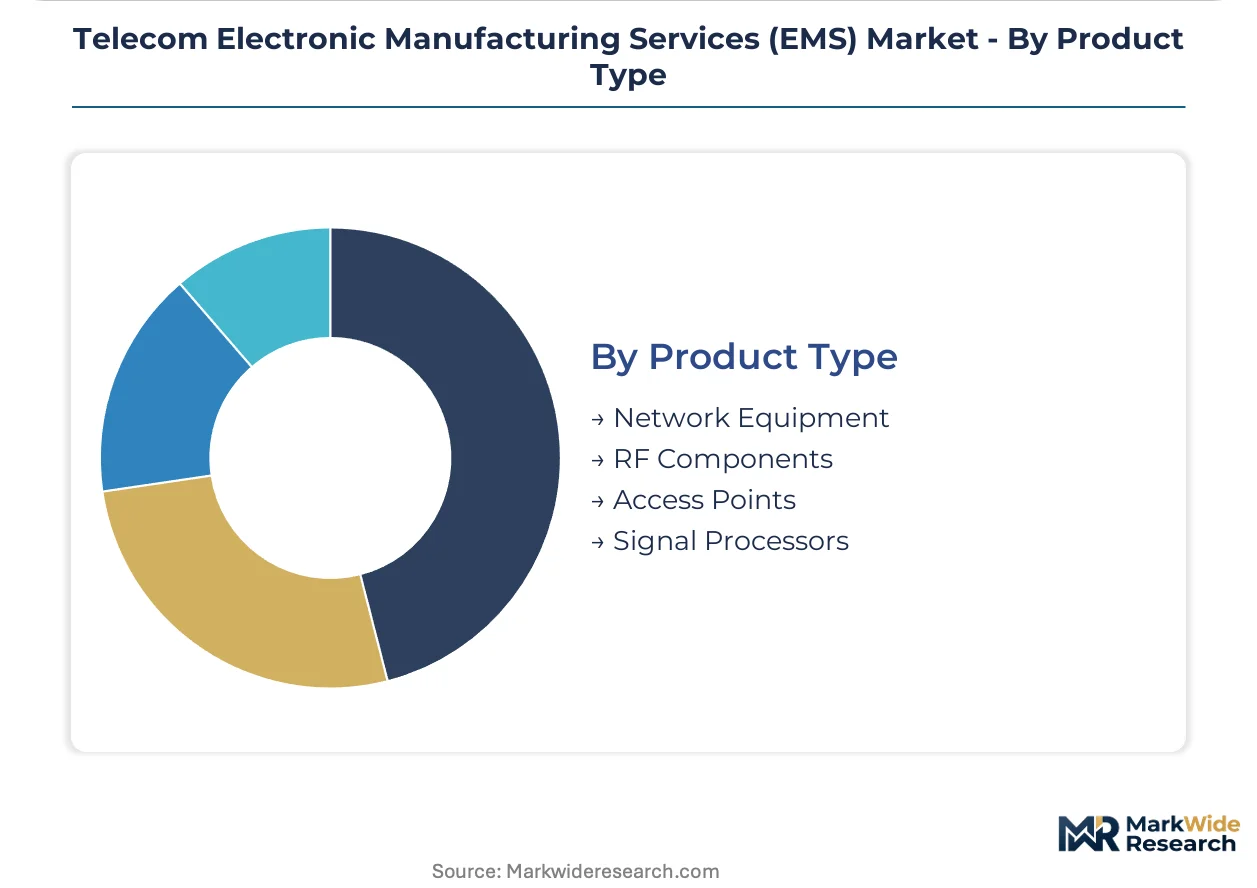
Product Type:
Physical form factors and signal processing complexity determine assembly automation levels and cleanroom classification requirements.
- Network Equipment:Base station enclosures and outdoor units require integrated thermal management with vapor chamber substrates. Concentrated rare earth processing for RF magnetics creates single-source vulnerability in Chinese refining operations.
- RF Components:Power amplifier assemblies with neodymium and dysprosium dependencies face supply concentration risk. ITAR-compliant cleanroom operations in North America capture defense-adjacent telecom infrastructure demand.
- Access Points:Indoor small-cell form factors prioritize compact SMT density and conformal coating processes.
- Signal Processors:High-layer-count PCBs with controlled impedance specifications demand specialized laminate qualification.
Network Equipment dominates volume through base station refresh cycles. RF Components are gaining share fastest as spectral efficiency requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturers cluster final-stage integration capacity in tariff-advantaged export corridors. Vietnam's northern industrial belt absorbs relocation momentum from legacy East Asian manufacturing zones. Regulatory compliance requirements in destination markets reshape material sourcing protocols across production networks.
United States
FCC equipment authorization mandates compress product launch timelines for open RAN radio units. The IRA domestic content provisions incentivize onshore assembly of base station power systems. Austin and Phoenix manufacturing corridors attract EMS investment for defense-adjacent telecom infrastructure with ITAR-compliant workflows.
Germany
Massive MIMO antenna deployment by Deutsche Telekom and Vodafone drives demand for mmWave testing competencies. REACH substance restrictions and EU F-Gas Regulation phase-downs accelerate halogen-free PCB laminate adoption. Bavaria's precision engineering cluster hosts specialized cleanroom operations serving European OEM qualification programs.
Vietnam
Tariff-advantaged export routes to North American telecom equipment vendors concentrate final-stage integration in Bac Ninh and Bac Giang provinces. The country's national industrial development frameworks prioritize electronics manufacturing foreign direct investment. Foxconn anchors this corridor through massive facility investments displacing higher-cost manufacturing zones.
South Korea
SK Telecom and KT Corporation procurement of high-density 5G infrastructure mandates REACH-compliant material traceability from EMS partners. The MFDS regulatory alignment with EU hazardous material standards shapes solder alloy qualification protocols. Gyeonggi-do semiconductor-adjacent manufacturing zones integrate RF component assembly with precision machining capabilities.
Japan
NTT Docomo and KDDI open RAN interoperability certification costs favor scaled manufacturing partners with dedicated regulatory affairs teams. METI technology roadmaps prioritize thermal management material development for base station outdoor enclosures. Nagoya industrial corridor hosts captive supply relationships for vapor chamber substrate production.
Telecom Electronic Manufacturing Services (EMS) Market Key Industry Players
Scale-driven integrators and specialized RF testing providers split the market into distinct competitive tiers. Tier-one vendors consolidate box-build and system-integration responsibilities under single-source agreements that bundle design-for-manufacturing services. Two archetypes dominate: full-service EMS with captive regulatory affairs teams, and niche specialists with mmWave laboratory investments. Competitive moves center on geographic relocation to tariff-advantaged corridors and backward integration into precision machining for thermal management components.
Among Taiwan-based fabricators, Foxconn and Wistron Corporation exemplify the scale-driven archetype through their facility investments in Vietnam's northern industrial belt. Jabil Inc occupies a position within the specialized tier, anchoring competitive positioning around vertical integration into RF testing workflows. These three entities represent the dominant strategic configurations: geographic arbitrage through relocation, and technical differentiation through testing competency capture.
| Leading Market Players |
|---|
| Sanmina Corporation |
| Wistron Corporation |
| Foxconn |
| Plexus Corp |
| Pegatron Corporation |
| Flex Ltd |
| Celestica Inc |
| Universal Scientific Industrial Co., Ltd |
| Jabil Inc |
| Others |
Cost & Logistics Intelligence
Bac Ninh province's industrial corridor absorbs final-stage integration capacity migrating from legacy East Asian manufacturing zones, compressing margin structures for contract manufacturers competing on tariff-advantaged export routes to North American telecom equipment vendors. REACH substance restrictions and RoHS hazardous material limits reshape input cost profiles across European-bound production lines, forcing metallurgy transitions that cascade into tiered service pricing.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across thermal management material categories, separating fluorinated gas-dependent legacy formulations from premium-qualified phase change alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—ITAR-compliant cleanroom operations command substantial premiums over transactional build-to-print assembly. Cost compression in standard-tier contract manufacturing intensifies as Foxconn and Wistron Corporation scale Vietnam capacity. Equipment manufacturers with consolidated box-build procurement show lowest price sensitivity, while IoT device companies with high-mix requirements exhibit acute cost responsiveness.
Supply Chain Analysis
Foxconn, Jabil Inc, and Celestica Inc anchor contract-manufacturing concentration across Vietnam, Mexico, and Malaysia corridors. Neodymium and dysprosium for RF magnetics draws from Chinese refining operations, while halogen-free PCB laminates hinge on Japanese and Taiwanese substrate suppliers. Single-source vulnerability concentrates in rare earth processing for base station power amplifier assemblies. Distribution runs through tier-one vendor direct agreements with telecom operators and equipment manufacturers, displacing fragmented component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interoperability certification creates platform-economics inflection, rewarding EMS providers with captive regulatory affairs teams and multi-vendor qualification capabilities.
For Market Incumbents: Harden defensive positioning through backward integration into precision machining for thermal management components and captive RF testing laboratory accreditation. Consolidate box-build and system-integration responsibilities under single-source agreements to offset margin pressure from Vietnam-based geographic arbitrage. Prioritize ITAR-compliant cleanroom capacity additions in Austin and Phoenix corridors. For New Entrants and Emerging Players: Build out mmWave signal integrity testing capabilities to capture white-space demand from German and South Korean massive MIMO antenna programs. Target aftermarket lifecycle services through AI-driven predictive maintenance integration into base station power supplies. Lead with design-for-manufacturing partnerships that embed engineering teams within open RAN hardware qualification timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized RF testing providers with demonstrated RoHS compliance audit trails over scale-driven geographic arbitrage plays. Long-term viability rests on regulatory certification moats rather than transient tariff advantages. Monitor open RAN interoperability certification timelines as inflection indicator for OEM qualification criteria shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ITAR-Compliant Cleanroom Expansion | Captures defense-adjacent telecom infrastructure demand in US manufacturing corridors. |
| Halogen-Free PCB Laminate Qualification | Secures European market access ahead of anticipated REACH substance list expansions. |
| mmWave Testing Laboratory Accreditation | Enables massive MIMO antenna procurement from Deutsche Telekom and SK Telecom. |
| AI-Driven Predictive Maintenance Integration | Generates recurring lifecycle revenue from base station power supply sensor networks. |
| Vietnam Final-Stage Integration Relocation | Captures tariff-advantaged export routes to North American telecom equipment vendors. |
Research Approach
Desk research of regulatory filings, customs trade databases, and EMS provider capacity disclosures preceded structured interviews with RF test engineering directors, telecom operator procurement leads, and thermal materials R&D heads. Primary fieldwork with contract manufacturing executives and OEM qualification managers combined with secondary validation through FCC equipment authorization records and EU Radio Equipment Directive compliance databases. Bottom-up capacity assessments triangulated against top-down demand projections from carrier capex disclosures.
Assumptions held fixed include REACH substance restriction trajectories and Vietnam tariff-advantaged export route durability, while open RAN interoperability certification timelines and rare earth supply concentration were modeled as scenario variables across the projection horizon. Segmentation dimensions encompassed service type, end user archetype, technology generation, and product form factor. CAGRs derived from production volume buildups and average selling price trajectories, with thermal management material scarcity and mmWave engineering talent availability as industry-specific forecast inputs.
Sensitivities concentrate around FCC equipment authorization timeline compression and EU F-Gas Regulation phase-down acceleration. Forecasts reflect documented assumptions regarding carrier procurement consolidation and geographic relocation momentum. Quarterly review of open RAN hardware qualification program announcements and rare earth export quota adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Repeaters Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Global Time Sensitive Networking Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
5G BTS Antenna Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
Telecom Equipment Market