
 DWDM Transceiver Market | 2026-2036
DWDM Transceiver Market Size, Share, and Industry Trends Forecast 2026-2036
DWDM Transceiver Market Insights
Chinese module assembly capacity is rebalancing toward higher-speed coherent platforms as domestic fabs expand 400G+ output. Coherent Corp. leverages vertical integration across indium phosphide and silicon photonics to sustain margin on advanced tunable transceivers. Lumentum anchors North American supply through its specialized pump laser and modulator portfolio for long-haul systems. Broadcom competes on merchant silicon economics, controlling the DSP and PAM4 chipset layers that define pluggable module performance.
A DWDM transceiver is a fiber-optic component that multiplexes multiple wavelengths onto a single fiber using dense wavelength division multiplexing, typically operating across the C-band and L-band with channel spacing of 100 GHz or 50 GHz. It serves the core function of expanding fiber capacity without laying new physical infrastructure, enabling terabit-scale throughput across telecom and cloud networks. Pluggable form factors now lead unit shipments as data centers prioritize swap-out flexibility and reduced power draw per gigabit. Coherent technology captures the fastest expansion trajectory, driven by 400ZR and 800ZR standards penetration in metro and cloud interconnects. Fixed-wavelength modules remain a mature margin pool within access-tier metro rings where upgrade cycles stretch longer.
FCC broadband infrastructure programs and NIST optical measurement standards shape US deployment timelines and interoperability requirements, while China's MIIT enforces domestic GB standards and dual carbon compliance on module power efficiency. The EU AI Act and CSRD disclosure rules are beginning to filter into procurement criteria for European telecom and cloud operators. Stakeholders must monitor standardization battles between OIF, IEEE, and ITU-T on next-generation coherent interfaces, as these specifications will determine which module architectures achieve multi-vendor interoperability and volume scale.
Market Dynamics
Hyperscale data center operators are compressing transceiver replacement cycles to sustain AI training cluster bandwidth density, forcing module suppliers to accelerate coherent DSP roadmaps and pluggable form factor power efficiency gains.
Growth Catalysts
- 400G/800G coherent standards penetration:Metro and cloud interconnect architectures are absorbing ZR/ZR+ pluggable modules as default building blocks for terabit-scale fiber capacity expansion without new cable lays.
- China's dual carbon compliance mandates:MIIT power efficiency standards are accelerating domestic module assembly rebalancing toward silicon photonics platforms that reduce thermal load per gigabit.
- Virginia fiber corridor concentration:Northern Virginia's hyperscale campus density is generating concentrated procurement volumes that validate multi-source coherent module interoperability at scale.
Market Restraints
- Indium phosphide substrate supply concentration:Tunable laser and high-speed modulator production remains captive to limited specialty wafer foundry capacity, creating input cost volatility for coherent transceiver tiers.
- China MIIT domestic content requirements:GB standards enforcement is fragmenting module certification pathways, forcing non-Chinese suppliers to maintain parallel assembly lines or absorb compliance overhead.
- Copper direct-attach cable substitution:Short-reach data center interconnects below 3 meters are shifting to passive copper assemblies that eliminate optical transceiver content entirely.
Strategic Opportunities
- India telecom infrastructure buildout:TRAI fiberization mandates and 5G backhaul requirements are opening procurement windows for coherent 100G/400G modules in previously underpenetrated metro rings.
- Linear drive pluggable (LPO) architecture convergence:DSP-free module designs combining silicon photonics with linear TIAs are emerging as power-optimized alternatives for latency-sensitive AI clusters.
- EU CSRD supply chain disclosure rules:European cloud operators are embedding carbon footprint and circularity criteria into transceiver procurement specifications, favoring suppliers with verified lifecycle data.
Industry Challenges
- Coherent DSP firmware talent scarcity:Module vendors face acute competition for signal processing engineers capable of optimizing 7nm/5nm ASIC implementations under strict thermal envelopes.
- OIF/IEEE/ITU-T standardization timeline drift:Competing interoperability specifications for next-generation 800G coherent interfaces are delaying multi-vendor qualification cycles and freezing procurement commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DWDM Transceiver Market |
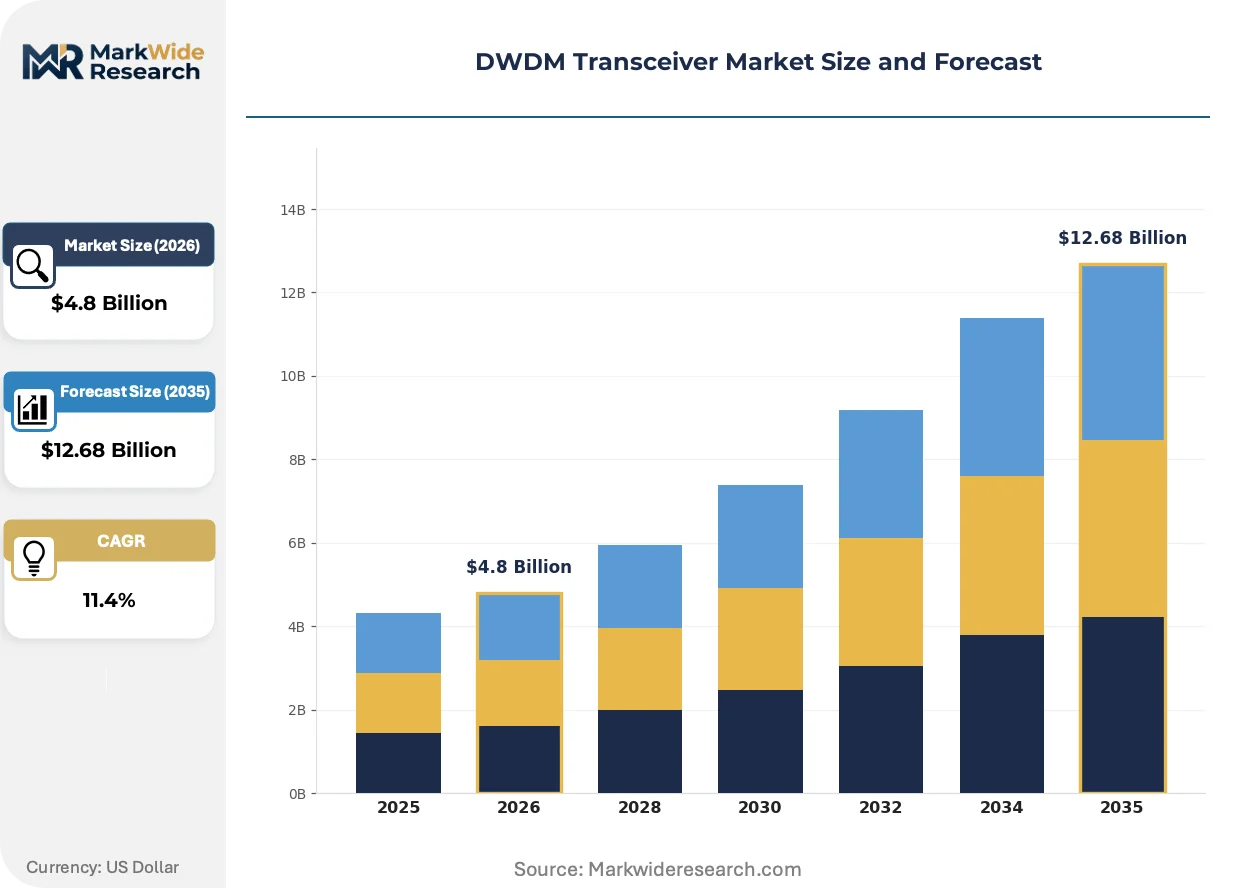
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Tunable, Coherent, Pluggable Technology: ACR, OTN, Ethernet, SONET End User: Telecom Providers, Data Centers, Enterprises, Research Institutions Application: Long Haul, Metro, Cloud Computing, Video Streaming |
| Companies Covered | Coherent Corp., Lumentum, Broadcom, Accelink Technologies, Innolight, Cisco Systems, Sumitomo Electric Industries, Huawei Technologies, Ciena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DWDM Transceiver Market Trends and Innovations
Silicon photonics fabrication maturation is collapsing the cost gap with indium phosphide for coherent transceivers, while regulatory pressure on data center energy intensity is redefining module power efficiency as a primary procurement filter.
Silicon photonics co-packaging with switch ASICs is expanding into hyperscale data center spine architectures as the dominant path to 51.2T switch radix without front-panel power constraints. Amazon Web Services and Microsoft Azure procurement teams are qualifying co-packaged optics (CPO) prototypes for 2026 deployment tranches. This integration architecture is expanding into pluggable module substitution by collapsing electrical reach and eliminating retimer power overhead.
China's MIIT GB standards enforcement is mandating domestic module power efficiency thresholds that exceed IEEE 802.3 specifications by 15-20 percent, forcing global suppliers to redesign thermal management subsystems for China-specific SKUs. Domestic fabs in Wuhan and Shenzhen are capturing assembly volume as foreign vendors recalibrate compliance costs. The policy divergence is fragmenting global module portfolios into parallel certification tracks with incompatible test harnesses.
Hyperscale operators are consolidating transceiver procurement around direct supplier relationships that bypass traditional distribution channels, compressing channel margins and shifting technical support burden to module vendors. Meta and Google procurement teams now require field-replaceable unit (FRU) traceability and failure analysis turnaround commitments that distributors cannot fulfill. The channel restructuring is most visible in Oregon's Hillsboro campus zone and Virginia's Loudoun County corridor where single-site annual volumes exceed 500,000 units.
DWDM Transceiver Market Segmentation
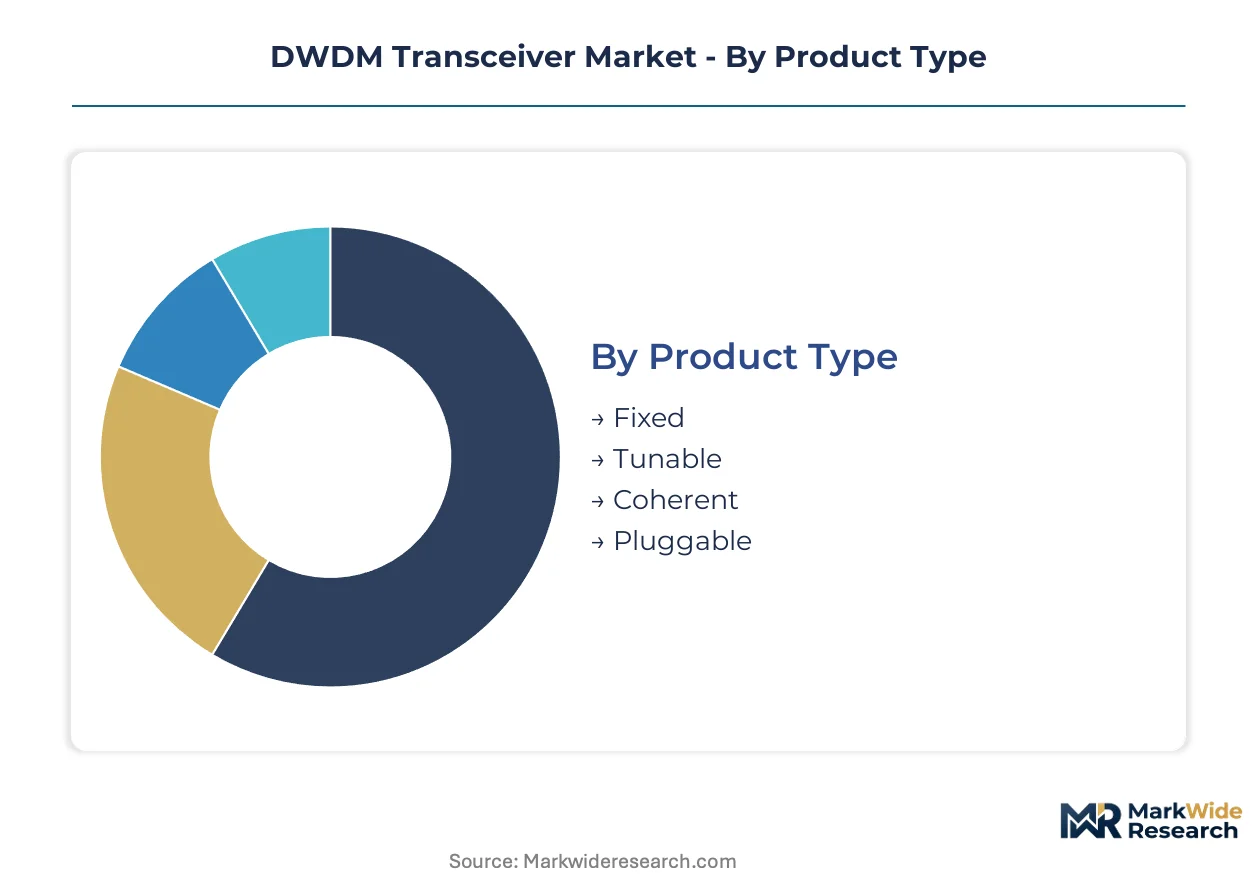
DWDM transceiver procurement patterns diverge sharply across deployment contexts, with coherent pluggable modules commanding premium positioning in hyperscale data centers while fixed-wavelength variants sustain volume economics in legacy metro rings. Understanding these segment boundaries enables suppliers to calibrate R&D roadmaps and inventory positioning against divergent replacement cycles and margin structures.
Product Type:
Supply concentration in indium phosphide laser fabrication and silicon photonics foundry capacity shapes competitive positioning across form factor tiers, with captive DSP design capabilities determining which architectures achieve multi-source interoperability.
- Fixed:Single-wavelength modules with predetermined channel assignments dominate access-tier metro deployments where upgrade cycles extend beyond seven years. Demand concentrates in China's provincial carrier networks under MIIT domestic content mandates, constraining foreign supplier participation despite mature cost structures.
- Tunable:Wavelength-agile transceivers integrating micro-electromechanical systems or thermal tuning enable dynamic wavelength provisioning across C-band and L-band ranges. Procurement in Virginia's Loudoun County hyperscale corridor validates multi-vendor interoperability for inventory pooling, with operators requiring sub-50ms switching latency for live traffic reconfiguration.
- Coherent:DSP-enabled modules supporting 400G/800G modulation formats with advanced forward error correction.
- Pluggable:Hot-swappable form factors including QSFP-DD and OSFP that reduce data center operational complexity.
Today's leader: Coherent. Tomorrow's challenger: Pluggable.
Technology:
Protocol-layer differentiation determines which transceiver architectures align with carrier transport modernization timelines versus cloud-native Ethernet deployments, fragmenting supplier specialization across incompatible certification tracks.
- ACR:Adaptive clock recovery interfaces synchronize timing across asynchronous network boundaries without external reference distribution. Deployment concentrates in European incumbent carrier backhaul networks where ETSI timing standards mandate holdover performance during GNSS outages.
- OTN:Optical Transport Network framing preserves TDM hierarchy integrity across wavelength-division multiplexed infrastructure. China's three major carriers specify OTN-capable coherent modules for provincial backbone rings under MIIT network modernization directives, creating dedicated procurement volumes distinct from cloud operator Ethernet preferences.
- Ethernet:Native packet-optical interfaces supporting 100G/400G/800G line rates with PAM4 modulation.
- SONET:Legacy synchronous optical networking interfaces sustaining T1/T3 circuit emulation in federal and utility networks.
OTN commands carrier infrastructure budgets. Ethernet climbs fastest in cloud interconnects.
End User:
Customer-type concentration in hyperscale procurement offices versus distributed carrier sourcing functions is redefining channel economics and technical support models across the supplier base.
- Telecom Providers:Incumbent and competitive carriers deploying coherent modules across regional and national fiber footprints. Verizon and AT&T procurement teams in the United States specify 400ZR+ modules for metro edge consolidation, with qualification cycles extending eighteen months due to interoperability testing requirements.
- Data Centers:Hyperscale and colocation operators optimizing transceiver density per rack watt. Meta's Hillsboro campus zone in Oregon generates concentrated annual volumes exceeding half a million units, with direct supplier relationships displacing traditional distribution channels and compressing channel margins to single-digit percentages.
- Enterprises:Financial and healthcare institutions deploying private fiber interconnects for data sovereignty compliance.
- Research Institutions:National laboratories and university networks requiring specialized coherent receivers for optical sensing and quantum communication experiments.
Data centers drive volume scaling. Telecom providers sustain margin premiums through extended qualification barriers.
Application:
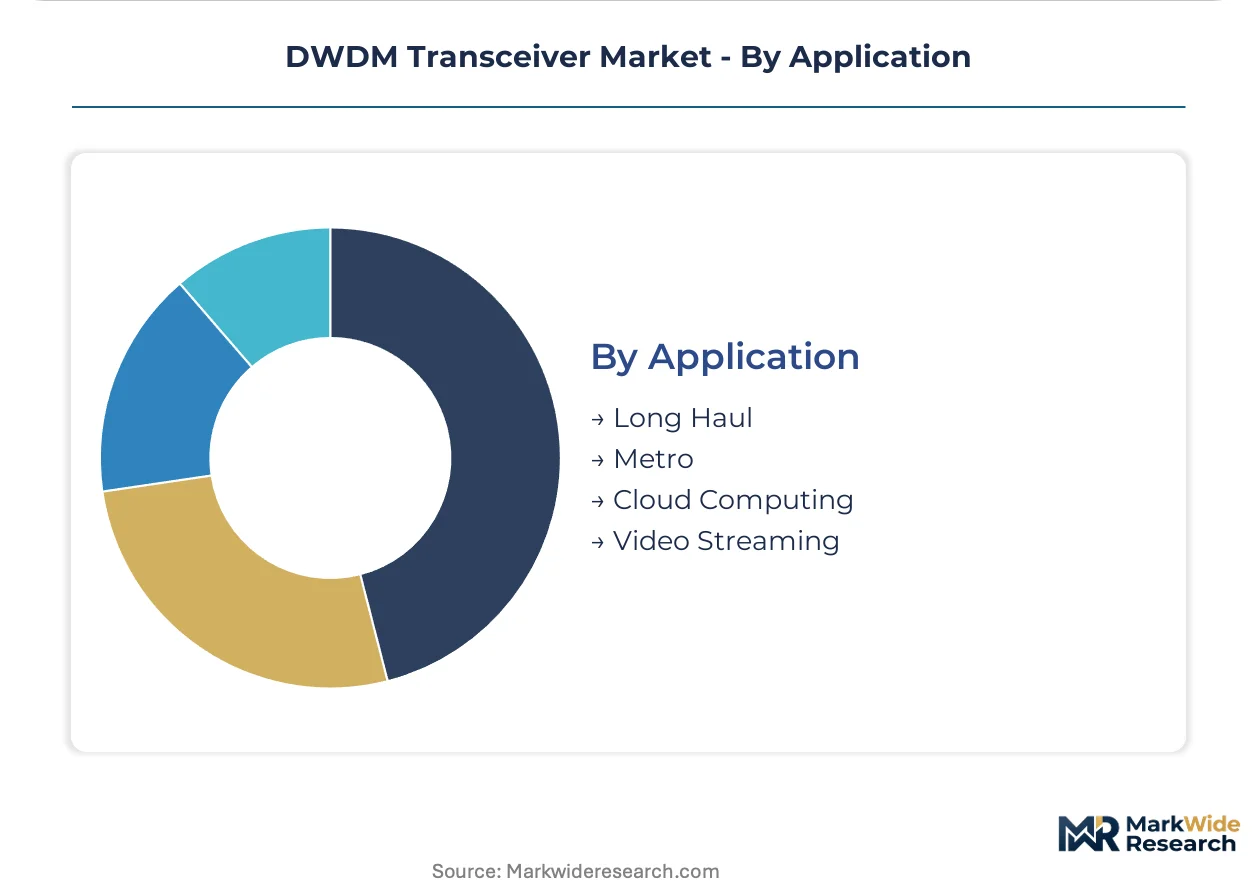
Distance-reach requirements and latency sensitivity create distinct module specification clusters, with cloud computing applications demanding power-optimized pluggable formats incompatible with long-haul amplification architectures.
- Long Haul:Amplified spans exceeding 1000 kilometers requiring high-output power and advanced dispersion compensation. Submarine cable operators including consortiums landing in Virginia Beach specify ultra-long-reach coherent modules with probabilistic constellation shaping, with Fujitsu and NEC maintaining dedicated product lines for transoceanic power budgets.
- Metro:Regional interconnects between 80-400 kilometers connecting carrier central offices and data center campuses. China's Wuhan fiber corridor deployment of 400G coherent modules under MIIT 5G backhaul standards validates domestic silicon photonics assembly capacity, with Yangtze Optical Fibre and Accelink capturing procurement share through GB standards compliance.
- Cloud Computing:Data center spine and leaf architectures requiring sub-10 kilometer reach with minimal power draw.
- Video Streaming:Content delivery network edge caches demanding burst-tolerant throughput for live event traffic.
Metro rings absorb the steepest expansion trajectory. Cloud computing threatens to displace metro volume as co-packaged optics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing DWDM transceiver assembly capacity toward jurisdictions with aligned carbon-efficiency mandates and domestic content incentives, compressing margins for suppliers maintaining parallel certification tracks.
United States
FCC broadband infrastructure programs and hyperscale data center expansion are absorbing coherent 400G/800G modules at scale. NIST optical measurement standards enforce interoperability testing that extends qualification cycles. Northern Virginia's Loudoun County fiber corridor concentrates procurement volumes exceeding 500,000 units annually at single campus zones.
China
MIIT 5G backhaul standards and national dual carbon goals are accelerating 400G/800G coherent module deployment across provincial carrier networks. GB standards enforcement fragments global module portfolios into parallel certification tracks with incompatible test harnesses. Wuhan and Shenzhen domestic fabs are capturing assembly volume through compliance-aligned silicon photonics output.
Germany
ETSI timing standards and EU CSRD supply chain disclosure rules are embedding carbon footprint criteria into transceiver procurement specifications for incumbent carrier networks. REACH and RoHS compliance frameworks constrain material inputs for pluggable module designs. Frankfurt's carrier-neutral data center cluster validates multi-vendor coherent interoperability for financial sector interconnects.
Japan
METI industrial policy and JIS standards are sustaining domestic demand for ultra-long-reach coherent modules in submarine cable landing stations. Probabilistic constellation shaping technologies for transoceanic power budgets concentrate procurement with specialized product lines. Tokyo-Osaka metro fiber rings absorb ZR/ZR+ pluggable volumes for cloud interconnect modernization.
India
TRAI fiberization mandates and 5G backhaul requirements are opening procurement windows for coherent 100G/400G modules in previously underpenetrated metro rings. Department of Telecommunications spectrum policy is accelerating carrier infrastructure buildout. Mumbai and Bangalore data center corridors are qualifying domestic assembly partnerships for pluggable module volumes.
DWDM Transceiver Market Competitive Landscape
United States producers anchor one tier; Chinese specialists hold assembly-scale positions; Japanese and European incumbents retain long-haul technology segments. The vendor base stratifies across captive DSP design capabilities, silicon photonics foundry access, and indium phosphide laser fabrication. Three archetypes dominate: vertically integrated optical component houses, merchant silicon DSP suppliers, and contract assembly specialists with GB standards compliance. Competitive moves center on co-packaged optics integration partnerships and China-specific SKU thermal management redesigns.
Among North American optical component houses, Coherent Corp. and Lumentum occupy positions spanning indium phosphide and silicon photonics platforms. Broadcom represents the merchant silicon archetype with DSP and PAM4 chipset layer control. Chinese specialists Accelink Technologies and Innolight exemplify domestic standards compliance and scaled assembly capacity. These five entities collectively illustrate the geographic and technological fault lines determining multi-vendor interoperability and procurement access.
| Leading Market Players |
|---|
| Coherent Corp. |
| Lumentum |
| Broadcom |
| Accelink Technologies |
| Innolight |
| Cisco Systems |
| Sumitomo Electric Industries |
| Huawei Technologies |
| Ciena |
| Others |
Pricing and Supply Chain Analysis
Silicon photonics fabrication maturation is collapsing the cost gap with indium phosphide for coherent transceivers while simultaneously redistributing assembly capacity toward China and Southeast Asia. This dual shift compresses margins for legacy indium phosphide suppliers and fragments global portfolios into parallel certification tracks.
Pricing Analysis
Distributor margins have compressed to single-digit percentages as hyperscale operators consolidate procurement around direct supplier relationships. Three-tier pricing structure across premium coherent, standard pluggable, and economy fixed-wavelength levels reflects DSP complexity and thermal management requirements. Price erosion runs through the pluggable tier as merchant silicon DSPs commoditize 400G/800G performance. Data center operators exhibit lowest price sensitivity given total cost of ownership framing, while provincial carriers in China face acute budget constraints under MIIT domestic content mandates.
Supply Chain Analysis
Refurbishment flows for field-replaceable units are expanding as Meta and Google mandate traceability and rapid failure analysis turnaround. Indium phosphide substrate supply concentrates in Japan and the United States, while silicon photonics foundry capacity clusters in Taiwan and China. DSP and PAM4 chipset production rests on TSMC and Samsung advanced node access. Single-source vulnerability sits with specialty wafer foundry capacity for tunable lasers. Distribution runs through direct OEM contracts that bypass traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DWDM transceiver demand compounds steadily as AI training clusters force continuous bandwidth upgrades without new fiber lays. Hyperscale procurement concentration and coherent technology transitions create durable margin pools for positioned suppliers.
For Market Incumbents: Cement multi-vendor interoperability leadership by accelerating OIF/IEEE qualification cycles before standardization timeline drift freezes procurement commitments. Deepen captive DSP design capabilities to defend against merchant silicon commoditization. Prioritize thermal management subsystem redesigns for China-specific SKUs to maintain MIIT compliance access without fragmenting global portfolios.
For New Entrants and Emerging Players: Launch via direct hyperscale procurement relationships in India's TRAI-mandated fiberization buildout, where coherent 100G/400G penetration remains underdeveloped. Target linear drive pluggable architectures for latency-sensitive AI clusters as a DSP-free alternative. Pursue EU CSRD-aligned carbon footprint verification to capture European cloud operator procurement windows.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract assembly specialists with GB standards compliance and scaled silicon photonics capacity. Long-term viability centers on co-packaged optics integration partnerships with switch ASIC vendors. Monitor OIF/IEEE/ITU-T standardization convergence as the critical inflection signal for multi-vendor interoperability scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Expansion | Accelink and domestic Wuhan fabs capture MIIT-compliant assembly volume from foreign vendors. |
| Co-Packaged Optics Integration | AWS and Microsoft Azure qualification programs validate 51.2T switch radix architectures. |
| Linear Drive Pluggable Development | DSP-free designs address power constraints in Virginia's Loudoun County hyperscale corridors. |
| China-Specific SKU Thermal Redesign | GB standards enforcement mandates 15-20% power efficiency thresholds above IEEE specifications. |
| Direct Hyperscale Procurement Relationships | Meta's Hillsboro campus zone exceeds 500,000 annual units with channel margin compression. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with optical component procurement managers, DSP firmware engineers, carrier network planning directors, and hyperscale data center infrastructure leads with secondary validation. Regulatory filings from FCC, MIIT, and ETSI anchored policy impact assessment. SEC 10-K disclosures, customs trade data, and OIF/IEEE standards documentation provided supply-side triangulation. Bottom-up module shipment tracking and top-down carrier capex analysis were reconciled across the projection horizon.
Segment-weighting approaches modeled product type, technology protocol, end user archetype, application reach, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from installed base replacement cycles, coherent standards penetration curves, and hyperscale data center buildout trajectories. Forecast inputs incorporated AI training cluster bandwidth density requirements, MIIT dual carbon compliance thresholds, and OIF/IEEE/ITU-T standardization timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under indium phosphide supply disruption or accelerated copper direct-attach cable substitution below three meters. Forecasts reflect documented assumptions on coherent DSP roadmaps and pluggable form factor power efficiency gains. Practitioners should monitor OIF/IEEE interoperability qualification milestones and MIIT GB standards enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Global FPGA in Telecom Sector Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Set-Top Box Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Global Volte Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
LTE IoT Devices Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Point-To-Point Antenna Market
Telecom Hardware
Subscriber Identity Module (SIM) Market