
 Telecom Equipment Market | 2026-2036
Telecom Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Equipment Market Intelligence
Direct procurement relationships between mobile network operators and original equipment manufacturers is reshaping traditional distributor roles in the Telecom Equipment Market. Cisco Systems leverages its enterprise routing portfolio to sustain channel control across North American carrier accounts. Huawei Technologies anchors massive MIMO deployments across Asia-Pacific markets despite trade restriction complexity. Nokia Corporation differentiates through optical fiber specialization and submarine cable system leadership.
Telecom equipment encompasses the physical and virtualized infrastructure enabling signal transmission, switching, routing, and network management across wired and wireless architectures, with optical fiber systems achieving latency below one millisecond per kilometer and base stations operating across sub-6 GHz and millimeter-wave spectrum bands. This infrastructure serves mobile network operators, enterprise systems, and public safety networks requiring continuous connectivity. Switches and routers constitute the mature revenue backbone where margin pools remain deepest, while base stations and optical fiber represent the fastest-expanding categories driven by 5G densification and fiber-to-the-home rollouts. SDN and NFV technologies are displacing proprietary hardware stacks in data center and carrier environments.
The FCC governs spectrum allocation and equipment authorization in the United States, while the European Telecommunications Standards Institute coordinates CE marking and interoperability frameworks across EU member states, and India's Telecommunication Engineering Centre enforces mandatory testing for network security compliance. These regulatory layers shape product development cycles, certification costs, and market entry timelines for vendors. Stakeholders must monitor spectrum auction schedules, open interface mandates, and cybersecurity certification requirements as determinants of competitive positioning.
Market Dynamics
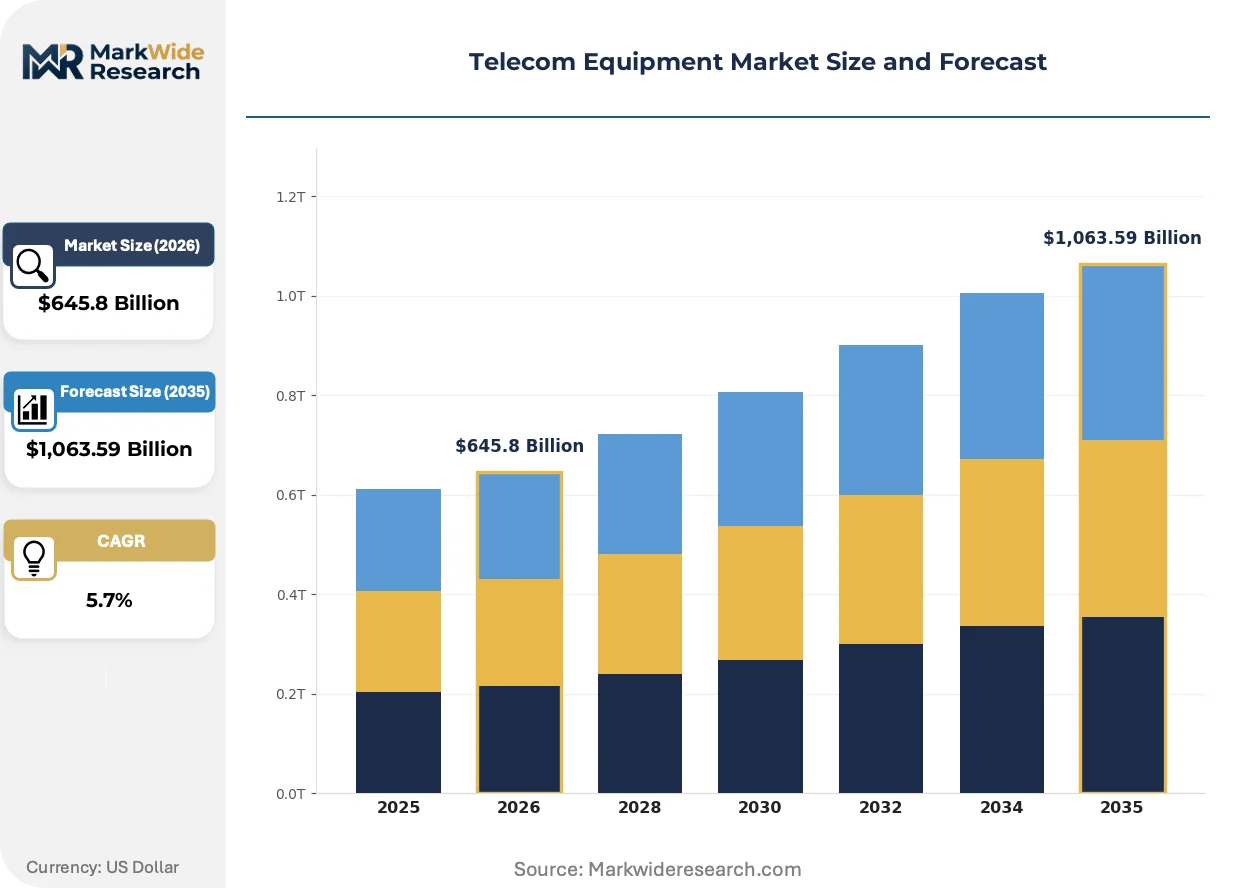
5G network densification mandates from the FCC and European regulators are forcing equipment vendors to requalify hardware for open interface compatibility, compressing product development cycles while fragmenting procurement authority across mobile network operators and systems integrators.
Growth Catalysts
- Open RAN mandates:The FCC and European regulators now require disaggregated radio access network architectures. This policy shift forces incumbent vendors to open proprietary interfaces.
- India's PLI scheme:The Department of Telecommunications offers production-linked incentives for domestic 5G equipment manufacturing. Foreign vendors are establishing local assembly operations to capture subsidy eligibility.
- Millimeter-wave spectrum deployment:Base station manufacturers are scaling small cell production for dense urban coverage. This technology addresses capacity constraints in high-traffic zones.
Market Restraints
- Semiconductor supply concentration:Advanced baseband processors and RF front-end modules depend on Taiwan and South Korean foundry capacity. Geographic concentration creates single-point vulnerability for equipment lead times.
- Trade restriction complexity:US export controls on Chinese technology suppliers fragment component sourcing. Vendors must maintain dual supply chains for restricted and unrestricted markets.
- Copper and optical fiber input volatility:Submarine cable and terrestrial fiber deployments face raw material price swings. Margin pressure intensifies for capital-intensive infrastructure projects.
Strategic Opportunities
- Rural 5G penetration gaps:India's BharatNet program and US Rural Digital Opportunity Fund target unserved territories. Equipment vendors can capture first-mover advantage in low-competition zones.
- Private network enterprise demand:Manufacturing campuses and mining operations are deploying standalone 5G networks. This application diversifies revenue beyond traditional mobile network operators.
- Network function virtualization convergence:SDN and edge computing integration enables software-defined radio platforms. This technology pairing reduces hardware dependency while accelerating service deployment.
Industry Challenges
- Open RAN integration complexity:Multi-vendor interoperability testing extends deployment timelines. Systems integrators bear responsibility for fault isolation across disaggregated components.
- Millimeter-wave RF engineering scarcity:Specialized talent for beamforming antenna design remains concentrated among legacy vendors. Recruitment competition intensifies as open architecture expands supplier pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Equipment Market |
| Market Size in 2026 | $645.8 Billion |
| Market Size in 2035 | $1,063.59 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Base Stations, Optical Fiber, Modems, Antennas Technology: 5G, 4G LTE, IoT Connectivity, MIMO, SDN, NFV Application: Mobile Network Operators, Satellite Communication, Broadcasting, Enterprise Networks, Public Safety Networks, Intelligent Transportation Systems End User: Carrier Service Providers, Internet Service Providers, Government Agencies, Content Providers, Data Centers, Managed Service Providers |
| Companies Covered | Cisco Systems, Samsung Electronics, Huawei Technologies, Juniper Networks, Ciena Corporation, Nokia Corporation, ZTE Corporation, Motorola Solutions, Telefonaktiebolaget LM Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Equipment Market Strategic Shifts & Innovations
Virtualization architectures are collapsing the boundary between hardware-centric and software-defined network infrastructure, enabling new vendor entry while compressing margins for proprietary equipment incumbents.
Radio access network functions are virtualizing through cloud-native baseband processing platforms. Mobile network operators in Germany and Japan are trialing containerized distributed unit deployments. This architecture is virtualizing capital expenditure models by shifting compute loads to commercial off-the-shelf servers.
The European Telecommunications Standards Institute has accelerated open interface specifications under its O-RAN alliance framework. Equipment vendors must now certify interoperability across disaggregated radio, distributed unit, and centralized unit components. Base station manufacturers serving EU member states are restructuring R&D budgets toward software development.
Enterprise buyers are consolidating procurement authority through direct original equipment manufacturer relationships. Traditional distributor margins are compressing as Vodafone and Verizon establish vendor-managed inventory agreements. This pattern is most visible in North American carrier accounts where channel disintermediation accelerates.
Telecom Equipment Market Segmentation
Telecom equipment segmentation reveals divergent margin structures and procurement patterns across hardware categories, network technologies, and customer archetypes. Equipment vendors calibrate R&D allocation and certification investments based on segment-specific growth velocities and regulatory exposure.
Product Type:
Maturity gradients separate established switching infrastructure from emerging open radio access network hardware, with each tier commanding distinct customer relationships and replacement cycles.
- Switches:Layer 2 and Layer 3 switching platforms process packet forwarding at terabit-scale throughput for enterprise and carrier core networks. Data center operators in the United States and Germany drive refresh demand as east-west traffic patterns intensify. Migration to 400G and 800G port densities accelerates hardware replacement timelines.
- Base Stations:Macro cells and small cells transmit radio signals across sub-6 GHz and millimeter-wave spectrum bands. India's Department of Telecommunications auctions and the FCC's rural 5G mandates concentrate deployment demand. Open RAN disaggregation requirements reshape vendor qualification pathways for radio unit suppliers.
- Routers:Edge and core routing platforms direct traffic across autonomous system boundaries using BGP and segment routing protocols.
- Optical Fiber:Single-mode and multimode fiber systems achieve sub-millisecond latency per kilometer for terrestrial and submarine deployments.
- Modems:CPE devices terminate broadband connections across DSL, cable, and fiber access technologies.
- Antennas:Passive and active antenna arrays enable beamforming for massive MIMO configurations.
Switches retain volume leadership; base stations hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive 5G infrastructure from software-defined overlays that monetize existing hardware investments through virtualization layers.
- 5G:New radio interfaces operate across FR1 (sub-6 GHz) and FR2 (millimeter-wave) spectrum with network slicing capabilities. Mobile network operators in Japan and South Korea densify urban small cell grids while India's BharatNet program extends coverage to rural constituencies. Standalone core deployments enable ultra-reliable low-latency communication for industrial automation.
- SDN:Software-defined networking abstracts control plane functions from proprietary hardware into centralized controllers. Financial services firms and cloud providers in Singapore and the United Kingdom deploy SDN fabrics to automate provisioning and reduce operational expenditure. OpenFlow and P4 programming languages standardize switch behavior across multi-vendor environments.
- 4G LTE:Existing radio access networks sustain coverage in areas awaiting 5G spectrum allocation.
- IoT Connectivity:NB-IoT and LTE-M radio technologies support low-power wide-area machine-to-machine communication.
- MIMO:Multiple-input multiple-output antenna configurations multiply spectral efficiency through spatial multiplexing.
- NFV:Network function virtualization converts proprietary network appliances into software instances running on commodity servers.
5G infrastructure commands the highest capital intensity per deployment site; SDN solutions are expanding most quickly within enterprise data center environments.
Application:
Customer type fragmentation distributes procurement authority across regulated carriers, sovereign entities, and private enterprises with divergent technical specifications and contract structures.
- Mobile Network Operators:Licensed spectrum holders deploy radio access networks and core infrastructure to serve consumer and enterprise subscribers. Verizon and Vodafone establish direct OEM relationships that disintermediate traditional distribution channels. Capital expenditure cycles concentrate in spectrum auction follow-on periods.
- Enterprise Networks:Campus and branch infrastructure supports private 5G, Wi-Fi 6E, and software-defined WAN deployments. Manufacturing facilities in Germany and mining operations in Australia deploy standalone 5G networks for deterministic latency requirements. IT departments consolidate vendor relationships through single-source agreements.
- Satellite Communication:Geostationary and low-earth orbit constellations provide backhaul and direct-to-device connectivity.
- Broadcasting:Terrestrial and satellite distribution systems transmit audio-visual content to consumer receivers.
- Public Safety Networks:Mission-critical communications infrastructure serves first responder agencies.
- Intelligent Transportation Systems:Vehicle-to-everything roadside units enable autonomous navigation and traffic optimization.
Mobile network operators retain volume leadership; enterprise networks hold the steepest expansion curve.
End User:
Geographic procurement concentration clusters demand in markets with active spectrum policy and infrastructure subsidy programs.
- Carrier Service Providers:Tier-1 and tier-2 telecommunications operators own licensed spectrum and physical network infrastructure. The FCC's Rural Digital Opportunity Fund and India's PLI scheme direct procurement toward domestic manufacturing incentives. Long-term vendor-managed inventory agreements reshape working capital requirements.
- Data Centers:Hyperscale cloud operators and colocation providers deploy spine-leaf architectures and optical interconnects. Facilities in Northern Virginia and Frankfurt am Main scale fiber count per rack to support AI training cluster bandwidth demands. Power density constraints drive interest to co-packaged optics and linear pluggable transceivers.
- Internet Service Providers:Fixed broadband operators deploy access network equipment for residential and commercial subscribers.
- Government Agencies:Sovereign entities procure secure communications infrastructure for defense and civilian applications.
- Content Providers:Streaming and gaming platforms invest in edge caching and interconnection infrastructure.
- Managed Service Providers:Outsourced IT operators procure equipment on behalf of mid-market enterprise clients.
Carrier service providers retain volume leadership; data centers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States carrier contracts while procurement leverage shifts toward Indian domestic manufacturing incentives. Equipment vendors calibrate margin structures against these divergent regulatory environments. The regional landscape fragments across spectrum policy regimes and infrastructure subsidy programs.
United States
The FCC's Rural Digital Opportunity Fund directs $20 billion toward unserved territories, compelling base station manufacturers to requalify hardware for open RAN compatibility. Verizon and AT&T consolidate procurement authority through direct OEM relationships that bypass traditional distribution channels. Northern Virginia data center clusters scale optical fiber deployment to support AI training infrastructure bandwidth demands.
India
The Department of Telecommunications accelerates 5G spectrum auctions while PLI scheme subsidies attract foreign vendors to establish local assembly operations. BharatNet program targets 600,000 village-level connectivity nodes, creating concentrated demand for cost-optimized radio equipment. Tamil Nadu and Karnataka host emerging manufacturing corridors where Ericsson and Nokia operate captive production facilities.
Germany
The European Telecommunications Standards Institute enforces O-RAN alliance interoperability specifications that force incumbent vendors to open proprietary interfaces. Deutsche Telekom trials containerized distributed unit deployments across industrial zones in Bavaria and North Rhine-Westphalia. Automotive manufacturers in Stuttgart and Munich deploy private 5G networks for deterministic factory automation.
China
MIIT spectrum allocation policies prioritize millimeter-wave band trials in dense urban corridors. Huawei Technologies anchors massive MIMO deployments across Asia-Pacific markets despite US export control complexity. Shenzhen and Beijing manufacturing clusters sustain vertical integration from semiconductor packaging through base station final assembly.
Japan
METI coordinates 5G network densification mandates with NTT Docomo and KDDI accelerating small cell grid deployment in Tokyo and Osaka metropolitan zones. SoftBank trials cloud-native baseband processing platforms using containerized architectures. Nagoya industrial corridor enterprises procure standalone 5G networks for robotics integration and predictive maintenance applications.
Telecom Equipment Market Key Industry Players
Integrated infrastructure conglomerates and specialized radio access network vendors split the market into contrasting margin tiers. The vendor base concentrates around five dominant holding companies that control proprietary patent portfolios and certification pathways. Three strategic archetypes emerge: end-to-end solution providers, component specialists, and systems integrators. Competitive moves center on open interface certification investments and geographic manufacturing footprint expansion.
Among North American networking specialists, Cisco Systems and Juniper Networks occupy positions within enterprise and carrier routing segments where channel control remains contested. Nokia Corporation and Telefonaktiebolaget LM Ericsson exemplify European end-to-end infrastructure providers restructuring R&D budgets toward software development under O-RAN mandates. These four anchors represent divergent responses to virtualization pressure.
| Leading Market Players |
|---|
| Cisco Systems |
| Samsung Electronics |
| Huawei Technologies |
| Juniper Networks |
| Ciena Corporation |
| Nokia Corporation |
| ZTE Corporation |
| Motorola Solutions |
| Telefonaktiebolaget LM Ericsson |
| Others |
Cost & Logistics Intelligence
Trans-Pacific fiber-optic cable freight corridors from Shanghai to Los Angeles transmit base station components and optical modules at rates that fluctuate with semiconductor wafer output from Taiwan and South Korea, compressing margins for vendors serving price-sensitive Indian carriers while enabling premium pricing for expedited delivery to US Rural Digital Opportunity Fund deployments.
Pricing Analysis
The customization-premium spread separates standard catalog pricing for Layer 2 switches from configured-to-order base stations with Open RAN interoperability certification. Project-based contracting dominates 5G infrastructure, with price differentiation hinging on FCC open interface compliance and volume scale commitments from tier-1 mobile network operators. Cost compression in millimeter-wave small cells is intensifying because of foundry capacity constraints for RF front-end modules. Indian carrier service providers exhibit highest price sensitivity; US data center operators show lowest sensitivity due to AI training cluster bandwidth requirements.
Supply Chain Analysis
Foxconn, Jabil, and Flex hold contract manufacturing capacity for base station final assembly across Taiwan, Mexico, and Vietnam. Raw material dependencies center on gallium nitride substrates for power amplifiers, single-mode fiber preforms from Corning and YOFC, and advanced baseband processors fabricated in Taiwan. Single-source vulnerability concentrates in TSMC's 7nm and 5nm foundry nodes for 5G modems. Distribution runs through direct OEM relationships that disintermediate traditional telecom distributors, with vendor-managed inventory agreements at Verizon and Vodafone reshaping working capital structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase driven by India's PLI scheme subsidy disbursements triggering capital expenditure acceleration from foreign vendors establishing domestic assembly operations.
For Market Incumbents: Pre-empt Open RAN certification fragmentation by accelerating software development budgets toward O-RAN alliance interoperability specifications before European Telecommunications Standards Institute mandates harden. Anchor backward integration into gallium nitride substrate sourcing to defend margin position against RF component cost volatility. Lock in multi-year vendor-managed inventory agreements with tier-1 carriers to forestall channel disintermediation.
For New Entrants and Emerging Players: Establish a beachhead in private 5G networks for German automotive manufacturing campuses, where deterministic latency requirements and limited incumbent presence create penetrable white space. Target India's BharatNet rural connectivity nodes with cost-optimized radio units qualifying for PLI scheme subsidies. Pursue systems integrator partnerships rather than direct carrier sales to bypass lengthy mobile network operator qualification cycles.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate parent companies restructuring away from proprietary hardware toward software-defined architectures. Long-term viability favors component specialists with captive optical fiber or RF engineering capabilities rather than end-to-end generalists facing margin compression. Monitor FCC spectrum auction schedules and India's Department of Telecommunications subsidy disbursement timelines as inflection indicators for capital expenditure cycle turns.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Certification Investment | Qualifies hardware for FCC and European Telecommunications Standards Institute procurement mandates across disaggregated architectures. |
| Domestic Manufacturing Footprint Expansion | Captures India's PLI scheme subsidies while reducing exposure to US-China trade restriction complexity. |
| Cloud-Native Baseband Platform Development | Enables NTT Docomo and Deutsche Telekom containerized distributed unit deployments shifting capex to commercial servers. |
| Private 5G Systems Integrator Partnership | Accelerates enterprise network penetration in German automotive and Japanese robotics corridors. |
| Optical Fiber Capacity Buildout | Serves Northern Virginia and Frankfurt data center clusters scaling fiber count for AI training infrastructure. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, FCC equipment authorization databases, ETSI interoperability specifications, and carrier capital expenditure disclosures. Primary interviews engaged network engineering directors at tier-1 mobile network operators, procurement leads at hyperscale data center operators, regulatory affairs specialists at base station manufacturers, and supply chain managers at contract electronics manufacturers. Bottom-up unit shipment estimates triangulate against top-down addressable market calculations across product type, technology, and end user segments.
Forecast inputs incorporate spectrum auction schedules, PLI scheme subsidy disbursement timelines, Open RAN mandate implementation phases, and data center power density trajectories across the projection horizon. Segmentation dimensions modeled include product type maturity gradients, 5G standalone versus non-standalone deployment modes, and geographic regulatory cluster differentiation. CAGRs derive from logistic adoption curve fitting against infrastructure replacement cycles and virtualization technology penetration rates. Foundry capacity constraints and raw material price volatility are stress-tested as scenario variables.
Stress conditions across Taiwan semiconductor supply disruption, India PLI scheme eligibility changes, and European O-RAN interoperability timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding carrier capital expenditure cyclicality and enterprise private network adoption velocity. Quarterly review of FCC Rural Digital Opportunity Fund disbursement rates, India's Department of Telecommunications auction announcements, and ETSI specification release cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Voice Communication Equipment Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Global Time Sensitive Networking Market
Telecom Hardware
Set-Top Box Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Industrial Transceivers Market
Telecom Hardware
Commercial Antennas Market