
 Global Time Sensitive Networking Market | 2026-2036
Global Time Sensitive Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Time Sensitive Networking Market Foresight
The EU Green Deal's industrial decarbonization mandates is realigning factory network upgrade priorities toward deterministic Ethernet architectures. Siemens leverages its native industrial automation footprint to anchor TSN switch deployments across European manufacturing basins. Cisco Systems competes through IT-OT convergence platforms that extend enterprise networking expertise into operational technology environments. NXP Semiconductors specializes in automotive-grade TSN controllers that dominate next-generation vehicle gateway designs.
Time Sensitive Networking constitutes an IEEE 802.1 standards suite enabling deterministic data transmission over standard Ethernet through time-aware scheduling, frame preemption, and precise clock synchronization with sub-microsecond accuracy. Its primary purpose is to unify critical control traffic and best-effort data on shared infrastructure without isolation hardware. Industrial Automation applications currently lead installed TSN volume as legacy fieldbus replacement accelerates, while Automotive represents the fastest-expanding segment driven by zonal E/E architectures and sensor fusion bandwidth requirements. TSN Switches capture concentrated margin pools owing to ASIC design complexity and certification barriers that limit viable supplier counts.
The IEEE 802.1 working group, ETSI, and the IEC collaborate to harmonize TSN profiles with 5G ultra-reliable low-latency communication specifications, directly shaping product roadmaps and multi-vendor interoperability testing obligations. The US FCC's spectrum allocation decisions for private 5G networks indirectly condition TSN-wireless hybrid deployment economics by determining factory floor wireless backhaul viability. Stakeholders must monitor whether IEEE 802.1 standard revision cycles outpace automotive OEM platform lock-in timelines, as misalignment risks strand mid-decade infrastructure investments.
Market Dynamics
The convergence of IEEE 802.1 TSN standards with 5G ultra-reliable low-latency communication protocols is compressing deployment timelines across industrial and automotive networks, forcing infrastructure decisions before full multi-vendor interoperability maturation.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:Germany's Industrie 4.0 manufacturing corridors are accelerating deterministic Ethernet upgrades to replace legacy fieldbus systems and enable energy-optimized production scheduling.
- Zonal E/E architectures in automotive:Sensor fusion bandwidth requirements for autonomous vehicle networks in Japan are pulling automotive-grade TSN controller demand ahead of traditional gateway replacement cycles.
- Time-aware scheduling protocols:IEEE 802.1Qbv frame preemption capabilities are enabling unified critical control and best-effort traffic on shared infrastructure without hardware isolation.
Market Restraints
- ASIC design complexity barriers:TSN switch semiconductor development requires sub-microsecond timing precision that concentrates viable supplier pools among captive silicon designers.
- Certification timeline friction:IEC 62443 industrial cybersecurity certification for TSN devices extends product qualification periods beyond typical automotive OEM platform lock-in windows.
- Ethernet PHY component concentration:Specialized timing components for automotive-grade TSN controllers face supply concentration risk in East Asian semiconductor fabrication capacity.
Strategic Opportunities
- Private 5G-TSN hybrid backhaul:US FCC spectrum allocation decisions for factory-floor wireless are creating viable deployment economics for untethered deterministic control applications.
- Medical device connectivity:IEC 60601-1-8 alarm system integration with TSN-enabled surgical networks represents an underpenetrated vertical beyond industrial automation.
- ETSI-IEC harmonization tailwinds:Standard profile convergence between 5G URLLC and IEEE 802.1 is reducing multi-vendor integration testing obligations for system integrators.
Industry Challenges
- Embedded systems timing engineering scarcity:Sub-microsecond clock synchronization implementation requires specialized expertise that outpaces current university pipeline output.
- Legacy fieldbus migration complexity:Brownfield industrial sites face protocol translation layer development costs that strain OT-IT convergence project budgets.
- Standard revision cycle misalignment:IEEE 802.1 working group publication schedules risk stranding mid-decade infrastructure investments against locked automotive platform timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Time Sensitive Networking Market |
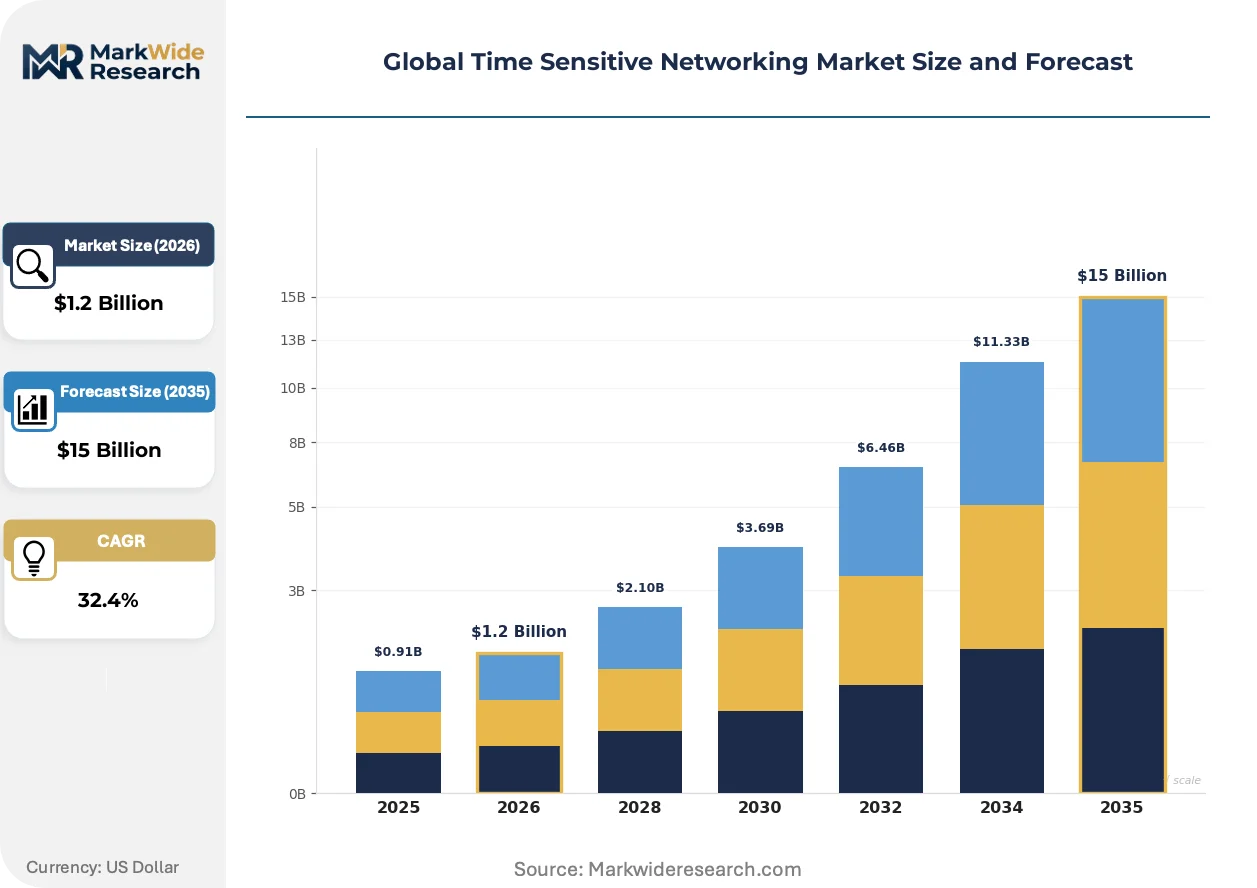
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $15 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Industrial Automation, Automotive, Smart Grids, Audio/Video Broadcasting Technology: Ethernet, Wireless, IP, TSN Switches End User: Manufacturers, Telecommunications, Energy Providers, Media Companies Service Type: Consulting, Integration, Maintenance, Support |
| Companies Covered | Texas Instruments Incorporated, NXP Semiconductors, Siemens, Broadcom, Cisco Systems, Microchip Technology, Analog Devices, Belden, Marvell Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Time Sensitive Networking Market Shifts & Advancements
Deterministic networking architectures are fragmenting into application-specific profiles that trade universal interoperability for vertical-optimized performance, compressing vendor consolidation timelines while expanding qualified supplier entry points.
TSN-enabled edge computing nodes are modularizing factory automation control hierarchies by distributing time-critical processing from centralized PLCs to field-level devices. German automotive suppliers are deploying these architectures fastest, collapsing traditional three-tier automation pyramids into flatter, latency-optimized mesh topologies that reduce cabling weight and simplify maintenance access.
Japan's METI has issued technical guidelines harmonizing domestic precision automation standards with IEC/IEEE 60802 TSN profiles for industrial automation. This regulatory alignment accelerates domestic vendor certification reciprocity, compressing product approval timelines from eighteen months to under nine months for compliant switch and controller designs targeting export markets.
Buyer procurement patterns in European manufacturing are pivoting from component-centric purchasing toward system-level performance contracting. Siemens and Cisco channel partners report growing preference for guaranteed latency-SLA agreements over discrete hardware transactions, with German automotive OEMs leading this shift by bundling TSN infrastructure into comprehensive digital transformation programs rather than standalone network refresh cycles.
Global Time Sensitive Networking Market Segmentation
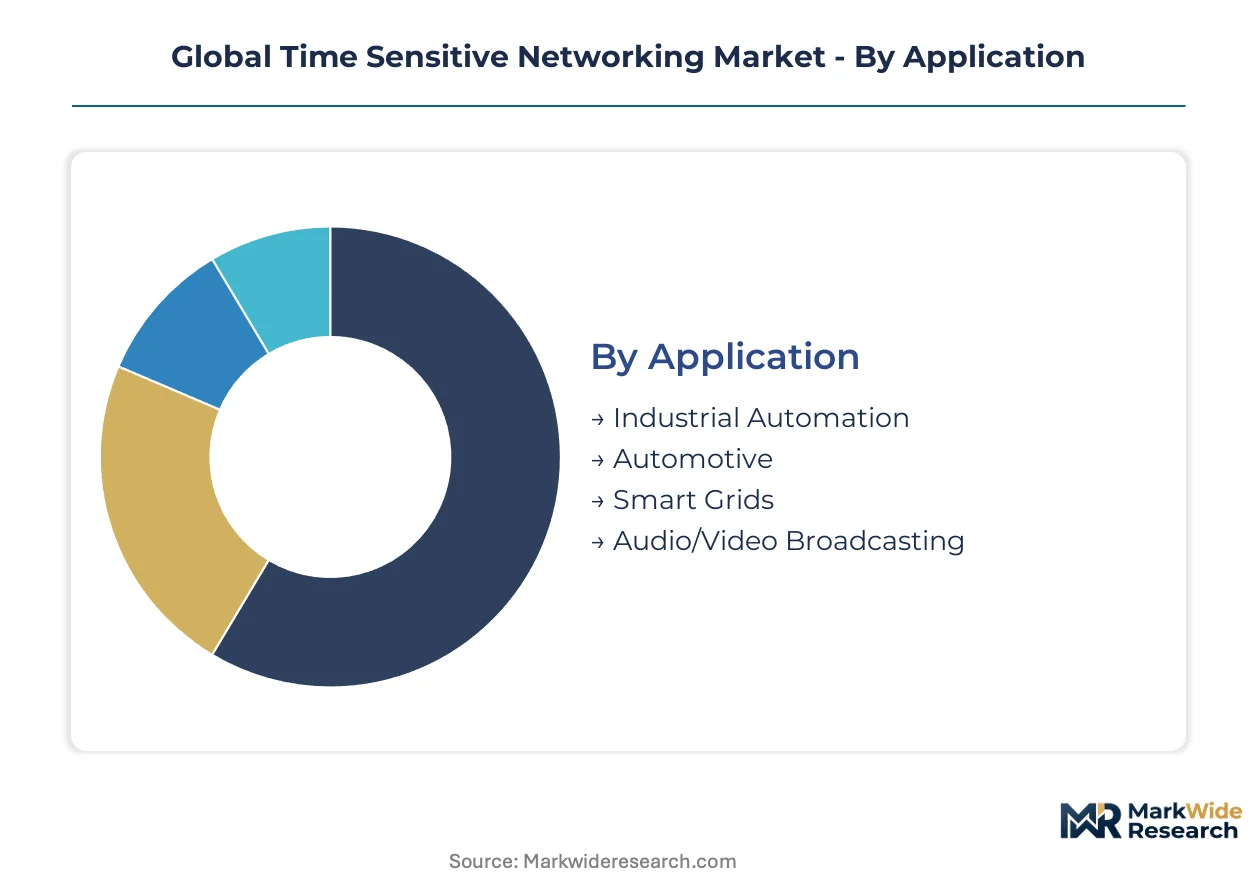
TSN market segmentation reveals how infrastructure replacement cycles concentrate revenue across distinct technology layers and buyer profiles. Upgrade timelines vary dramatically by vertical, with industrial automation demanding fieldbus displacement while automotive pushes zonal architecture transitions.
Application:
Replacement-cycle urgency differs sharply across verticals, with legacy system obsolescence forcing some sectors toward immediate deployment while others await platform maturation.
- Industrial Automation:Fieldbus-to-Ethernet migration dominates current installed base conversion, driven by Germany's Industrie 4.0 corridors requiring deterministic control for energy-optimized production scheduling. Brownfield protocol translation complexity strains OT-IT convergence budgets across European manufacturing basins.
- Automotive:Zonal E/E architectures and sensor fusion bandwidth requirements are compressing traditional gateway replacement cycles, with Japanese OEMs pulling automotive-grade controller demand ahead of semiconductor supply stabilization.
- Smart Grids:Utility substation automation leverages IEEE 1588 precision timing for distributed energy resource synchronization.
- Audio/Video Broadcasting:Professional media infrastructure adopts SMPTE ST 2110 convergence with TSN timing for studio IP migration.
Industrial Automation sits at the top of the volume ranking, with Automotive climbing the fastest.
Technology:
Cost-tier differentiation separates commodity connectivity from precision-engineered timing infrastructure, with ASIC complexity creating supplier concentration at the premium end.
- Ethernet:Standard IEEE 802.3 physical layer with 802.1Q time-aware scheduling extensions enables unified critical and best-effort traffic without hardware isolation, anchoring volume deployments in German precision manufacturing.
- TSN Switches:ASIC designs achieving sub-microsecond timing precision capture concentrated margin pools, with certification barriers limiting viable supplier counts to captive silicon designers serving automotive OEM platform lock-ins.
- Wireless:5G URLLC hybrid backhaul extends deterministic control to untethered factory-floor applications pending US FCC spectrum allocation clarity.
- IP:Layer-3 routing integration with 802.1Qcc stream reservation supports multi-subnet industrial deployments.
Ethernet dominates current infrastructure attach rates, while TSN Switches command the steepest expansion trajectory in value terms.
End User:
Customer-type maturity separates specification-driven procurement from outcome-based performance contracting, with German automotive OEMs pioneering bundled digital transformation programs.
- Manufacturers:Discrete and process automation buyers pivot from component-centric purchasing toward guaranteed latency-SLA agreements, with Siemens and Cisco channel partners reporting preference shifts across European production networks.
- Energy Providers:Grid modernization mandates drive substation automation timing requirements for renewable integration.
- Telecommunications:Private 5G network operators evaluate TSN-wireless hybrid economics for industrial verticals.
- Media Companies:Broadcast infrastructure migration to IP-based production workflows creates specialized timing demands.
Manufacturers anchor current demand concentration, with Energy Providers gaining share fastest as grid decentralization accelerates.
Service Type:
Supply-side capability scarcity concentrates margin in specialized integration and maintenance functions requiring sub-microsecond timing engineering expertise.
- Integration:Multi-vendor interoperability testing and legacy fieldbus translation layer development command premium pricing, with system integrators facing compressed timelines from IEEE 802.1-5G convergence.
- Consulting:Network architecture design for brownfield OT-IT convergence projects.
- Maintenance:Clock synchronization calibration and timing drift remediation services.
- Support:Vendor-certified technical assistance for certified device deployments.
Integration services capture the highest value per engagement, with Maintenance expanding most quickly as installed base scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems timing engineers concentrate in Germany's industrial automation corridors and Japan's precision manufacturing clusters, anchoring TSN deployment expertise in these geographies.
United States
Private 5G network operators and automotive OEMs drive TSN controller demand for zonal E/E architectures and factory-floor wireless backhaul. The FCC's spectrum allocation decisions for industrial wireless directly condition hybrid deployment economics. Detroit's automotive engineering base and Austin's semiconductor design clusters anchor domestic controller development.
Germany
Industrie 4.0 manufacturing corridors require deterministic Ethernet to replace legacy fieldbus systems and enable energy-optimized production scheduling. The EU Green Deal's industrial decarbonization mandates accelerate factory network upgrade timelines. Siemens anchors TSN switch deployments across Bavarian and North Rhine-Westphalian production basins.
Japan
Automotive OEMs compress traditional gateway replacement cycles to meet sensor fusion bandwidth requirements for autonomous vehicle networks. METI's technical guidelines harmonize domestic precision automation standards with IEC/IEEE 60802 TSN profiles. Nagoya's automotive supplier ecosystem and Tokyo's electronics design houses dominate automotive-grade controller qualification.
China
Industrial automation modernization and smart grid substation deployment pull TSN infrastructure demand across manufacturing and energy verticals. MIIT's industrial internet development policies promote deterministic Ethernet adoption in advanced manufacturing zones. The Yangtze River Delta's electronics manufacturing clusters and Pearl River Delta's automation equipment suppliers drive domestic switch and controller production scaling.
South Korea
Semiconductor fabrication automation and automotive electronics manufacturing generate concentrated demand for sub-microsecond timing precision in production networks. The country's national industrial technology regulator promotes smart factory standards alignment with IEEE 802.1 specifications. Seoul Capital Area's memory fabrication complexes and Busan-Ulsan's automotive component suppliers anchor regional TSN integration service demand.
Global Time Sensitive Networking Market Competitive Landscape
Capital-heavy semiconductor foundries compete with asset-light fabless designers for automotive-grade TSN controller sockets, creating a tiered structure where captive silicon capabilities separate premium-tier suppliers from commodity connectivity vendors. The market concentrates around ASIC designers achieving IEC 62443 cybersecurity certification and systems integrators managing multi-vendor interoperability testing. Three archetypes dominate: captive semiconductor divisions serving locked OEM platforms, independent silicon suppliers licensing timing IP, and IT-OT convergence platforms extending enterprise networking into operational technology environments. Competitive moves center on strategic partnerships for 5G-TSN hybrid certification and geographic expansion into Japan's compressed automotive qualification timelines.
Among semiconductor specialists, NXP Semiconductors and Texas Instruments Incorporated exemplify the captive-design archetype for automotive timing controllers, while Cisco Systems occupies a position bridging enterprise networking expertise with industrial automation deployment requirements. These three anchors represent distinct competitive vectors: automotive-grade silicon qualification, precision timing ASIC development, and IT-OT convergence platform integration.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Siemens |
| Broadcom |
| Cisco Systems |
| Microchip Technology |
| Analog Devices |
| Belden |
| Marvell Technology |
| Others |
Supply & Pricing Matrix
The EU Green Deal's industrial decarbonization mandates gate qualified supply and premium-tier pricing access, as factories seeking deterministic Ethernet infrastructure must source from IEC 62443-certified vendors whose cybersecurity qualification timelines compress available supplier pools. German automotive OEMs and Japanese precision manufacturers absorb pricing premiums for automotive-grade TSN controllers while brownfield sites face protocol translation costs that strain OT-IT convergence budgets.
Pricing Analysis
Bundled digital transformation programs separate from unbundled component transactions, with German automotive OEMs pioneering guaranteed latency-SLA agreements over discrete hardware purchases. Three-tier pricing structure across premium ASIC designs, standard switch configurations, and economy Ethernet extensions reflects certification grade and volume scale differentiation. Cost compression in mid-tier switches is intensifying because captive silicon designers concentrate automotive-grade timing controller production. Component-centric manufacturers exhibit highest price sensitivity, while outcome-contracting automotive OEMs absorb premium positioning.
Supply Chain Analysis
Workforce-availability constraints in Germany's Bavarian automation corridors and Japan's Nagoya automotive supplier ecosystem tether TSN switch production to embedded systems timing engineering scarcity. Semiconductor fabrication draws from Taiwan's foundry capacity, South Korea's memory fabrication complexes, and China's Yangtze River Delta electronics clusters. Specialized automotive-grade timing components face single-source vulnerability in East Asian wafer fabrication. Distribution runs through Siemens and Cisco channel partners serving European manufacturing basins and Japanese precision automation clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: certification timeline compression in Japan's METI-aligned approval pathways versus extended IEC 62443 qualification periods in European manufacturing corridors creates cost-differential capture opportunities for suppliers with multi-regional compliance capabilities.
For Market Incumbents: Extend platform lock-in advantages by deepening captive silicon relationships with automotive OEMs before IEEE 802.1 standard revision cycles strand mid-decade infrastructure investments. Anchor TSN switch deployments through bundled digital transformation programs that embed maintenance and calibration services into long-term performance contracts, countering emerging IT-OT convergence platforms from enterprise networking vendors. For New Entrants and Emerging Players: Enter via medical device connectivity verticals, where IEC 60601-1-8 alarm system integration with TSN-enabled surgical networks remains underpenetrated beyond industrial automation. Target private 5G-TSN hybrid backhaul deployments in US manufacturing corridors pending FCC spectrum allocation clarity, leveraging system-level performance contracting preferences to bypass component-centric procurement barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless timing IP licensors lacking captive foundry relationships but holding IEEE 802.1 working group influence. Long-term viability across the analysis window hinges on standard-profile convergence with 5G URLLC specifications. Watch for METI-IEC harmonization acceleration as inflection indicator compressing Japanese vendor certification reciprocity timelines.| Strategic Initiative | Industry Significance |
|---|---|
| 5G-TSN Hybrid Certification Partnership | Enables untethered factory-floor deterministic control pending US FCC spectrum clarity. |
| Automotive-Grade ASIC Qualification Investment | Captures zonal E/E architecture sockets ahead of sensor fusion bandwidth scaling. |
| IEC 62443 Cybersecurity Certification Acceleration | Compresses product approval timelines against automotive OEM platform lock-in windows. |
| Medical Device Vertical Market Entry | Accesses surgical network timing demand beyond saturated industrial automation corridors. |
| Backward Integration into Timing Component Supply | Reduces East Asian semiconductor fabrication concentration risk for automotive controllers. |
Research Methodology
Coverage spans Germany's Industrie 4.0 manufacturing basins, Japan's precision automation clusters, and US private 5G deployment corridors, with primary inputs from each. Semiconductor vendor product managers, automotive OEM platform engineers, system integrators managing brownfield OT-IT convergence, and industrial automation procurement leads contributed structured interviews. Secondary validation drew from IEEE 802.1 working group publications, ETSI 5G URLLC specifications, IEC 62443 certification databases, and SEC filings from captive silicon designers. Bottom-up unit economics triangulated against top-down vertical demand aggregation.
Rate-of-change decomposition anchored forecast construction, segmenting by application layer, technology tier, end-user procurement maturity, and service type attachment. Deployment velocity across German automotive OEM digital transformation programs, Japanese METI-aligned vendor reciprocity timelines, and US FCC spectrum allocation trajectories shaped growth trajectory modeling. CAGRs derived from replacement-cycle compression analysis and standard convergence acceleration patterns.
Inputs from IEEE 802.1 working group draft specifications and ETSI-IEC harmonization committees were available through the study window; gaps in multi-vendor interoperability testing completion introduce uncertainty bands around deployment timeline assumptions. Forecasts reflect documented assumptions regarding automotive platform lock-in synchronization and semiconductor supply stabilization. Material deviation in METI certification reciprocity acceleration or IEEE 802.1 revision cycle pacing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
SATCOM Transceivers Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
Europe Set-Top Box Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Point-To-Point Microwave Antenna Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
Global Microwave Transmission Equipment Market
Telecom Hardware
Land Mobile Radio System Market
Telecom Hardware
Set-Top Box Market