
 Saudi Arabia Retail Banking Market | 2026-2036
Saudi Arabia Retail Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Retail Banking Market Analytics
Digital banking talent is rotating from traditional branch operations into API development and cybersecurity units, tightening conventional service capacity while unlocking platform scalability. Saudi National Bank leverages its sovereign-linked deposit base to sustain low-cost funding advantages across retail segments. Al Rajhi Bank anchors Sharia-compliant product innovation, while Alinma Bank competes through pure-play digital onboarding with zero physical branch dependency.
Saudi Arabia retail banking encompasses the provision of deposit, credit, payment, and wealth management services to non-corporate clients through regulated financial institutions, operating under Basel III liquidity coverage ratios and SAMA-mandated consumer protection standards. Its primary commercial purpose is intermediating household savings into productive domestic credit channels while facilitating daily transactional flows. Loan products directed at mortgage and auto financing dominate balance sheet growth, whereas digital wallets within the technology dimension capture the fastest adoption velocity among younger demographics. Branch networks retain significance for high-net-worth relationship management, though margin pools increasingly shift toward mobile-first customer acquisition.
SAMA's open banking directives and Consumer Protection Principles reshape product transparency requirements and third-party data sharing protocols across licensed institutions. The Saudi Central Bank's fintech regulatory sandbox and anti-money laundering frameworks govern market entry standards for new digital challengers. Stakeholders must monitor how rapidly evolving licensing categories for neobanks and payment service providers alter competitive dynamics and deposit fragmentation patterns.
Market Dynamics
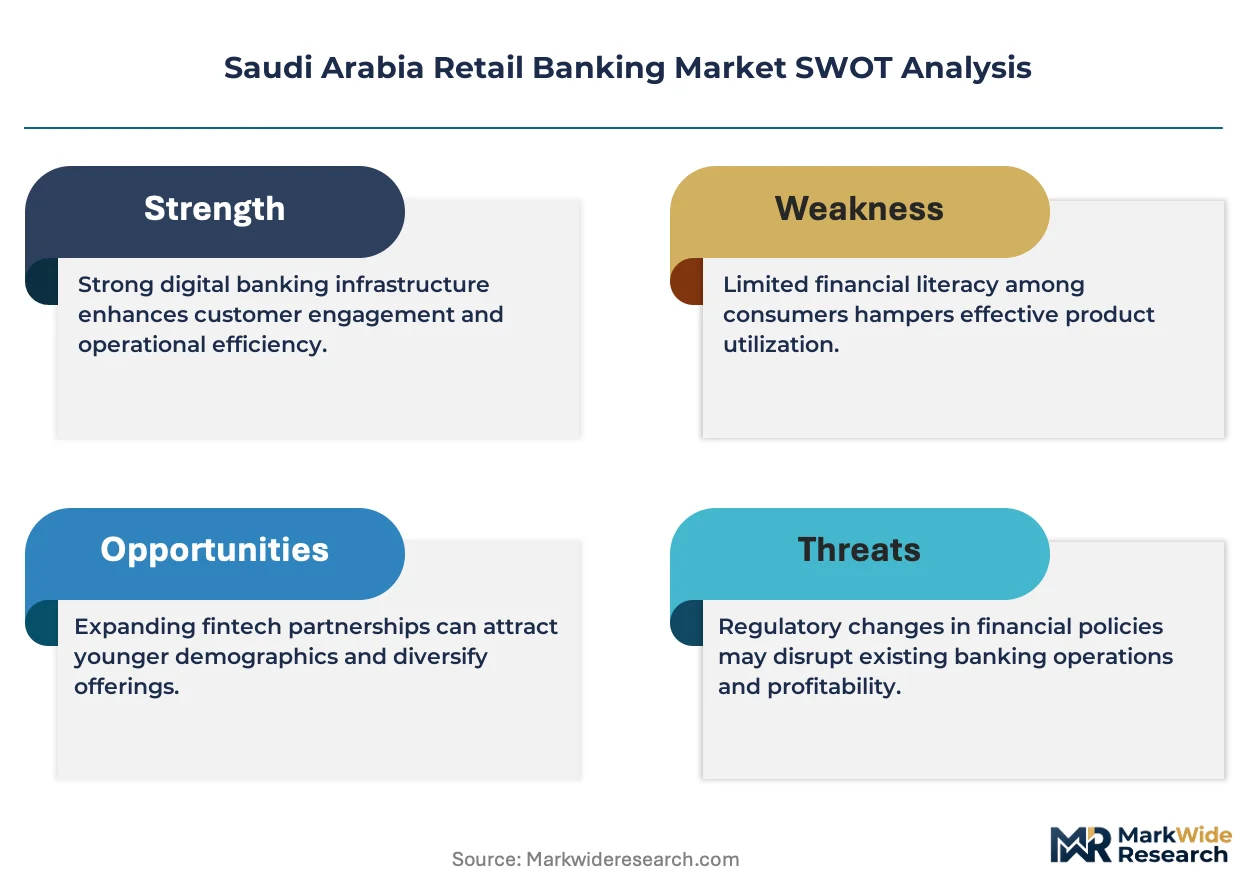
SAMA's open banking framework is compressing legacy branch economics while redistributing talent toward API architecture and cybersecurity functions. This regulatory-technology nexus is the dominant structural force reshaping competitive positioning across the Kingdom's retail banking landscape.
Growth Catalysts
- Vision 2030 Economic Diversification:Non-oil sector expansion is generating demand for SME credit facilities and structured lending products. Small enterprises in Riyadh and Jeddah are accelerating their uptake of formal banking channels.
- SAMA Open Banking Directives:The central bank's API standardization and third-party data sharing protocols are enabling fintech partnerships. Licensed institutions are migrating services onto platform architectures at accelerated velocity.
- Mobile Penetration Concentration:Urban clusters in Riyadh and Jeddah exhibit branch density and smartphone adoption rates that outpace other Saudi cities. Younger demographics are driving digital wallet adoption velocity.
Market Restraints
- Basel III Liquidity Coverage Ratios:SAMA-mandated reserve requirements constrain balance sheet flexibility for mortgage and auto financing expansion. Compliance costs compress net interest margins on retail deposits.
- Talent Migration Friction:Digital banking expertise is rotating out of traditional branch operations into API development and cybersecurity units. Conventional service capacity tightens as platform scalability unlocks.
- Deposit Fragmentation Risk:Neobank licensing categories and payment service provider authorizations are altering competitive dynamics. Licensed institutions face pressure on funding cost advantages.
Strategic Opportunities
- Sharia-Compliant Product Innovation:Untapped white space exists in Islamic wealth management and takaful-linked deposit structures. Al Rajhi Bank's positioning demonstrates scalable architecture for pure-play digital onboarding.
- Zero-Branch Digital Models:Alinma Bank's branch-dependency elimination provides template for capital-light customer acquisition. Geographic expansion into secondary cities follows mobile penetration gradients.
- Consumer Protection Principle Enforcement:SAMA's transparency mandates create competitive differentiation for institutions with superior disclosure architecture. Product standardization reduces switching friction for relationship migration.
Industry Challenges
- API Integration Complexity:Legacy core banking systems require substantial reconfiguration to interface with open banking infrastructure. Middleware development timelines extend platform rollout schedules.
- Cybersecurity Certification Burden:SAMA's anti-money laundering frameworks and data protection standards demand continuous compliance investment. Penetration testing and audit cycles consume operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Retail Banking Market |
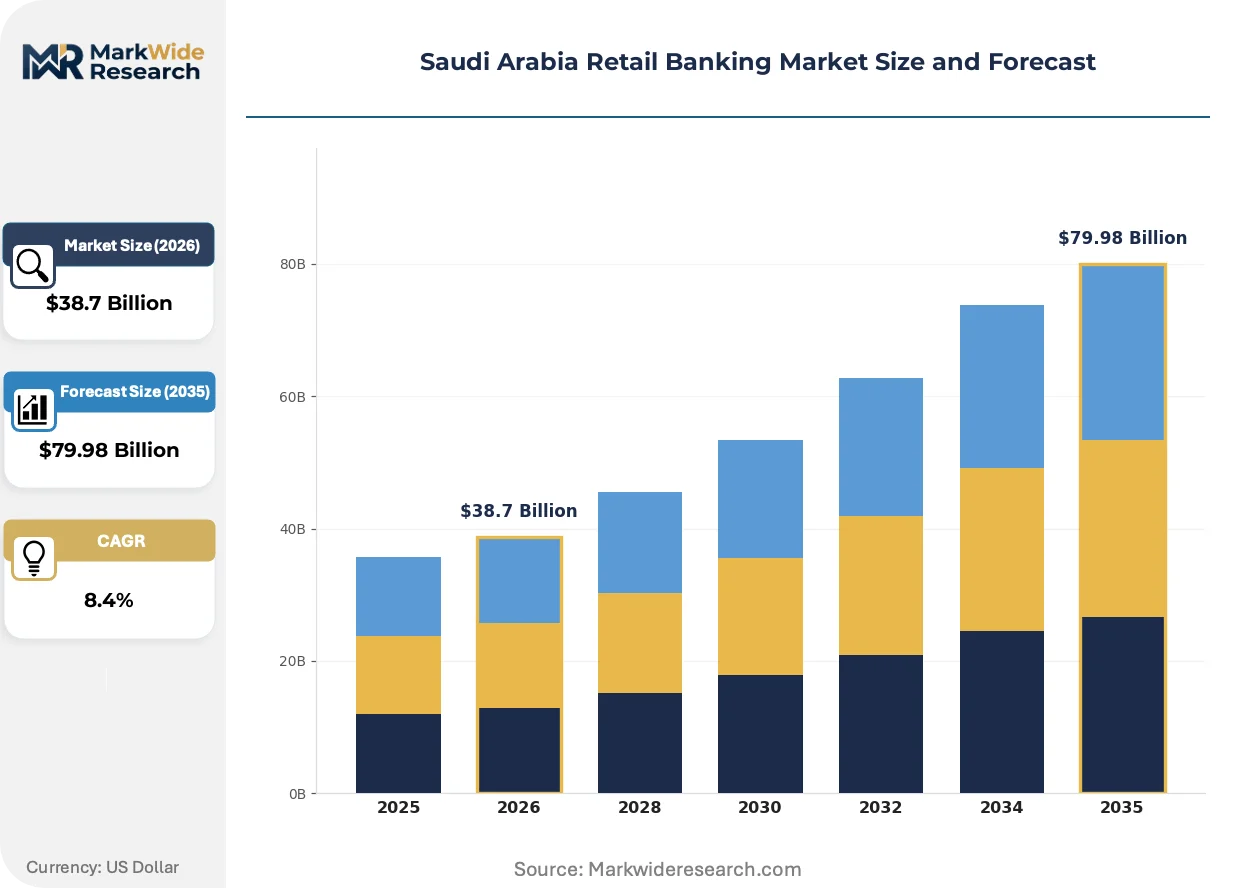
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Account Services, Loan Products, Investment Services, Insurance Solutions Customer Type: Individual Clients, Small Enterprises, Corporations, High-Net-Worth Individuals Technology: Mobile Banking, Online Banking, ATM Services, Digital Wallets Channel: Branch Network, Online Platforms, Call Centers, Third-Party Agents |
| Companies Covered | Alinma Bank, Banque Saudi Fransi, Saudi National Bank, Bank Albilad, Arab National Bank, Al Rajhi Bank, Saudi Awwal Bank, Saudi Investment Bank, Riyad Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Retail Banking Market Evolving Landscape
Platform architectures are supplanting branch-centric distribution models across Saudi retail banking. This transformation is compressing physical footprint requirements while unlocking scalable customer acquisition economics.
API-first banking infrastructure is supplanting traditional core system monoliths in licensed institutions. Tier-1 banks are deploying microservices architectures to enable real-time payment processing and third-party fintech integration. The structural consequence is a bifurcation between platform-scale players and branch-dependent institutions.
SAMA's Consumer Protection Principles are mandating granular fee disclosure and complaint resolution timelines across all licensed deposit-takers. Product transparency requirements are compressing cross-subsidization models that historically obscured true pricing. Retail mortgage and auto financing segments are responding with standardized product sheets and digital comparison tools.
Younger Saudi demographics are compressing switching cycles through mobile-first bank selection. Branch proximity is losing primacy to app-store ratings and onboarding speed in acquisition decisions. Riyadh and Jeddah urban clusters exhibit the most pronounced behavioral shift away from relationship-managed accounts toward self-service platforms.
Saudi Arabia Retail Banking Market Segmentation
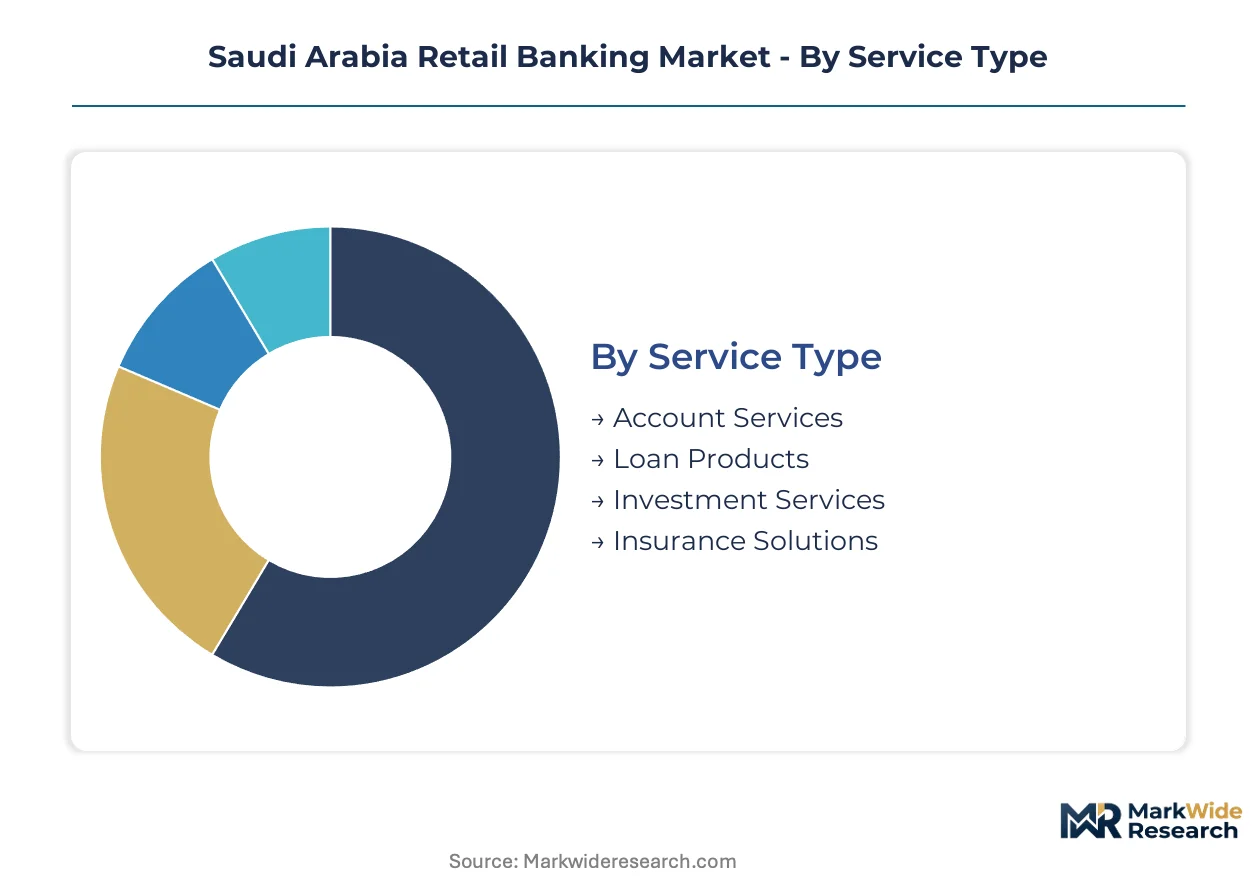
Saudi Arabia retail banking segments reflect divergent margin economics across service delivery modes and customer sophistication tiers. SAMA's regulatory framework shapes how each category captures value from Vision 2030 diversification and open banking migration.
Service Type:
Loan Products command the widest net interest margin spreads across the Kingdom's retail banking landscape.
- Loan Products:Mortgage and auto financing facilities dominate balance sheet composition with structured collateral requirements and SAMA-mandated consumer protection disclosures. Riyadh and Jeddah households concentrate demand for residential property financing as urban real estate development accelerates under Vision 2030 non-oil expansion.
- Account Services:Current and savings deposits provide low-cost funding foundations for licensed institutions. SAMA's liquidity coverage ratio requirements constrain how banks deploy these liabilities into higher-yielding credit channels.
- Investment Services:Sharia-compliant wealth management and sukuk portfolios serve HNW relationship segments.
- Insurance Solutions:Takaful-linked deposit structures and bancassurance distribution partnerships.
Loan Products holds installed capacity. Account Services is rotating up the share rankings.
Customer Type:
Small Enterprises generate the steepest expansion trajectory in formal credit uptake across secondary city clusters.
- Small Enterprises:Structured credit facilities and working capital lines serve Riyadh and Jeddah SME formations diversifying beyond oil-dependent revenue streams. SAMA's open banking framework enables faster underwriting through real-time transaction data sharing.
- Individual Clients:Mass-market depositors and retail borrowers constitute volume foundation. Mobile-first acquisition economics compress customer acquisition costs relative to branch-dependent relationship models.
- Corporations:Treasury management and payroll services.
- High-Net-Worth Individuals:Dedicated relationship management and bespoke Sharia portfolio construction.
Individual Clients anchors deposit funding. Small Enterprises is climbing the fastest.
Technology:
Digital Wallets capture the most rapid adoption velocity among younger demographics in urban concentration zones.
- Digital Wallets:Smartphone-native payment and peer-to-peer transfer applications bypass traditional card infrastructure. Jeddah and Riyadh urban clusters exhibit penetration rates that outpace other Saudi cities as SAMA's fintech licensing regime accelerates platform competition.
- Mobile Banking:Full-service application stacks with biometric authentication and real-time transaction processing. API-first architectures enable third-party fintech integration under open banking protocols.
- Online Banking:Browser-based account management and fund transfer portals.
- ATM Services:Cash withdrawal and deposit infrastructure.
ATM Services holds physical footprint. Digital Wallets is gaining share fastest.
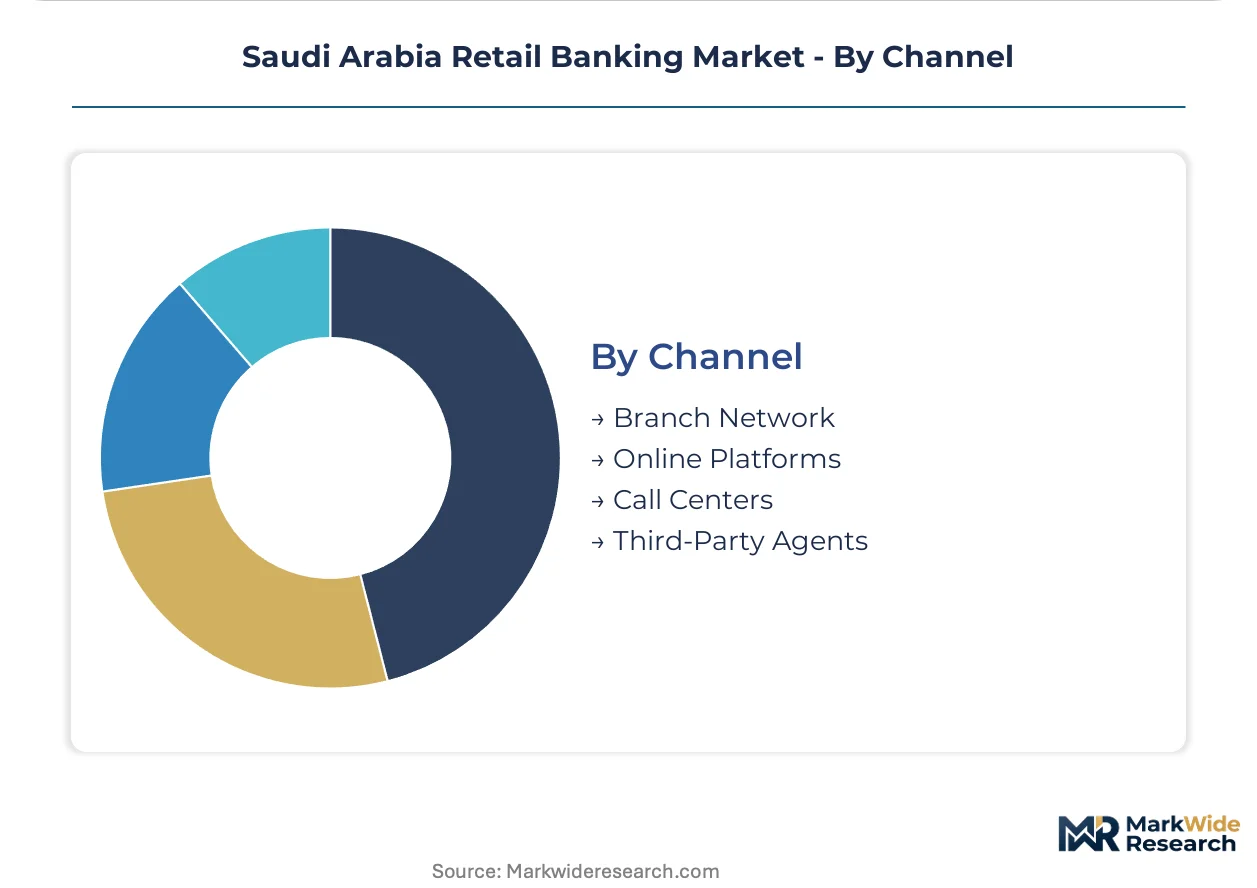
Channel:
Online Platforms concentrate margin expansion as branch economics compress under talent migration pressure.
- Online Platforms:Web and application-based service delivery eliminates physical footprint costs while scaling customer acquisition across geographic dispersion. SAMA's consumer protection mandates enforce transparency requirements that reduce switching friction.
- Branch Network:Relationship-managed HNW service and complex product consultation retain relevance. Riyadh and Jeddah maintain density concentration as secondary cities shift toward digital-first engagement.
- Call Centers:Voice-based service resolution and telemarketing acquisition.
- Third-Party Agents:Correspondent banking and merchant-acquired deposit relationships.
Branch Network holds relationship infrastructure. Online Platforms is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh and Jeddah concentrate retail banking activity through divergent consumption patterns. Riyadh households favor mortgage and structured investment products. Jeddah consumers accelerate digital wallet adoption velocity.
Riyadh
Vision 2030 non-oil diversification and SME formation drive credit facility demand. SAMA's Consumer Protection Principles mandate fee transparency and complaint resolution timelines. The Riyadh Financial District anchors fintech licensing activity as neobanks establish operational headquarters.
Eastern Province
Industrial payroll services and corporate treasury spillover generate retail deposit concentration. The country's central bank enforces Basel III liquidity coverage ratios across licensed institutions. Dammam and Khobar maintain branch density for relationship-managed high-net-worth segments.
Western Region
Umrah and Hajj pilgrimage flows sustain remittance and foreign exchange service demand. SAMA's open banking framework accelerates API standardization for real-time payment processing. Jeddah's Red Sea coastal corridor exhibits smartphone penetration rates that outpace interior provinces.
NEOM Northwest
Greenfield smart city construction generates project finance and contractor banking relationships. The central bank's fintech regulatory sandbox authorizes experimental digital-only service models. The Tabuk regional zone attracts capital-light branchless banking pilots.
Asir and Southern Provinces
Agricultural credit facilities and microenterprise lending expand formal banking penetration. SAMA-mandated consumer protection standards reshape product disclosure requirements. Abha and surrounding highland cities follow mobile penetration gradients for digital onboarding migration.
Saudi Arabia Retail Banking Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Saudi retail banking structure. Sovereign-linked deposit bases and Sharia-compliant product architectures define the upper tier. Specialists compete through pure-play digital models and zero-branch dependency. Competitive moves concentrate on API-first platform migration and fintech partnership formation.
Within the integrated leader tier, Saudi National Bank and Al Rajhi Bank occupy positions reflecting divergent strategic anchors. Saudi National Bank exemplifies sovereign-linked funding advantages across retail deposit segments. Al Rajhi Bank represents Sharia-compliant product innovation with scalable digital onboarding architecture. Alinma Bank sits within the specialist tier as a branch-dependency elimination template.
| Leading Market Players |
|---|
| Alinma Bank |
| Banque Saudi Fransi |
| Saudi National Bank |
| Bank Albilad |
| Arab National Bank |
| Al Rajhi Bank |
| Saudi Awwal Bank |
| Saudi Investment Bank |
| Riyad Bank |
| Others |
Value Network & Pricing Analysis
Branch network scale economies at Saudi National Bank and Al Rajhi Bank compress unit operating costs while establishing deposit-gathering floors that smaller digital challengers struggle to match. This concentration of physical infrastructure in Riyadh and Jeddah simultaneously anchors pricing power in relationship-managed segments and forces margin compression in commoditized digital channels.
Pricing Analysis
Long-term mortgage offtake contracts dominate retail lending pricing structures, with SAMA-mandated consumer protection disclosures standardizing fee schedules across licensed institutions. Price differentiation rests on Sharia certification tier and relationship-managed service bundling rather than raw rate competition. Pricing pressure stems from neobank deposit fragmentation as zero-branch models force incumbent net interest margin compression. Small enterprises exhibit highest price sensitivity due to working capital constraints, while high-net-worth individuals prioritize relationship quality over rate optimization.
Supply Chain Analysis
Inbound technology licensing costs from US and European core banking software vendors concentrate procurement expenditure for Saudi retail institutions. Legacy system dependencies draw from IBM, Oracle, and Temenos platforms, while API middleware and cybersecurity layers feed from specialized fintech infrastructure providers. Single-source vulnerability in core banking software licensing exposes institutions to renewal cost escalation. Distribution runs through branch networks for relationship-managed segments and mobile application stores for digital-native acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia retail banking is navigating a cyclical recovery anchored to Vision 2030 non-oil diversification and SME credit expansion. Formal banking penetration in secondary cities is accelerating as mobile infrastructure matures and SAMA's open banking framework reduces switching friction.
For Market Incumbents: Fortify deposit franchise advantages through sovereign-linked funding cost preservation and Sharia-compliant product innovation. Defensive consolidation should prioritize API-first platform migration to counter neobank customer acquisition velocity. Capacity addition in Riyadh Financial District technology centers supports cybersecurity certification maintenance under SAMA's evolving standards.
For New Entrants and Emerging Players: Differentiate on zero-branch operational economics and pure-play digital onboarding speed to penetrate secondary city clusters beyond Riyadh and Jeddah. The most penetrable segment lies in small enterprise working capital facilities underserved by legacy relationship models. Go-to-market execution should leverage SAMA's fintech regulatory sandbox for accelerated licensing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among institutions with established mortgage servicing portfolios and sticky deposit relationships. Long-term viability over the coming decade favors platforms with demonstrated API architecture scalability and regulatory compliance automation. Acquisition target archetypes include specialist digital challengers with proven customer acquisition economics. The signal to watch is SAMA's evolving neobank licensing categories and their impact on deposit fragmentation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Migration | Enables real-time fintech integration under SAMA's open banking directives. |
| Sharia-Compliant Product Innovation | Captures untapped white space in Islamic wealth management and takaful-linked structures. |
| Zero-Branch Digital Expansion | Replicates Alinma Bank's capital-light model for secondary city penetration. |
| Cybersecurity Certification Investment | Satisfies SAMA's anti-money laundering and data protection audit requirements. |
| SME Credit Facility Scaling | Aligns balance sheet growth with Vision 2030 non-oil diversification priorities. |
Research Methodology
Operator-level perspectives from retail banking executives, digital transformation officers, SAMA regulatory affairs specialists, and fintech platform architects anchored the qualitative base. Primary interview findings triangulated against secondary validation from SAMA regulatory circulars, Basel Committee liquidity coverage ratio guidelines, and licensed institution disclosure filings. Bottom-up segment sizing and top-down macroeconomic cross-checks converged on market estimates across the analysis window.
Sensitivity analysis tested forecast robustness against alternative scenarios for mobile penetration velocity and neobank licensing pace. Segmentation dimensions modeled include service type, customer sophistication tier, technology deployment mode, and channel preference across the projection horizon. CAGRs derived from historical trajectory analysis and structural growth factor weighting. Industry-specific inputs incorporated SAMA's open banking implementation timeline and Vision 2030 SME formation targets.
The analysis sits within stated boundaries; outcomes outside sustained regulatory support for digital banking migration and stable macroeconomic conditions in non-oil sectors would require recalibration. Forecasts reflect documented assumptions regarding technology adoption curves and competitive dynamics. SAMA policy shifts, cybersecurity incident frequency, and deposit fragmentation patterns represent primary revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Southeast Asia Commercial Banking Market
Banking
Automated Teller Machine (ATM) Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Latin America Banking As a Service Market
Banking
AI and Automation in Banking Market
Banking
Bank Kiosk Market
Banking
China Bank Kiosk Market
Banking
Global Neo and Challenger Bank Market
Banking
Digital Banking Market
Banking
Europe Machine Learning in Banking Market
Banking
Smart ATM Market
Banking
South America Challenger Banks Market
Banking
Open Banking Market
Banking
Smart Banking Solutions Market
Banking
Banking Smart Cards Market
Banking
Blockchain in Retail Banking Market