
 Middle East and Africa Neobanking Market | 2026-2036
Middle East and Africa Neobanking Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Neobanking Market Foresight
A capital-intensity divergence between legacy-backed neobanks and lean fintech startups is unwinding competitive dynamics across the Middle East and Africa. Mashreq Neo leverages its parent's balance sheet strength to fund aggressive customer acquisition across the UAE. MNT-Halan anchors its position in Egypt through hybrid digital-physical distribution that reaches rural micro-merchants. TymeBank competes in South Africa via a low-cost, cloud-native infrastructure model that minimizes branch overhead.
Neobanking in the Middle East and Africa denotes the provision of banking services through digital-only platforms operating without traditional physical branch networks, typically employing API-driven architectures, real-time payment rails, and mobile-native KYC verification to serve retail and commercial clients. The primary purpose centers on expanding financial inclusion for underbanked populations while reducing unit economics for deposit and lending operations. Mobile Payments and Digital Wallets within the Service Type dimension currently dominate transaction volume, while Financial Management Tools capture emerging margin pools as small businesses demand integrated cash flow analytics. Artificial Intelligence and Big Data Analytics within the Technology dimension represent the fastest-expanding capability layer, enabling credit scoring for thin-file customers previously excluded from formal banking.
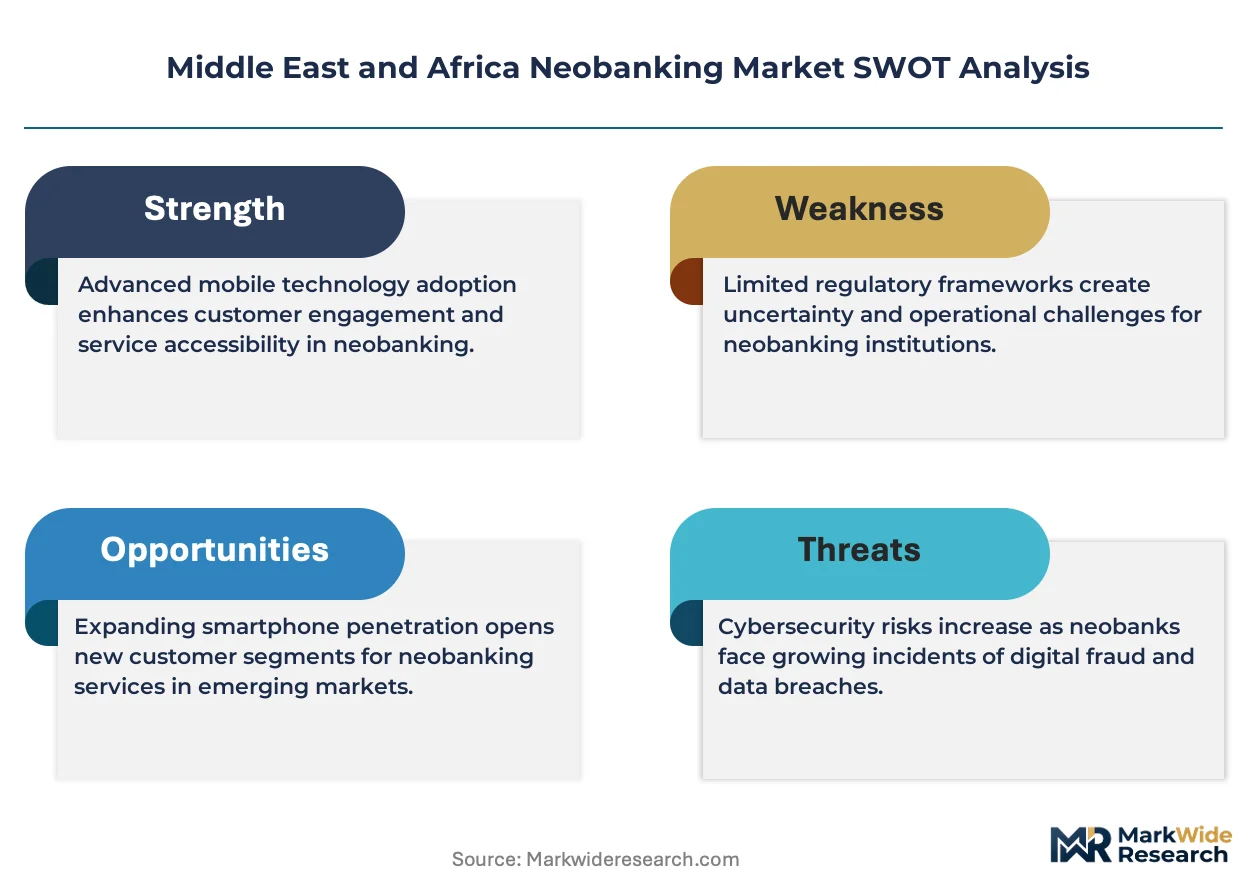
The UAE's central bank and Saudi Arabia's SAMR supervise licensing frameworks that determine which digital entrants gain deposit-taking authority and payment system access. South Africa's Prudential Authority applies Basel-aligned capital requirements that shape product rollout timelines for emerging players. Egypt's FRA and Nigeria's CBN enforce tiered KYC rules that directly affect customer onboarding friction and account functionality limits. Stakeholders must monitor how rapidly regulators harmonize cross-border digital banking passports across the region.
Market Dynamics
Regulatory divergence between deposit-taking licenses and payment service authorizations is fragmenting competitive access across the Middle East and Africa, forcing neobanks to pursue multi-jurisdictional licensing strategies that strain capital deployment timelines.
Growth Catalysts
- Open Banking Frameworks:SAMR in Saudi Arabia and the UAE Central Bank are mandating API interoperability standards that reduce customer switching costs and accelerate third-party fintech integration.
- Mobile-First Underbanked Demand:Nigeria's CBN tiered KYC regulations enable basic account opening with minimal documentation, expanding addressable populations previously excluded from formal credit systems.
- Cloud-Native Infrastructure:AWS and Azure regional data centers in South Africa and the UAE are compressing core banking deployment costs for new entrants by eliminating on-premise hardware requirements.
Market Restraints
- FX Volatility Exposure:Egyptian pound and Nigerian naira depreciation against dollar-denominated cloud and software licensing costs is eroding unit economics for deposit-funded neobanks.
- Interchange Rate Compression:South Africa's Prudential Authority caps on debit interchange are constraining transaction revenue models that subsidize free account offerings.
- Thin-File Credit Scoring Limitations:Absence of centralized credit bureaus in Ethiopia and Kenya forces reliance on expensive alternative data partnerships that raise customer acquisition costs.
Strategic Opportunities
- Rural Micro-Merchant Banking:Egypt's FRA agent banking regulations permit non-bank correspondents to handle cash-in/cash-out, opening distribution channels beyond urban smartphone penetration limits.
- Islamic Digital Banking:Sharia-compliant neobanking products in Saudi Arabia and the UAE address underserved segments with differentiated profit-sharing deposit structures.
- Embedded Finance Convergence:API partnerships between neobanks and ride-hailing or e-commerce platforms in Nigeria are creating contextual lending origination at point-of-sale.
Industry Challenges
- Cloud Infrastructure Talent Scarcity:DevOps and cybersecurity specialists with financial services compliance experience command premium compensation in Dubai and Johannesburg labor markets.
- Multi-Jurisdiction Compliance Burden:Neobanks operating across Egypt, Nigeria, and Kenya face divergent data localization mandates that fragment technology architectures and audit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Neobanking Market |
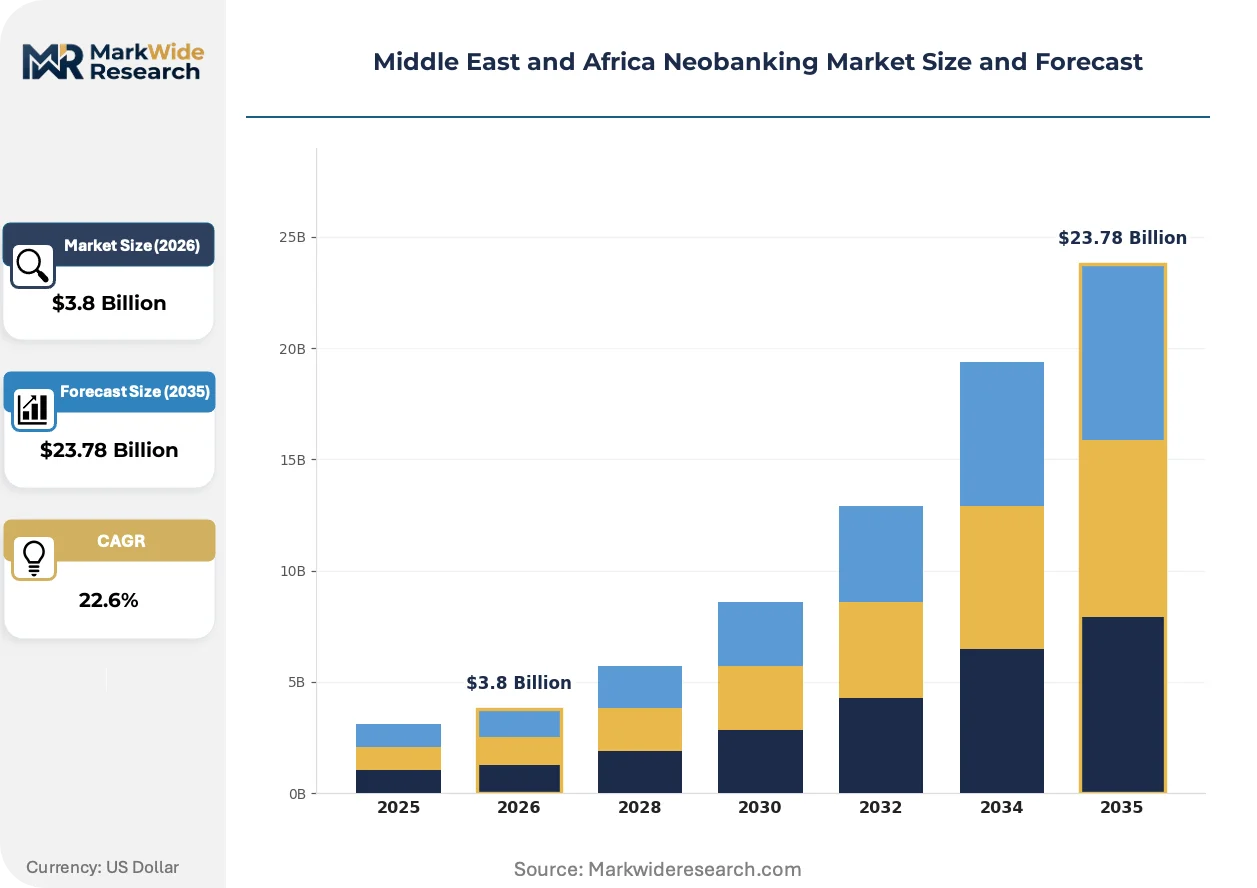
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.78 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Virtual Banking, Mobile Payments, Digital Wallets, Financial Management Tools Customer Type: Millennials, Small Businesses, Freelancers, Expatriates Technology: Blockchain, Artificial Intelligence, Big Data Analytics, Cloud Computing End User: Consumers, Enterprises, Startups, NGOs |
| Companies Covered | Mashreq Neo, meem, Liv. (Emirates NBD), Opay, CBD Now, STC Pay, Bank Zero, MNT-Halan, TymeBank, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Neobanking Market Shifts & Advancements
Artificial intelligence is compressing credit decision cycles from weeks to minutes across the Middle East and Africa, while regulatory sandboxes in the UAE and Nigeria are accelerating product iteration timelines previously constrained by static licensing regimes.
API-driven core banking platforms are decomposing monolithic legacy systems into modular microservices that enable rapid product configuration. Small business lenders in South Africa are adopting these architectures to launch sector-specific working capital products within days rather than quarters. This decomposition is collapsing the traditional IT vendor lock-in that protected incumbent banks from agile competitors.
Saudi Arabia's SAMR digital banking framework and the UAE's stored value facility regulations are creating tiered licensing pathways that separate full banks from specialized payment institutions. These frameworks are channeling capital toward narrow-license entrants that avoid Basel capital requirements while restricting deposit-taking scope. Fintechs in Dubai are responding by pursuing payment institution licenses initially, then upgrading to full banking authorizations after proving unit economics.
Merchant acquisition patterns are fragmenting as micro-businesses in Nigeria and Egypt bypass traditional POS terminals in favor of QR-code payments linked to mobile wallets. Neobanks are capturing this shift through zero-hardware onboarding that eliminates terminal deployment costs. This behavioral pivot is most visible among informal traders in Lagos and Cairo who prioritize cash-flow visibility over formal credit access.
Middle East and Africa Neobanking Market Segmentation
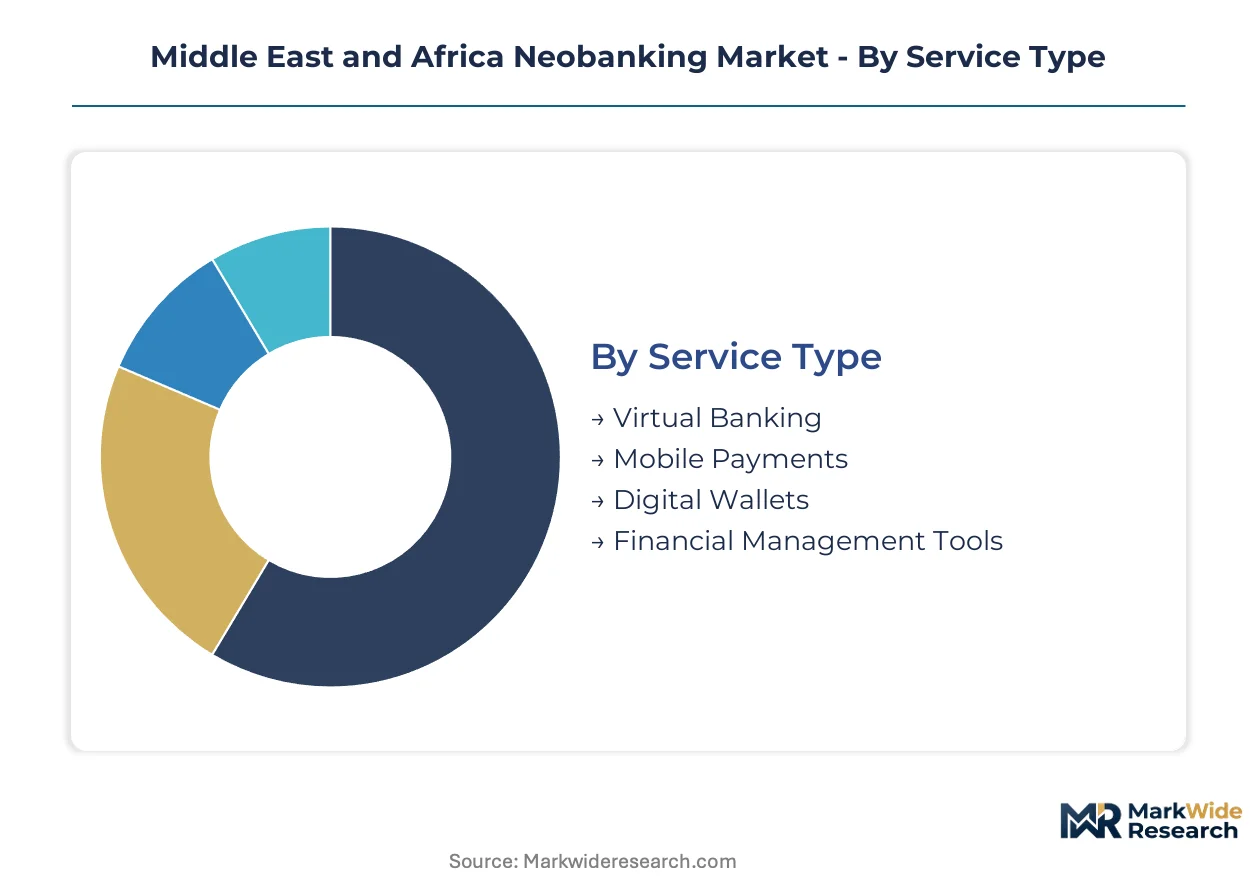
Segmentation in Middle East and Africa neobanking reveals divergent monetization pathways. Service type determines transaction economics, customer type shapes acquisition cost structures, and technology deployment separates capital-light challengers from legacy-backed entrants.
Service Type:
Margin pools concentrate in payment-adjacent services where interchange and float income compound, while pure deposit products face compressed spreads in high-inflation environments.
- Mobile Payments:Real-time fund transfers via USSD and smartphone apps dominate transaction volume across Nigeria and Egypt. Rural micro-merchants in Lagos and Cairo adopt QR-code acceptance to bypass terminal hardware costs, with demand concentrating where cash-in/cash-out agent networks extend beyond bank branch footprints.
- Digital Wallets:Stored-value accounts with tiered KYC functionality capture underbanked populations excluded from formal credit systems. Nigeria's CBN basic account regulations enable onboarding with minimal documentation, driving adoption among thin-file customers previously dependent on informal savings circles.
- Virtual Banking:Full-spectrum deposit and lending operations licensed under UAE Central Bank and Saudi SAMR frameworks serve mass-affluent segments in Gulf markets.
- Financial Management Tools:Integrated cash flow analytics and automated bookkeeping target small business owners seeking visibility beyond traditional bank statements.
The dominant share belongs to Mobile Payments, while Financial Management Tools is closing the gap fastest as SME banking margins attract specialized entrants.
Customer Type:
Acquisition economics vary sharply by segment, with small businesses commanding premium pricing tolerance but requiring higher touch support infrastructure.
- Small Businesses:Informal traders and registered SMEs across South Africa and Egypt demand working capital products with rapid disbursement cycles. TymeBank's cloud-native infrastructure enables same-day loan decisions that incumbent banks match only with manual underwriting delays.
- Millennials:Salary-earning professionals in Dubai and Johannesburg prioritize fee-free transactions and cryptocurrency adjacent services. Mashreq Neo targets this cohort with gamified savings products and fractional investment access.
- Freelancers:Gig economy workers in Nigeria's tech and creative sectors require irregular income smoothing tools and cross-border payment corridors.
- Expatriates:Remittance-intensive populations in UAE and Saudi Arabia seek multi-currency accounts with competitive FX execution.
Small Businesses command the highest revenue per customer, though Millennials expand most quickly through viral referral mechanics and social media distribution.
Technology:
Deployment architecture determines capital efficiency and regulatory compliance burden, with cloud-native stacks enabling faster licensing timelines than on-premise alternatives.
- Artificial Intelligence:Machine learning models compress credit decision cycles from weeks to minutes for thin-file applicants. MNT-Halan deploys alternative data scoring across Egypt's rural micro-merchant base where traditional bureau coverage remains sparse.
- Big Data Analytics:Transaction pattern recognition enables behavioral segmentation and predictive churn intervention. South African neobanks leverage these capabilities to tailor product recommendations across diverse income strata.
- Cloud Computing:AWS and Azure regional data centers in Johannesburg and Dubai eliminate hardware procurement delays and localize data residency compliance.
- Blockchain:Distributed ledger applications concentrate in cross-border remittance corridors and trade finance documentation.
Artificial Intelligence absorbs the largest share of venture funding, while Big Data Analytics delivers the steepest margin improvement trajectory through automated underwriting cost reduction.
End User:
Product complexity and regulatory requirements scale with entity sophistication, separating retail-focused challengers from B2B infrastructure providers.
- Consumers:Individual account holders drive volume economics through high-frequency, low-value transactions. Nigeria's tiered KYC framework enables basic account functionality that scales to full-service relationships.
- Enterprises:Corporate treasury and payroll integration demands API connectivity and multi-user permission architectures. UAE-based neobanks compete for SME corporate banking relationships previously captive to legacy institutions.
- Startups:Venture-backed technology companies require venture debt and cap table management tools alongside standard banking services.
- NGOs:Humanitarian disbursement programs in Kenya and Ethiopia prioritize transparent fund tracking and biometric beneficiary verification.
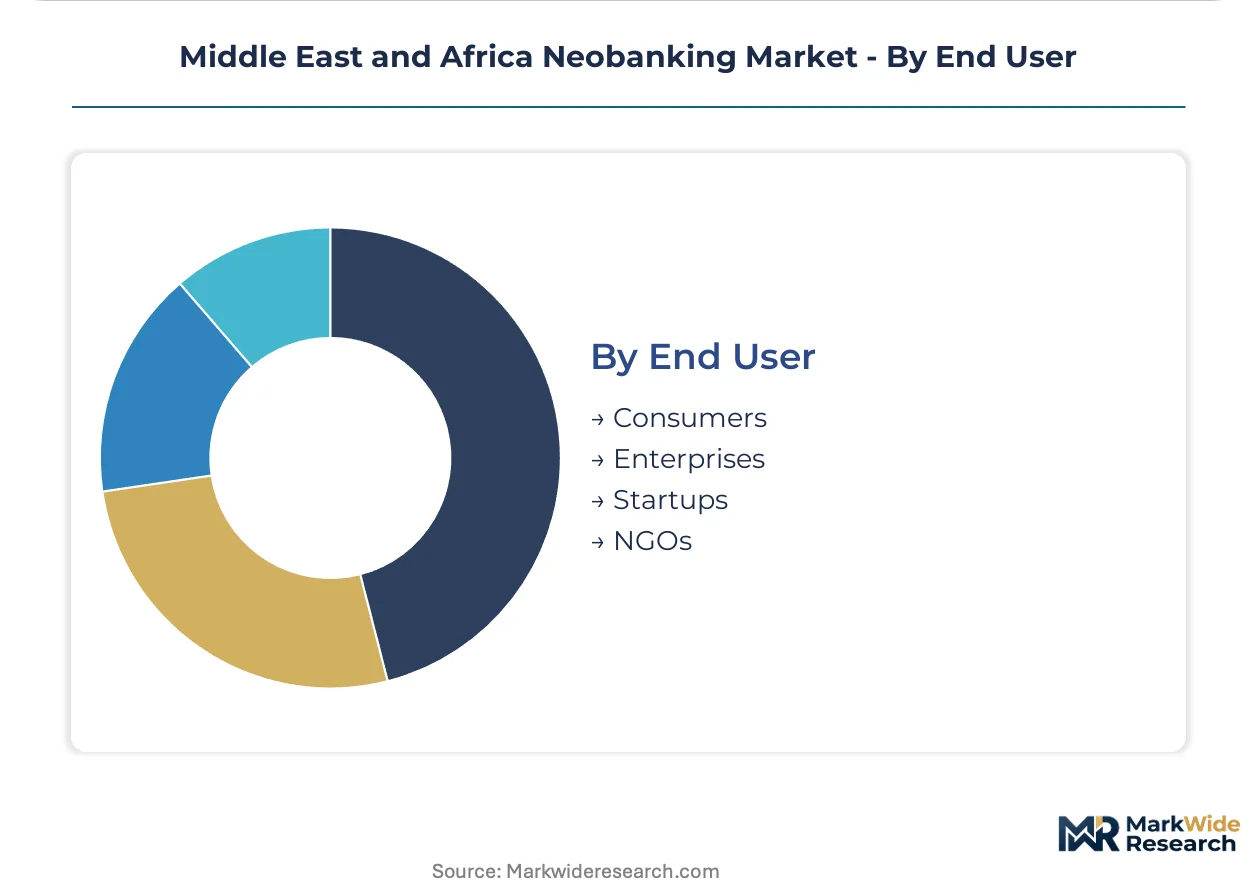
Consumers retain the dominant transaction volume position, though Enterprises generate the fastest revenue per account expansion through treasury management fee structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gulf Cooperation Council markets where regulatory clarity and dollar-pegged currencies attract foreign capital, while sub-Saharan African markets contend with currency volatility and thinner margins. This asymmetry shapes divergent competitive strategies across the region.
United Arab Emirates
Mass-affluent retail demand and SME corporate banking migration drive neobank penetration in Dubai and Abu Dhabi. The UAE Central Bank's stored value facility regulations create tiered licensing pathways that separate payment institutions from full deposit-takers. Dubai International Financial Centre clusters fintech infrastructure providers serving Gulf-wide expansion.
Saudi Arabia
Youthful demographics and smartphone saturation propel mobile-first banking adoption among salary-earning professionals. SAMR's digital banking framework mandates API interoperability standards that accelerate third-party fintech integration. Riyadh anchors the kingdom's fintech regulatory sandbox where product iteration timelines compress.
Nigeria
Underbanked populations and informal trader cash-flow management needs concentrate demand in Lagos and Abuja. The CBN's tiered KYC regulations enable basic account opening with minimal documentation, expanding addressable markets. Lagos clusters agent banking networks that extend cash-in/cash-out beyond traditional branch footprints.
South Africa
Small business working capital demand and gig economy income smoothing tools attract specialized entrants in Johannesburg and Cape Town. The Prudential Authority applies Basel-aligned capital requirements that shape product rollout timelines for emerging players. Johannesburg anchors cloud-native infrastructure deployment serving regional expansion.
Egypt
Rural micro-merchant banking and hybrid digital-physical distribution drive adoption beyond urban smartphone penetration limits. The FRA's agent banking regulations permit non-bank correspondents to handle cash transactions, opening rural channels. Cairo and Alexandria cluster fintech infrastructure targeting unbanked populations in the Nile Delta.
Middle East and Africa Neobanking Market Competitive Landscape
Concentration sits with legacy-backed digital subsidiaries that leverage parental balance sheets for customer acquisition, while lean fintech challengers compete on cloud-native cost structures. The market structure fragments across three strategic archetypes: incumbent-spawned digital banks, pure-play fintechs, and telecom-anchored payment platforms. Dominant competitive moves include hybrid digital-physical distribution expansion and API-driven embedded finance partnerships with ride-hailing and e-commerce platforms.
Among legacy-backed digital subsidiaries, Mashreq Neo exemplifies the parental-balance-sheet archetype, while MNT-Halan occupies a position within the hybrid distribution tier. TymeBank anchors the cloud-native challenger segment. These three entities represent distinct capital deployment models competing for overlapping customer segments across retail and small business banking.
| Leading Market Players |
|---|
| Mashreq Neo |
| meem |
| Liv. (Emirates NBD) |
| Opay |
| CBD Now |
| STC Pay |
| Bank Zero |
| MNT-Halan |
| TymeBank |
| Others |
Supply & Pricing Matrix
Capacity reservation agreements with cloud infrastructure providers lock in both compute access and cost predictability for neobanks operating across Dubai and Johannesburg data centers. These multi-year contracts insulate deposit-funded challengers from dollar-denominated AWS and Azure pricing volatility that erodes unit economics in naira and pound markets.
Pricing Analysis
The customization-premium spread separates configured-to-order SME treasury packages from standard retail account offerings. Three-tier pricing structure across premium, standard, and economy levels captures divergent customer lifetime values, with Gulf Cooperation Council markets commanding subscription fees that subsidize free tiers in sub-Saharan African markets. Price differentiation hinges on API integration depth and after-sales support tiers. Pricing pressure stems from South Africa's Prudential Authority interchange caps that constrain transaction revenue subsidization. Small businesses in Egypt and Nigeria exhibit highest price sensitivity, while mass-affluent expatriates in Dubai demonstrate lowest elasticity.
Supply Chain Analysis
South Africa and the United Arab Emirates anchor cloud-native core banking infrastructure deployment, with Nigeria and Egypt feeding from regional data center extensions. AWS Cape Town and Azure Johannesburg facilities supply compute capacity, while API middleware draws from Dubai fintech clusters. Single-source vulnerability concentrates in hyperscaler dependency for KYC verification and payment rail connectivity. Distribution runs through hybrid digital-physical networks combining mobile app stores with agent banking correspondents in Lagos and Cairo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward small business aggregators and platform ecosystems as neobank procurement concentrates through embedded finance partnerships with ride-hailing and e-commerce operators.
For Market Incumbents: Compound parental balance sheet advantages through exclusive API partnerships with Saudi SAMR-licensed payment institutions. Deepen cloud infrastructure backward integration to reduce hyperscaler dependency. Defensive consolidation must address MNT-Halan's hybrid distribution threat in Egypt's rural micro-merchant segments. For New Entrants and Emerging Players: Differentiate on Islamic digital banking compliance to capture underserved segments in Saudi Arabia and the UAE. White-space targets include rural agent banking networks beyond Cairo and Lagos smartphone penetration limits. Most penetrable entry point: tiered KYC basic accounts in Nigeria's underbanked informal trader population. Go-to-market angle: zero-hardware QR-code merchant onboarding. For Investors and Strategic Acquirers: Cloud-native challengers with proven unit economics in high-inflation markets represent the priority acquisition archetype. Long-term viability hinges on regulatory passporting capabilities across Egypt, Nigeria, and Kenya. Signal to monitor: harmonization of cross-border digital banking licenses that would unlock regional scalability.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Certification | SAMR and UAE Central Bank mandates accelerate third-party fintech integration timelines. |
| Hybrid Distribution Expansion | Agent banking correspondents extend cash-in/cash-out beyond urban smartphone penetration limits. |
| Alternative Data Partnership | Machine learning scoring compresses credit cycles for thin-file Egyptian micro-merchants. |
| Sharia-Compliant Product Suite | Profit-sharing deposit structures capture underserved segments in Gulf Cooperation Council markets. |
| Embedded Finance Integration | Contextual lending origination at Nigerian ride-hailing point-of-sale deepens customer acquisition. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with neobank product executives, regulatory affairs leads at UAE Central Bank and SAMR, cloud infrastructure procurement officers, and Egyptian agent banking network operators; and secondary validation against CBN tiered KYC filings, South African Prudential Authority capital requirement disclosures, AWS regional data center expansion announcements, and embedded finance partnership press releases. Bottom-up transaction volume modeling and top-down regulatory licensing capacity analysis were triangulated.
Across the analysis window, forecasts segment by service type, customer archetype, deployment technology, and end-user sophistication. Modeled dimensions include mobile payment velocity, SME working capital demand cycles, and cloud-native versus legacy-backed infrastructure economics. CAGRs were derived from licensing pipeline velocity and deposit growth trajectories in dollar-pegged versus floating currency markets.
The analysis sits within stated boundaries; outcomes outside sustained regulatory sandbox momentum and hyperscaler regional expansion would require recalibration. Forecasts assume continued tiered KYC liberalization and cloud infrastructure localization mandates. Recalibration cycles align with material shifts in SAMR digital banking framework revisions and CBN agent banking regulation amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Cloud Computing Banking Market
Banking
Letter of Credit Confirmation Market
Banking
Biometric Banking Wristband Market
Banking
China Data Analytics in Banking Market
Banking
Singapore Neobanking Market
Banking
APAC Banking-As-A-Service Market
Banking
Italy Data Analytics in Banking Market
Banking
Europe Banking-As-A-Service Market
Banking
AI and Automation in Banking Market
Banking
Banking Wearable Market
Banking
Commercial Banking Market
Banking
Latin America Neo Banking Services Market
Banking
Investment Banking Market
Banking
Latin America Banking As a Service Market
Banking
Europe Machine Learning in Banking Market
Banking
Investment Banking and Trading Services Market