
 Bank Guarantee Market | 2026-2036
Bank Guarantee Market Size, Share, and Industry Trends Forecast 2026-2036
Bank Guarantee Market Analysis
Buyer concentration among multinational infrastructure developers is recalibrating how banks price counter-guarantee risk. HSBC leverages its trade finance network across Asia-Pacific and the Middle East to sustain documentary guarantee volumes. UniCredit anchors European performance bond issuance through specialized corporate banking desks in Germany and Italy. Standard Chartered competes on emerging market bid security, where local currency guarantees require sophisticated hedging infrastructure.
A bank guarantee is a contingent liability instrument issued by a financial institution, promising to cover a specified sum if the applicant defaults on contractual or financial obligations; it operates through independent legal undertakings governed by UCP 600 or ISP98 rules, with tenors typically spanning 12 to 60 months depending on underlying project cycles. Financial institutions dominate issuance volume, though online platforms are displacing paper-based workflows fastest among SME customer segments. Performance bonds command premium pricing relative to bid security instruments, reflecting longer risk windows and more complex collateral structures.
Basel III frameworks compel issuers to hold risk-weighted capital against off-balance-sheet guarantee exposures, while ICC uniform rules standardize cross-border enforceability. The EU Green Deal and associated sustainable finance taxonomy are beginning to condition guarantee pricing on environmental performance criteria for infrastructure projects. Stakeholders must monitor how digital trade platforms and embedded finance models reshape traditional correspondent banking relationships in guarantee distribution.
Market Dynamics
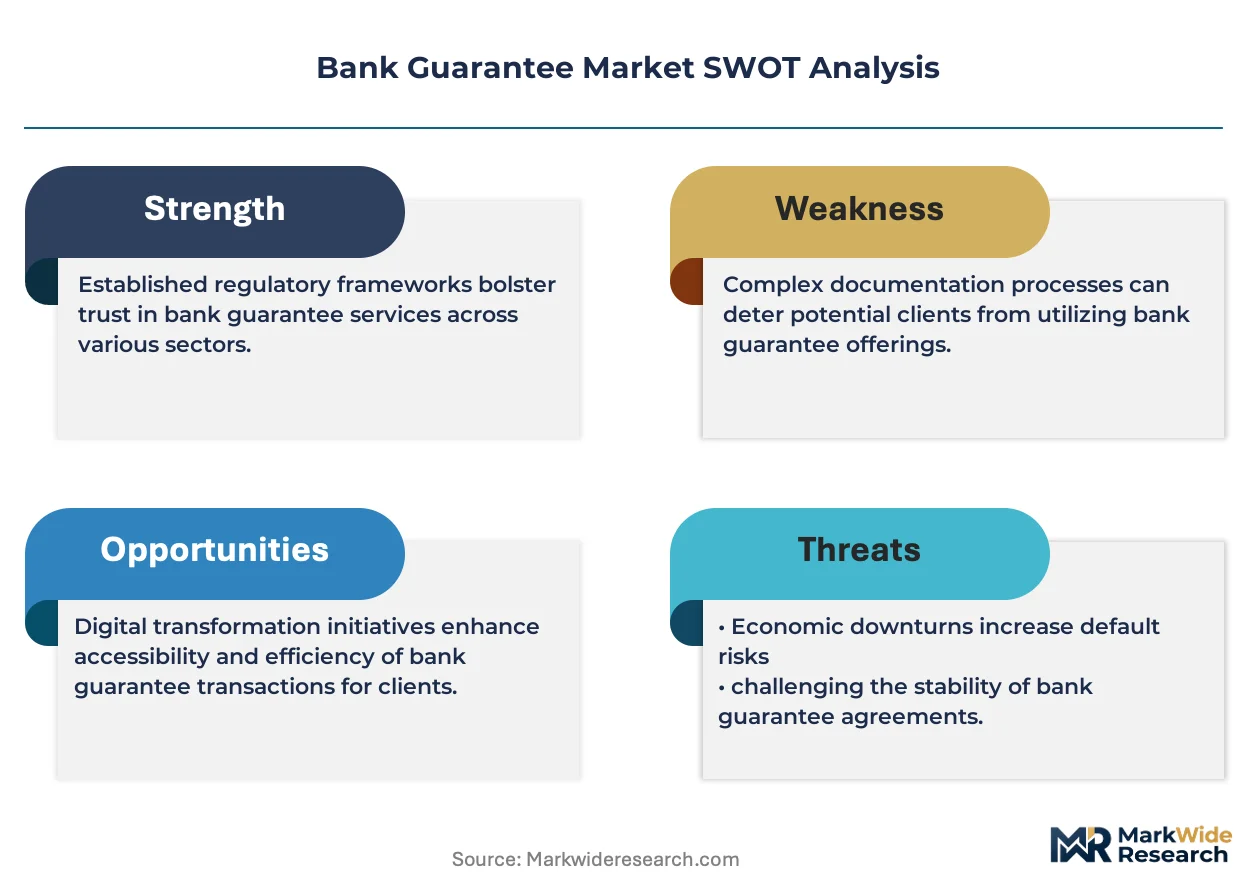
Basel III capital adequacy frameworks are compressing bank guarantee issuance capacity by forcing higher risk-weighted capital reserves against off-balance-sheet exposures, fundamentally altering how financial institutions structure counter-guarantee pricing and tenor flexibility.
Growth Catalysts
- India's PLI-linked procurement mandates:Domestic manufacturing incentives under the Production Linked Incentive scheme are accelerating bank guarantee issuance for contractor qualification and performance security.
- Emerging market infrastructure buildout:Public works contractors across Southeast Asia and the Middle East are expanding performance bond utilization to secure government-backed project finance.
- Digital trade platform integration:API-connected guarantee issuance is converging with open banking infrastructure to compress turnaround times for SME bid security applications.
Market Restraints
- Collateral liquidity constraints:Long-dated performance bonds require locked cash deposits or pledged securities that strain working capital for mid-tier contractors.
- Counter-guarantee concentration risk:Emerging market local currency guarantees depend on correspondent banking relationships concentrated in Singapore and Hong Kong clearing systems.
- Regulatory capital arbitrage limits:Basel III standardized approach removes favorable risk-weighting for unrated sovereign-backed guarantee exposures.
Strategic Opportunities
- EU Green Deal conditional pricing:Sustainable finance taxonomy alignment allows premium guarantee structures for infrastructure projects meeting environmental performance thresholds.
- Embedded finance distribution:Non-bank platforms are integrating guarantee issuance into procurement software workflows, bypassing traditional branch-based origination.
- Blockchain-verified document handling:Distributed ledger verification of beneficiary claims is compressing dispute resolution cycles and fraud exposure.
Industry Challenges
- Trade finance talent scarcity:Documentary credit specialists with UCP 600 and ISP98 expertise are retiring faster than training pipelines replenish qualified practitioners.
- Legacy core system integration:Guarantee workflow digitization requires costly middleware development to connect 1990s-era banking platforms with modern API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bank Guarantee Market |
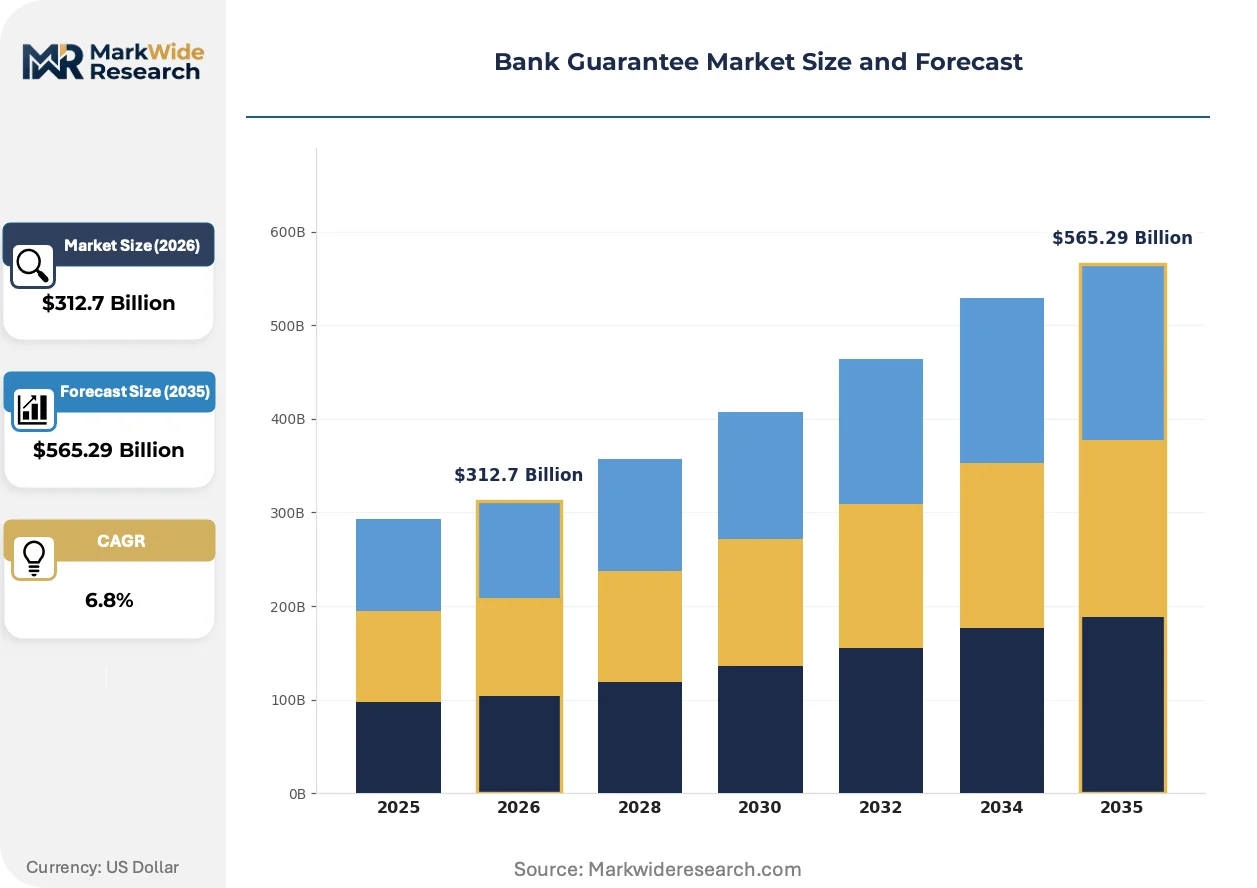
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Financial Institutions, Corporations, Government Agencies, Contractors Guarantee Purpose: Trade Transactions, Performance Bonds, Loan Security, Bid Security Customer Type: SMEs, Large Enterprises, Government Bodies, Multinational Companies Issuance Method: Direct Issuance, Counter Guarantees, Documentary Guarantees, Online Platforms |
| Companies Covered | DBS Bank, UniCredit, HSBC, Ecobank, Raiffeisen Bank International, Societe Generale, Santander, BNY Mellon, Standard Chartered, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bank Guarantee Market Emerging Trajectories
Distributed ledger infrastructure and open API standards are converging to displace paper-based guarantee workflows, while regulatory frameworks in Europe and Asia-Pacific increasingly condition financial instrument pricing on sustainability performance criteria.
Smart contract-enabled guarantee execution is converging with automated oracle verification to enable conditional payout triggers without manual document examination. Infrastructure contractors in the Middle East are piloting these instruments for performance bonds tied to milestone completion. This compression of verification overhead is converging with reduced legal friction in cross-border enforcement.
The EU Green Deal sustainable finance taxonomy is mandating environmental performance disclosure for infrastructure project guarantees, with ESG-linked pricing differentials now materializing in German and Italian corporate banking desks. Contractors failing to meet carbon intensity thresholds face higher risk premiums or shortened tenors. Renewable energy and rail infrastructure segments are responding fastest by embedding guarantee terms into green bond covenants.
Buyer concentration among multinational infrastructure developers is compressing guarantee pricing power toward volume-based fee structures. Tier-one EPC contractors now demand standardized guarantee formats across multiple jurisdictions, displacing bespoke national instruments. This consolidation is most visible in Indian and Saudi Arabian public procurement, where pre-qualified contractor pools have shrunk to fewer than twenty firms controlling majority bid security issuance.
Bank Guarantee Market Segmentation
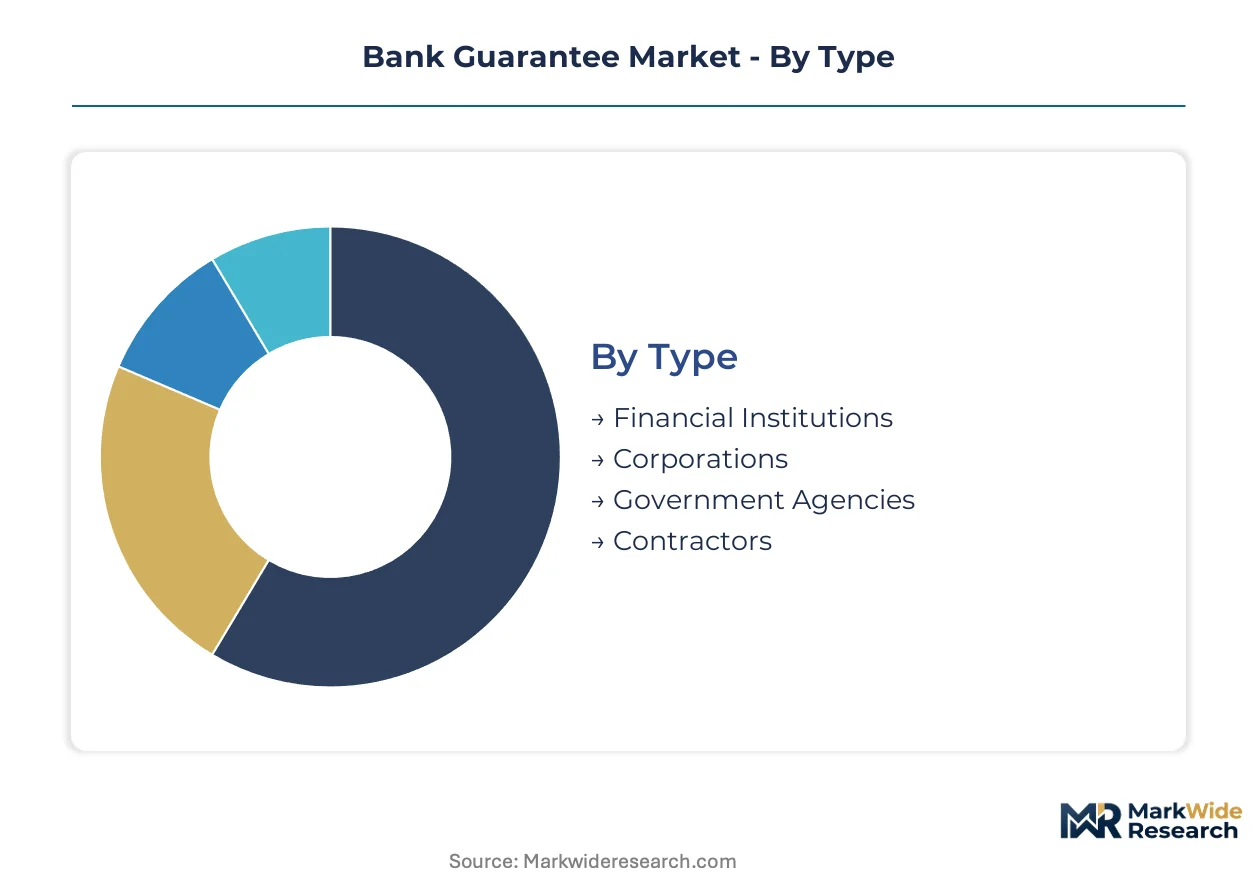
Bank guarantee market segmentation reveals how risk allocation, regulatory capital treatment, and digital distribution reshape competitive positioning across issuer categories and instrument types. Understanding these divisions exposes where pricing power concentrates and which customer segments drive volume expansion.
Type:
Issuer type determines capital reserve requirements under Basel III frameworks and shapes counter-guarantee network access.
- Financial Institutions:Commercial banks dominate issuance volume through specialized trade finance desks, with capital adequacy rules forcing higher risk-weighted reserves against long-dated performance exposures. Indian public sector banks anchor domestic guarantee flows through PLI-linked procurement mandates, while European institutions compress pricing for EPC contractors with cross-border project portfolios.
- Corporations:Multinational infrastructure developers and energy majors issue parent company guarantees to subsidiaries, bypassing bank fees but concentrating counterparty risk on consolidated balance sheets. Saudi Aramco and Adani Group entities leverage this structure for contractor qualification in mega-project procurement.
- Government Agencies:Sovereign-backed instruments carry favorable risk weighting under standardized approaches, with India's EXIM Bank and Germany's KfW issuing payment guarantees for export finance.
- Contractors:Large EPC firms issue retention guarantees to subcontractors, creating cascading liability chains in construction project hierarchies.
Financial institutions lead on scale; corporations lead on momentum as vertical integration into captive guarantee issuance accelerates.
Guarantee Purpose:
Purpose classification tracks how guarantee tenors, collateral structures, and beneficiary claim patterns vary by underlying commercial function.
- Trade Transactions:Documentary guarantees governed by UCP 600 rules secure cross-border payment obligations, with demand concentrating in Asia-Pacific manufacturing supply chains where open account terms require bank-backed security.
- Performance Bonds:Long-dated instruments spanning 24-60 months secure contractor completion obligations, commanding premium pricing for infrastructure projects in Saudi Arabia's giga-developments and India's national highway expansion. Collateral requirements strain working capital for mid-tier construction firms.
- Loan Security:Credit enhancement guarantees support project finance structures, with RBI-mandated provisions shaping Indian infrastructure lending.
- Bid Security:Short-tenor bid bonds qualify contractors for tender participation, with digital platforms compressing turnaround times for SME applicants.
Performance bonds lead on scale; bid security leads on momentum as procurement digitization accelerates.
Customer Type:
Customer scale determines pricing tier access, collateral flexibility, and relationship banking intensity.
- SMEs:Small contractors and traders face cash collateral lock-up requirements that constrain working capital, driving demand for online platform issuance with API-connected workflows.
- Large Enterprises:Tier-one EPC contractors negotiate standardized guarantee formats across multiple jurisdictions, extracting volume-based fee discounts from relationship banks.
- Government Bodies:Public procurement authorities mandate guarantee instruments for contractor pre-qualification, with India's CPWD and Saudi Arabia's NHC driving regional issuance concentration.
- Multinational Companies:Cross-border project developers require multi-jurisdictional guarantee programs with centralized treasury management.
Large enterprises lead on scale; SMEs lead on momentum as embedded finance platforms democratize access.
Issuance Method:
Distribution channel selection reflects customer digital maturity, counter-guarantee network requirements, and document complexity.
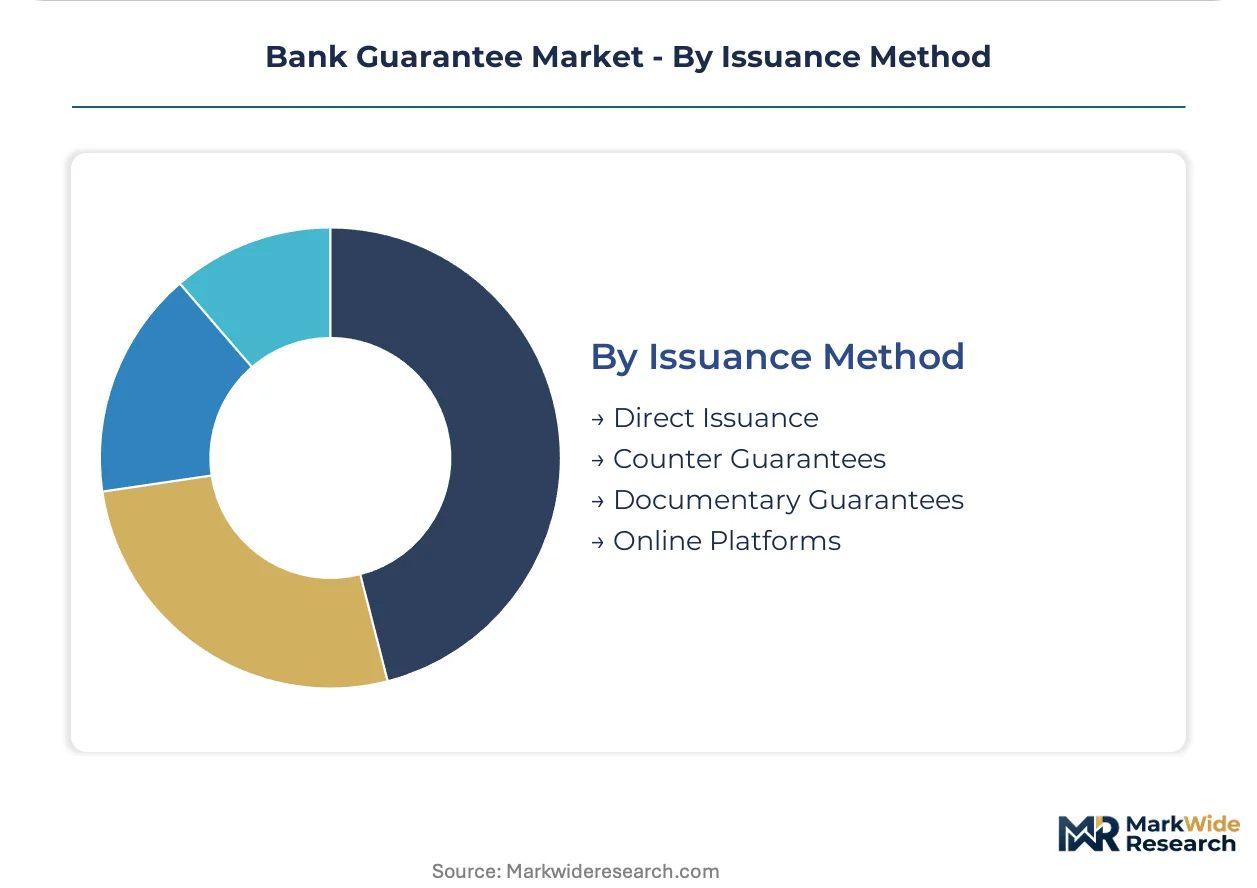
- Direct Issuance:Relationship banks issue guarantees directly to beneficiaries, maintaining pricing control but requiring branch-based document handling.
- Counter Guarantees:Correspondent banking networks in Singapore and Hong Kong enable local currency guarantees for emerging market contractors, with concentration risk in clearing system dependencies.
- Documentary Guarantees:Paper-based workflows governed by ISP98 rules persist for complex infrastructure projects requiring manual document examination.
- Online Platforms:API-connected issuance integrates with procurement software, compressing turnaround times for standardized bid security applications among SME segments.
Direct issuance leads on scale; online platforms lead on momentum as open banking infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Documentary credit specialists cluster in Singapore and Hong Kong correspondent banking hubs, anchoring guarantee issuance capacity for emerging market contractors across Asia-Pacific and Middle Eastern procurement corridors.
India
RBI-mandated project finance provisions and PLI-linked procurement mandates are accelerating performance bond issuance for domestic manufacturing contractors. The central bank's risk-weighting rules shape how public sector banks structure long-dated infrastructure guarantees. Mumbai's trade finance desks and Delhi-NCR procurement authorities concentrate bid security volume for national highway and renewable energy tenders.
Saudi Arabia
Giga-development contractors demand standardized guarantee formats across multiple giga-project portfolios, compressing pricing power toward volume-based structures. SAMR procurement regulations and NHC pre-qualification mandates require bank-backed performance security for contractor participation. Riyadh-based corporate banking units and Eastern Province project sites anchor regional issuance concentration for energy and infrastructure buildouts.
Germany
KfW export finance guarantees and EU Green Deal sustainable finance taxonomy are conditioning guarantee pricing on environmental performance thresholds for infrastructure projects. ECHA disclosure requirements and CSRD reporting standards shape how corporate banking desks structure ESG-linked instruments. Frankfurt's trade finance specialists and Bavarian industrial clusters drive premium pricing for renewable energy and rail project guarantees.
United States
Multinational infrastructure developers concentrate bid security demand among relationship banking networks, extracting standardized formats across federal and state procurement jurisdictions. SEC disclosure requirements and FERC project finance regulations shape how commercial banks structure credit enhancement guarantees for energy infrastructure. New York's correspondent banking hubs and Texas energy corridors anchor regional issuance for EPC contractors.
Singapore
Correspondent banking networks enable local currency guarantee issuance for Southeast Asian contractors, with concentration risk in clearing system dependencies. MAS regulatory frameworks and trade finance digitization initiatives are compressing turnaround times for documentary guarantee workflows. The city's trade finance specialists and regional treasury management hubs anchor cross-border guarantee distribution for Indonesian and Vietnamese infrastructure projects.
Bank Guarantee Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across guarantee issuance, with commercial banks dominating volume through specialized trade finance desks while regional players carve niches in local currency instruments. The market structure tilts toward tiered consolidation, where global institutions with correspondent banking networks command premium positioning against emerging market specialists with regulatory proximity advantages. Three archetypes define competitive positioning: Asia-Pacific network banks with multi-jurisdictional counter-guarantee infrastructure, European universal banks with ESG-linked pricing capabilities, and emerging market specialists with local regulatory relationships. Dominant competitive moves include API-connected platform investments compressing SME turnaround times and strategic partnerships embedding guarantee issuance into procurement software workflows.
Among Asia-Pacific network institutions, DBS Bank and Standard Chartered occupy positions exemplifying correspondent banking scale across Singapore and Hong Kong clearing corridors, while HSBC anchors multi-jurisdictional guarantee distribution through its trade finance network spanning the Middle East and emerging Asian markets.
| Leading Market Players |
|---|
| DBS Bank |
| UniCredit |
| HSBC |
| Ecobank |
| Raiffeisen Bank International |
| Societe Generale |
| Santander |
| BNY Mellon |
| Standard Chartered |
| Others |
Supply Flow & Price Mechanics
API-connected guarantee issuance is compressing cost economics for SME bid security while concentrating pricing power among correspondent banking hubs in Singapore and Hong Kong. This technology shift simultaneously reduces document handling overhead and reinforces tiered fee structures where volume-based discounts accrue to multinational EPC contractors with centralized treasury operations.
Pricing Analysis
Bundled relationship pricing for multi-jurisdictional guarantee programs commands premium fees, while unbundled transactional issuance for one-off bid security faces compression from online platform competition. Three-tier pricing structure across premium, standard, and economy levels segments by relationship depth, collateral flexibility, and counter-guarantee network access. Pricing pressure stems from buyer concentration among tier-one infrastructure developers demanding standardized formats across Saudi Arabian and Indian procurement corridors. SMEs exhibit highest price sensitivity due to cash collateral lock-up requirements, while sovereign-backed export finance guarantees from Germany's KfW and India's EXIM Bank anchor premium pricing tiers.
Supply Chain Analysis
Freight and document logistics costs for paper-based guarantee workflows persist in complex infrastructure projects requiring manual ISP98 examination, though digital platforms are displacing these expenses fastest among standardized bid security segments. Guarantee issuance capacity concentrates in India, Germany, and Singapore, with Mumbai and Frankfurt trade finance desks anchoring regional pricing benchmarks. Raw material inputs include risk-weighted capital reserves under Basel III frameworks, correspondent banking network access, and UCP 600 documentary credit expertise. Single-source vulnerability runs through Singapore and Hong Kong clearing systems for emerging market local currency guarantees. Distribution runs through relationship banking networks for large EPC contractors and embedded finance platforms for SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bank guarantee market functions as a stable compounder anchored by irreplaceable infrastructure procurement demand across emerging economies. Basel III capital requirements create durable barriers to entry while digital platforms expand addressable SME volume.
For Market Incumbents: To counter margin compression from buyer concentration among multinational EPC contractors, deepen API-connected platform investments compressing SME turnaround times, and secure exclusive embedded finance partnerships with procurement software vendors. Strengthen correspondent banking relationships in Singapore and Hong Kong to defend local currency guarantee pricing power.
For New Entrants and Emerging Players: Launch via white-label embedded finance integrations with construction procurement platforms targeting mid-tier contractors in India's PLI-linked manufacturing ecosystem. Focus initial penetration on bid security digitization where document standardization exceeds complexity, then ladder into performance bond segments through collateral innovation partnerships.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with regulatory proximity to India's RBI-mandated project finance provisions or Saudi Arabia's SAMR procurement frameworks. Long-term viability hinges on digital workflow adoption curves and correspondent banking network control. Monitor API integration penetration rates among SME contractor segments as inflection signal for platform-based margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Connected Platform Investment | Compresses bid security turnaround times for SME contractors through open banking infrastructure integration. |
| Embedded Finance Partnership | Integrates guarantee issuance directly into procurement software workflows, bypassing branch-based origination. |
| Correspondent Banking Expansion | Secures local currency guarantee capacity in Singapore and Hong Kong clearing corridors for emerging market exposure. |
| ESG-Linked Pricing Structure | Aligns guarantee terms with EU Green Deal taxonomy thresholds for renewable energy and rail infrastructure projects. |
| Blockchain Document Verification | Reduces fraud exposure and dispute resolution cycles through distributed ledger verification of beneficiary claims. |
Methodological Framework
Bottom-up contractor qualification modeling reconciled against top-down guarantee issuance tracking forms the analytical core of this study. Primary interviews with trade finance desk heads, EPC contractor treasury managers, procurement authority officials, and documentary credit specialists combined with secondary validation from RBI circulars, Basel Committee regulatory texts, ICC uniform rules publications, and customs trade finance data. Triangulation across these sources ensures segmentation integrity across issuer type, guarantee purpose, and customer category dimensions.
Input-output matrices map guarantee volume drivers including infrastructure procurement spend, PLI scheme disbursement trajectories, and Basel III risk-weighted capital allocation rules against issuance capacity constraints. Segmentation modeling spans financial institution type, guarantee instrument purpose, customer scale tier, and distribution channel across the projection horizon. CAGRs derive from regression analysis of historical issuance patterns against macroeconomic infrastructure investment forecasts, with specific incorporation of India's highway expansion pipeline and Saudi giga-development procurement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under correspondent banking relationship disruptions or abrupt Basel capital requirement revisions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Australia Neobanking Market
Banking
US Investment Banking Market
Banking
North America Bank Kiosk Market
Banking
Machine Learning in Banking Market
Banking
Corporate Banking Market
Banking
Southeast Asia Commercial Banking Market
Banking
Global Chatbot for Banking Market
Banking
Smart Banking Solutions Market
Banking
Asia-Pacific Machine Learning in Banking Market
Banking
API Banking Market
Banking
Banking As a Service (BAAS) Market
Banking
Banking Maintenance Support and Services Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
Global Retail Core Banking Systems Market
Banking
Global Neobanking Market
Banking
Latin America Neo Banking Services Market