
 Australia Neobanking Market | 2026-2036
Australia Neobanking Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Neobanking Market Analysis
Australian fintech infrastructure is broadening as cloud-native core banking platforms mature and API connectivity deepens. Judo Bank leverages direct SME relationship models to compete against incumbents on speed-to-decision. UP Neo Bank sustains engagement through automated savings and real-time spending analytics. Tyro anchors merchant payment ecosystems by integrating terminal hardware with working capital products.
A neobank operates as a licensed deposit-taking institution without physical branch networks, delivering retail and commercial banking services through mobile-first interfaces with real-time transaction processing and AI-driven risk scoring. Its primary purpose centers on reducing customer acquisition costs and operational overhead while improving user experience through data personalization. Service type segmentation shows mobile payments and budgeting tools generating the strongest user retention, while digital savings accounts concentrate the largest deposit pools. Customer type dynamics reveal freelancers as the fastest-acquiring segment due to irregular income matching neobank cash-flow tools.
APRA governs prudential standards and capital adequacy for authorized deposit-taking institutions, while ASIC enforces conduct and disclosure obligations across digital financial products. The Consumer Data Right mandates open banking data sharing, forcing neobanks to build interoperable platforms or lose competitive differentiation. Stakeholders must monitor how APRA's evolving restricted ADI pathway and ASIC's design-and-distribution obligations reshape product development timelines and compliance costs.
Market Dynamics
APRA's restricted ADI licensing framework compresses capital barriers for digital entrants, while cloud-native core banking platforms displace legacy infrastructure investments. This dual regulatory-technology pressure is reconfiguring competitive economics across deposit-taking and lending segments.
Growth Catalysts
- Consumer Data Right:Open banking mandates force interoperability, enabling neobanks to aggregate financial data from incumbent institutions and deliver personalized cash-flow analytics.
- SME relationship models:Direct engagement with entrepreneurs dissatisfied with legacy decision timelines accelerates small business lending origination.
- Real-time payment infrastructure:New Payments Platform integration enables instant settlement, reducing friction for merchant payment ecosystems and working capital products.
Market Restraints
- Deposit funding concentration:Retail savings pools cluster in Sydney and Melbourne, limiting geographic diversification of funding bases.
- Prudential capital requirements:APRA's capital adequacy standards for restricted ADIs constrain balance sheet expansion velocity relative to full license holders.
- Trust deficit in digital-only propositions:Older demographic segments exhibit persistent preference for physical branch presence during financial stress events.
Strategic Opportunities
- Freelancer segment expansion:Irregular income patterns among gig economy workers create demand for automated savings and tax withholding tools unmatched by incumbent product suites.
- Embedded finance partnerships:API connectivity enables neobanks to integrate deposit and lending products into accounting software and e-commerce platforms.
- ASIC design-and-distribution obligations:Regulatory clarity on product suitability creates compliance advantage for digitally-native institutions with integrated risk scoring.
Industry Challenges
- Cloud engineering talent scarcity:Competition for platform architects with financial services security clearance compresses hiring timelines and compensation structures.
- Core banking migration complexity:Transition from restricted to full ADI status requires data architecture reconfiguration without service interruption.
- Third-party risk management:ASIC's operational resilience expectations for outsourced technology providers extend compliance burden to vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Neobanking Market |
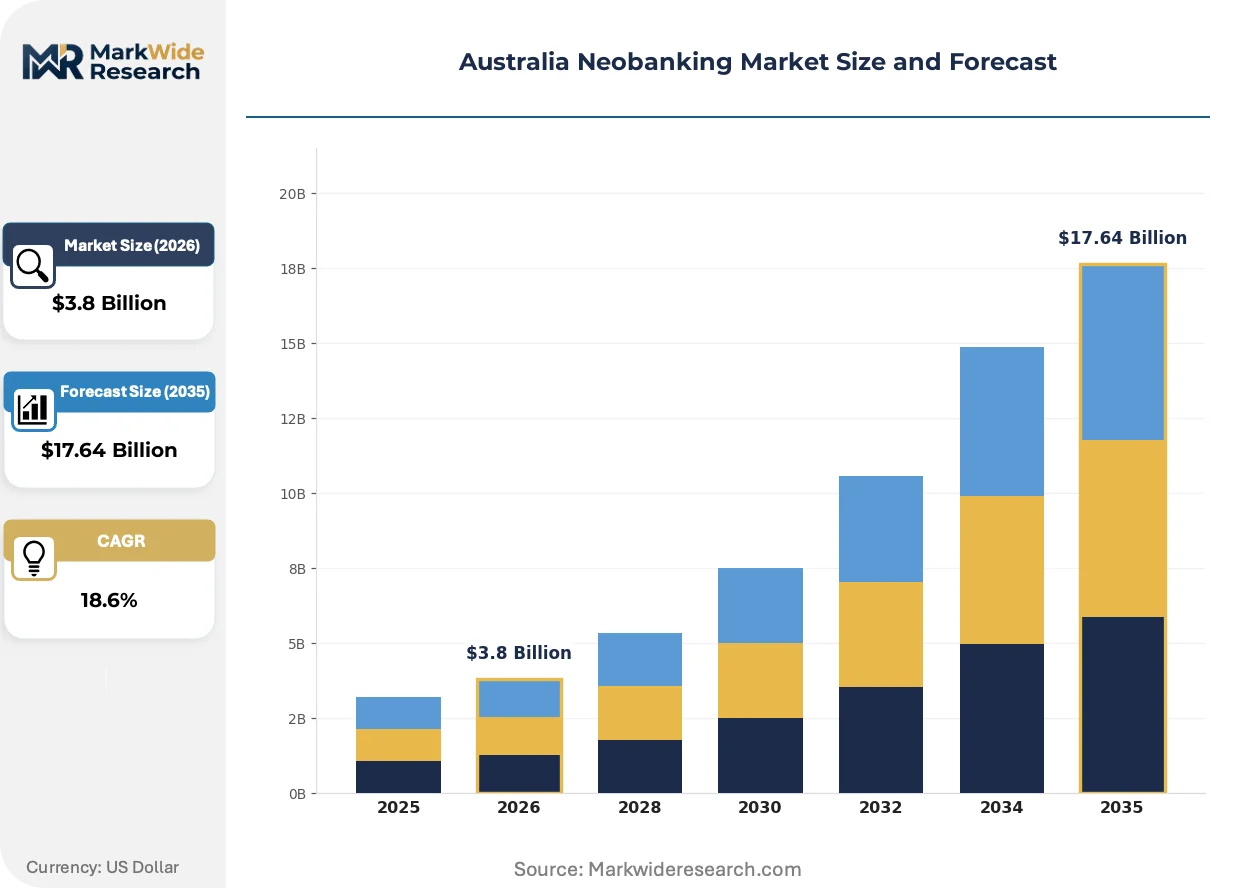
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Millennials, Gen Z, Freelancers, Small Businesses Service Type: Digital Savings, Mobile Payments, Budgeting Tools, Personal Loans Transaction Type: P2P Transfers, Bill Payments, Remittances, Point of Sale Platform Type: iOS, Android, Web-Based, Cross-Platform |
| Companies Covered | BNK, Judo Bank, UP Neo Bank, Tyro, Hay, Alex, Revolut, Douugh, Volt Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Neobanking Market Emerging Trajectories
Cloud-native architecture is consolidating vendor landscapes while regulatory data mandates force platform interoperability. Behavioral shifts among tech-native demographics accelerate mobile-first service expectations.
Artificial intelligence-driven risk scoring is consolidating credit decision workflows into automated pipelines. Neobanks deploy machine learning models trained on alternative data sources including transaction velocity and merchant category patterns. This compression of underwriting timelines from weeks to minutes enables real-time lending offers at point-of-need.
APRA's evolving restricted ADI pathway tightens graduation criteria for capital and operational maturity. Institutions must demonstrate sustainable funding models and governance frameworks before unrestricted deposit-taking authorization. This regulatory sequencing favors patient capital deployment over rapid balance sheet scaling.
Mobile-first engagement patterns among millennials in Sydney and Melbourne displace branch-centric relationship models. Users expect real-time spending analytics and automated savings triggers as standard features. This behavioral shift forces incumbents to accelerate digital transformation investments to retain deposit share.
Australia Neobanking Market Segmentation
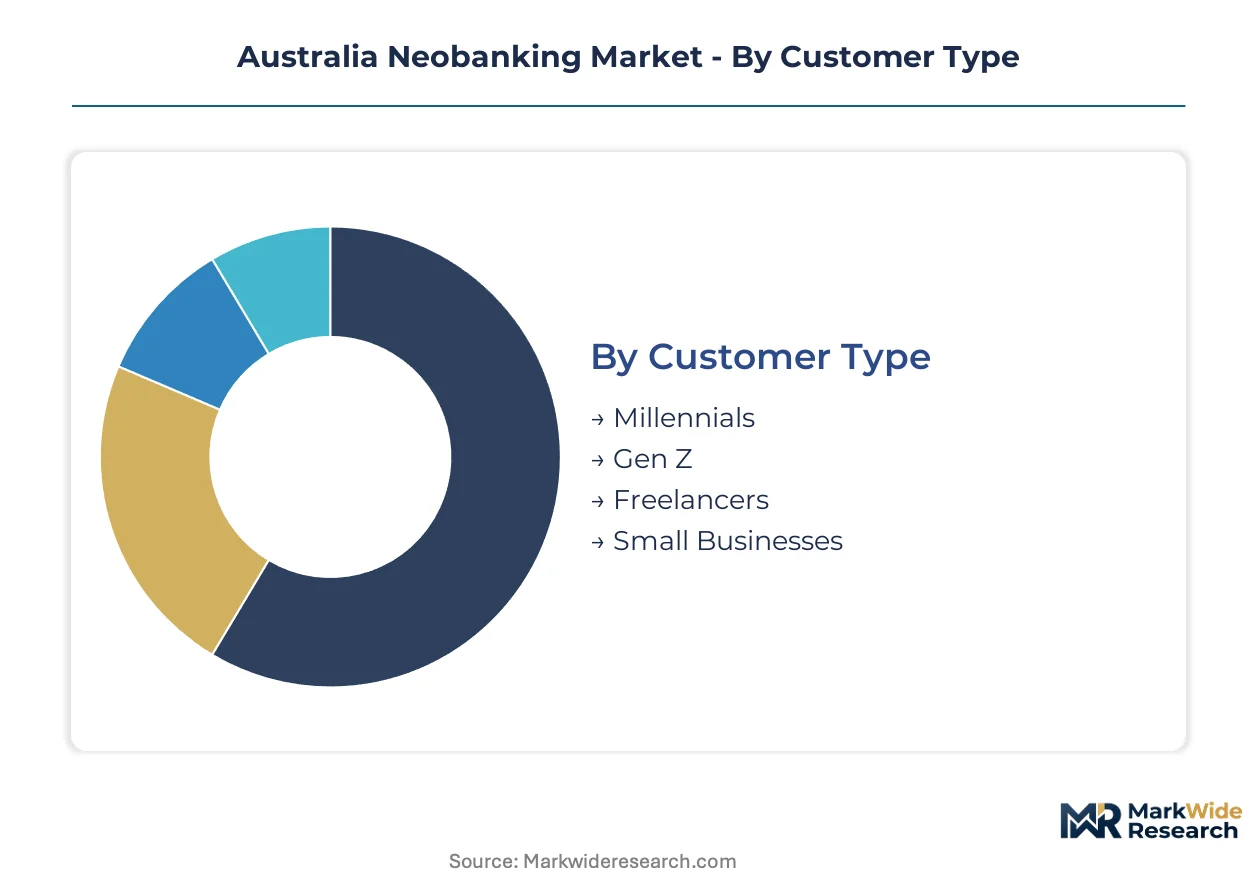
Segmentation in Australian neobanking reveals how digital-native institutions target discrete behavioral clusters with specialized product architectures. Each dimension—customer profile, service delivery, transaction mode, and platform access—shapes capital allocation and technology investment priorities.
Customer Type:
Supply concentration in Sydney and Melbourne drives customer acquisition strategy, with neobanks calibrating product suites to demographic density in these metropolitan clusters.
- Millennials:Tech-savvy professionals aged 28-43 dominate deposit volumes through automated savings triggers and real-time spending analytics. Demand concentrates in inner-Sydney postcodes where salary levels support premium feature adoption and cross-selling of investment products.
- Gen Z:Digital-native users entering workforce prioritize instant payment notifications and social money-sharing features. Melbourne's university precincts generate the steepest acquisition curves as students transition to graduate banking relationships.
- Freelancers:Irregular income patterns create demand for tax withholding automation and cash-flow smoothing tools unmatched by incumbent term deposit structures.
- Small Businesses:Entrepreneurs dissatisfied with legacy decision timelines accelerate working capital origination through API-integrated accounting platforms.
Millennials absorb the bulk of installed capacity; Freelancers are expanding most quickly.
Service Type:
Cost tier differentiation separates mass-market functionality from premium advisory layers, with fee structures calibrated to engagement depth and balance thresholds.
- Digital Savings:High-yield deposit accounts with automated round-up features and goal-based sub-accounts. Sydney's professional services workers concentrate the largest balance pools, though APRA's restricted ADI capital requirements constrain rate competitiveness against full-license incumbents.
- Mobile Payments:Real-time settlement via New Payments Platform integration enables instant peer-to-peer and merchant transactions. Melbourne's retail corridors drive merchant ecosystem adoption as neobanks bundle terminal hardware with transaction accounts.
- Budgeting Tools:AI-categorized spending insights and predictive cash-flow forecasting. ASIC's design-and-distribution obligations mandate suitability screening for automated financial guidance features.
- Personal Loans:Alternative-data underwriting using transaction velocity and merchant category patterns compresses approval timelines to minutes. Risk concentration in unsecured consumer credit requires sophisticated machine learning model governance.
Digital Savings captures the largest balance concentration; Mobile Payments is climbing the fastest as NPP infrastructure matures.
Transaction Type:
Application-specific routing determines infrastructure investment, with real-time settlement requirements dictating cloud architecture specifications.
- P2P Transfers:Instant domestic transfers between neobank users and external accounts via PayID. Social payment features drive viral acquisition among Melbourne's young professional networks.
- Bill Payments:Scheduled direct debits and BPAY integration for recurring obligations. Sydney's property rental market generates predictable payment volumes through automated rent transfer workflows.
- Remittances:Cross-border transfers to Asia-Pacific corridors with competitive FX margins. Regulatory compliance with AUSTRAML reporting requirements adds operational complexity.
- Point of Sale:Merchant acceptance through integrated terminal hardware and QR-code payments. Tyro's ecosystem model demonstrates working capital cross-sell potential at transaction origin.
P2P Transfers dominates transaction volume; Point of Sale is gaining share fastest as merchant acquisition accelerates.
Platform Type:
Customer type preferences for device ecosystem loyalty shape development resource allocation and feature parity requirements.
- iOS:Premium user base with higher average revenue per customer and stronger engagement with Apple Pay integration. Sydney's technology sector workforce exhibits pronounced iOS preference.
- Android:Broader demographic reach with greater market penetration in price-sensitive segments. Melbourne's diverse suburban markets show Android majority usage.
- Web-Based:Desktop access for complex product applications and business banking workflows. Small business accountants require full-featured web interfaces for multi-account management.
- Cross-Platform:Synchronized experience across mobile and desktop with consistent data architecture. Consumer Data Right interoperability mandates underpin cross-platform data portability requirements.
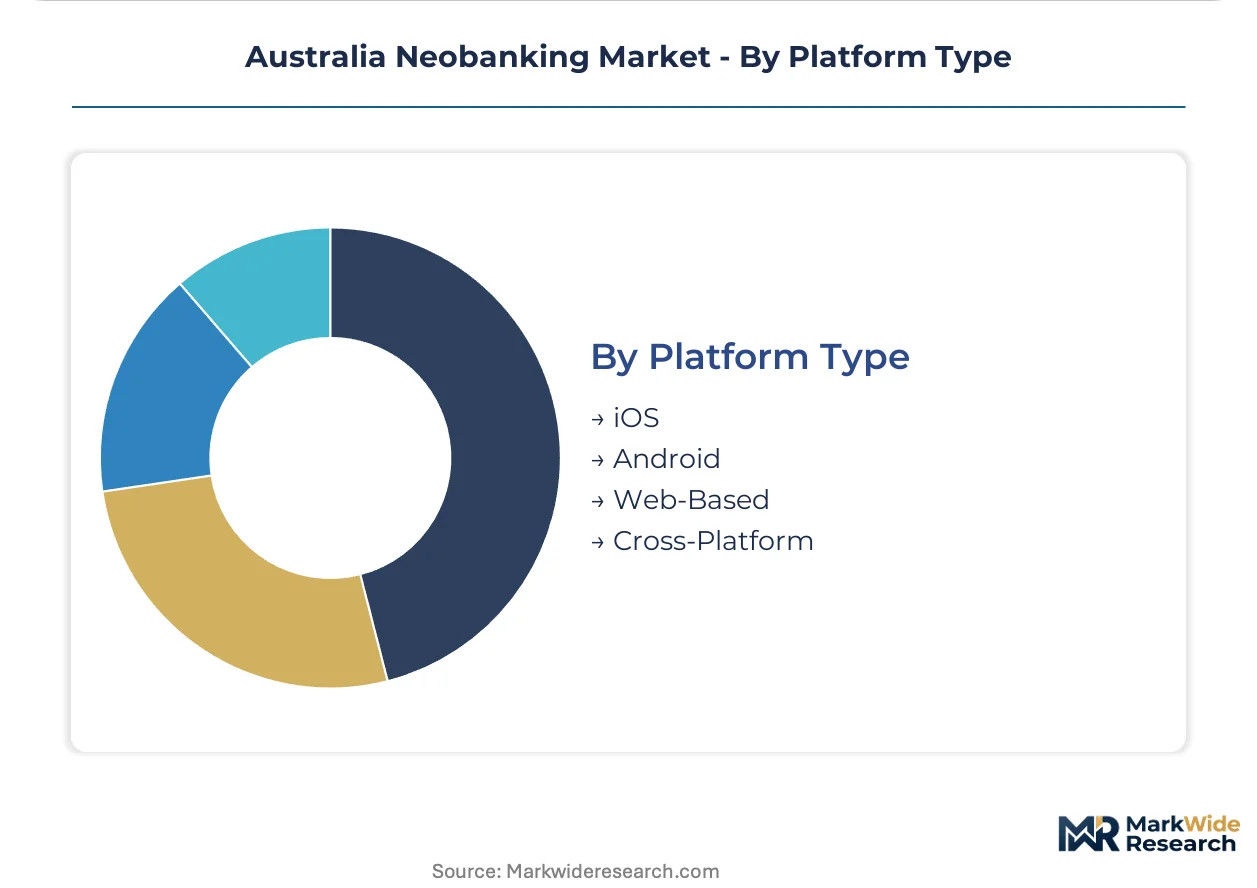
iOS captures the highest-value user base; Cross-Platform is expanding most quickly as open banking mandates force interoperability investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney's fintech talent pool and Melbourne's SME density anchor Australia's neobanking expansion. Deposit concentration and regulatory sequencing shape sub-regional competitive dynamics.
New South Wales
Tech-savvy millennials in inner-Sydney postcodes drive automated savings adoption. APRA's restricted ADI licensing framework lowers capital barriers for Sydney-based digital entrants. The Sydney CBD and surrounding technology corridors concentrate neobank headquarters and engineering talent pools.
Victoria
Melbourne's university precincts generate steep Gen Z acquisition curves as students transition to graduate banking. ASIC's design-and-distribution obligations mandate suitability screening for automated financial guidance features. The city's retail corridors accelerate merchant ecosystem adoption through bundled terminal hardware offerings.
Queensland
Brisbane's professional services workforce exhibits growing demand for real-time spending analytics. The Consumer Data Right mandates open banking data sharing, forcing interoperability investment. South-East Queensland's population growth creates expansion opportunities beyond the Sydney-Melbourne axis.
Western Australia
Perth's mining sector professionals seek cash-flow smoothing tools for irregular income patterns. Cloud engineering talent scarcity compresses hiring timelines for platform development. The state's geographic isolation intensifies reliance on mobile-first service delivery over physical presence.
South Australia
Adelaide's emerging startup ecosystem attracts second-tier neobank market entry. Third-party risk management requirements extend compliance burden to outsourced technology providers. The city's lower operational costs appeal to restricted ADI applicants seeking patient capital deployment.
Australia Neobanking Market Vendor Landscape
Global majors compete with regional champions across customer acquisition and deposit mobilization. The Australian neobanking sector exhibits tiered concentration, with full-license incumbents, restricted ADI challengers, and foreign digital entrants occupying distinct competitive positions. Three archetypes dominate: SME relationship specialists, consumer engagement platforms, and embedded finance integrators. Dominant competitive moves include strategic partnerships with accounting software providers and portfolio diversification into merchant payment ecosystems.
Within the SME-focused tier, Judo Bank and Tyro exemplify relationship-driven origination models. UP Neo Bank occupies a position among consumer-centric digital natives emphasizing automated savings triggers. Revolut represents the foreign entrant archetype leveraging global infrastructure for cross-border service delivery.
| Leading Market Players |
|---|
| BNK |
| Judo Bank |
| UP Neo Bank |
| Tyro |
| Hay |
| Alex |
| Revolut |
| Douugh |
| Volt Bank |
| Others |
Supply Flow & Price Mechanics
Venture-capital-backed neobanks operating under APRA's restricted ADI framework exercise pricing discipline through unbundled service architectures that separate core banking from premium advisory layers. This ownership structure concentrates development spend on mobile-first customer acquisition rather than branch infrastructure, compressing cost-to-serve and enabling rate competition on deposit products.
Pricing Analysis
Warranty and service bundling remains minimal across Australian neobanks, with customer support and dispute resolution treated as cost centers rather than premium differentiators. Three-tier pricing structure across premium, standard, and economy levels segments users by engagement depth and balance thresholds. Price differentiation rests on API integration complexity and real-time analytics sophistication. Cost compression in the standard tier is intensifying because cloud-native competitors match feature parity without legacy overhead. Freelancers exhibit highest price sensitivity due to irregular cash flows, while small businesses show lowest sensitivity when speed-to-decision improves working capital access.
Supply Chain Analysis
Freight and logistics costs exert minimal direct pressure on neobank operations given the absence of physical product distribution. Technology infrastructure draws from cloud service providers concentrated in the United States, Ireland, and Singapore data center regions. Core dependencies include API gateway services, identity verification platforms, and payment switching infrastructure. Single-source vulnerability concentrates in New Payments Platform access, where technical failure cascades across real-time settlement capabilities. Distribution runs through direct mobile application stores and embedded finance partnerships with accounting software providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APRA's restricted ADI licensing functions as a cost-of-compliance moat, with capital adequacy and operational maturity requirements filtering out undercapitalized entrants and protecting compliant incumbents from price-war erosion.
For Market Incumbents: Anchor deposit retention through accelerated feature parity on automated savings triggers and real-time spending analytics. Threat from Judo Bank's SME relationship model demands defensive investment in API-integrated working capital products. Channel control through exclusive accounting software partnerships protects origination volumes. For New Entrants and Emerging Players: Perth-based mining professionals represent an underserved buyer archetype seeking cash-flow smoothing tools for irregular income patterns. White-space availability concentrates in Queensland beyond the Sydney-Melbourne axis. Go-to-market through embedded finance partnerships with resource sector payroll platforms offers lowest customer acquisition cost. For Investors and Strategic Acquirers: Distressed-cycle entries favor restricted ADI applicants with demonstrated graduation pathway progress in South Australia. Long-term viability hinges on sustainable funding model proof points and governance framework maturity. Signal to watch is APRA's evolving full-license authorization timeline as inflection indicator for balance sheet scaling permission.| Strategic Initiative | Industry Significance |
|---|---|
| Core Banking Platform Migration | Restricted ADI graduation requires data architecture reconfiguration without service interruption under APRA supervision. |
| Open Banking API Integration | Consumer Data Right interoperability mandates force competitive differentiation through data aggregation capabilities. |
| Embedded Finance Partnership | API connectivity enables deposit and lending product integration into accounting software and e-commerce platforms. |
| SME Lending Origination Buildout | Direct entrepreneur engagement accelerates working capital products against legacy bank decision timelines. |
| Cloud Security Certification Investment | ASIC operational resilience expectations extend compliance burden to outsourced technology vendor ecosystems. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with neobank product executives, APRA supervisory specialists, and SME banking relationship managers combined with secondary validation from ASIC disclosure databases and New Payments Platform operator reports. Bottom-up deposit and lending volume estimates triangulated against top-down market sizing from authorized deposit-taking institution prudential returns.
Data-stream reconciliation across multiple input sources informed the analytical framework. Segmentation dimensions modeled include customer type, service tier, transaction mode, and platform ecosystem across the analysis window. CAGRs derived from trend extrapolation of restricted ADI deposit growth trajectories and full-license competitor response patterns. Forecast inputs incorporated APRA licensing pipeline visibility and cloud infrastructure capex disclosure trends from major service providers.
Revisions become necessary when APRA modifies restricted ADI graduation criteria, major cloud service providers experience operational resilience failures, or Consumer Data Right interoperability mandates shift compliance cost structures. Forecasts reflect documented assumptions about regulatory sequencing and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Corporate Banking Market
Banking
Voice Banking Market
Banking
AI and Automation in Banking Market
Banking
Blockchain in Banking Market
Banking
Cloud-Based Core Banking Market
Banking
Japan Trade Finance Market
Banking
Europe Banking-As-A-Service Market
Banking
APAC Banking-As-A-Service Market
Banking
Global Certificate of Deposit Market
Banking
Global Neo and Challenger Bank Market
Banking
Performance Bank Guarantee Market
Banking
Russia Data Analytics in Banking Market
Banking
Global Retail Core Banking Systems Market
Banking
Virtual Teller Machine (VTM) Market
Banking
Africa Data Analytics in Banking Market
Banking
Disaster Recovery in Banking Market