
 China Retail Banking System Market | 2026-2036
China Retail Banking System Market Size, Share, and Industry Trends Forecast 2026-2036
China Retail Banking System Market Insights
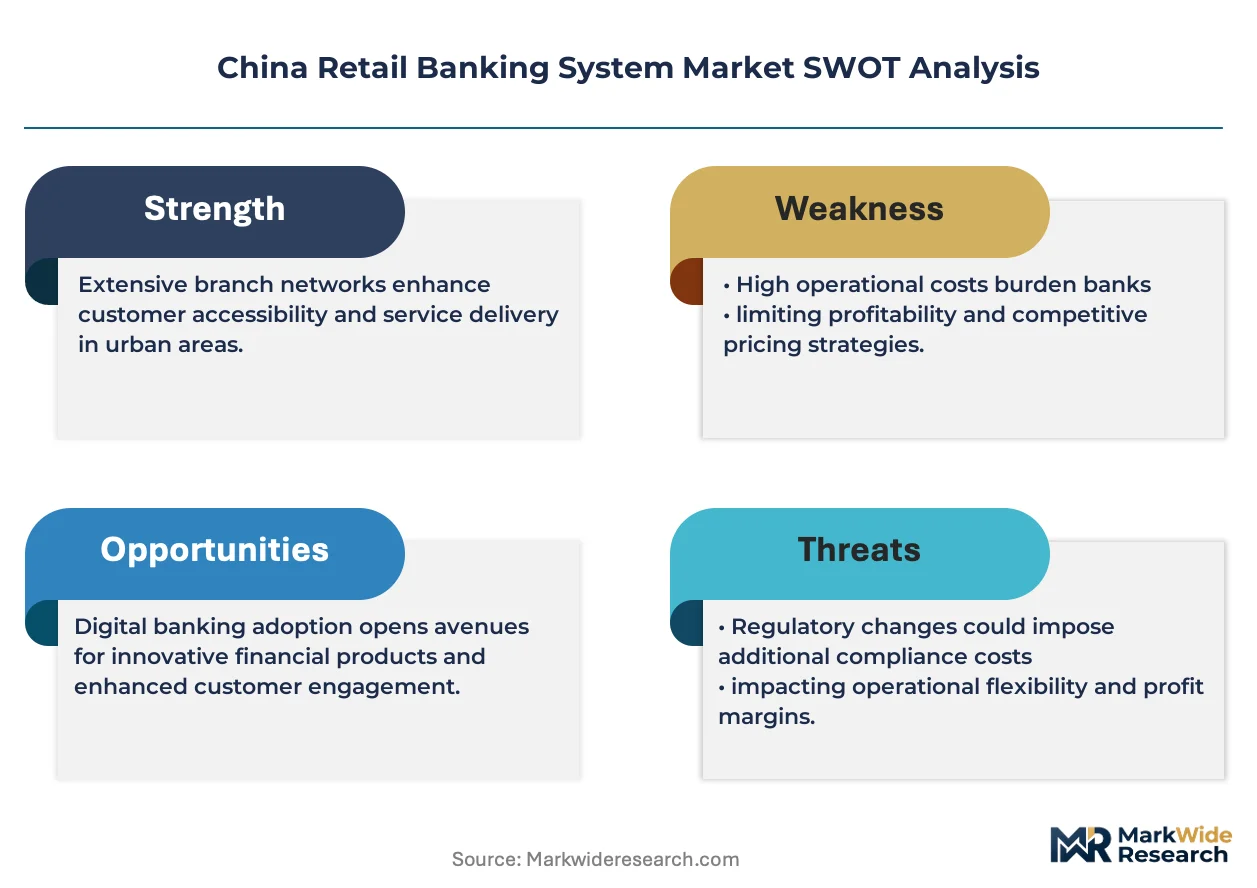
Asset-light distribution models and third-party platform leasing are narrowing the capital barrier for mid-tier banks to deploy full-service retail architectures. Industrial and Commercial Bank of China Ltd. leverages its state-backed balance sheet to sustain nationwide branch digitization. China Merchants Bank Co., Ltd. differentiates through proprietary mobile ecosystems that anchor affluent customer relationships. Ping An Bank Co., Ltd. competes by integrating insurance and banking data streams across its technology stack.
The China Retail Banking System encompasses the software, infrastructure, and service delivery mechanisms that process deposits, loans, payments, and wealth products for individual and small-business clients, typically operating through core banking platforms with sub-50 millisecond transaction latency and API-first architectures. Its primary commercial purpose is to reduce unit costs per transaction while enabling personalized product recommendation engines. Deposit products and loan products occupy the largest revenue pools given their foundational role in household balance sheets, while wealth management and investment products represent the fastest-expanding margin segments as fee-based income displaces net interest margins. Artificial intelligence and robotic process automation are reshaping back-office cost structures, though mobile banking remains the dominant customer-facing channel by transaction volume.
SAMR enforces data governance and consumer protection standards that dictate platform architecture choices for all licensed retail banks, while the PBOC's digital yuan framework and MEE cybersecurity requirements constrain how institutions design cloud infrastructure and cross-border data flows. BIS certification protocols for financial IT systems add compliance layers that favor incumbent vendors with established testing relationships. Stakeholders must weigh the pace of central bank digital currency integration against the fragmentation risk of proprietary fintech ecosystems.
Market Dynamics
PBOC's digital yuan pilots and SAMR's data governance mandates are compressing architecture refresh cycles across tier-one and tier-two city banks. Institutions must rebuild core platforms to sub-50 millisecond latency standards while integrating central bank digital currency rails.
Growth Catalysts
- Wealth management adoption:High-net-worth households in Shanghai, Beijing, and Shenzhen are migrating deposits into fee-based investment products, forcing banks to deploy AI-driven recommendation engines.
- Dual carbon goals:MEE's green finance disclosure requirements are mandating carbon-tracking modules in retail banking software stacks, creating upgrade demand.
- API-first mandates:Open banking protocols are requiring institutions to expose core functions to third-party fintechs, accelerating middleware procurement.
Market Restraints
- Cloud infrastructure compliance:SAMR's cross-border data flow restrictions and MEE cybersecurity requirements force on-premise or sovereign cloud deployments, raising capital intensity.
- Vendor concentration:BIS certification protocols favor incumbent IT vendors with established testing relationships, limiting procurement flexibility for mid-tier banks.
- Core system fragility:Legacy mainframe architectures in provincial banks resist API integration, creating technical debt that constrains mobile platform expansion.
Strategic Opportunities
- Tier-three city penetration:Mobile banking infrastructure remains underdeployed in central and western provinces where branch density exceeds digital adoption.
- Embedded finance convergence:Retail banking APIs are hybridizing with e-commerce and mobility platforms, creating distribution partnerships beyond traditional channels.
- Digital yuan integration services:PBOC's expanding CBDC pilots create white space for wallet infrastructure and merchant onboarding solutions.
Industry Challenges
- Legacy system integration:Core banking modernization requires parallel-running old and new architectures during multi-year transitions, straining operational bandwidth.
- Compliance talent scarcity:Shortages of engineers fluent in both SAMR data governance and MEE cybersecurity standards are delaying platform certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Retail Banking System Market |
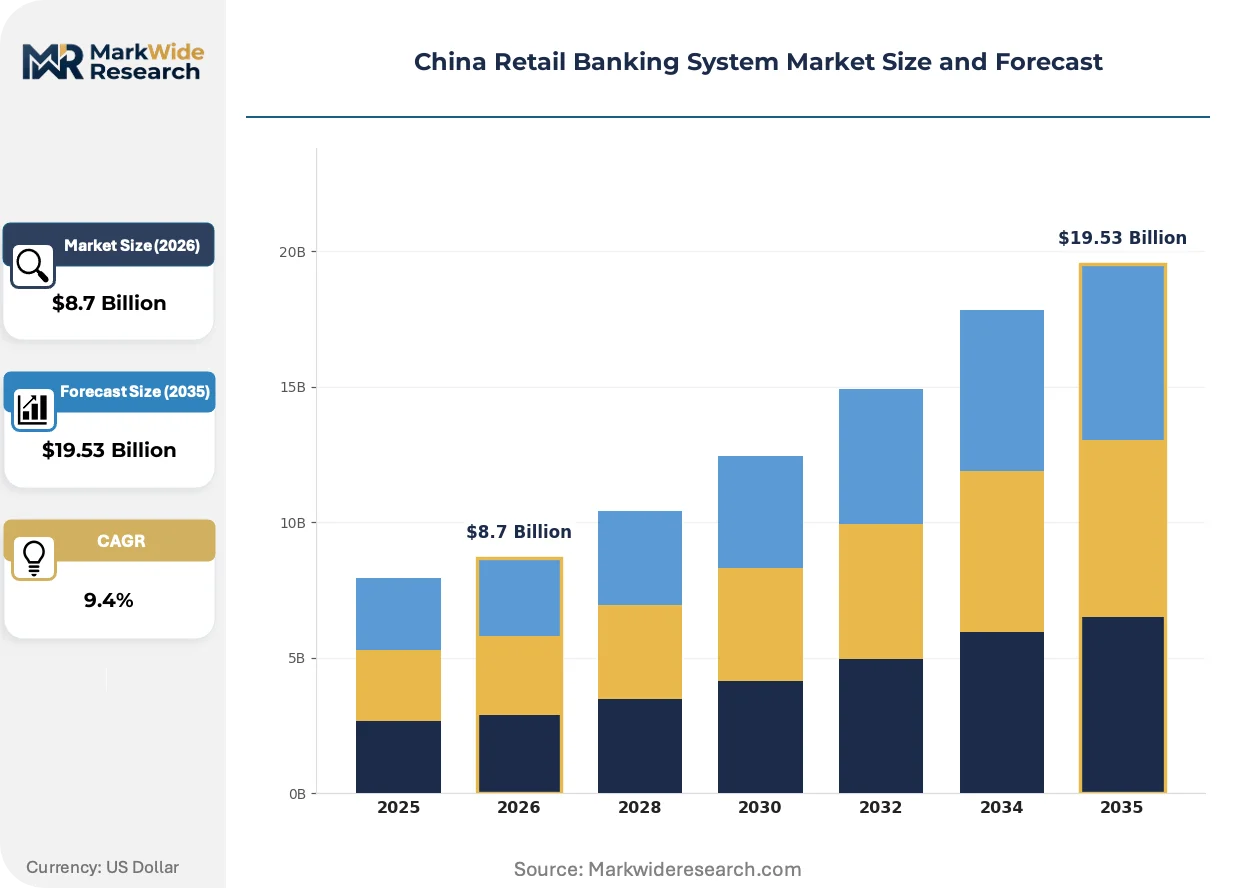
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Loans, Credit Cards, Savings Accounts, Wealth Management Customer Type: Individual Consumers, SMEs, High-Net-Worth Individuals, Corporate Clients Technology: Mobile Banking, Online Banking, Robotic Process Automation, Artificial Intelligence Product Type: Deposit Products, Loan Products, Investment Products, Insurance Products |
| Companies Covered | Industrial and Commercial Bank of China Ltd., China Construction Bank Corp., Agricultural Bank of China Ltd., Bank of China Ltd., Bank of Communications Co., Ltd., Postal Savings Bank of China Co., Ltd., China Merchants Bank Co., Ltd., Ping An Bank Co., Ltd., China CITIC Bank Corp. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Retail Banking System Market Trends and Innovations
Artificial intelligence and distributed ledger architectures are compressing transaction costs while fragmenting service delivery across non-bank platforms. Institutions are racing to embed banking functions into daily commerce workflows.
Core banking platforms are hybridizing with containerized microservices architectures. Tier-one banks in Shanghai and Shenzhen are adopting Kubernetes-orchestrated workloads to decouple deposit processing from loan origination systems. This architecture is hybridizing vendor relationships as institutions mix proprietary development with licensed modules.
SAMR's data governance standards and PBOC's digital yuan framework are mandating real-time transaction monitoring and immutable audit trails. Banks must rebuild data lakes to satisfy granular consent management and localization requirements. Wealth management divisions face the steepest compliance burden as customer profiling algorithms fall under heightened scrutiny.
Affluent households are unbundling banking relationships across multiple fintech apps rather than consolidating with single institutions. Mobile-first wealth platforms are capturing investment flows that previously cycled through branch-advised deposit products. This behavioral shift is most pronounced in Beijing and Shenzhen where super-app ecosystems dominate daily financial interactions.
China Retail Banking System Market Segmentation
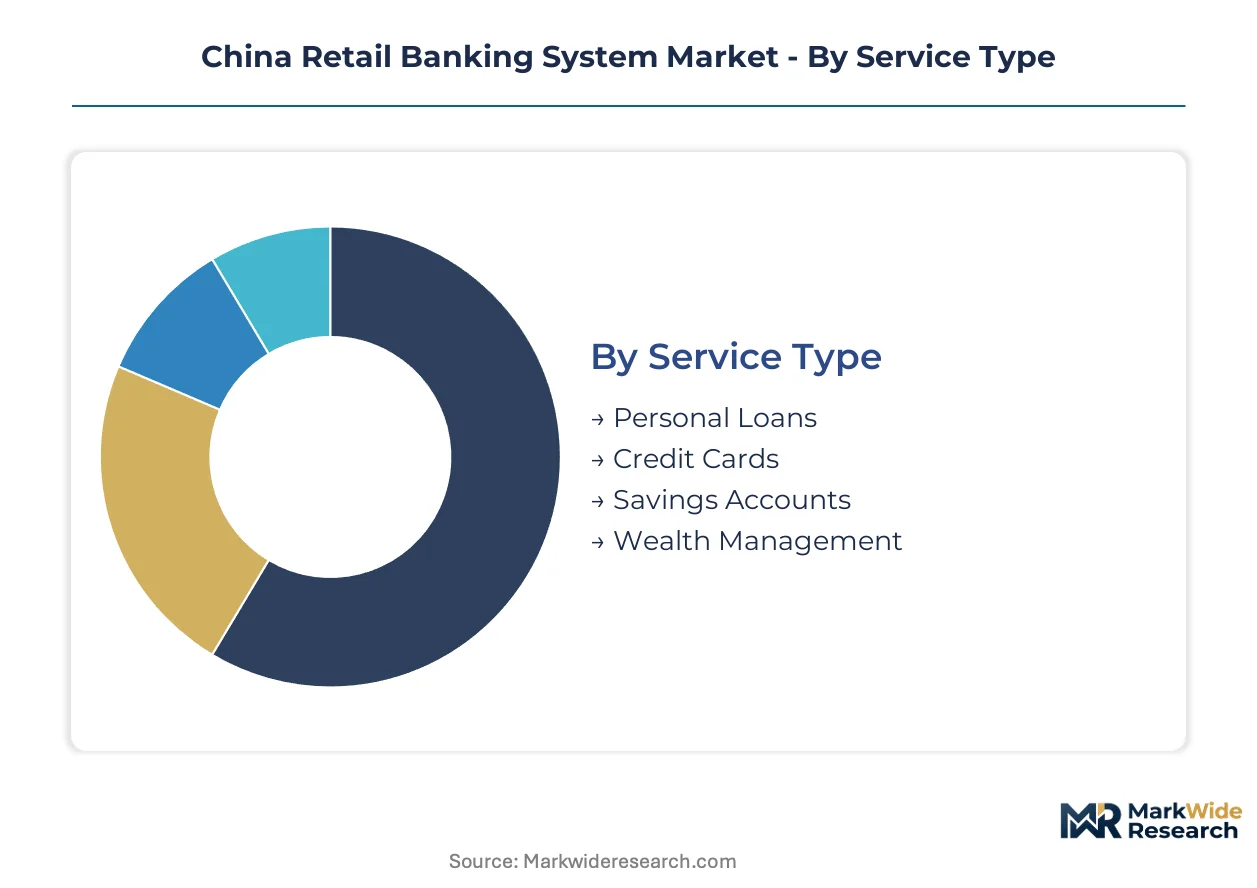
Retail banking systems in China exhibit divergent upgrade cycles across service lines, with wealth management platforms requiring continuous algorithmic refinement while deposit infrastructure demands stability. Customer migration patterns between digital channels force vendors to architect modular systems that isolate high-velocity segments from core transactional workloads.
Service Type:
After-sales service intensity varies sharply across service lines, with wealth management demanding ongoing portfolio rebalancing support while deposit products require minimal post-implementation intervention.
- Personal Loans:Origination platforms integrate credit scoring engines with PBOC credit bureau feeds, processing automated underwriting decisions in under two minutes. Demand concentrates in tier-two cities where provincial banks compete against fintech lenders through faster approval workflows.
- Credit Cards:Transaction processing systems manage real-time authorization against dynamic fraud models, requiring sub-50 millisecond response times. Shanghai and Beijing issuers drive replacement demand as EMV migration completes and contactless infrastructure expands.
- Savings Accounts:Core deposit systems prioritize ledger integrity and regulatory reporting over feature velocity.
- Wealth Management:Fee-based advisory platforms require continuous compliance updates as SAMR tightens algorithmic disclosure requirements.
Deposit products hold the largest share; momentum sits with wealth management as fee income displaces net interest margins.
Customer Type:
Cost-to-serve economics diverge dramatically across customer tiers, with high-net-worth segments justifying dedicated relationship management modules while mass retail relies on self-service automation.
- High-Net-Worth Individuals:Private banking platforms integrate trust structuring, cross-border custody, and alternative investment access through unified dashboards. Shenzhen and Beijing wealth concentrations drive demand for multi-currency reporting and offshore connectivity.
- SMEs:Business banking stacks combine cash management, trade finance, and payroll processing within single sign-on environments. Provincial banks in Zhejiang and Jiangsu prioritize SME modules to capture manufacturing supply chain deposits.
- Individual Consumers:Mass retail architectures emphasize mobile-first onboarding and automated savings products.
- Corporate Clients:Treasury workstations require API connectivity to enterprise resource planning systems.
Individual consumers hold the largest share; momentum sits with high-net-worth individuals as tier-one city affluence deepens.
Technology:
Implementation complexity scales with architectural abstraction, with artificial intelligence layers requiring specialized MLOps infrastructure while mobile banking builds on standardized development frameworks.
- Artificial Intelligence:Recommendation engines and credit risk models demand continuous retraining pipelines, specialized inference hardware, and explainability audits for SAMR compliance. Tier-one banks in Shanghai deploy proprietary AI labs to differentiate wealth advisory outputs.
- Robotic Process Automation:Back-office automation targets know-your-customer document processing and regulatory report generation, delivering measurable headcount reduction in provincial bank operations centers.
- Mobile Banking:Super-app integration dominates customer-facing development roadmaps.
- Online Banking:Browser-based platforms retain relevance for corporate treasury functions.
Mobile banking holds the largest share; artificial intelligence is expanding most quickly as personalization becomes a competitive battleground.
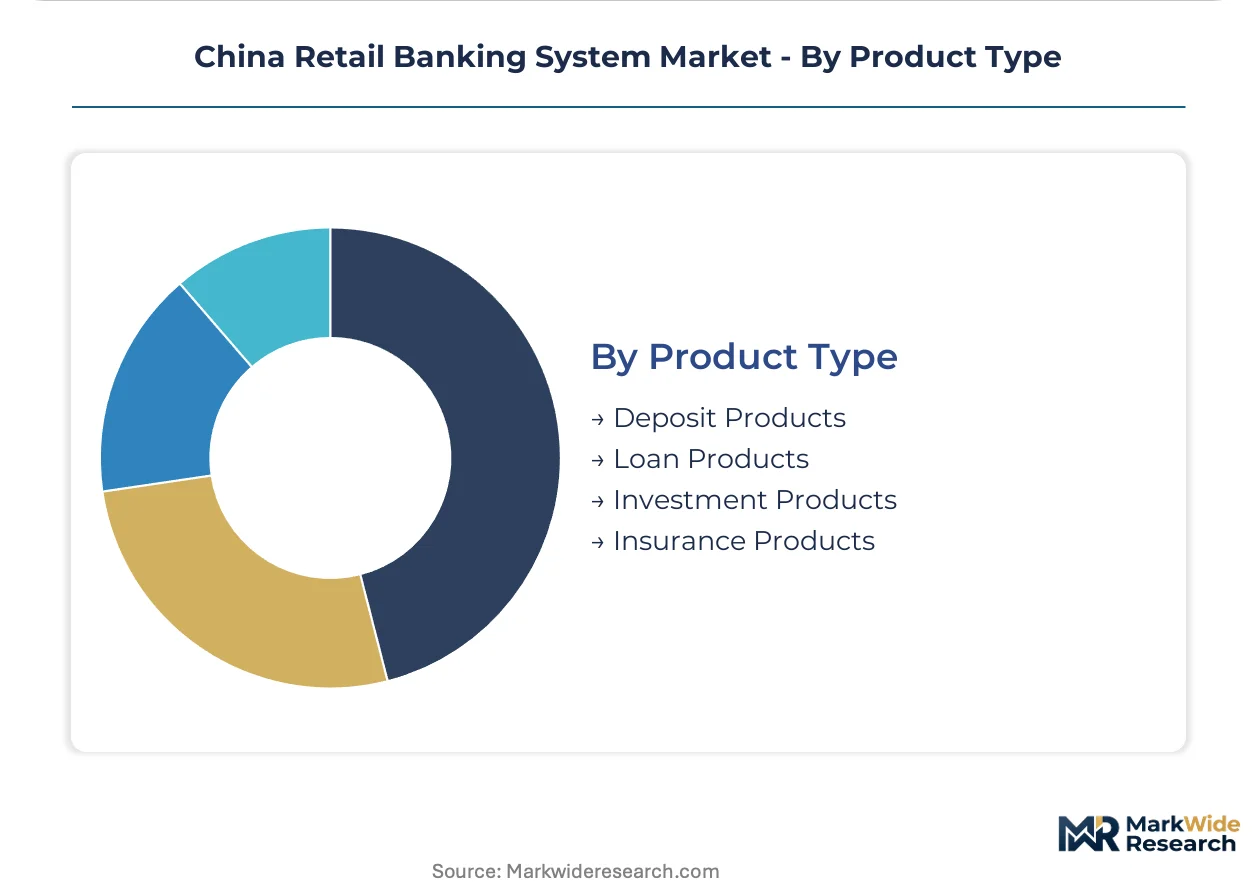
Product Type:
Margin structure varies fundamentally across product categories, with investment products commanding premium pricing for advisory content while deposit products compete on operational efficiency.
- Deposit Products:Core banking modules manage demand deposits, time deposits, and structured savings with emphasis on ledger accuracy and PBOC reserve reporting. Provincial banks in central China maintain mainframe-dependent architectures that resist cloud migration.
- Loan Products:Origination and servicing platforms span mortgages, consumer credit, and working capital facilities, with automated collateral valuation becoming critical for mortgage growth in tier-three cities.
- Investment Products:Fund distribution and custody platforms require real-time NAV feeds and regulatory disclosure engines.
- Insurance Products:Bancassurance integration demands policy administration connectivity with carrier core systems.
Deposit products hold the largest share; investment products are gaining share fastest as household financial asset allocation shifts from savings to markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned commercial banks concentrate procurement authority in Beijing and Shanghai, while joint-stock banks and city commercial banks distribute demand across provincial capitals. Tier-one cities drive platform modernization spending. Western provinces lag in core system replacement cycles.
Yangtze River Delta
Shanghai anchors wealth management platform demand as high-net-worth households migrate deposits into fee-based products. SAMR's algorithmic disclosure requirements force continuous compliance updates on advisory engines. Industrial and Commercial Bank of China Ltd. deploys proprietary mobile ecosystems across Jiangsu and Zhejiang manufacturing corridors.
Pearl River Delta
Shenzhen's fintech ecosystem accelerates API-first banking architecture adoption among joint-stock institutions. PBOC's digital yuan pilots mandate real-time transaction monitoring infrastructure upgrades. Ping An Bank Co., Ltd. integrates insurance-banking data streams across Guangdong's SME manufacturing clusters.
Beijing-Tianjin-Hebei
Policy banks and state-owned giants concentrate core banking procurement in the capital region. MEE cybersecurity requirements enforce sovereign cloud deployments for transaction data. China Construction Bank Corp. sustains nationwide branch digitization from its Beijing technology headquarters.
Sichuan-Chongqing
Provincial banks in the southwest lag tier-one cities by two to three upgrade cycles on legacy mainframe architectures. BIS certification protocols favor incumbent IT vendors with established testing relationships in Chengdu. City commercial banks here struggle with API integration for mobile platform expansion.
Western China
Central and western provinces exhibit the widest branch density-to-digital adoption gap in the national market. Dual carbon goals mandate carbon-tracking modules in retail banking software stacks across Shaanxi and Gansu. Postal Savings Bank of China Co., Ltd. leverages its rural network to capture underpenetrated mobile banking demand.
China Retail Banking System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure. State-owned commercial banks dominate procurement volume through centralized technology budgets. Joint-stock banks differentiate through proprietary mobile ecosystems and wealth management specialization. City commercial banks and rural cooperatives concentrate demand for standardized core banking modules. Competitive moves center on strategic partnerships with fintech infrastructure providers and geographic expansion into tier-three cities through leased platform architectures.
Among state-backed institutions, Industrial and Commercial Bank of China Ltd. and China Construction Bank Corp. exemplify the scale-driven archetype that sustains nationwide branch digitization through balance sheet capacity. Within the joint-stock tier, China Merchants Bank Co., Ltd. occupies a position emphasizing affluent customer relationships through mobile-first wealth platforms. These three entities collectively represent the competitive spectrum from state-mandated universal coverage to specialized high-net-worth segmentation.
| Leading Market Players |
|---|
| Industrial and Commercial Bank of China Ltd. |
| China Construction Bank Corp. |
| Agricultural Bank of China Ltd. |
| Bank of China Ltd. |
| Bank of Communications Co., Ltd. |
| Postal Savings Bank of China Co., Ltd. |
| China Merchants Bank Co., Ltd. |
| Ping An Bank Co., Ltd. |
| China CITIC Bank Corp. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Domestic IT vendor concentration in Beijing and Shanghai anchors procurement costs for core banking platforms, concentrating margin pools with BIS-certified incumbents who command premium licensing fees. Provincial banks absorb this pricing power differential through sovereign cloud deployment mandates that inflate capital intensity.
Pricing Analysis
Certification level under BIS protocols creates the primary spread between tier-one and tier-three bank procurement costs. Licensing models stratify across perpetual enterprise licenses, subscription-based SaaS tiers, and project-based implementation fees. SAMR compliance burdens are compressing margins for mid-tier institutions forced into parallel legacy-modernization runs. Mass retail banks exhibit highest price sensitivity due to thin net interest margins, while state-backed giants absorb certification premiums through balance sheet scale.
Supply Chain Analysis
Export-control regimes on advanced semiconductors constrain GPU and AI accelerator flows into domestic cloud infrastructure builds. Hardware supply concentrates in Taiwan, South Korea, and the United States for high-performance computing components. Software licensing draws from proprietary core banking stacks developed in Beijing, Shanghai, and Hangzhou. Single-source vulnerability sits with NVIDIA-dependent AI training clusters. Distribution runs through state-owned procurement consortia and direct vendor relationships with tier-one banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PBOC's digital yuan expansion and SAMR's algorithmic governance mandates constitute a dual regulatory inflection reshaping competitive economics. Institutions must recalibrate technology investment against compliance velocity.
For Market Incumbents: Entrench API-first architectures through backward integration into middleware development, insulating against fintech disintermediation. Accelerate BIS certification pipelines to lock out emerging domestic competitors. Prioritize tier-three city branch digitization to capture Postal Savings Bank's rural network advantage before provincial banks modernize. For New Entrants and Emerging Players: Build out white-label core banking modules for city commercial banks stranded on legacy mainframes. Target Sichuan-Chongqing and western provinces where incumbent vendor relationships lag tier-one standards by two to three upgrade cycles. Pursue sovereign cloud partnerships with provincial governments as the primary go-to-market channel. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fintech infrastructure specialists holding SAMR compliance certifications but lacking balance sheet scale. Long-term viability hinges on digital yuan integration capabilities and AI-driven wealth management differentiation. Watch PBOC CBDC pilot expansion announcements as the critical signal for platform modernization demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Yuan Wallet Infrastructure | PBOC pilot expansion mandates real-time transaction monitoring stack upgrades across tier-two banks. |
| AI-Driven Wealth Advisory Platform | SAMR algorithmic disclosure requirements force continuous compliance investment in recommendation engines. |
| Sovereign Cloud Partnership | MEE cybersecurity mandates accelerate on-premise deployment partnerships with provincial technology consortia. |
| API-First Core Modernization | Open banking protocols require institutions to expose deposit functions to third-party fintech ecosystems. |
| Carbon-Tracking Module Integration | Dual carbon goals mandate MEE-compliant green finance disclosure capabilities in retail software stacks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with retail banking technology executives, SAMR compliance officers, and provincial bank procurement leads; and secondary validation against PBOC policy circulars, BIS certification registries, and MEE cybersecurity disclosure filings. Bottom-up triangulation across vendor shipment records and top-down reconciliation against tier-one bank technology budgets anchored market sizing.
Forecast inputs span service type segmentation, customer tier economics, and technology deployment models across the projection horizon. CAGRs derive from regression analysis of historical platform replacement cycles calibrated against regulatory mandate timelines. Industry-specific inputs include PBOC digital yuan pilot expansion trajectories and SAMR data governance implementation phases.
Sensitivities concentrate around PBOC CBDC rollout acceleration and SAMR enforcement intensity on algorithmic disclosure. Forecasts assume stable cross-border data flow restrictions and continued BIS certification protocol continuity. Material shifts in central bank digital currency integration timelines or MEE cybersecurity requirement expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
In Vitro Fertilization Banking Services Market
Banking
Cybersecurity in Banking Market
Banking
Singapore Neobanking Market
Banking
Japan Data Analytics in Banking Market
Banking
ATM Market
Banking
Canada Data Analytics in Banking Market
Banking
Virtual Teller Machine (VTM) Market
Banking
Southeast Asia Commercial Banking Market
Banking
Germany Neobanking Market
Banking
Mobile Banking Market
Banking
South Korea Data Analytics in Banking Market
Banking
US Data Analytics in Banking Market
Banking
Payment Bank Solutions Market
Banking
Global Retail Core Banking Systems Market
Banking
Armenia Banking Market
Banking
Smart ATM Market