
 Banking Maintenance Support and Services Market | 2026-2036
Banking Maintenance Support and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Maintenance Support and Services Market Outlook
ISO 20022 certification for payment messaging is reorganizing vendor eligibility across the Banking Maintenance Support and Services landscape, forcing maintenance providers to demonstrate protocol fluency. FIS sustains its dominance through captive servicing of core banking platforms installed at tier-one institutions. HCL Technologies Limited anchors its position with labor-arbitraged delivery centers supporting legacy mainframe environments. Temenos AG competes by specializing in cloud-native maintenance workflows for digital-first banks.
Banking Maintenance Support and Services encompasses the ongoing technical upkeep, repair, and optimization of financial infrastructure spanning ATM fleets, core banking software, network operations centers, and cybersecurity architectures. Service delivery typically operates under strict SLAs mandating uptime thresholds above 99.9% for critical payment systems and sub-four-hour response windows for hardware failures. Software Maintenance commands the largest revenue pool as institutions delay core system replacements in favor of incremental upgrades. Cloud Computing represents the fastest-expanding technology dimension, displacing on-premise maintenance contracts with subscription-based platform support. ATM Support remains structurally mature in developed markets while experiencing renewal demand in emerging economies with expanding cash-access networks.
The Federal Reserve, RBI, and ECB collectively shape maintenance priorities through operational resilience mandates, data localization requirements, and stress-testing protocols that dictate system availability standards. BIS guidelines on cyber risk management further compel banks to maintain dedicated security operations centers with 24/7 monitoring capabilities. Stakeholders must weigh the capital efficiency of outsourced maintenance against the control retained through in-house technical teams as regulatory scrutiny intensifies.
Market Dynamics
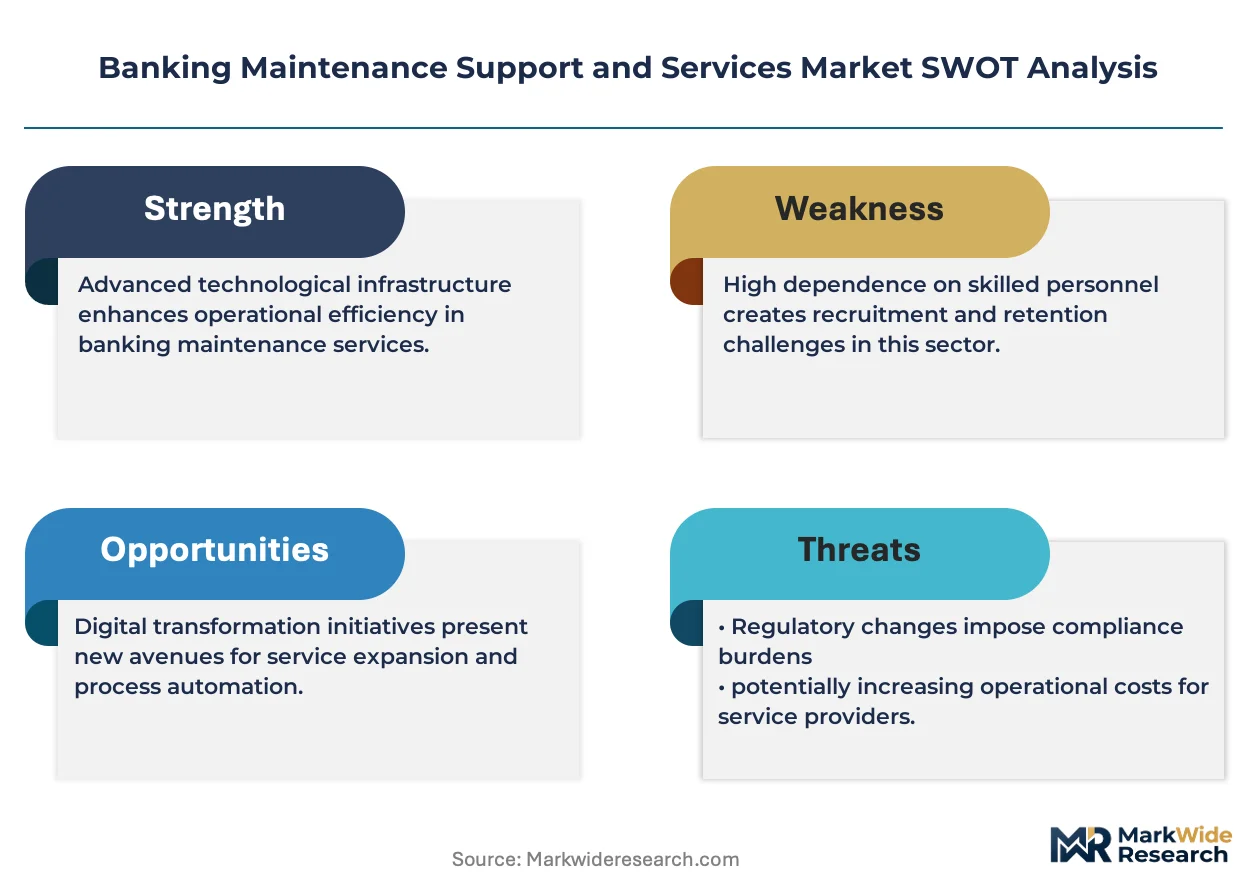
The Federal Reserve's operational resilience mandates are compressing maintenance response windows and forcing banks to abandon break-fix models in favor of predictive service architectures with guaranteed uptime commitments.
Growth Catalysts
- ISO 20022 protocol migration:Payment infrastructure upgrades across the United States, India, and the Eurozone are generating sustained demand for certified maintenance providers fluent in the new messaging standard.
- ATM fleet modernization cycles:Regional banks in India and the United States are expanding hardware support contracts as legacy cash-dispensing networks undergo phased replacement programs.
- Cloud-native core banking:Digital-first institutions are outsourcing platform maintenance to specialized vendors capable of managing containerized environments and API-driven service delivery.
Market Restraints
- Mainframe talent scarcity:The shrinking pool of engineers proficient in COBOL and legacy IBM systems concentrates maintenance capacity in a handful of specialized labor markets.
- Data localization mandates:India's RBI requirements for domestic storage of financial records fragment service delivery models and inflate compliance overhead for multinational providers.
- Capital intensity of 24/7 operations:Regulatory uptime requirements above 99.9% demand redundant network operations centers with dedicated security operations capabilities.
Strategic Opportunities
- Metropolitan corridor digitization:India's public sector banks are accelerating legacy infrastructure replacement in Mumbai, Delhi, and Bangalore, creating concentrated demand spikes for maintenance services.
- Subscription-based platform support:Cloud computing maintenance contracts are displacing traditional on-premise service agreements with recurring revenue structures favored by capital-constrained institutions.
- Cybersecurity operations center consolidation:BIS guidelines on cyber risk management are compelling mid-tier banks to outsource 24/7 threat monitoring to specialized security vendors.
Industry Challenges
- Legacy system integration complexity:Maintenance providers must bridge decades-old core banking architectures with modern API layers without disrupting transaction processing.
- ISO 20022 certification timelines:Vendors face compressed qualification windows to demonstrate protocol fluency before eligibility deadlines set by major payment clearing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Maintenance Support and Services Market |
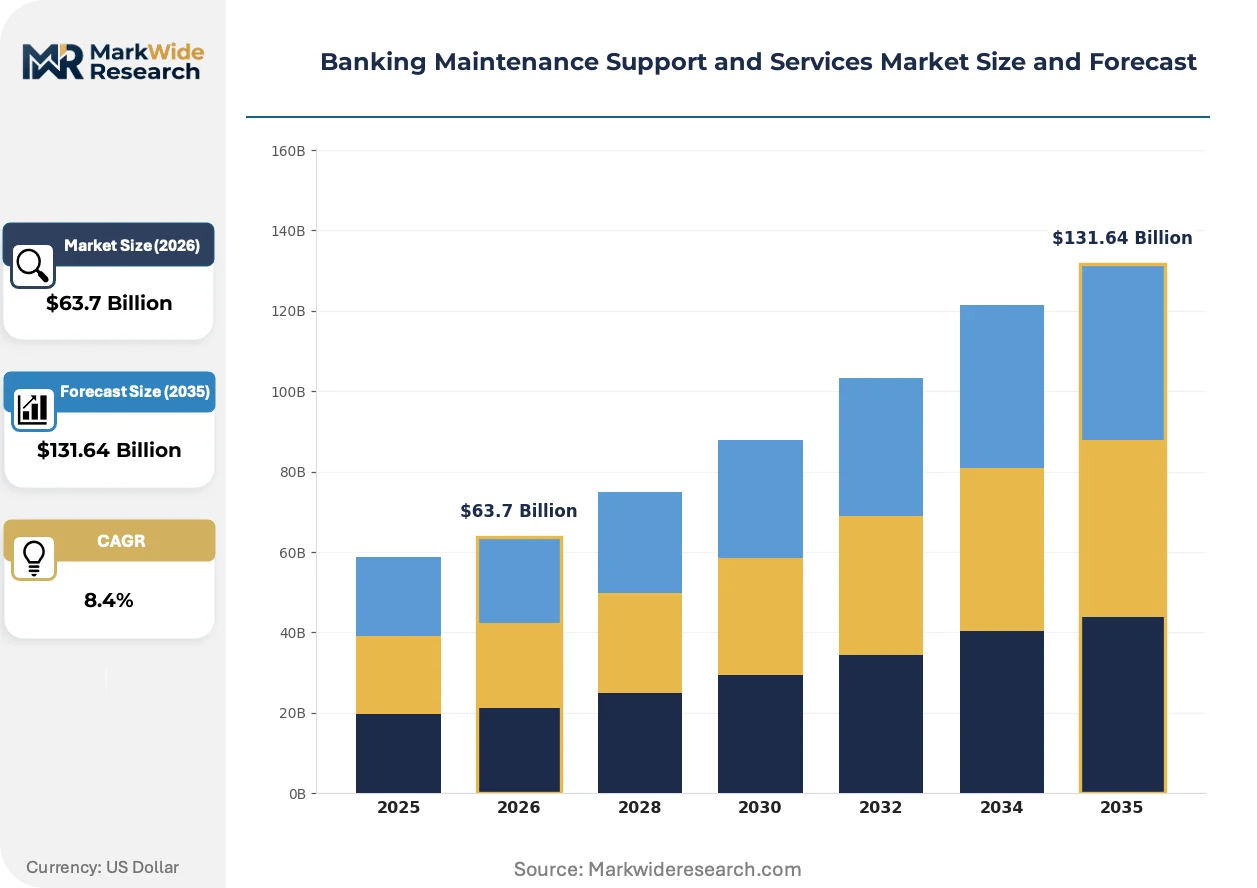
| Market Size in 2026 | $63.7 Billion |
| Market Size in 2035 | $131.64 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: ATM Support, Software Maintenance, Network Management, Hardware Repair Client Type: Retail Banks, Commercial Banks, Investment Banks, Credit Unions Technology: Cloud Computing, Data Analytics, Cybersecurity Solutions, Blockchain End User: Banking Institutions, Financial Service Providers, Payment Processors, Online Banks |
| Companies Covered | FIS (Fidelity National Information Services), Fiserv, Inc., Jack Henry & Associates, Microsoft, SAP, Oracle, Capgemini, Temenos AG, HCL Technologies Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Maintenance Support and Services Market Strategic Shifts
Cloud-native maintenance workflows are reorganizing competitive positioning as institutions abandon perpetual license models. The transition favors vendors with API-first architectures and consumption-based pricing.
Containerized microservices architectures are displacing monolithic core banking maintenance contracts. Digital-first banks in Singapore and the Netherlands are adopting Kubernetes-based platform support at twice the rate of traditional institutions. This shift is compressing vendor margins on legacy upgrade projects while expanding recurring revenue from orchestration-layer management.
REACH chemical compliance and the EU AI Act are reshaping hardware maintenance protocols for ATM fleets across Germany, France, and Italy. Component suppliers must now certify circuit boards and display assemblies against restricted substance lists. European banks are consolidating vendor panels to reduce audit duplication, favoring maintenance providers with integrated compliance documentation.
Outcome-based service level agreements are replacing time-and-material contracts in the United Kingdom and Australia. Tier-two institutions are purchasing guaranteed uptime rather than engineer hours, transferring operational risk to maintenance vendors. This procurement evolution demands predictive analytics capabilities that most regional service providers lack, creating acquisition targets for platforms with mature IoT sensor networks.
Banking Maintenance Support and Services Market Segmentation
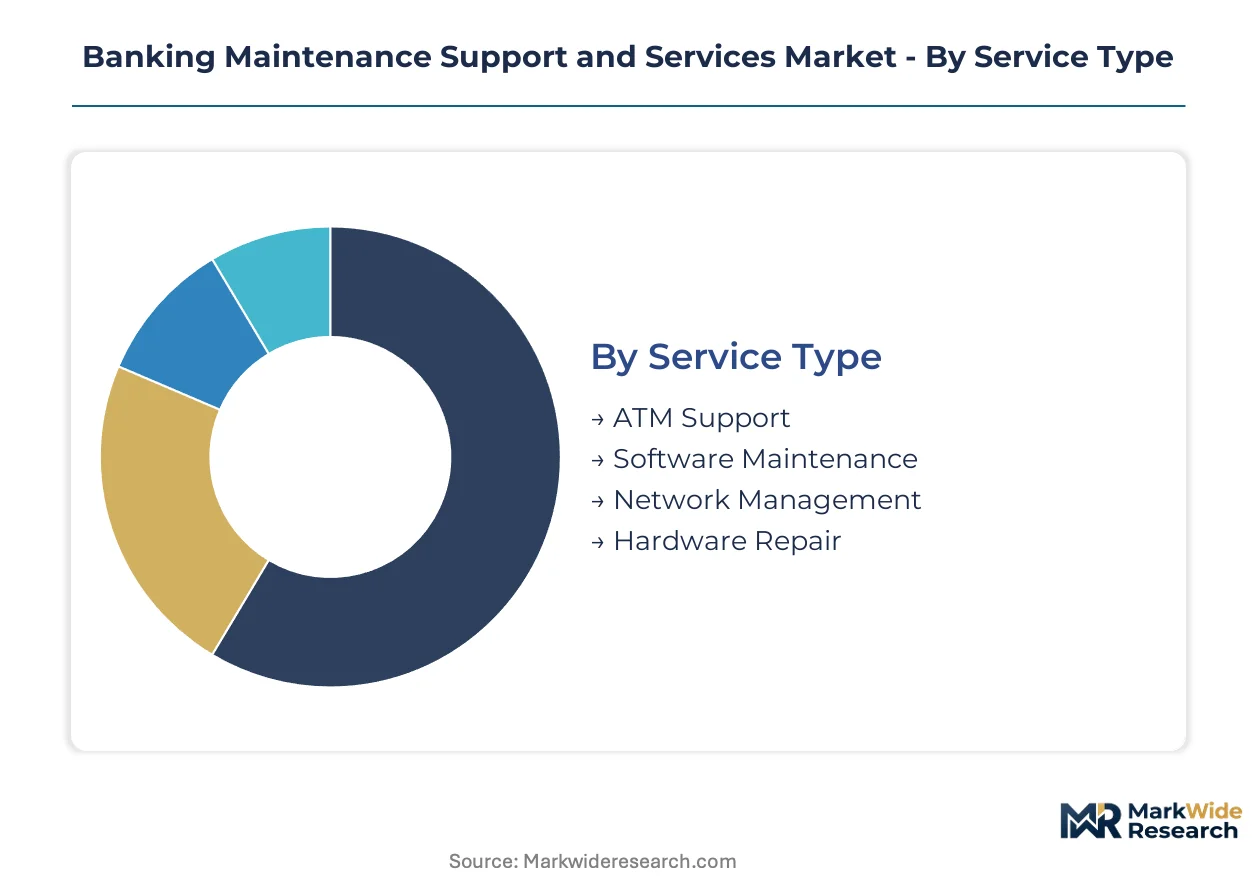
Banking maintenance contracts flow through distinct procurement channels shaped by regulatory mandates, technology maturity, and institutional risk appetite. Segment boundaries increasingly blur as cloud-native architectures unify service delivery models.
Service Type:
Channel mix varies sharply by service complexity — ATM fleets route through hardware specialists, software layers consolidate under platform vendors, while network operations increasingly flow through managed security providers.
- Software Maintenance:Encompasses patch management, version upgrades, and API layer optimization for core banking platforms. Demand concentrates at tier-one institutions in the United States and India delaying full system replacements in favor of incremental modernization. The Federal Reserve's ISO 20022 deadlines compress vendor certification timelines.
- ATM Support:Covers cash dispenser upkeep, card reader calibration, and compliance hardware servicing. India's public sector banks in Mumbai and Delhi corridors drive renewal demand as legacy fleets undergo phased replacement programs under RBI operational resilience guidelines.
- Network Management:Routing, switching, and bandwidth optimization for payment system interconnectivity.
- Hardware Repair:Break-fix and preventive maintenance for server infrastructure, storage arrays, and branch peripherals.
By volume, ATM Support leads. By growth pace, Software Maintenance is ahead.
Client Type:
Cost tier segmentation separates capital-constrained institutions pursuing subscription models from balance-sheet-heavy banks retaining captive technical teams.
- Retail Banks:Branch-heavy networks with distributed ATM fleets and high-touch customer service infrastructure. Regional banks across the United States expand support contracts as branch modernization accelerates under Fed operational resilience mandates.
- Commercial Banks:Transaction-volume-intensive institutions with complex treasury and trade finance system requirements. India's metropolitan banking corridors in Bangalore and Chennai generate concentrated demand for core platform maintenance.
- Investment Banks:Low-latency trading infrastructure and compliance-heavy research platform environments.
- Credit Unions:Member-owned institutions with constrained IT budgets favoring outsourced managed services.
By contract count, Retail Banks dominate. By contract value, Commercial Banks command premium pricing.
Technology:
Application focus determines vendor selection — cloud-native stacks attract platform specialists, cybersecurity layers consolidate under SOC operators, while blockchain remains experimental.
- Cloud Computing:Container orchestration, serverless architecture management, and multi-tenant platform support. Digital-first banks in Singapore and the Netherlands adopt Kubernetes-based maintenance at accelerated rates, displacing perpetual license models with consumption-based contracts.
- Cybersecurity Solutions:24/7 threat monitoring, incident response, and compliance reporting for security operations centers. BIS guidelines compel mid-tier institutions to outsource dedicated SOC capabilities, transferring operational risk to specialized vendors.
- Data Analytics:Predictive maintenance algorithms and customer insight platform optimization.
- Blockchain:Distributed ledger infrastructure maintenance for pilot payment and settlement applications.
By revenue concentration, Cybersecurity Solutions leads. By expansion trajectory, Cloud Computing is climbing the fastest.
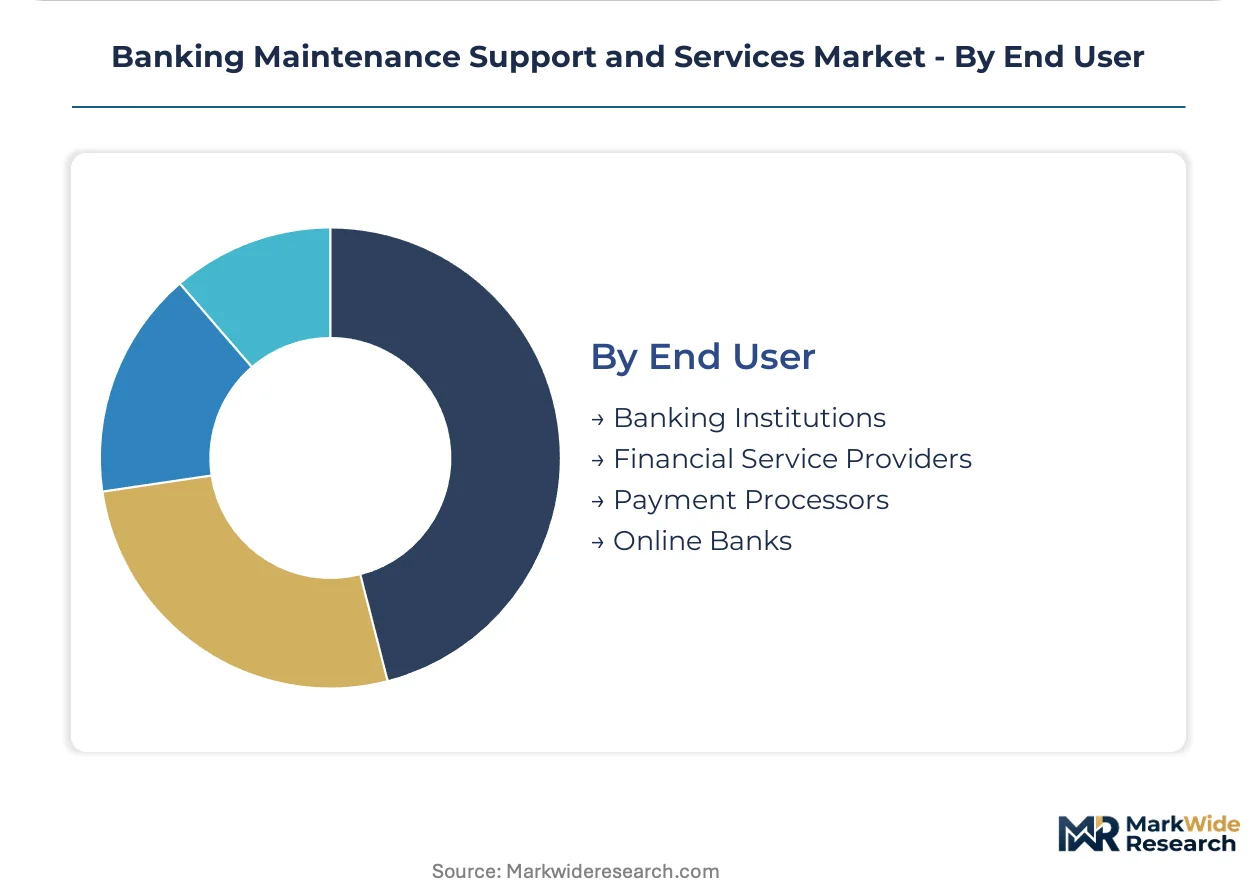
End User:
Geography and regulatory jurisdiction fragment service delivery — domestic banks favor local maintenance partners, payment processors require cross-border compliance expertise, while online banks prioritize cloud-native vendor ecosystems.
- Banking Institutions:Traditional deposit-taking and lending operations with branch networks and legacy core systems. The Eurozone's ECB stress-testing protocols and India's RBI data localization mandates shape procurement priorities for hardware and software maintenance.
- Payment Processors:High-availability transaction clearing infrastructure requiring sub-second uptime guarantees. ISO 20022 protocol migration across the United States, India, and Eurozone generates sustained demand for certified maintenance providers.
- Financial Service Providers:Non-bank lenders, insurers, and wealth managers with hybrid technology estates.
- Online Banks:Branchless digital-native institutions with API-first architectures and containerized microservices.
By maintenance spend, Banking Institutions lead. By vendor switching velocity, Online Banks are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal Reserve operational resilience mandates are compressing maintenance response windows across the United States, while India's RBI data localization requirements and the ECB's stress-testing protocols reshape procurement priorities in their respective jurisdictions.
United States
Regional banks are expanding ATM support contracts as branch networks modernize under Fed guidelines. The Federal Reserve's operational resilience mandates push institutions toward proactive hardware maintenance with guaranteed uptime commitments. Banking corridors in Texas and the Southeast generate concentrated demand for core platform servicing.
India
Public sector banks are digitizing legacy infrastructure at scale across metropolitan banking corridors. RBI data localization requirements for domestic storage of financial records fragment service delivery models and inflate compliance overhead. Mumbai, Delhi, and Bangalore drive concentrated demand spikes for maintenance services.
Germany
REACH chemical compliance and the EU AI Act reshape hardware maintenance protocols for ATM fleets. Component suppliers must certify circuit boards against restricted substance lists. Frankfurt and Munich banking clusters consolidate vendor panels to reduce audit duplication.
United Kingdom
Outcome-based service level agreements replace time-and-material contracts among tier-two institutions. Tier-two banks purchase guaranteed uptime rather than engineer hours, transferring operational risk to vendors. London's financial district anchors demand for predictive analytics capabilities.
Singapore
Digital-first banks adopt Kubernetes-based platform support at accelerated rates, displacing perpetual license models. Containerized microservices architectures compress vendor margins on legacy projects while expanding recurring revenue. The city-state's banking hub attracts cloud-native maintenance specialists.
Banking Maintenance Support and Services Market Competitive Environment
Listed leaders compete with private specialists across technology delivery models, creating a tiered structure where scale-driven platform vendors face specialized labor-arbitrage challengers. The market consolidates around three strategic archetypes: captive core banking servicers, cloud-native workflow specialists, and labor-arbitrage delivery centers. Dominant competitive moves include portfolio diversification into adjacent cybersecurity operations and geographic expansion through metropolitan corridor digitization contracts.
Within the captive servicing tier, FIS anchors its position through platform maintenance tied to installed core banking systems. HCL Technologies Limited exemplifies the labor-arbitrage archetype with delivery center models supporting legacy environments. Temenos AG occupies the cloud-native specialization vector, targeting digital-first institutions with containerized maintenance workflows.
| Leading Market Players |
|---|
| FIS (Fidelity National Information Services) |
| Fiserv, Inc. |
| Jack Henry & Associates |
| Microsoft |
| SAP |
| Oracle |
| Capgemini |
| Temenos AG |
| HCL Technologies Limited |
| Others |
Value Chain & Pricing Dynamics
Fixed-price multi-year service contracts lock in both supply access for maintenance providers and cost predictability for banking institutions navigating RBI data localization mandates and Fed operational resilience deadlines. These agreements concentrate pricing power with certified vendors holding ISO 20022 protocol credentials while fragmenting margin capture among regional hardware specialists.
Pricing Analysis
Certification level creates the primary spread between premium and standard service tiers. Subscription-based SaaS pricing dominates software maintenance contracts, while ATM support operates on per-unit transactional models with geographic delivery cost as the secondary differentiator. Pricing pressure stems from cloud-native platform commoditization as Kubernetes-based maintenance displaces legacy perpetual licenses. Tier-one commercial banks show lowest price sensitivity due to regulatory uptime mandates, whereas credit unions and regional retail banks aggressively negotiate managed service bundles.
Supply Chain Analysis
India and the United States anchor specialized engineering talent pools for legacy mainframe and cloud-native platform support respectively. Component supply for ATM hardware repairs draws from China-based circuit board manufacturers and Mexico-based peripheral assembly operations. Single-source vulnerability concentrates in COBOL-proficient engineer networks where retirement waves thin maintenance capacity. Distribution runs through vendor-direct field service organizations and third-party managed service integrators serving metropolitan banking corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contracting availability of engineers fluent in both legacy COBOL environments and modern API architectures constrains expansion velocity for maintenance providers across all tiers. Institutions that solve this workforce gap through structured apprenticeship pipelines or targeted acquisition strategies capture disproportionate pricing power in ISO 20022 migration windows.
For Market Incumbents: Shield core banking platform relationships by embedding predictive maintenance analytics and guaranteed uptime commitments into renewal negotiations. Acquire specialized cybersecurity operations capabilities to defend against cloud-native entrants targeting SOC outsourcing demand. Vertical integration into container orchestration tooling preserves margin on Kubernetes-based contracts displacing traditional upgrade projects. For New Entrants and Emerging Players: Anchor in India's public sector bank digitization corridors where RBI mandates fragment incumbent delivery models. Target mid-tier commercial banks in Bangalore and Chennai with hybrid legacy-cloud maintenance propositions. Lead with ISO 20022 certification credentials and domestic data center partnerships as the primary go-to-market wedge. For Investors and Strategic Acquirers: Engineering-heavy mid-cap specialists with captive mainframe talent and established Fed compliance track records represent the most defensible acquisition profile. Long-term viability hinges on successful workforce transition from COBOL-dependent servicing to containerized platform management. Monitor container adoption rates at tier-two U.S. regional banks as the inflection signal for cloud-native maintenance contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Certification Investment | Protocol fluency secures eligibility for Fed payment infrastructure upgrade contracts. |
| Domestic Data Center Partnership | RBI localization mandates require India-based service delivery for public sector banks. |
| Legacy-to-Cloud Workforce Retraining | COBOL engineer pipelines transition toward Kubernetes and container orchestration competencies. |
| Predictive Maintenance Platform Deployment | IoT sensor networks enable outcome-based SLAs transferring operational risk to vendors. |
| Cybersecurity Operations Center Acquisition | BIS guidelines compel mid-tier institutions to outsource 24/7 threat monitoring capabilities. |
Study Parameters
The analysis maps software maintenance, ATM support, network management, and cybersecurity operations segments, each validated through primary interviews with core banking platform directors, ATM fleet managers, security operations leads, and procurement officers at tier-one and regional institutions. Secondary validation draws from Federal Reserve operational resilience guidelines, RBI circulars on data localization, BIS cyber risk management frameworks, and SEC filings of listed maintenance providers. Bottom-up contract value estimates triangulate against top-down market sizing from technology spend disclosures.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models service type, client tier, technology stack, and end-user category dimensions with geographic regulatory cluster overlays. CAGRs derive from fitted growth curves adjusted for ISO 20022 migration timelines and cloud displacement rates. Forecast inputs include ATM fleet replacement schedules at Indian public sector banks and container adoption velocity at Singapore digital-first institutions.
Material uncertainties — regulatory deadline extensions, mainframe talent attrition acceleration, or cloud platform consolidation — sit outside the modeled envelope. Forecasts reflect assumptions about maintenance contract renewal rates and certification timeline adherence. Recalibration cycles align with material shifts in Fed operational resilience rulemaking and RBI data localization enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking ERP Software Market
Banking
Letter of Credit Confirmation Market
Banking
Banking As a Service (BAAS) Market
Banking
Armenia Banking Market
Banking
Global Banking BPS Market
Banking
Cloud-Based Core Banking Market
Banking
Asia-Pacific Machine Learning in Banking Market
Banking
Global Neo and Challenger Bank Market
Banking
US Investment Banking Market
Banking
Africa Data Analytics in Banking Market
Banking
Japan Data Analytics in Banking Market
Banking
E-Banking Market
Banking
Banking Credit Analytics Market
Banking
Europe Banking-As-A-Service Market
Banking
Bank Kiosk Market
Banking
APAC Banking-As-A-Service Market