
 Asia-Pacific Challenger Banks Market | 2026-2036
Asia-Pacific Challenger Banks Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Challenger Banks Market Insights
Cloud-native core banking infrastructure is pivoting away from on-premise legacy stacks across the Asia-Pacific financial sector. WeBank leverages its Tencent-backed technology architecture to dominate consumer lending volumes in China. MY Bank sustains merchant-focused working capital products through Ant Group's e-commerce data streams. Rakuten Bank differentiates via deep integration with Japan's largest online shopping ecosystem and loyalty currency circulation.
Asia-Pacific challenger banks are licensed deposit-taking institutions operating exclusively through mobile applications and digital interfaces without physical branch networks, typically running on microservices-based technology stacks with API-first architectures enabling real-time payment processing and automated credit underwriting. Digital banks and neobanks anchor the fastest expansion trajectories as regulatory sandboxes in multiple jurisdictions lower capital barriers for new entrants. The unbanked customer segment within target audience classifications represents the deepest margin pool where traditional KYC costs previously rendered micro-accounts unprofitable.
TRAI's payment system oversight in India, MAS sandbox frameworks in Singapore, and ASIC's licensing requirements in Australia collectively shape product standards and market access timelines across the region. China's NMPA-aligned fintech regulations and Japan's Banking Act revisions further constrain foreign entity participation while privileging domestically chartered operators. Stakeholders must monitor evolving capital adequacy thresholds for digital-only licenses as regulators balance innovation promotion against systemic risk containment.
Market Dynamics
Cloud-native core banking infrastructure is pivoting away from on-premise legacy stacks across the Asia-Pacific financial sector, compressing deployment timelines from years to months while collapsing operational cost structures for new entrants.
Growth Catalysts
- India's UPI infrastructure:The Unified Payments Interface displaces legacy clearing systems through real-time settlement rails, enabling micro-merchants to accept digital payments without merchant discount rate burdens.
- MAS sandbox frameworks:Singapore's regulatory sandbox lowers capital barriers for digital banking licenses, accelerating market entry timelines for fintech operators seeking full bank charters.
- Smartphone penetration gaps:Southeast Asian markets where mobile device density outpaces physical branch networks create addressable populations previously excluded by traditional KYC economics.
Market Restraints
- Deposit insurance thresholds:Digital-only licensees face differentiated coverage limits under national banking acts, constraining liability management strategies versus incumbent banks.
- Foreign ownership caps:China's NMPA-aligned fintech regulations and Japan's Banking Act revisions privilege domestically chartered operators, blocking cross-border consolidation pathways.
- Core banking migration costs:Legacy system decommissioning requires parallel operational expenditure during transition windows, draining capital reserves from pre-profitability challengers.
Strategic Opportunities
- Indonesia's unbanked archipelago:The archipelagic geography fragments traditional branch economics, positioning mobile-first deposit products to capture remittance and micro-lending flows across 17,000 islands.
- Embedded finance convergence:API-first banking stacks integrating with ride-hailing and e-commerce platforms enable contextual credit origination at point-of-transaction.
- Vietnam's circular 19/2016:The State Bank of Vietnam's pilot licensing framework for non-bank payment intermediaries creates regulatory precedent for limited-purpose digital banking expansion.
Industry Challenges
- Cloud architecture talent scarcity:Kubernetes and microservices engineering expertise concentrates in Singapore and Bangalore, forcing regional challengers into compensation wars for DevOps capabilities.
- Real-time fraud detection capex:Transaction monitoring systems requiring sub-50 millisecond decision latency demand specialized infrastructure investment before scale economies materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Challenger Banks Market |
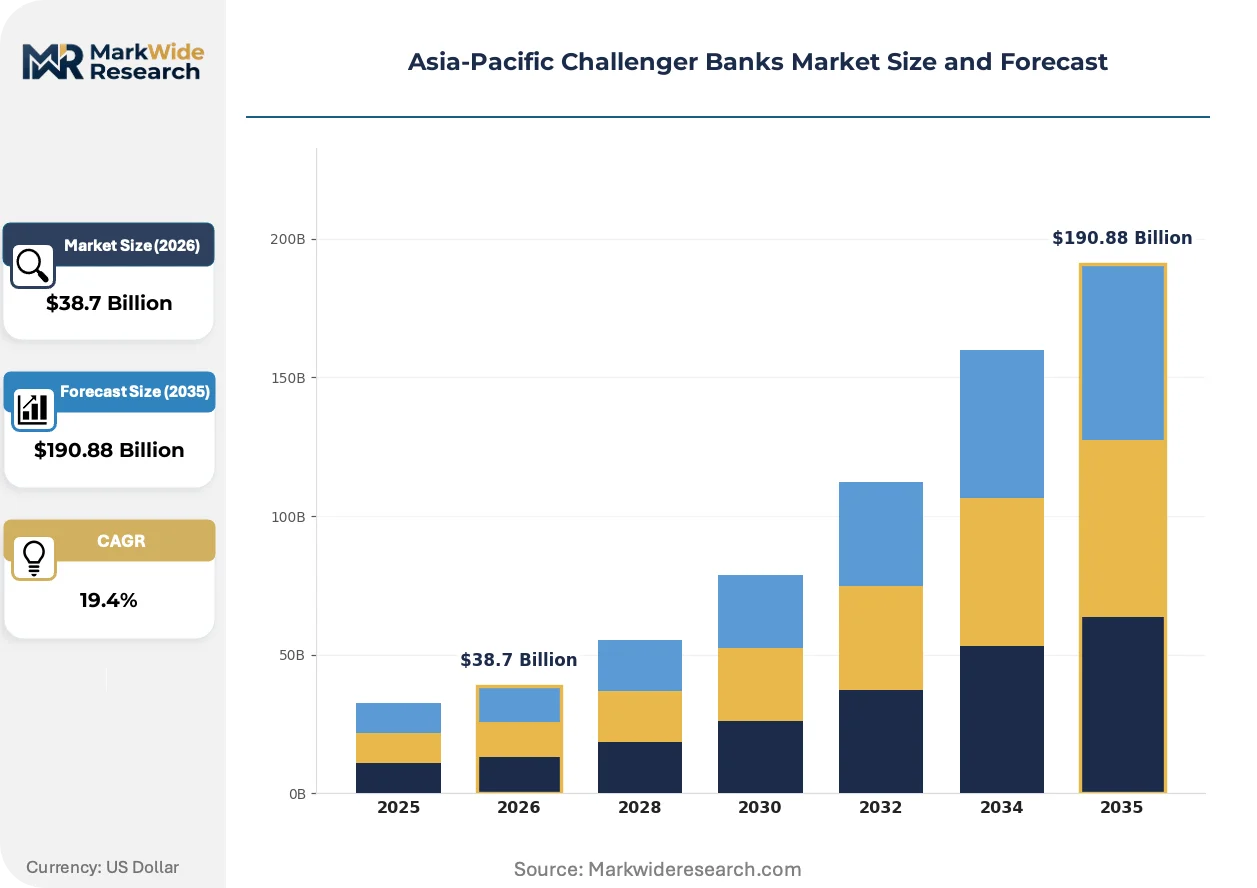
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $190.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bank Type: Digital Banks, Neobanks, Traditional Banks, Hybrid Banks Target Audience: Millennials, Small Businesses, Freelancers, Unbanked Customers Service Offering: Payment Solutions, Savings Accounts, Investment Services, Loan Products Regulatory Landscape: Sandbox Regulations, Licensing Requirements, Compliance Standards, Consumer Protection Laws |
| Companies Covered | WeBank, MY Bank, Jenius Bank, Paytm Payments Bank, EON Bank PH, Rakuten Bank, PayPay Bank, Jibun Bank, K Bank, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Challenger Banks Market Trends and Innovations
Embedded finance architectures are dissolving boundaries between banking services and non-financial platforms, forcing challengers to compete on distribution integration rather than standalone product features.
Distributed ledger technology is absorbing cross-border settlement functions previously executed through correspondent banking networks. ASEAN-based remittance corridors are adopting blockchain rails for Thai-Baht to Philippine-Peso flows, compressing settlement windows from 48 hours to near-real-time. This infrastructure shift is absorbing liquidity requirements from traditional nostro-vostro account structures, freeing capital for on-lending activities.
ASIC's licensing requirements in Australia are tightening operational resilience standards for digital banks, mandating 99.99% uptime commitments and disaster recovery testing protocols. The prudential regulator's 2023 updated guidance imposes equivalent technology risk management obligations on neobanks as traditional deposit-taking institutions. Australian challengers are responding by diverting engineering resources from feature development to compliance automation tooling.
SME banking relationships are fragmenting across multiple specialized providers rather than consolidating with single institutions. Indonesian garment exporters now maintain separate accounts for receivables financing, foreign exchange hedging, and working capital term loans across three distinct digital platforms. This behavioral shift is most visible in Vietnam's manufacturing corridors, where factory owners prioritize best-in-class single-purpose tools over bundled relationship banking.
Asia-Pacific Challenger Banks Market Segmentation
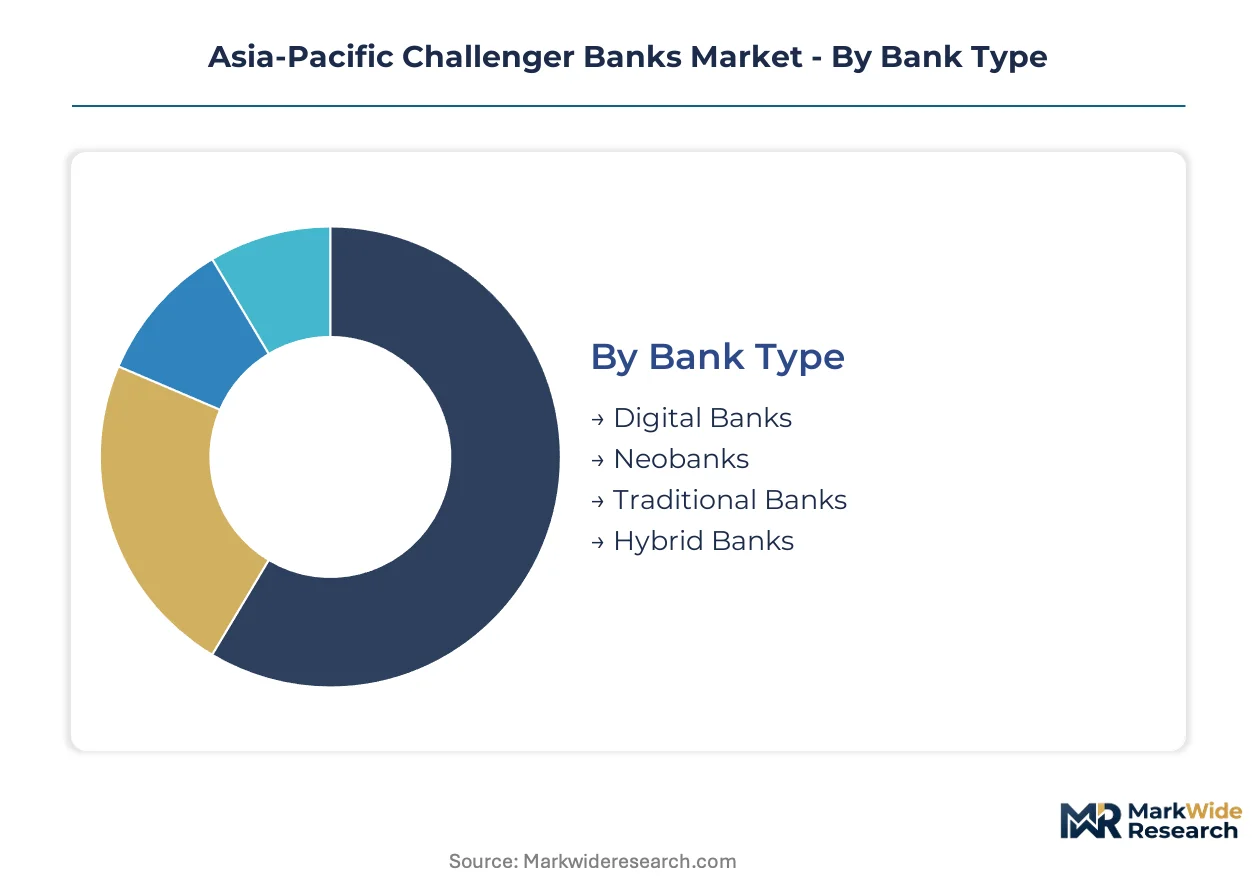
Challenger bank operators in Asia-Pacific must align technology stacks and licensing strategies against distinct customer acquisition economics and regulatory treatment tiers. Segment boundaries determine capital requirements, product velocity, and margin sustainability across divergent national frameworks.
Bank Type:
License classification dictates capital reserves, deposit insurance access, and permissible product scope for new entrants across Asia-Pacific jurisdictions.
- Digital Banks:Full deposit-taking charters operating exclusively through mobile interfaces with cloud-native core systems. Singapore's MAS digital bank licensees and Australia's authorized deposit-taking institutions concentrate demand here as regulators grant parity with incumbent banks on deposit insurance and payment system access.
- Neobanks:E-money or payment institution licenses enabling transaction banking without full lending authority. Indonesia's OJK-licensed neobanks and Philippines' EMI operators dominate this tier where lighter capital requirements accelerate market entry but constrain credit product monetization.
- Traditional Banks:Legacy branch networks pursuing digital transformation through subsidiary spin-offs. Japan's regional banks and South Korea's savings banks occupy this segment as defensive repositioning against pure-play challengers.
- Hybrid Banks:Phased digital migration retaining limited physical presence for high-value transactions. India's small finance banks and Vietnam's joint-stock banks with digital-first subsidiaries cluster here where regulatory arbitrage between branch and branch-lite licenses persists.
Digital banks lead on scale; neobanks lead on momentum.
Target Audience:
Customer archetype selection determines unit economics, with acquisition cost spreads and lifetime value profiles varying by financial sophistication and prior banking access.
- Millennials:Smartphone-native demographics demanding instant onboarding and lifestyle-integrated financial tools. Indian metro millennials and Southeast Asian urban professionals drive concentration here, with salary-linked credit products and investment automation as primary hooks.
- Small Businesses:Micro-enterprises and SMEs underserved by collateral-heavy traditional lending. Indonesia's garment exporters and Vietnam's manufacturing subcontractors anchor this segment where invoice financing and supply chain credit replace relationship-based branch banking.
- Freelancers:Gig economy participants with irregular income streams requiring cash flow smoothing. Philippines' BPO contractors and Thailand's platform economy workers populate this niche where earned wage access and micro-lending against platform data substitute for credit bureau scores.
- Unbanked Customers:Populations excluded by KYC documentation thresholds or branch accessibility constraints. India's rural agricultural households and Indonesia's outer island residents represent this segment where simplified e-KYC and agent-assisted onboarding unlock previously uneconomical account economics.
Small businesses concentrate revenue contribution; unbanked customers expand addressable market breadth.
Service Offering:
Product mix selection reflects regulatory license boundaries and technology stack capabilities, with cross-sell depth determining customer lifetime value.
- Payment Solutions:Real-time transaction processing, QR code acceptance, and cross-border remittance rails. India's UPI-integrated wallets and Singapore's PayNow-linked accounts dominate volume here as infrastructure interoperability mandates level the competitive field.
- Savings Accounts:High-yield deposit products competing on interest rate transparency and liquidity terms. Australia's neobanks and South Korea's internet-only banks compete aggressively here, using rate premiums to offset absent branch convenience.
- Investment Services:Fractional securities, robo-advisory, and alternative asset access embedded in primary banking apps. Japan's Rakuten Bank and China's WeBank extend into wealth management here, leveraging existing customer data for risk-appropriate product matching.
- Loan Products:Automated credit underwriting against alternative data streams including e-commerce transactions and mobile wallet history. MY Bank's merchant cash advances and Indonesia's paylater products illustrate this segment where real-time scoring replaces collateral assessment.
Payment solutions lead on transaction volume; loan products lead on margin contribution.
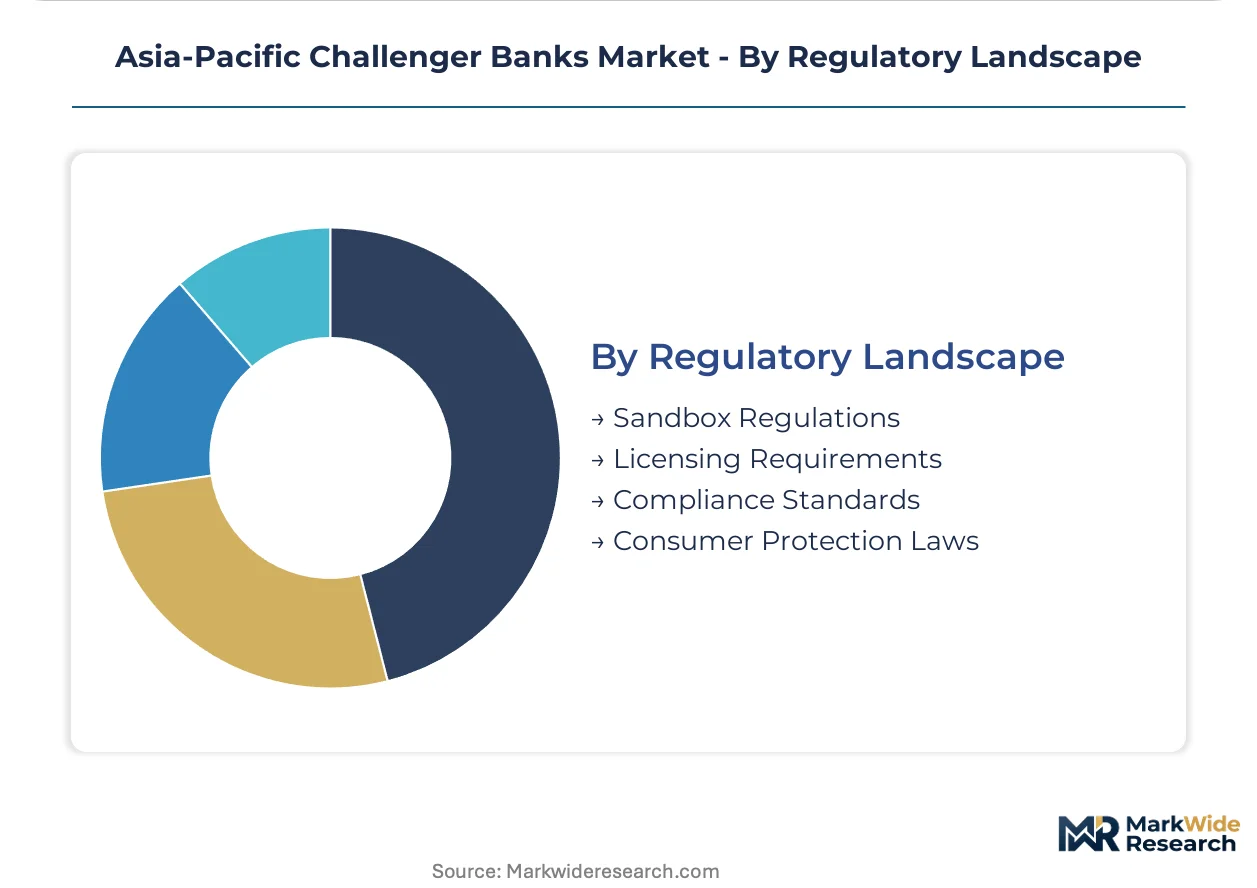
Regulatory Landscape:
Compliance architecture selection shapes market entry timing and ongoing operational burden across Asia-Pacific's fragmented supervisory environment.
- Sandbox Regulations:Time-bound experimental licenses permitting limited-scale product testing under modified rules. Singapore's MAS sandbox and Australia's ASIC innovation hub concentrate activity here, with explicit failure permissions reducing pre-launch compliance investment.
- Licensing Requirements:Full charter applications with prudential capital, governance, and technology risk standards. India's RBI digital banking licenses and Hong Kong's restricted license banks illustrate this tier where multi-year approval timelines filter out undercapitalized applicants.
- Compliance Standards:Ongoing operational obligations including AML monitoring, data localization, and business continuity mandates. Australia's CPS 230 operational risk requirements and Singapore's TRM guidelines impose equivalent burdens on digital and traditional banks.
- Consumer Protection Laws:Disclosure, dispute resolution, and fair treatment obligations specific to retail financial services. India's RBI ombudsman scheme and Philippines' BSP financial consumer protection framework govern this domain where digital-only delivery complicates complaint handling.
Licensing requirements govern market access; sandbox regulations govern innovation velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Marina Bay financial district anchors Asia-Pacific challenger banking innovation, hosting MAS-licensed digital banks and regional headquarters for cloud-native operators. Regulatory sandboxes across Southeast Asia compress market entry timelines while India's UPI infrastructure redefines payment economics at scale.
China
Ant Group's MY Bank and Tencent-backed WeBank dominate merchant cash advance and consumer lending volumes through e-commerce data integration. The National Medical Products Administration-aligned fintech regulations privilege domestically chartered operators over foreign entrants. Shenzhen's technology corridor concentrates engineering talent for microservices architecture development.
India
Paytm Payments Bank leverages TRAI's payment system oversight and RBI's digital banking licenses to capture micro-merchant deposits and UPI transaction flows. The central bank's simplified KYC frameworks unlock rural agricultural households previously excluded by branch economics. Mumbai's financial district and Bangalore's technology cluster split regulatory and engineering functions.
Japan
Rakuten Bank and PayPay Bank embed banking services within e-commerce and mobile wallet ecosystems, circulating loyalty currencies at scale. METI's Banking Act revisions constrain foreign ownership while privileging domestically integrated operators. Tokyo's metropolitan corridor concentrates consumer fintech adoption alongside Osaka's merchant services specialization.
Indonesia
Jenius Bank targets the archipelago's unbanked population across 17,000 islands where smartphone penetration outpaces branch density. OJK's neobank licensing framework enables lighter capital entry than full bank charters demand. Jakarta's fintech corridor and Surabaya's manufacturing belt anchor digital lending against e-commerce transaction data.
South Korea
K Bank competes for salary-linked credit products and investment automation among smartphone-native millennials in Seoul's metropolitan zone. The Financial Services Commission's internet-only bank licensing grants deposit insurance parity with traditional institutions. Seoul's Gangnam district concentrates affluent customer acquisition while Busan's port economy drives SME working capital demand.
Asia-Pacific Challenger Banks Market Competitive Landscape
Global technology conglomerates compete with regional financial champions across distribution integration and data asset depth. Market structure concentrates around three tiers: platform-embedded banks with e-commerce parentage, standalone digital banks with full charters, and mobile wallet operators with payment institution licenses. Strategic archetypes include ecosystem-anchored lenders, regulatory arbitrage specialists, and API-first infrastructure providers. Dominant competitive moves encompass embedded finance partnerships and alternative data underwriting capabilities.
Within the ecosystem-anchored tier, WeBank and MY Bank exemplify platform-integrated models leveraging parent company transaction data for real-time credit decisions. Rakuten Bank occupies a position representing loyalty-currency circulation strategies. These three entities anchor divergent geographic and business model archetypes across the regional competitive map.
| Leading Market Players |
|---|
| WeBank |
| MY Bank |
| Jenius Bank |
| Paytm Payments Bank |
| EON Bank PH |
| Rakuten Bank |
| PayPay Bank |
| Jibun Bank |
| K Bank |
| Others |
Pricing and Supply Chain Analysis
Cloud-native core banking migrations across Asia-Pacific are compressing technology deployment timelines from multi-year legacy implementations to months, simultaneously collapsing operational cost structures and redistributing vendor power toward specialized infrastructure providers. This shift enables challengers to price deposit products aggressively against incumbents while forcing legacy system decommissioning costs onto pre-profitability entrants.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and API gateway fees shapes pricing models across the Asia-Pacific challenger bank landscape. Three-tier pricing structure across premium relationship, standard transactional, and economy micro-account levels dominates, with differentiation driven by KYC depth and credit product access. Pricing pressure stems from zero-commission payment rails like India's UPI, which compresses interchange revenue. Small businesses show highest price sensitivity to lending spreads, while affluent millennials accept premium subscription fees for wealth management integration.
Supply Chain Analysis
Workforce availability for Kubernetes and microservices engineering concentrates in Singapore's fintech corridor and Bangalore's technology cluster, creating compensation wars that inflate operational costs for regional challengers. Supply chain dependencies center on cloud infrastructure from AWS, Azure, and Alibaba Cloud, alongside specialized fraud detection hardware from NVIDIA and FPGA vendors. Single-source vulnerability runs through Singapore's submarine cable landing stations for cross-border data flows. Distribution runs through API-first partnerships with ride-hailing and e-commerce platforms rather than traditional branch networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific challenger banking operates as a geographic-arbitrage play where Singapore's regulatory sandbox timelines compress market entry costs versus India's multi-year full charter approvals, enabling capital-efficient scaling strategies.
For Market Incumbents: Deepen cloud-native infrastructure investments to match neobank cost structures before deposit flight accelerates. Prioritize vertical integration into alternative data underwriting capabilities to defend lending margins against MY Bank and WeBank's merchant cash advance products. Accelerate MAS digital bank license applications to neutralize regulatory arbitrage from pure-play entrants. For New Entrants and Emerging Players: MAS sandbox frameworks in Singapore open a window for limited-scale product testing before full charter capital requirements apply. Target Indonesia's unbanked archipelago where smartphone penetration outpaces branch density across 17,000 islands. Pursue embedded finance partnerships with Gojek and Grab as the primary go-to-market channel rather than standalone app acquisition. For Investors and Strategic Acquirers: Valuations sit cheapest among payment-institution-licensed neobanks constrained from lending monetization, creating acquisition targets with regulatory upgrade optionality. Long-term viability hinges on successful charter conversion within a five-to-ten year regulatory window. Watch for ASIC operational resilience mandate compliance costs as the inflection signal separating scalable infrastructure from technical debt burdens.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Infrastructure Migration | Enables real-time payment processing and automated credit underwriting against UPI and PayNow rails. |
| Alternative Data Underwriting | Leverages Ant Group and Tencent e-commerce transaction streams for merchant cash advance decisions. |
| Regulatory Sandbox Entry | Compresses MAS and ASIC market access timelines while limiting pre-launch compliance capital drain. |
| Embedded Finance Partnership | Integrates banking services into Grab and Shopee platforms at point-of-transaction for contextual origination. |
| Cloud-Native Core Replacement | Displaces legacy IBM and Oracle stacks with microservices architecture reducing operational expenditure. |
Research Methodology
Coverage spans China, India, Singapore, Indonesia, and Australia, with primary inputs from each market's regulatory and technology clusters. The analysis combines structured interviews with digital bank CTOs, MAS licensing officers, cloud infrastructure procurement leads, and API platform engineers alongside secondary validation from RBI circulars, ASIC prudential standards, and OJK neobank frameworks. Bottom-up transaction volume modeling and top-down GDP-correlated banking penetration estimates provide triangulation.
Rate-of-change decomposition separates smartphone adoption curves, regulatory sandbox expansion velocity, and cloud infrastructure cost decline trajectories across the projection horizon. Segmentation dimensions include license classification, target audience archetype, service offering mix, and national regulatory framework. CAGRs derive from fitted adoption S-curves against demographic banking penetration ceilings. Industry-specific inputs incorporate UPI transaction growth rates and MAS digital bank license issuance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA-aligned fintech regulation tightening in China or ASIC operational resilience mandate acceleration in Australia. Forecasts reflect assumptions on regulatory sandbox renewal permissions and cloud provider pricing stability. Material deviation in UPI merchant discount rate policy or MAS capital adequacy threshold adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
AI and Automation in Banking Market
Banking
Corporate Banking Market
Banking
Digital Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
US Investment Banking Market
Banking
API Banking Market
Banking
Middle East Data Analytics in Banking Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
Global Neo and Challenger Bank Market
Banking
Commercial Banking Market
Banking
Banking Credit Analytics Market
Banking
Embedded Banking Market
Banking
Data Analytics in Banking Market
Banking
UK Retail Banking Market
Banking
In Vitro Fertilization Banking Services Market