
 Credit Intermediation Market | 2026-2036
Credit Intermediation Market Size, Share, and Industry Trends Forecast 2026-2036
Credit Intermediation Market Analysis
The capital-intensity divergence between large universal banks and digital-native platforms is collapsing as cloud-based underwriting erodes the funding advantage of branch networks. JPMorgan Chase and Co. leverages its balance-sheet depth to compete across wholesale and retail credit channels. Goldman Sachs Group Inc. differentiates through its Marcus platform, which specializes in direct consumer lending outside traditional branch infrastructure.
Credit intermediation denotes the process of channeling funds from surplus units to deficit units through financial institutions that transform maturity, risk, and scale—typically involving credit scoring algorithms, collateral valuation protocols, and regulatory capital reserves. Its primary commercial purpose is reducing information asymmetry between borrowers and lenders while generating net interest margin. The engagement model dimension shows online platforms capturing the fastest expansion as algorithmic underwriting compresses origination costs, while traditional banks still anchor the largest margin pools due to deposit-funded cost advantages. Home mortgages within the financial product category represent the most mature segment with established secondary-market liquidity, whereas peer-to-peer structures under engagement models face structural pressure from SEC registration requirements and state lending license fragmentation.
The Federal Reserve and the SEC jointly shape U.S. credit intermediation through reserve requirements, stress-test protocols, and securities disclosure rules that determine which institutions can originate and distribute credit products. The EU's CRD IV and the Basel Committee on Banking Supervision standards further constrain global players by mandating common equity tier ratios and liquidity coverage minimums that directly affect lending capacity. Stakeholders must monitor how open-banking APIs and embedded finance partnerships redistribute origination control away from chartered depositories toward technology platforms that operate under lighter regulatory umbrellas.
Market Dynamics
Cloud-native underwriting platforms are collapsing the funding-cost advantage that branch-based deposit networks historically held over digital competitors, forcing incumbent banks to rebuild core infrastructure while fintechs scale without legacy fixed-cost burdens.
Growth Catalysts
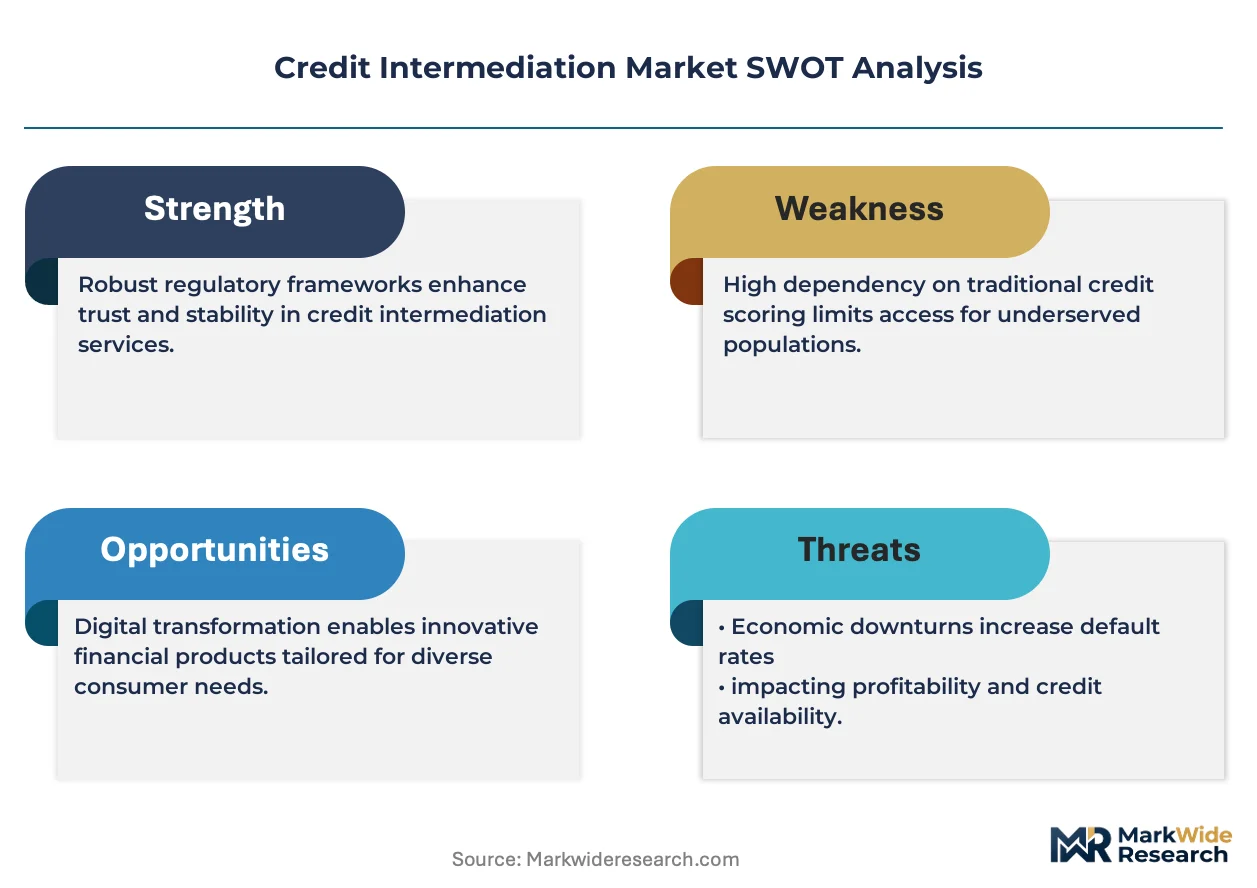
- Basel III Implementation:Risk-weighted capital frameworks are pushing surplus deposits toward non-bank credit originators who operate outside stringent reserve requirements, expanding the addressable market for alternative lenders.
- Small Business Credit Gap:Main Street enterprises rejected by traditional branch underwriting are migrating to algorithmic scoring platforms that assess cash-flow data rather than collateral-heavy balance sheets.
- Embedded Finance APIs:Software vendors integrating lending modules directly into accounting and e-commerce workflows are capturing origination moments previously controlled by chartered depositories.
Market Restraints
- State Licensing Fragmentation:Peer-to-peer lenders face compliance burdens from 50 separate state usury ceilings and registration regimes that prevent standardized national product rollouts.
- Deposit-Funding Concentration:Four U.S. universal banks control the majority of insured retail deposits, creating a structural moat that digital platforms cannot replicate without brokered-certificate cost penalties.
- Secondary Market Liquidity:Non-agency consumer loans lack the uniform underwriting standards and guarantee structures that make conforming mortgages tradable, trapping originators on their balance sheets.
Strategic Opportunities
- Open Banking Mandates:Consumer Financial Protection Bureau rules enabling permissioned data sharing will allow underwriters to access real-time transaction histories previously locked inside bank silos.
- Supply Chain Finance:B2B platforms embedding invoice financing into enterprise resource planning systems can capture working-capital flows that banks have historically ignored due to high origination costs per transaction.
- Credit-Builder Products:Thin-file borrowers excluded from prime scoring models represent an underserved segment for secured-card and installment structures that report to all three bureaus.
Industry Challenges
- Model Risk Management:Algorithmic underwriting systems require continuous validation against fair-lending statutes, demanding specialized quantitative compliance talent that commands premium compensation.
- Core System Migration:Legacy mainframe architectures at established institutions cannot support real-time API connectivity without multi-year transformation programs that disrupt near-term profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Credit Intermediation Market |
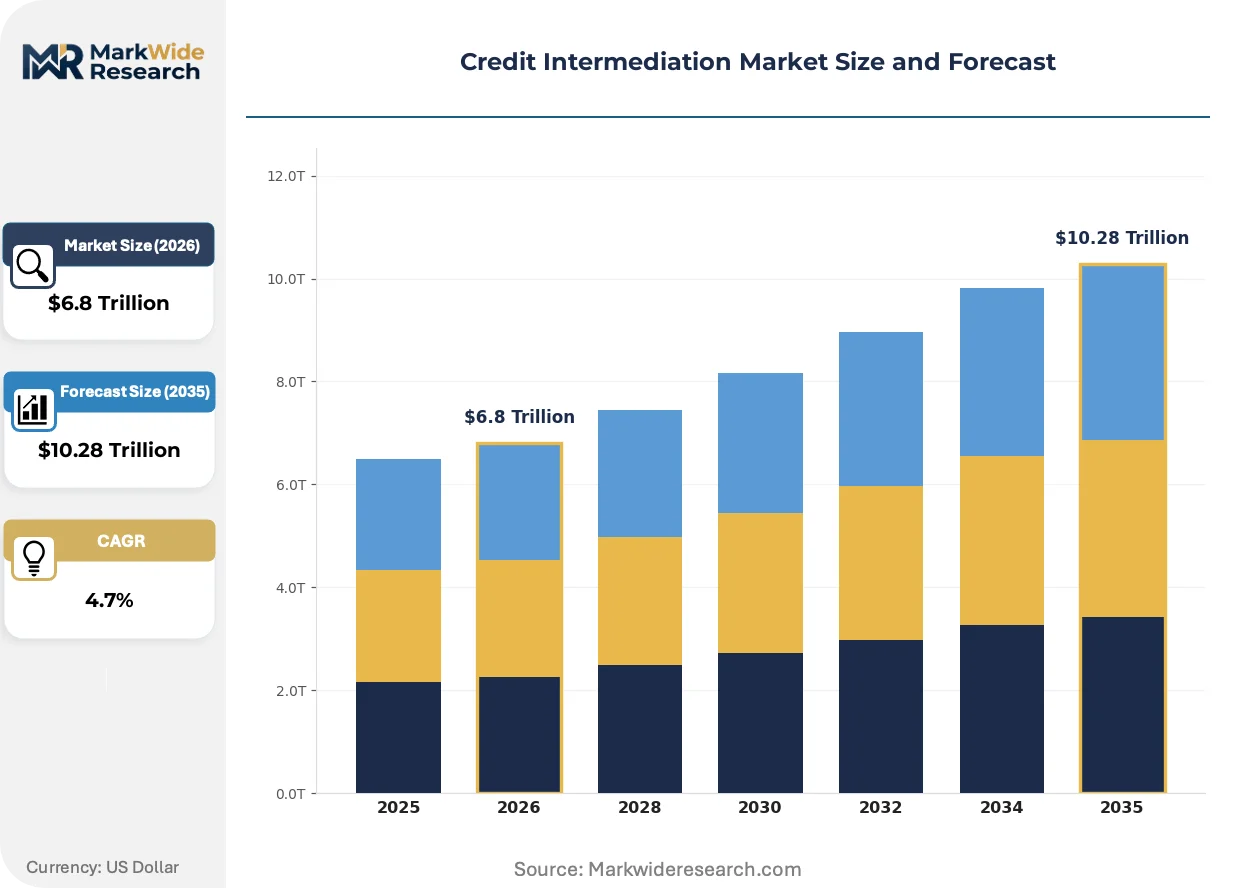
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $10.28 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Loan Brokerage, Mortgage Advisory, Debt Management, Investment Advice Client Type: Individuals, Small Businesses, Corporations, Non-Profits Financial Product: Personal Loans, Business Loans, Home Mortgages, Credit Cards Engagement Model: Direct Lending, Peer-to-Peer, Online Platforms, Traditional Banks |
| Companies Covered | JPMorgan Chase and Co., Bank of America Corp., Citigroup Inc., Wells Fargo and Co., HSBC Holdings Plc, Barclays PLC, Goldman Sachs Group Inc., Deutsche Bank AG, BNP Paribas S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Credit Intermediation Market Emerging Trajectories
Artificial intelligence is rewriting the economics of credit decisioning, compressing origination timelines from days to seconds while regulators scramble to adapt supervision frameworks to opaque machine-learning models.
Machine-learning credit scoring is supplanting traditional FICO-centric approaches by incorporating alternative data streams including utility payments, rental history, and cash-flow velocity. Subprime and near-prime originators are adopting these tools fastest, seeking competitive differentiation in segments where bureau scores provide thin discrimination. The structural consequence is a compression in risk-based pricing granularity, as algorithmic platforms narrow the spread between prime and subprime default predictions.
The EU's Digital Operational Resilience Act is mandating stress-testing and third-party risk management for all credit institutions using external technology service providers. European banks must now map critical dependencies across cloud infrastructure and software vendors, documenting failover protocols for underwriting systems. This is accelerating consolidation among mid-tier institutions that lack compliance scale, pushing them toward white-label platform partnerships.
Corporate treasury departments are unbundling relationship-banking services, selecting credit providers through competitive RFP processes rather than maintaining exclusive bilateral arrangements. Middle-market manufacturers and distributors are segmenting working-capital needs across specialized invoice-finance platforms, asset-based lenders, and traditional revolvers. The geographic epicenter of this behavior is the U.S. Southeast, where private-equity-backed portfolio companies drive standardization in procurement processes.
Credit Intermediation Market Segmentation
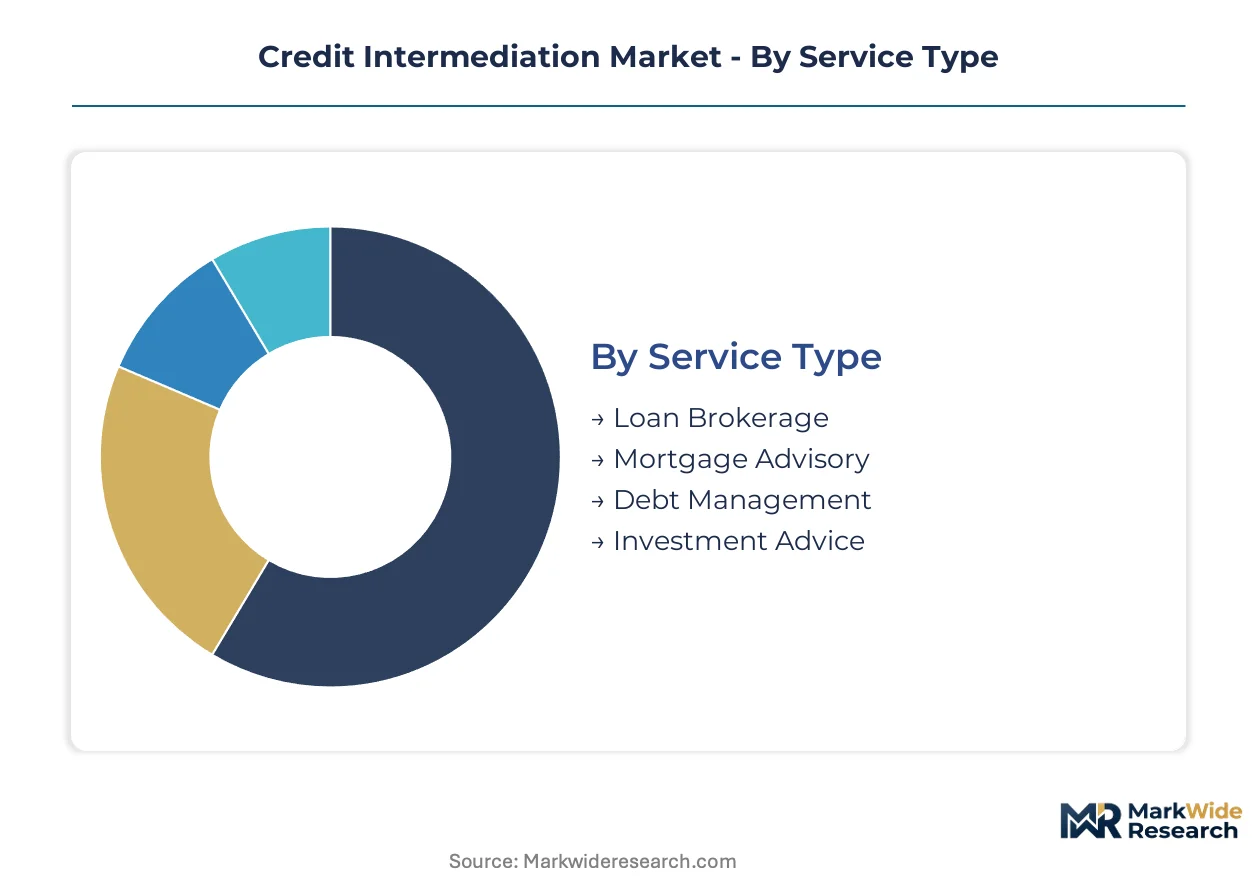
Segmentation reveals how capital flows fragment across borrower profiles and distribution architectures. Credit intermediation strategies diverge sharply between collateral-secured mortgage channels and unsecured cash-flow lending, while regulatory treatment varies by engagement model.
Service Type:
Domestic demand concentrates in loan brokerage and debt management as household leverage rises, while mortgage advisory follows cross-border capital flows into dollar-denominated property markets.
- Loan Brokerage:Intermediaries match borrowers with institutional lenders through proprietary origination networks, earning placement fees rather than balance-sheet exposure. Demand clusters around small business owners navigating SBA application complexity and consumers refinancing into conforming products.
- Mortgage Advisory:Licensed counselors guide borrowers through rate-lock timing, points optimization, and secondary market eligibility. The segment anchors revenue in high-cost coastal metros where jumbo origination volumes justify specialized advisory fees.
- Debt Management:Non-profit and for-profit agencies negotiate repayment plans with card issuers and collection entities. Federal Trade Commission disclosure rules constrain fee structures while state attorney general enforcement shapes competitive density.
- Investment Advice:Registered investment advisors integrate margin lending and securities-based credit into holistic wealth strategies. SEC Regulation Best Interest elevates compliance costs for hybrid advisory models.
Loan brokerage commands the established base. The steepest expansion runs through debt management as household delinquency rates climb.
Client Type:
Cost-tier stratification separates collateral-rich corporate borrowers from thin-file individuals, with small businesses occupying the contested middle ground where algorithmic underwriting displaces relationship banking.
- Individuals:Retail borrowers access credit through FICO-scored installment products and home-secured lines. Demand concentrates in Sun Belt metros where home equity extraction funds renovation and consolidation.
- Small Businesses:Main Street enterprises with under $5 million revenue represent the fastest-expanding addressable pool as automated cash-flow scoring replaces manual financial statement review.
- Corporations:Investment-grade issuers tap syndicated loan markets and commercial paper programs through relationship banks. Treasury departments unbundle services across specialized providers.
- Non-Profits:Mission-driven organizations access program-related investments and mission-based lending from community development financial institutions. Federal tax-exempt status unlocks preferential rate structures.
Individuals anchor volume concentration. Small businesses are climbing the fastest as fintech platforms capture origination share from branch networks.
Financial Product:
Application-driven segmentation separates term-structured products from revolving facilities, with mortgage origination requiring distinct licensing and secondary market infrastructure.
- Personal Loans:Unsecured installment credit with fixed terms ranging from 12 to 60 months. Subprime and near-prime originators deploy alternative data scoring to price thin-file applicants previously excluded from prime tiering.
- Business Loans:Term debt and revolving facilities collateralized by equipment, receivables, or real estate. SBA guarantee programs reduce lender risk exposure while extending maturity profiles unavailable in conventional markets.
- Home Mortgages:Long-term amortizing debt secured by residential real estate with established secondary market liquidity through agency and private-label securitization channels.
- Credit Cards:Revolving unsecured lines with variable pricing tied to prime rate benchmarks. Interchange revenue and late fee structures dominate issuer economics.
Home mortgages command the established base. Personal loans are gaining share fastest as fintech platforms compress origination timelines.
Engagement Model:
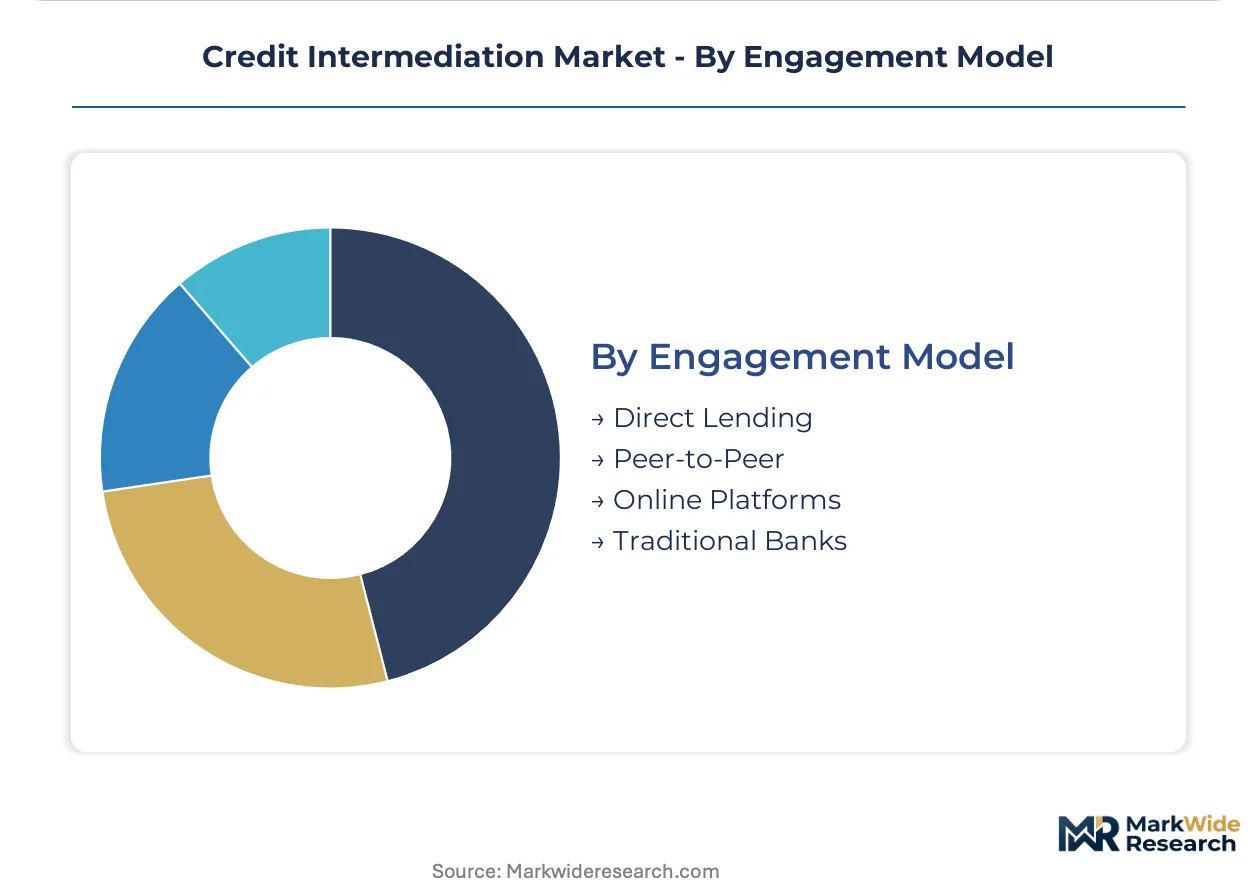
Supply concentration separates deposit-funded institutions from capital-markets-dependent platforms, with regulatory arbitrage driving origination migration toward lighter-touch licensing regimes.
- Direct Lending:Balance-sheet lenders originate and hold loans through proprietary capital without intermediary placement. Insurance companies and asset managers deploy long-duration liabilities into private credit structures.
- Peer-to-Peer:Marketplace platforms match retail investors with consumer borrowers through fractional note structures. State lending license fragmentation and SEC registration requirements constrain national scaling.
- Online Platforms:Cloud-native underwriters deploy API-integrated origination workflows with algorithmic decisioning. Embedded finance partnerships distribute lending modules through accounting and e-commerce software.
- Traditional Banks:Chartered depositories fund lending through insured retail deposits with Federal Reserve reserve requirements and Basel III capital constraints.
Traditional banks command the established base. Online platforms are expanding most quickly as embedded finance redistributes origination control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in U.S. credit markets exceeds European counterparts by roughly 80 basis points on comparable risk profiles, reflecting deeper capital market liquidity and lighter non-bank regulatory burdens. This asymmetry channels cross-border origination volume toward dollar-denominated structures.
United States
Deep secondary market liquidity and fintech infrastructure attract both domestic and cross-border credit flows. The Federal Reserve and SEC jointly shape intermediation through reserve requirements, stress-test protocols, and securities disclosure rules. New York and San Francisco anchor algorithmic underwriting clusters where cloud-native platforms compress origination timelines.
Germany
Corporate treasury unbundling drives demand for specialized working-capital providers outside relationship-banking structures. The EU's Digital Operational Resilience Act mandates stress-testing for institutions using external technology service providers. Frankfurt's banking quarter hosts consolidation among mid-tier institutions lacking compliance scale for white-label platform partnerships.
United Kingdom
Open banking mandates enable permissioned data sharing for real-time transaction history access previously locked inside bank silos. The Financial Conduct Authority oversees embedded finance partnerships redistributing origination control toward technology platforms. London's fintech corridor concentrates API-integrated lending modules distributed through accounting software workflows.
China
Alternative data scoring adoption accelerates in subprime segments where traditional bureau scores provide thin discrimination. The National Financial Regulatory Administration monitors algorithmic underwriting systems against fair-lending statutes. Shanghai and Shenzhen host machine-learning credit scoring development compressing risk-based pricing granularity.
India
Thin-file borrowers excluded from prime scoring models drive demand for secured-card and installment structures reporting to all bureaus. The Reserve Bank of India governs non-bank financial company capital adequacy and digital lending guidelines. Mumbai and Bangalore concentrate supply chain finance platforms embedding invoice financing into enterprise resource planning systems.
Credit Intermediation Market Vendor Landscape
Concentration sits with universal banks holding insured deposit bases and proprietary origination networks. Four U.S. institutions control the majority of retail deposits, creating structural moats that digital platforms cannot replicate without brokered-certificate cost penalties. Strategic archetypes separate balance-sheet lenders from marketplace platforms and embedded finance distributors. Dominant competitive moves include core system migration toward cloud-native architectures and white-label platform partnerships for mid-tier institutions lacking compliance scale.
Within the universal bank tier, JPMorgan Chase and Co. and Bank of America Corp. exemplify deposit-funded institutions competing across wholesale and retail credit channels. Goldman Sachs Group Inc. occupies a distinct position through direct consumer lending outside traditional branch infrastructure. These three entities represent the archetype spectrum from balance-sheet depth to digital-native origination, illustrating how capital intensity divergence collapses as cloud-based underwriting erodes historical funding advantages.
| Leading Market Players |
|---|
| JPMorgan Chase and Co. |
| Bank of America Corp. |
| Citigroup Inc. |
| Wells Fargo and Co. |
| HSBC Holdings Plc |
| Barclays PLC |
| Goldman Sachs Group Inc. |
| Deutsche Bank AG |
| BNP Paribas S.A. |
| Others |
Supply Flow & Price Mechanics
Deposit-scale economies at the four largest U.S. universal banks compress funding costs below digital-native competitors, creating price floors that algorithmic underwriters cannot match without brokered-certificate penalties. This concentration simultaneously shapes supply chain architecture, as origination capacity concentrates in institutions with proprietary branch networks and Federal Reserve master account access.
Pricing Analysis
The customization-premium spread separates configured-to-order working-capital facilities from standardized personal installment products. Net interest margins stratify across prime, near-prime, and subprime borrower tiers, with risk-based pricing granularity narrowing as machine-learning models compress default prediction spreads. Pricing pressure stems from cloud-native platforms eroding origination cost advantages previously held by deposit-funded incumbents. Small businesses exhibit highest price sensitivity due to thin collateral buffers, while investment-grade corporate treasuries prioritize relationship flexibility over rate minimization.
Supply Chain Analysis
Inventory and lead-time compression in algorithmic underwriting systems has collapsed origination timelines from days to seconds, eliminating the float-based revenue that previously subsidized branch infrastructure. Origination capacity concentrates in the United States, the United Kingdom, and Germany, where regulatory clarity around open-banking APIs enables real-time data aggregation. Capital deployment draws from insured retail deposits, institutional wholesale funding, and marketplace investor pools. Single-source vulnerability sits with cloud infrastructure providers hosting critical underwriting systems. Distribution runs through embedded finance partnerships, direct-to-consumer platforms, and traditional branch networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-banking API ecosystems and embedded finance interoperability are redistributing origination control away from chartered depositories, creating platform-economics inflection points where software vendors capture lending moments inside accounting and e-commerce workflows.
For Market Incumbents: Compound balance-sheet depth with algorithmic underwriting capability through cloud-native core system migration, defending against fintech origination share capture while leveraging deposit-funded cost advantages that digital platforms cannot replicate without brokered-certificate penalties. For New Entrants and Emerging Players: State lending license fast-tracks in unified regulatory jurisdictions offer the most penetrable pathway, targeting small business cash-flow lending where automated scoring displaces manual financial statement review, with go-to-market execution through accounting software API integrations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among embedded finance distributors with software-origination integration, where long-term viability over the projection horizon rests on white-label platform partnerships that mid-tier institutions lacking compliance scale will require to remain competitive; watch open-banking mandate implementation velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Core System Cloud Migration | Enables real-time API connectivity that legacy mainframe architectures cannot support without multi-year transformation programs. |
| White-Label Platform Partnership | Allows mid-tier institutions lacking compliance scale to access algorithmic underwriting without proprietary infrastructure investment. |
| Embedded Finance Integration | Captures origination moments inside accounting and e-commerce workflows previously controlled by chartered depositories. |
| Open Banking API Development | Unlocks permissioned transaction data access that the Consumer Financial Protection Bureau mandates for real-time underwriting. |
| Alternative Data Scoring Expansion | Compresses risk-based pricing granularity by incorporating utility payments and cash-flow velocity beyond traditional FICO-centric approaches. |
Methodological Framework
Initial hypotheses were tested against primary input from credit risk officers, fintech product managers, regulatory compliance leads, and commercial banking relationship managers, then refined against secondary validation from SEC filings, Federal Reserve statistical releases, Basel Committee regulatory texts, and open-banking implementation reports. Bottom-up origination volume estimates were triangulated with top-down macroeconomic credit flow data to ensure consistency across modeling approaches.
Variance decomposition across service type, client type, financial product, and engagement model dimensions structured the analytical framework, with CAGRs derived from segmented growth trajectory analysis and convergence assumptions. Forecast inputs incorporated Basel III implementation timelines, open-banking mandate rollout schedules, and embedded finance partnership adoption curves without specifying implementation dates.
Underlying assumptions cover regulatory implementation continuity, technology platform scalability, and funding market stability, with deviation risk concentrated in state licensing fragmentation and fair-lending algorithmic validation requirements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Global Neobanking Market
Banking
US Banking-As-A-Service Market
Banking
AI and Automation in Banking Market
Banking
Cloud Billing in Banking Market
Banking
Core Banking Solutions Market
Banking
Japan Trade Finance Market
Banking
Embedded Banking Market
Banking
Saudi Arabia Retail Banking Market
Banking
US Retail Banking Market
Banking
North America Machine Learning in Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Singapore Data Analytics in Banking Market
Banking
Europe Data Analytics in Banking Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Payment Bank Solutions Market
Banking
Bank Management Software Market