
 Third-Party Banking Software Market | 2026-2036
Third-Party Banking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Third-Party Banking Software Market Intelligence
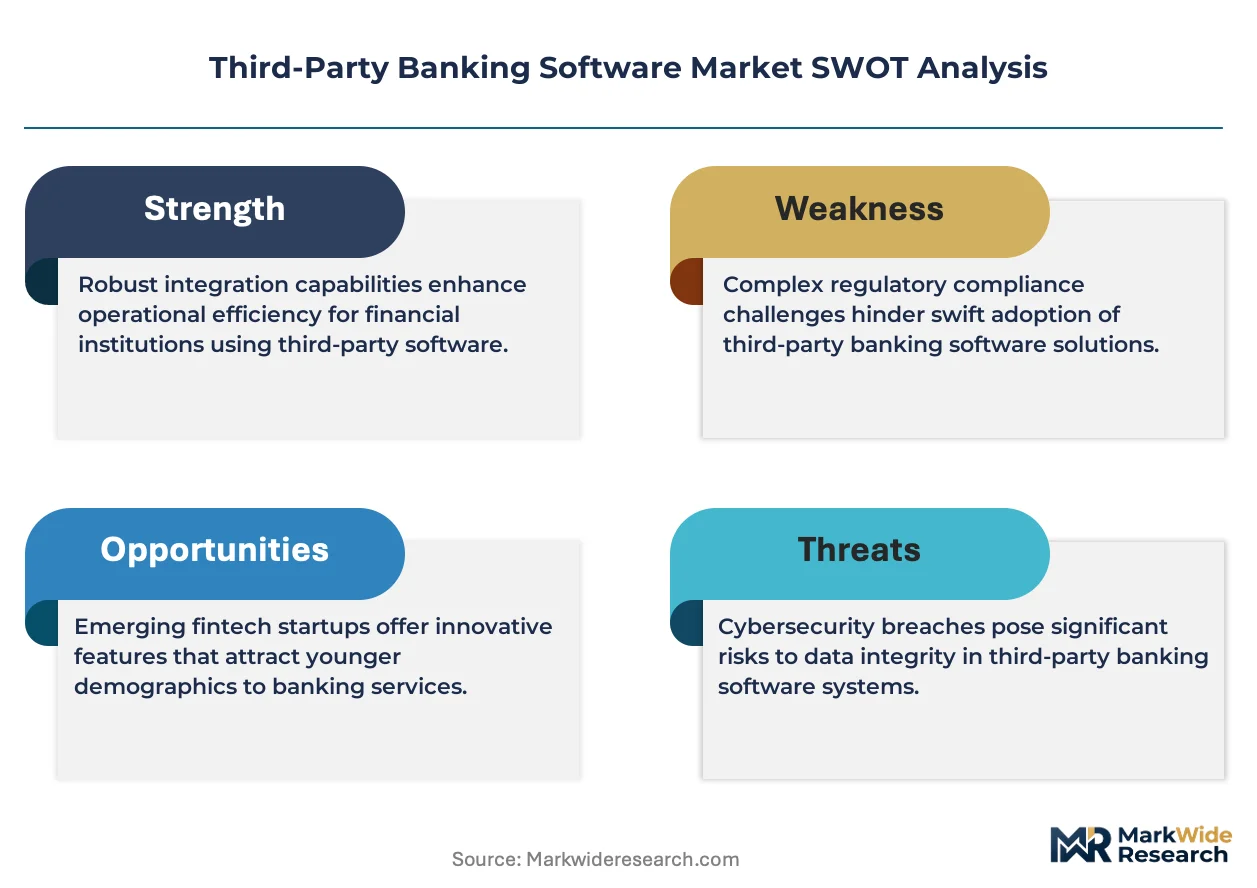
Subscription-based project finance for core banking transformations is tilting procurement power toward mid-tier institutions that previously lacked capital for full-stack replacements. Oracle Corporation leverages its database heritage to anchor long-term contracts with institutions prioritizing data sovereignty. Temenos competes through modular architecture that allows phased modernization without wholesale rip-and-replace cycles. FIS Global dominates payment processing infrastructure in North America, sustaining renewal rates through embedded compliance updates.
Third-party banking software encompasses externally licensed applications that handle transaction processing, customer account management, and regulatory reporting, typically deployed through APIs or middleware layers that interface with legacy host systems. These platforms automate clearing, settlement, and customer onboarding functions that would otherwise require proprietary development by financial institutions. Core banking systems retain the largest installed base but carry the highest switching costs, while cloud-based deployment is expanding fastest among fintech companies and digital-first challengers seeking elastic infrastructure. Payment processing commands premium pricing due to real-time throughput requirements and embedded fraud detection protocols.
The European Banking Authority enforces stringent operational resilience standards under DORA that mandate third-party risk management and continuity planning for critical software dependencies. In the United States, the OCC and FDIC supervise vendor management practices through guidance that shapes contractual liability and audit rights for outsourced banking functions. India's RBI mandates data localization for payment systems, creating jurisdictional complexity for multi-tenant cloud deployments serving South Asian banks. Stakeholders must weigh regulatory fragmentation against standardization pressures when selecting between regional specialists and global platform providers.
Market Dynamics
Cloud-native core banking platforms are compressing implementation cycles from years to months, forcing incumbent vendors to restructure pricing models and delivery architectures around subscription consumption rather than perpetual licensing.
Growth Catalysts
- PSD2 Open Banking Mandates:European banks must expose payment initiation and account information APIs to licensed third parties, creating compulsory demand for middleware and compliance layers.
- Real-Time Payment Rails:FedNow in the United States and similar instant settlement systems in Brazil and India require banks to upgrade legacy batch-processing infrastructure.
- Margin Compression:Domestic US banks facing net interest margin squeeze are outsourcing non-differentiated functions to reduce fixed cost bases.
Market Restraints
- Data Localization Requirements:India's RBI mandates domestic storage for payment data, fragmenting cloud architectures and raising compliance costs for multi-tenant providers.
- Core System Switching Costs:Migration from mainframe-based cores involves contract renegotiation, staff retraining, and parallel run periods that extend 18-36 months.
- Cyber Insurance Underwriting:Concentrated third-party dependencies attract heightened scrutiny from Lloyd's syndicates and US carriers, elevating premium costs for banks.
Strategic Opportunities
- Embedded Finance Convergence:Non-bank retailers and platforms in Southeast Asia seek white-label banking stacks, opening distribution beyond traditional FI channels.
- DORA Operational Resilience:The European Banking Authority's 2025 enforcement timeline creates immediate demand for continuity planning and vendor risk management tools.
- AI-Driven Fraud Orchestration:Machine learning models for transaction monitoring are migrating from rule-based engines, requiring new API integration layers.
Industry Challenges
- Mainframe Talent Scarcity:Cobol and assembler programming expertise is retiring faster than universities produce replacements, complicating hybrid migration paths.
- API Standardization Friction:Fragmented open banking specifications across UK, Australia, and Brazil force vendors to maintain multiple connector versions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Third-Party Banking Software Market |
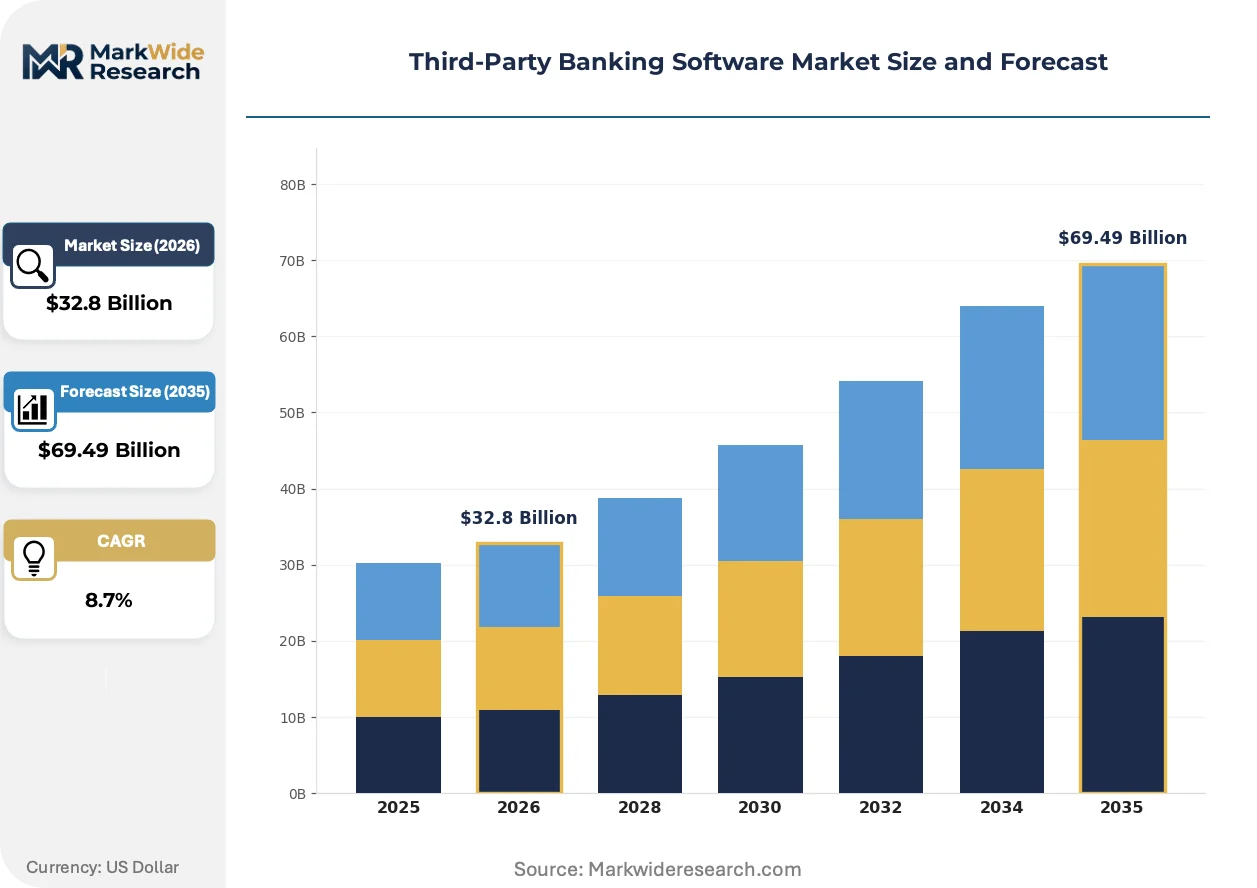
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $69.49 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Banking, Mobile Banking, Online Banking, Payment Processing Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Tenant End User: Retail Banks, Commercial Banks, Credit Unions, Fintech Companies Service Type: Consulting, Integration, Support, Maintenance |
| Companies Covered | Microsoft Corporation, Oracle Corporation, SAP, IBM Corporation, Temenos, FIS Global, Infosys Limited, Tata Consultancy Services Limited, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Third-Party Banking Software Market Strategic Shifts & Innovations
Distributed ledger interoperability and generative AI are converging to reshape how banking infrastructure handles settlement finality and customer interaction workflows.
Core processing workloads are migrating from on-premise mainframes to containerized cloud environments. Regional banks and credit unions lacking capital for data center expansion are adopting software-as-a-service cores from specialized vendors. This shift is compressing vendor consolidation timelines as mid-tier institutions bypass traditional tier-one suppliers.
The EU Digital Operational Resilience Act imposes mandatory third-party risk management and incident reporting thresholds for critical software dependencies. Banks must now map sub-contractor chains and test failover procedures under supervisory review. Nordic and German institutions are advancing fastest in compliance readiness, while Southern European banks lag in vendor documentation.
Subscription-based consumption models are displacing perpetual licenses across middle-market procurement. Finance teams prefer operational expenditure treatment for core transformations, while IT departments retain flexibility to scale modules incrementally. This pattern is most pronounced among US-based community banks with assets between $1 billion and $10 billion.
Third-Party Banking Software Market Segmentation
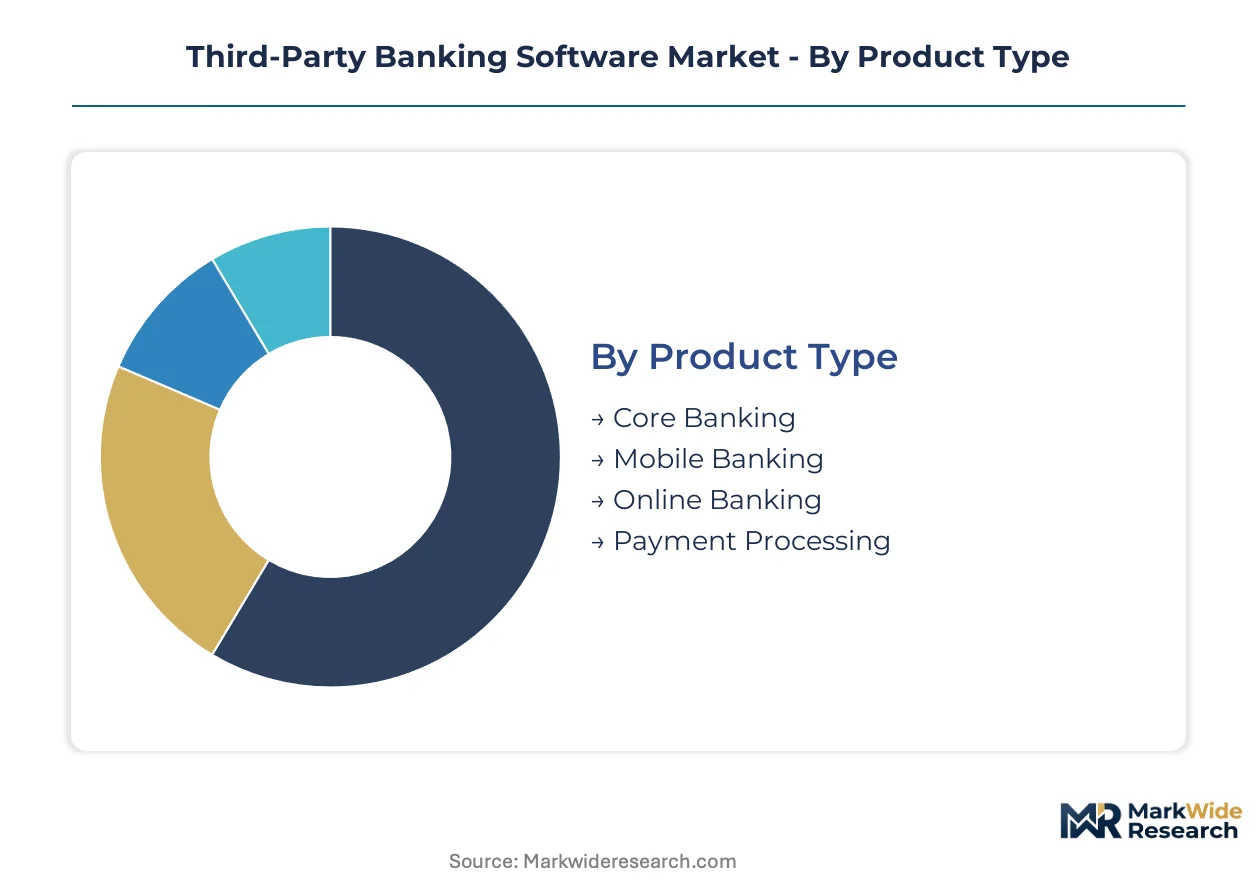
Third-party banking software procurement decisions hinge on deployment readiness, regulatory jurisdiction, and existing infrastructure debt. Institutions map vendor selection against core system age, cloud maturity, and compliance burden to optimize transformation timelines.
Product Type:
Mature transaction engines dominate installed capacity while emerging interface layers capture incremental investment.
- Core Banking:Centralized ledger systems manage account records, interest calculations, and regulatory reporting through batch-oriented architectures. US regional banks with mainframe dependencies drive replacement demand as Cobol expertise retires. Legacy switching costs and parallel run requirements extend procurement cycles.
- Payment Processing:Real-time clearing engines handle transaction routing, settlement finality, and fraud detection across card networks and instant payment rails. Brazilian and Indian banks upgrading to Pix and UPI respectively concentrate demand for throughput scalability. Premium pricing reflects 99.999% uptime requirements and embedded compliance modules.
- Mobile Banking:Native and responsive applications deliver account access, peer-to-peer transfers, and biometric authentication to retail customers.
- Online Banking:Browser-based portals support commercial treasury functions and bulk payment initiation for corporate clients.
Core Banking handles the majority of throughput; Payment Processing is the fastest mover on share.
Deployment:
Cost tier stratification separates capital-intensive on-premise builds from operational-expenditure cloud consumption.
- Cloud-Based:Containerized architectures enable elastic scaling and API-native integration without data center ownership. Southeast Asian digital banks and European neobanks favor multi-tenant SaaS cores to bypass infrastructure buildout. Subscription models align vendor incentives with customer success metrics.
- Hybrid:Split workloads maintain sensitive transaction processing on-premise while customer-facing channels migrate to cloud edge. German and French institutions with strict data residency requirements adopt this pattern to satisfy national regulators while modernizing delivery.
- On-Premise:Dedicated hardware installations persist among US credit unions with conservative risk appetites and existing facility investments.
- Multi-Tenant:Shared infrastructure instances reduce per-customer operational overhead for standardized banking functions.
Cloud-Based deployments are expanding most quickly; On-Premise retains the largest installed base.
End User:
Customer type determines feature depth, compliance complexity, and integration architecture requirements.
- Retail Banks:Branch networks and digital channels serving individual depositors require omnichannel consistency and mass-market onboarding automation. US community banks between $1 billion and $10 billion in assets concentrate procurement of cloud-native cores to compete with national institutions.
- Fintech Companies:Unlicensed technology platforms seeking embedded finance capabilities demand white-label banking stacks with rapid API deployment. Southeast Asian e-commerce platforms and Latin American payroll providers represent emerging demand clusters.
- Commercial Banks:Corporate lending and treasury management operations need multi-entity cash pooling and trade finance modules.
- Credit Unions:Member-owned cooperatives prioritize cost efficiency and shared service models over proprietary differentiation.
Retail Banks generate the largest contract value; Fintech Companies show the steepest adoption trajectory.
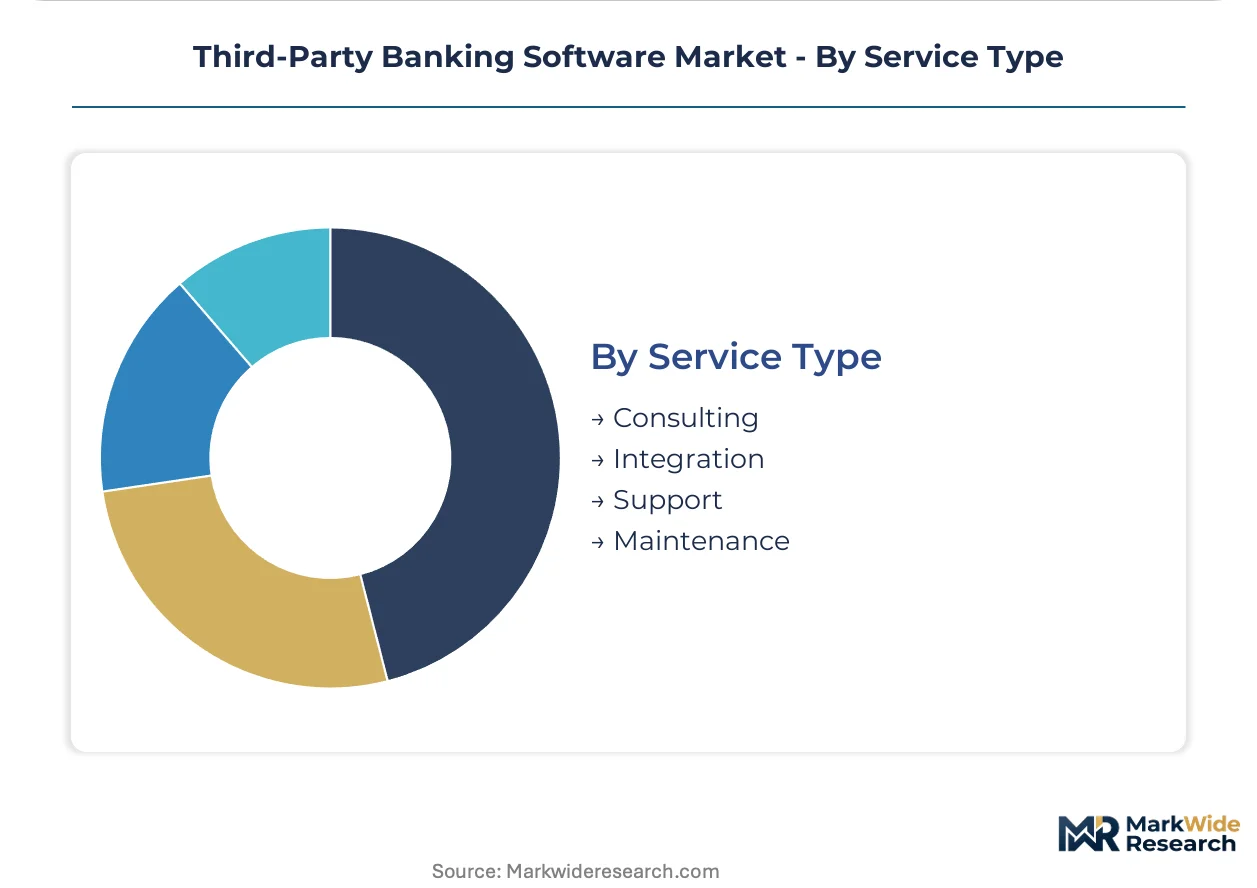
Service Type:
Margin structure varies sharply between high-touch consulting engagements and recurring support revenue.
- Integration:Middleware development and API mapping connect third-party platforms to legacy host systems with proprietary data formats. Indian system integrators and Eastern European development shops capture substantial implementation work for global vendors.
- Maintenance:Ongoing patch management, security updates, and regulatory compliance refreshes sustain long-term vendor relationships. US banks prioritize maintenance contracts with embedded cyber insurance and incident response commitments.
- Consulting:Business process redesign and vendor selection advisory guide transformation strategy before procurement execution.
- Support:Tiered help desk and technical escalation services resolve operational incidents and configuration issues.
Integration commands the highest project fees; Maintenance delivers the most predictable recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PSD2 enforcement across the European Union and FedNow deployment in the United States are reshaping procurement priorities for core banking modernization. Regulatory deadlines in India and Brazil are compressing vendor selection cycles. Cloud migration incentives in Southeast Asia are attracting SaaS providers to establish local data centers.
United States
FedNow real-time payment rails are forcing regional banks to upgrade batch-processing infrastructure. The OCC supervises vendor management practices through contractual liability guidance that shapes audit rights for outsourced functions. Community banks in the Southeast and Midwest with assets between $1 billion and $10 billion are accelerating cloud-native core adoption to compete with national institutions.
Germany
Strict data residency requirements under national banking supervision are sustaining hybrid deployment patterns. The EU Digital Operational Resilience Act mandates third-party risk management and incident reporting thresholds for critical software dependencies. Frankfurt-based institutions and Bavarian cooperative banks are advancing fastest in DORA compliance readiness and vendor documentation standards.
India
RBI-mandated data localization for payment systems is fragmenting cloud architectures and raising compliance costs for multi-tenant providers. The central bank's UPI expansion is concentrating demand for throughput scalability among domestic banks. Mumbai and Bangalore are emerging as hubs where system integrators capture substantial implementation work for global vendors.
Brazil
Pix instant payment system adoption is driving upgrades to legacy clearing infrastructure among mid-tier institutions. The central bank's open finance framework is compelling exposure of customer data APIs to licensed third parties. São Paulo-based fintechs and digital challengers are favoring multi-tenant SaaS cores to bypass infrastructure buildout.
United Kingdom
Open banking mandates under the Competition and Markets Authority are maturing into comprehensive variable recurring payment frameworks. The Financial Conduct Authority enforces operational resilience standards that shape vendor selection criteria. London's concentration of neobanks and fintech platforms is sustaining demand for white-label banking stacks with rapid API deployment capabilities.
Third-Party Banking Software Market Key Industry Players
On the supply side, the industry is consolidating around database heritage vendors, modular architecture specialists, and payment infrastructure incumbents. Tier-one providers anchor long-term contracts through data sovereignty guarantees and embedded compliance modules. Mid-tier SaaS vendors capture share through subscription consumption models that align vendor incentives with customer success metrics. Dominant competitive moves include strategic partnerships with system integrators and geographic expansion through local data center establishment.
Within the database-centric tier, Oracle Corporation and Microsoft Corporation exemplify providers leveraging infrastructure heritage to secure multi-year enterprise agreements. Temenos occupies a position representing modular architecture approaches that allow phased modernization without wholesale replacement cycles. FIS Global sits within the payment processing infrastructure segment where real-time throughput requirements and embedded fraud detection protocols command premium positioning.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| SAP |
| IBM Corporation |
| Temenos |
| FIS Global |
| Infosys Limited |
| Tata Consultancy Services Limited |
| Accenture |
| Others |
Cost & Logistics Intelligence
Indian system integrators and Eastern European development shops anchor upstream implementation capacity, concentrating margin capture in middleware development and API mapping while global vendors retain recurring maintenance revenue pools. This concentration feeds downstream into how financial institutions negotiate subscription versus perpetual licensing terms.
Pricing Analysis
Certification level under DORA and RBI data localization mandates creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with embedded compliance modules and cyber insurance commitments differentiating top-tier contracts. Pricing pressure stems from margin compression among US community banks seeking operational expenditure treatment for core transformations. Fintech companies show highest price sensitivity due to unlicensed status and capital constraints, while tier-one retail banks absorb premium pricing for data sovereignty guarantees.
Supply Chain Analysis
Tariff exposure between US and Indian IT services jurisdictions dominates supply chain risk assessment for implementation timelines. Software development capacity concentrates in India, Poland, and Romania, with cloud infrastructure provisioning drawing from hyperscaler regions in Ireland, Singapore, and Virginia. Raw material dependencies center on semiconductor components for on-premise hardware, API gateway licenses, and cybersecurity threat intelligence feeds. Single-source vulnerability persists in mainframe talent pools as Cobol expertise retires. Distribution runs through direct vendor sales teams, system integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third-party banking software represents a defensive-moat market where regulatory entrenchment and core system switching costs protect incumbent positions against pure-play SaaS challengers.
For Market Incumbents: Insulate renewal revenue through embedded compliance update commitments and data localization architecture investments. Oracle Corporation and Temenos should deepen API-native integration capabilities to counter modular challengers. Vertical integration into cyber insurance underwriting partnerships addresses Lloyd's syndicate scrutiny on concentrated third-party dependencies. Capacity addition in Mumbai and Bangalore captures RBI-mandated implementation demand.
For New Entrants and Emerging Players: Mid-market US community banks between $1 billion and $10 billion in assets represent the most penetrable entry point for cloud-native core alternatives. Southeast Asian embedded finance platforms seeking white-label banking stacks offer second-mover advantage outside traditional FI channels. Go-to-market execution should emphasize subscription consumption models with embedded DORA operational resilience tooling.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular architecture specialists lacking payment processing scale. Long-term viability across the next decade hinges on FedNow and Pix instant payment rail integration depth. Acquisition target archetype: SaaS core vendors with multi-tenant cloud deployments and existing RBI or EBA compliance certifications. Signal to watch: central bank open finance framework deadlines compressing vendor selection cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native middleware layers satisfy PSD2 and open banking mandate compliance requirements. |
| Geographic Expansion | Local data center establishment in Mumbai and São Paulo addresses RBI and Pix localization demands. |
| Strategic Partnership | System integrator alliances in Bangalore and Warsaw accelerate implementation for global vendors. |
| Acquisition of Specialist Firm | Cobol migration expertise targets mainframe talent scarcity complicating hybrid cloud transitions. |
| Product Launch | AI-driven fraud orchestration modules replace rule-based engines requiring new API integration layers. |
Research Approach
Two parallel data streams informed the analysis: structured conversations with banking technology executives, regulatory affairs leads at financial institutions, cloud procurement officers, and system integrator delivery heads; and secondary validation against SEC filings, EBA supervisory disclosures, RBI circulars, and hyperscaler capex reports. Bottom-up triangulation across vendor contract values and top-down reconciliation against institution IT spending surveys anchored market sizing.
Forecast inputs span deployment model, institution asset tier, integration complexity, and regional regulatory framework intensity across the projection horizon. CAGRs derive from segment-level adoption curves weighted by FedNow, Pix, and UPI implementation deadlines. Modeled variables include cloud migration velocity among community banks, DORA compliance spending patterns, and embedded finance penetration in Southeast Asia.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and net interest margin compression severity would shift procurement timing for core banking transformations. Forecasts reflect assumptions on regulatory deadline adherence and vendor consolidation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Corporate Banking Market
Banking
South America Challenger Banks Market
Banking
Smart Machines in Banking Market
Banking
Letter of Credit Confirmation Market
Banking
Europe Data Analytics in Banking Market
Banking
Banking-As-A-Service (Baas) Platform Market
Banking
US Commercial Banking Market
Banking
Biometrics for Banking and Financial Services Market
Banking
Mobile Banking Market
Banking
E-Banking Market
Banking
Global Neobanking Market
Banking
Italy Data Analytics in Banking Market
Banking
Southeast Asia Commercial Banking Market
Banking
Middle East and Africa Neobanking Market
Banking
Video Banking Service Market
Banking
Asia-Pacific Data Analytics in Banking Market