
 Blackstrap Molasses Market | 2026-2036
Blackstrap Molasses Market Size, Share, and Industry Trends Forecast 2026-2036
Blackstrap Molasses Market Intelligence
Sorghum syrup is consolidating share in certain regional sweetener applications, though blackstrap molasses retains cost advantages in bulk industrial channels. Cargill leverages its North American grain and sweetener infrastructure to anchor supply security for feed and food manufacturers. B&G Foods competes through branded retail distribution, while ED&F Man specializes in commodity trading and risk management across sugar derivatives.
Blackstrap molasses is the final byproduct of repeated sugarcane or sugar beet extraction, containing approximately 45-55% total sugars by weight alongside significant iron, calcium, and potassium content; manufacturers clarify and concentrate this viscous liquid for binding, fermentation, and mineral supplementation purposes. The organic blackstrap segment commands premium positioning in nutraceutical and health food store channels, while conventional blackstrap dominates animal feed volume. Liquid form leads industrial procurement for feed mills and breweries, though powder form is gaining traction in cosmetics and dry premix applications where handling efficiency matters.
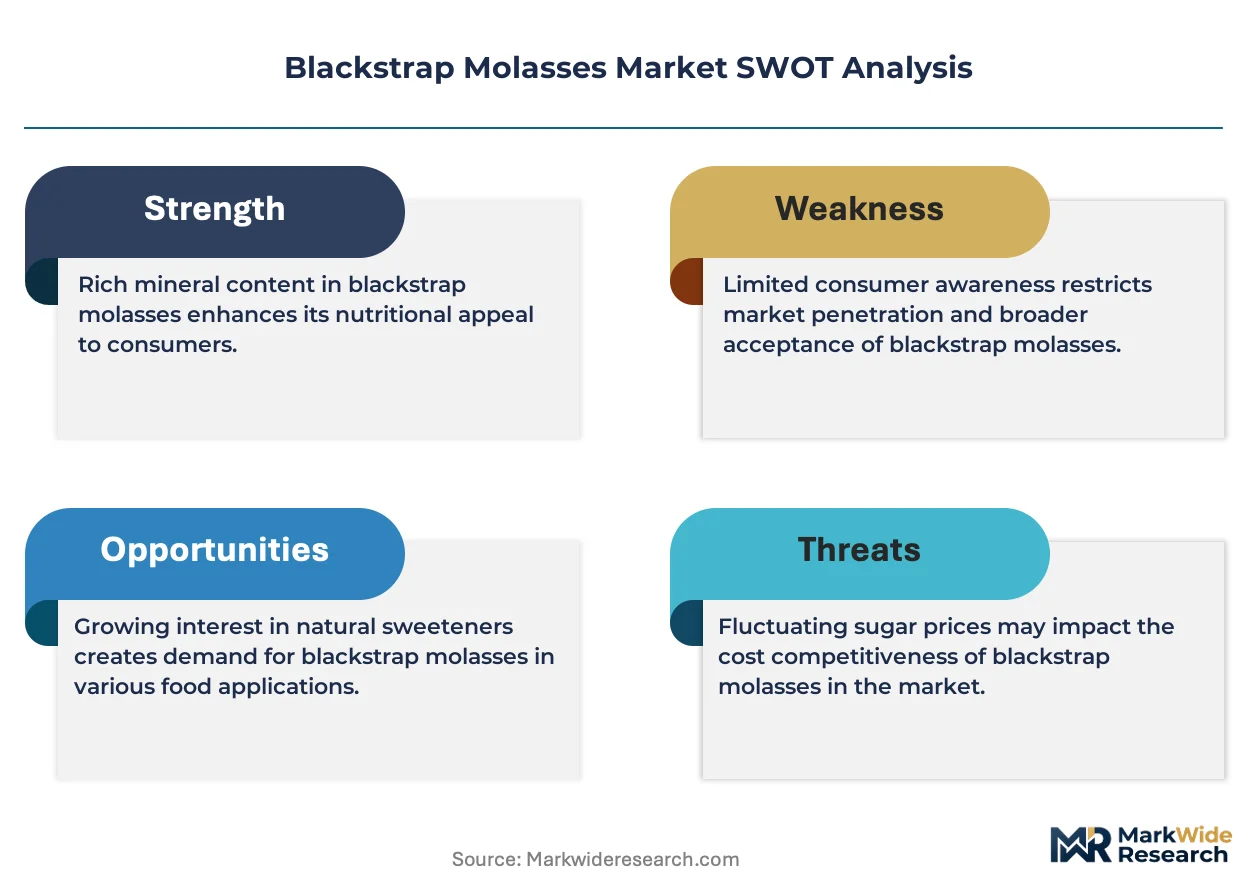
The U.S. FDA governs food-grade molasses under 21 CFR standards, while the EPA regulates agricultural runoff from cane processing facilities; Brazil's ANVISA and agricultural ministry oversee feed additive registration and environmental discharge permits for mills in São Paulo and Minas Gerais states. Stakeholders should monitor how carbon accounting rules and regenerative agriculture certifications reshape sourcing premiums and processor compliance costs.
Market Dynamics
Animal feed mills are consolidating procurement around integrated sugarcane processors, tightening the link between Brazilian ethanol production clusters and North American livestock nutrition supply chains. This supply-side concentration is compressing spot market liquidity and elevating long-term contract premiums.
Growth Catalysts
- FDA Feed-Grade Standards:Tighter purity requirements under 21 CFR are disqualifying low-grade molasses derivatives, channeling volume toward certified processors with clarification and concentration capabilities.
- Biofuel Co-Product Economics:Brazilian sugarcane mills are expanding blackstrap output as ethanol capacity scales, creating captive supply for integrated animal feed formulations.
- Fermentation Binding Demand:Breweries and distilleries are specifying liquid blackstrap for viscosity control in grain mashes, displacing synthetic binders in craft and industrial-scale operations.
Market Restraints
- Sugarcane Input Volatility:Weather-driven cane yield fluctuations in São Paulo state transmit directly to blackstrap availability, creating procurement uncertainty for feed mills without long-term supply agreements.
- Sorghum Syrup Substitution:Regional sweetener manufacturers in the US Southeast are promoting sorghum derivatives as drop-in replacements for certain binding applications, pressuring price points in non-feed channels.
- EPA Agricultural Runoff Rules:Discharge permits for cane processing facilities are tightening organic load limits, elevating compliance capital requirements for smaller independent mills.
Strategic Opportunities
- Organic Certification Premiums:ANVISA-aligned organic registration pathways in Brazil are opening specialized export channels to US nutraceutical distributors commanding 40-60% price markups over conventional grades.
- Powder Form Handling Efficiency:Spray-drying investments are unlocking dry premix applications in cosmetics and fortified food manufacturing where liquid logistics costs previously excluded blackstrap.
- Carbon Accounting Integration:Regenerative agriculture certification schemes are attaching sourcing premiums to molasses from mills with verified methane capture and bagasse co-generation systems.
Industry Challenges
- Clarification Chemistry Expertise:The shift toward higher-purity feed-grade specifications is exposing talent gaps in pH adjustment and heavy metal precipitation processes at mid-scale processors.
- Multi-Jurisdiction Registration Timelines:Simultaneous FDA, EPA, and ANVISA compliance pathways are extending product qualification cycles to 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blackstrap Molasses Market |
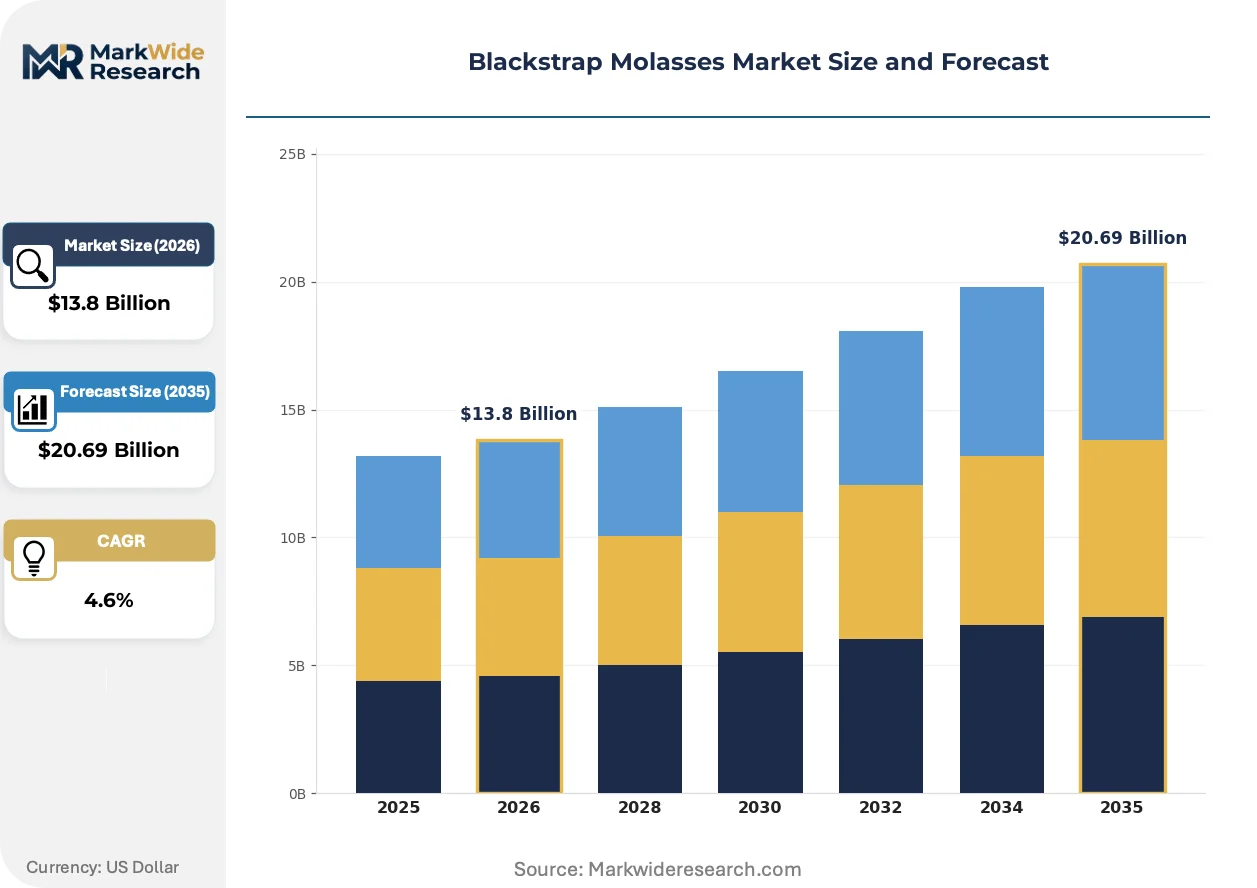
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Blackstrap, Conventional Blackstrap, Unsulfured Blackstrap, Sulfured Blackstrap End Use Industry: Food & Beverage, Animal Feed, Nutraceuticals, Cosmetics Form: Liquid, Powder, Granular, Syrup Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | B&G Foods, Archer Daniels Midland, Cargill, Zook Molasses Company, Crosby Molasses, Allied Old English, ED&F Man, Malt Products Corporation, Buffalo Molasses, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blackstrap Molasses Market Strategic Shifts & Innovations
Processing technology is advancing faster than end-use specification standards, creating interim mismatches between what mills can produce and what buyers are certified to accept. The gap is driving parallel investments in both capability expansion and regulatory harmonization.
Membrane filtration systems for sugarcane juice clarification are converging with traditional heat-concentration methods, enabling mills to recover higher-value sucrose fractions while simultaneously upgrading blackstrap purity for feed-grade applications. Mid-scale Brazilian processors are retrofitting existing evaporator trains with ceramic membrane skids, compressing the capital gap against integrated multinational facilities.
REACH-aligned chemical safety dossiers are extending disclosure requirements to agricultural co-products entering EU feed and food channels, compelling Brazilian exporters to document heavy metal and pesticide residue profiles across entire cane supply bases. Feed additive distributors serving the Netherlands and Germany are now requiring batch-level certificates of analysis, shifting compliance burdens upstream to mill laboratories.
Consolidated livestock operations in the US Midwest are bypassing traditional molasses traders to contract directly with Brazilian processor cooperatives, collapsing historical distribution layers. These arrangements specify quarterly volume commitments with quality-adjusted pricing, displacing spot-market procurement at regional feed mills in Iowa and Nebraska.
Blackstrap Molasses Market Segmentation
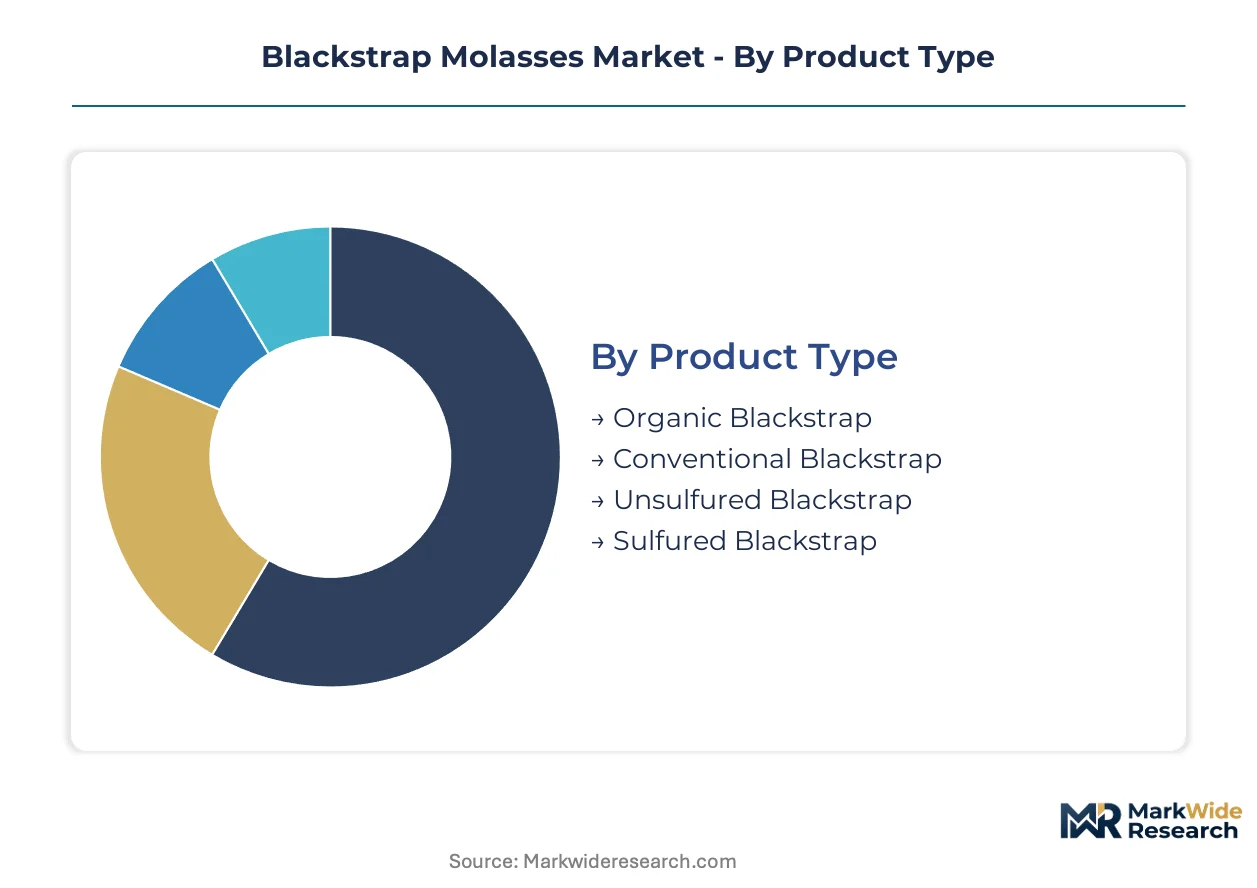
Blackstrap molasses procurement splits sharply between commodity-scale industrial buyers and premium-channel health food distributors. Understanding where volume concentrates versus where margins expand determines processor investment priorities and certification strategies.
Product Type:
Volume flows through conventional processing lines while certified organic commands disproportionate margin capture in export channels.
- Organic Blackstrap:Produced from cane cultivated without synthetic pesticides or fertilizers, meeting USDA Organic and EU Organic standards. Demand concentrates in US nutraceutical distributors and German health food retailers where ANVISA-aligned Brazilian certification unlocks 40-60% price premiums over conventional grades.
- Conventional Blackstrap:Standard extraction from chemically-treated cane fields dominates animal feed formulations and industrial fermentation. North American feed mills in Iowa and Nebraska source this grade through long-term contracts with São Paulo processor cooperatives, displacing spot-market procurement.
- Unsulfured Blackstrap:Processed without sulfur dioxide preservation, preferred by clean-label food manufacturers.
- Sulfured Blackstrap:Treated with sulfur dioxide for extended shelf stability in bulk storage and shipping.
Today's leader: Conventional Blackstrap. Tomorrow's challenger: Organic Blackstrap.
End Use Industry:
Application mix reflects divergent specification requirements across feed-grade purity standards and cosmetic-grade heavy metal limits.
- Animal Feed:Binding agent and energy source in ruminant and swine nutrition, with FDA 21 CFR feed-grade standards tightening purity requirements. Brazilian ethanol co-production clusters supply integrated North American livestock supply chains, compressing spot market liquidity.
- Food & Beverage:Natural sweetener and colorant in baked goods, sauces, and brewing applications where viscosity control displaces synthetic binders.
- Nutraceuticals:Mineral supplementation source capitalizing on iron, calcium, and potassium content in health food store channels.
- Cosmetics:Humectant and exfoliant ingredient where powder form handling efficiency matters for dry premix formulations.
Feed-grade tonnage anchors current revenue. Nutraceutical-grade purity commands the steepest expansion trajectory.
Form:
Physical state selection hinges on logistics economics and downstream processing compatibility.
- Liquid:Dominates industrial procurement for feed mills and breweries requiring viscosity control in grain mashes. Brazilian mills ship bulk liquid via tanker to North American ports, minimizing packaging costs at scale.
- Powder:Spray-dried form gaining traction in cosmetics manufacturing and fortified dry premixes where handling efficiency and reduced moisture content justify processing premiums.
- Granular:Intermediate moisture format for specialty feed applications requiring controlled dissolution rates.
- Syrup:Higher-moisture variant for direct consumer culinary use and certain confectionery applications.
Liquid form holds installed base advantage. Powder form represents the fastest-growing adoption curve as dry premix applications multiply.
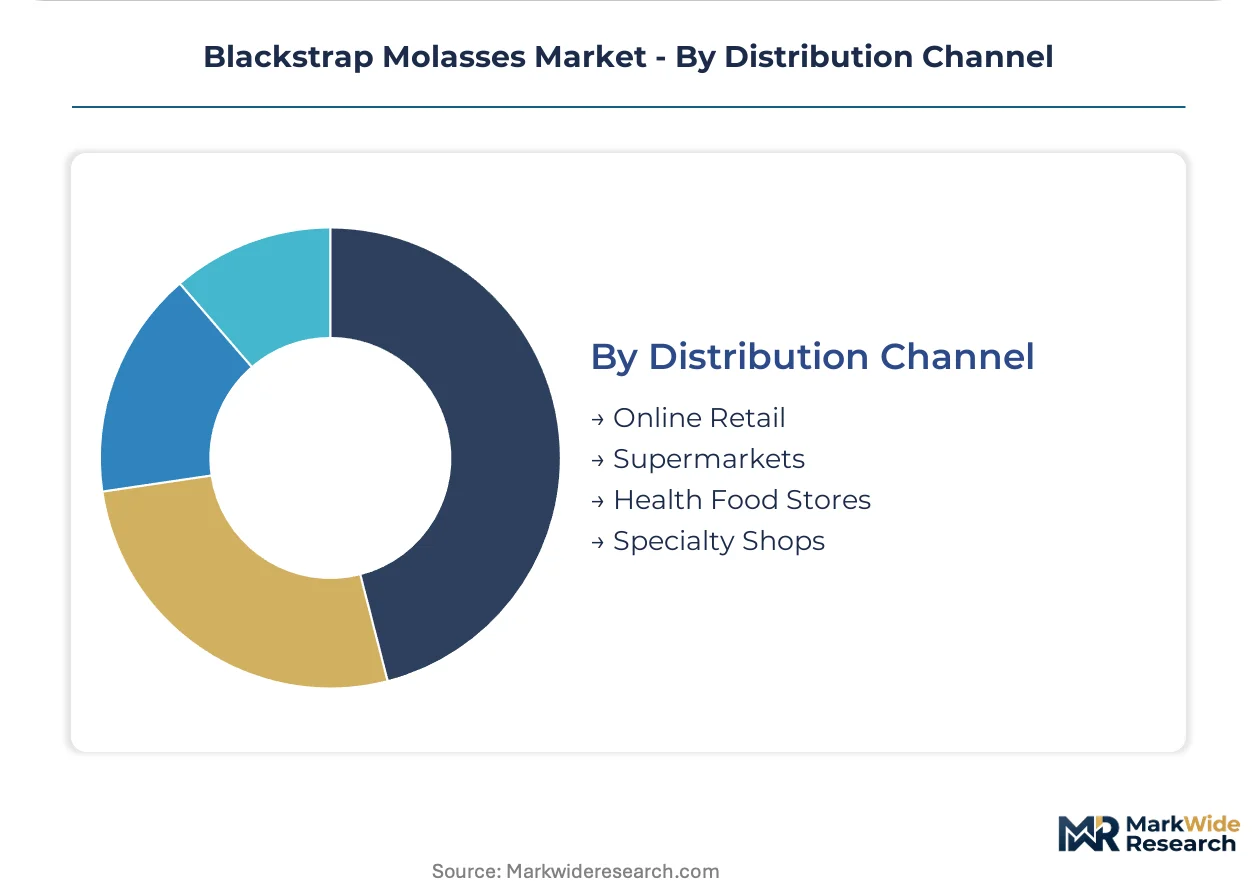
Distribution Channel:
Channel selection separates commodity volume flows from branded premium capture.
- Supermarkets:Mass retail placement for consumer-sized molasses containers, typically conventional grades in syrup form.
- Health Food Stores:Premium positioning for organic and unsulfured variants with mineral content labeling, serving nutraceutical-oriented consumers.
- Online Retail:Direct-to-consumer growth channel enabling subscription models for specialty grades and bulk purchasing.
- Specialty Shops:Ethnic grocery and brewing supply outlets serving niche culinary and craft fermentation demand.
Supermarkets move the most units. Health food stores extract the highest per-unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's sugarcane processing corridor anchors blackstrap molasses supply chains, with Brazilian ethanol co-production clusters feeding integrated North American livestock nutrition networks. Regional procurement patterns concentrate around three regulatory jurisdictions shaping purity standards and trade flows.
Brazil
ANVISA feed additive registration requirements and agricultural ministry discharge permits govern mill operations across São Paulo and Minas Gerais states. The country's national environmental regulator enforces organic load limits on cane processing effluent. São Paulo's Ribeirão Preto cluster hosts integrated ethanol-blackstrap facilities supplying long-term contracts to Iowa and Nebraska feed mills.
United States
FDA 21 CFR feed-grade standards disqualify low-grade molasses derivatives, channeling volume toward certified processors with clarification capabilities. The EPA regulates agricultural runoff from cane processing facilities under tightening discharge permit frameworks. Midwest livestock operations in Iowa and Nebraska bypass traditional traders to contract directly with Brazilian processor cooperatives.
Germany
REACH-aligned chemical safety dossiers extend disclosure requirements to agricultural co-products entering EU feed channels. EFSA standards govern mineral supplementation claims in nutraceutical applications. Hamburg and Rotterdam port distributors now require batch-level certificates of analysis, shifting compliance burdens upstream to Brazilian mill laboratories.
India
FSSAI standards govern food-grade molasses safety while the country's national agricultural regulator oversees feed additive quality parameters. Maharashtra and Uttar Pradesh sugar belts generate substantial blackstrap volumes from cane crushing operations. Mumbai-based trading houses coordinate bulk liquid shipments to Southeast Asian feed compounders.
Canada
Health Canada and PMRA frameworks regulate feed-grade additive purity and pesticide residue thresholds in imported molasses. The country's national food safety agency aligns with FDA standards for cross-border trade harmonization. Vancouver and Montreal port terminals handle transshipment volumes destined for US Midwest feed mill networks.
Blackstrap Molasses Market Key Industry Players
Global majors compete with regional champions across supply security and certification capabilities. The vendor base splits between integrated agribusiness conglomerates with captive cane supply and specialized commodity traders focused on risk management and logistics optimization. Three archetypes dominate: North American grain infrastructure operators, branded retail distributors, and sugar derivatives trading specialists. Competitive moves center on backward integration into Brazilian ethanol co-production assets and spray-drying capacity investments for powder form expansion.
Within the integrated infrastructure tier, Cargill exemplifies supply security positioning through North American grain and sweetener network control. B&G Foods occupies a branded retail distribution archetype competing through consumer-facing channel presence. ED&F Man represents the commodity trading specialist model, anchoring risk management capabilities across sugar derivatives markets. These three entities collectively illustrate how scale, brand, and trading expertise partition competitive terrain without overlapping strategic positioning.
| Leading Market Players |
|---|
| B&G Foods |
| Archer Daniels Midland |
| Cargill |
| Zook Molasses Company |
| Crosby Molasses |
| Allied Old English |
| ED&F Man |
| Malt Products Corporation |
| Buffalo Molasses |
| Others |
Cost & Logistics Intelligence
Captive supply integration into Brazilian ethanol co-production assets anchors both procurement security and contract pricing power for North American feed mill buyers. This structural choice locks in volume commitments with quality-adjusted pricing while displacing spot-market exposure.
Pricing Analysis
Input-cost pass-through from sugarcane yield volatility in São Paulo state transmits directly to blackstrap contract renegotiation cycles. Three-tier pricing structure across organic-certified, feed-grade conventional, and industrial fermentation grades separates premium nutraceutical channels from commodity animal feed tonnage. Pricing pressure stems from sorghum syrup substitution in US Southeast binding applications. Feed-grade buyers exhibit highest price sensitivity due to thin margins in livestock nutrition, while organic nutraceutical distributors accept steep markups for certified supply security.
Supply Chain Analysis
Dual-sourcing requirements from Iowa and Nebraska feed mills now mandate simultaneous qualification of at least two Brazilian processor cooperatives per procurement cycle. Geographic supply concentration centers on Brazil, India, and Thailand as dominant cane-processing jurisdictions. Raw material dependencies include sugarcane biomass, sulfur dioxide preservation agents, and ceramic membrane filtration components. Single-source vulnerability runs through São Paulo state weather exposure. Distribution runs through bulk liquid tanker shipments to North American port terminals with secondary rail distribution to Midwest feed mill networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blackstrap molasses market functions as a stable compounder anchored by irreplaceable demand from ruminant nutrition formulations where synthetic binders fail on palatability metrics.
For Market Incumbents: Deploy backward integration into São Paulo ethanol co-production assets to secure captive blackstrap output. Cargill and Archer Daniels Midland should expand clarification chemistry capabilities to meet tightening FDA 21 CFR feed-grade standards while sorghum syrup substitution threatens non-feed channels. Certification investment in ANVISA-aligned organic registration unlocks 40-60% export premiums to German health food retailers. For New Entrants and Emerging Players: Powder-form cosmetic ingredient buyers represent an underserved archetype with limited incumbent spray-drying capacity. White-space targets include dry premix manufacturers in fortified food and cosmetics where handling efficiency justifies processing premiums. The most penetrable entry point runs through ANVISA-certified organic production with direct distribution to US nutraceutical distributors bypassing commodity traders. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Brazilian processors with membrane filtration retrofit capabilities because consolidation captures both ethanol co-product synergies and feed-grade certification premiums. Long-term viability frames around 5-10 year livestock sector stability with carbon accounting integration as upside optionality. Target acquisition archetype: São Paulo-state mills with verified methane capture and ANVISA organic registration pathways. The signal to watch is EPA agricultural runoff rule tightening on discharge permits, which would accelerate independent mill distress sales.| Strategic Initiative | Industry Significance |
|---|---|
| Spray-Drying Capacity Expansion | Unlocks powder-form entry into cosmetics and fortified dry premix channels previously excluded by liquid logistics costs. |
| ANVISA Organic Registration | Opens specialized export channels to German health food retailers commanding steep premiums over conventional grades. |
| Membrane Filtration Retrofit | Enables mid-scale Brazilian processors to meet tightening FDA 21 CFR feed-grade purity specifications. |
| Direct Processor Cooperative Contracts | Collapses historical trader layers between São Paulo mills and Iowa-Nebraska feed mill buyers. |
| Carbon Accounting Certification | Attaches sourcing premiums to molasses from mills with verified methane capture and bagasse co-generation. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary interviews captured perspectives from sugarcane mill operations managers, North American feed mill procurement directors, Brazilian agricultural ministry regulators, ANVISA compliance officers, and German nutraceutical distributors. Secondary validation drew from FDA 21 CFR feed additive filings, ANVISA organic registration databases, EPA discharge permit records, EU REACH chemical safety dossiers, and Brazilian agricultural ministry cane processing statistics. Bottom-up volume modeling triangulated against top-down value projections across product type, end use, and form dimensions.
Comparable-period anchoring aligned the projection horizon against historical reference cycles spanning sugarcane harvest seasons and feed-grade specification evolution. Segmentation dimensions modeled included organic versus conventional certification grade, animal feed versus nutraceutical versus cosmetic end use, and liquid versus powder physical form. CAGRs derived from regression analysis of volume trajectories with industry-specific inputs capturing ethanol co-production economics and FDA purity standard tightening timelines.
Underlying measurement precision varies by segment; organic blackstrap carries tighter precision due to certification audit trails while conventional feed-grade estimates reflect broader procurement survey dispersion. Forecasts reflect assumptions around Brazilian cane yield stability, EPA regulatory trajectory, and sorghum syrup substitution elasticity. Deviation in São Paulo state weather patterns or ANVISA registration processing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Juice Concentrates Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Global Vinegar Market
Beverages
Carbonated Soft Drinks Market
Beverages
Direct Piping Water Dispenser Market
Beverages
US Bubble Tea Market
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Still Drinks Market
Beverages
Drinking Water Market
Beverages
Canned Beverages Market
Beverages
Fruit Water Market
Beverages
Beverage Dispenser Market
Beverages
United States Recovery Drinks Market
Beverages
Sports Drink Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Bangladesh Energy Drinks Market