
 Global Tool Holder Adapters Market | 2026-2036
Global Tool Holder Adapters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tool Holder Adapters Market Outlook
The distributor channel for precision tooling is fragmenting as direct-to-factory digital platforms erode traditional wholesale margins. Sandvik Coromant leverages its captive foundry network to control carbide substrate quality from mine to finished holder. Kennametal Inc. anchors North American demand through localized heat-treatment facilities that shorten lead times for automotive tier-one suppliers. Haimer GmbH specializes in shrink-fit and balancing systems that command premium positioning in German aerospace machining corridors.
Tool holder adapters are mechanical interface devices that secure cutting tools to machine tool spindles, typically incorporating tapered shanks with HSK or BT form factors and runout tolerances below 0.003 mm to maintain dimensional fidelity during high-speed rotation. Their primary purpose is to transfer torque and axial positioning accuracy from the spindle to interchangeable cutting inserts across milling, turning, and drilling operations. Collet adapters capture growing share in Swiss-type lathe applications where bar-feed diameters shift frequently, while locking adapters dominate heavy roughing cycles in steel forging where vibration damping determines insert life. CNC Machining technology sustains the largest installed base but 3D Printing of conformal-cooling adapter bodies is gaining traction in aerospace blade-root machining where thermal distortion limits conventional designs.
ISO spindle taper standards, Germany's DIN 69893 HSK specifications, and Japan's JIS B 6339 BT conventions collectively define interoperability requirements that constrain new entrants lacking certification laboratory relationships. The EU Machinery Directive and OSHA machine-guarding rules in the United States further mandate automatic tool changer reliability thresholds that drive replacement cycles in aging European and North American metalworking parks. Stakeholders must monitor how China's GB standards for polygonal tapers converge with or diverge from ISO baselines, as this alignment choice will determine adapter inventory strategies for multinational tool suppliers serving dual-certified production networks.
Market Dynamics
ISO 26623 polygonal taper standardization and carbide-insert coating advances are compressing procurement cycles as aerospace OEMs demand tighter runout tolerances below 0.003 mm for fleet modernization programs.
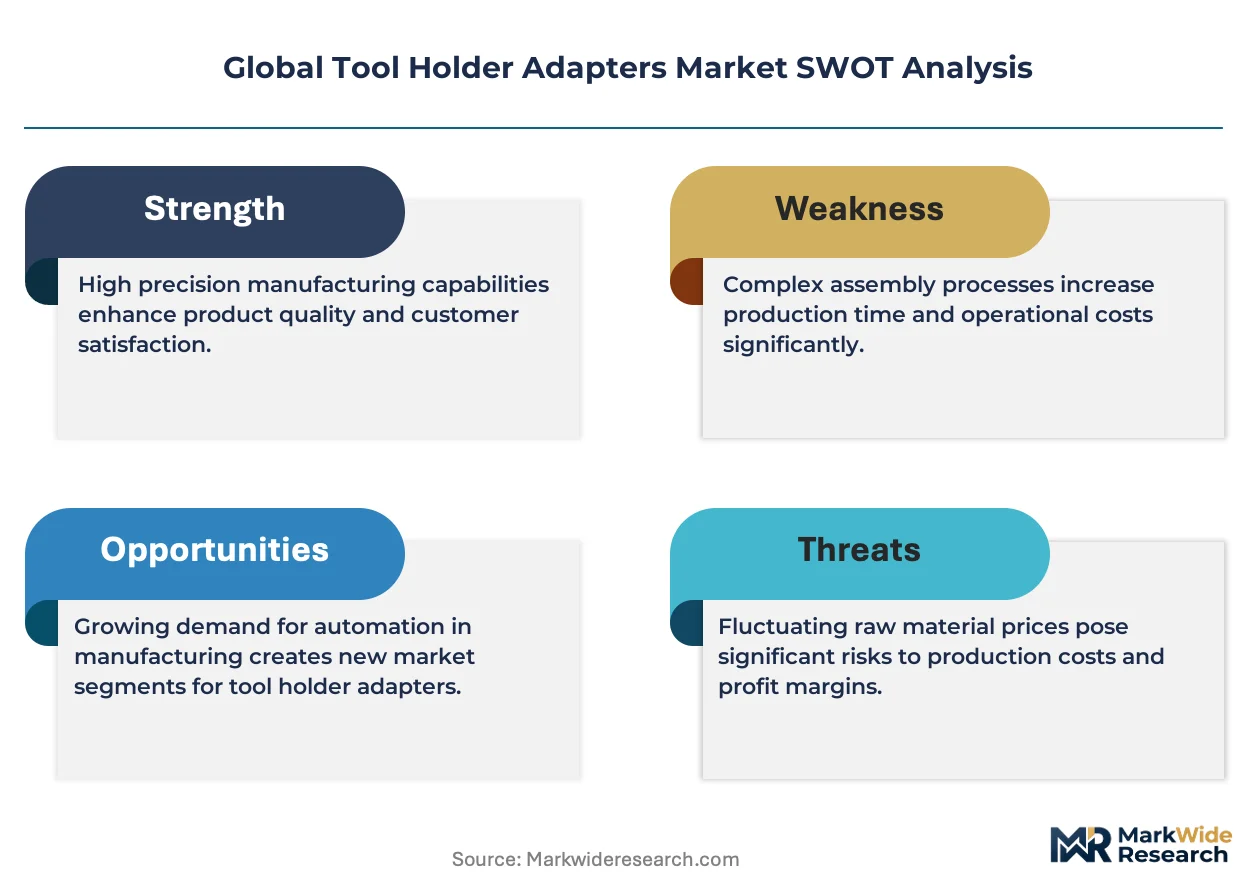
Growth Catalysts
- Aerospace Manufacturing Modernization:Fleet renewal programs in Germany, Japan, and the United States are mandating HSK and BT form factor upgrades to achieve sub-micron precision in turbine blade machining.
- EU Machinery Directive:Automatic tool changer reliability thresholds are accelerating replacement cycles across aging European metalworking parks, forcing certified adapter inventory expansion.
- Carbide Substrate Quality Control:Captive foundry networks spanning mine-to-finished-holder supply chains are reducing thermal distortion defects in high-speed rotation applications.
Market Restraints
- Tungsten Carbide Price Volatility:Raw material cost swings for cemented carbide substrates constrain margin predictability for precision tooling suppliers.
- German-Japanese Supply Concentration:DIN 69893 HSK and JIS B 6339 BT certification laboratory relationships cluster in Stuttgart and Nagoya corridors, limiting new entrant access.
- Steel Forging Vibration Limits:Heavy roughing cycle physics cap locking adapter penetration in forging applications where insert life depends on damping performance beyond current material science.
Strategic Opportunities
- India Precision Machining Clusters:BIS standards convergence with ISO baselines creates inventory arbitrage potential for multinational suppliers serving dual-certified production networks.
- Conformal-Cooling Additive Manufacturing:3D printing of adapter bodies with internal cooling channels addresses thermal distortion limits in aerospace blade-root machining that conventional designs cannot solve.
- Direct-to-Factory Digital Platforms:Erosion of traditional wholesale margins opens channel restructuring for tier-one automotive suppliers seeking shortened lead times.
Industry Challenges
- Metrology Technician Scarcity:Runout measurement below 0.003 mm requires specialized spindle balancing expertise concentrated in German aerospace machining corridors.
- Dual Certification Timeline Compression:China's GB standards divergence risk from ISO baselines forces parallel inventory strategies that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tool Holder Adapters Market |
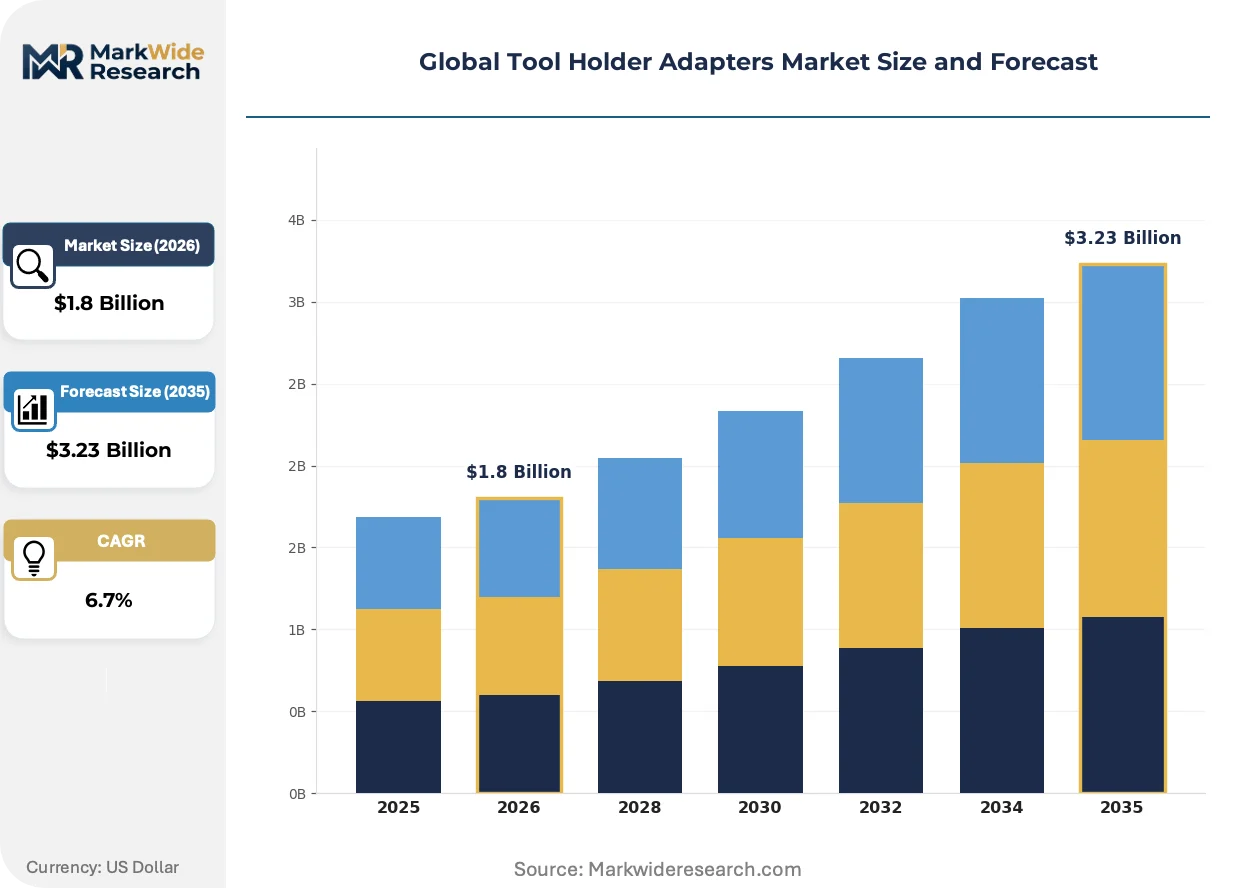
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locking Adapters, Collet Adapters, V-Flange Adapters, Boring Tool Adapters Technology: CNC Machining, 3D Printing, Injection Molding, Die Casting Application: Aerospace Manufacturing, Automotive Assembly, Metalworking, Woodworking End User: Manufacturers, Tool Shops, OEMs, Aftermarket Providers |
| Companies Covered | Sandvik Coromant, Kennametal Inc., Haimer GmbH, BIG Kaiser Precision Tooling Inc., Guhring KG, Seco Tools AB, Emuge-Franken, NT Tool Corporation, Mapal Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tool Holder Adapters Market Strategic Shifts
Digital thread integration across machine tool ecosystems is virtualizing adapter specification workflows, compressing the gap between spindle interface design and cutting tool procurement.
Shrink-fit clamping technology with integrated balancing systems is virtualizing mechanical collet redundancy in Swiss-type lathe applications. Medical device manufacturers in Switzerland and Minnesota are adopting these systems for bar-feed diameter flexibility. The technology is virtualizing inventory complexity by collapsing multiple collet sizes into single-holder platforms.
REACH substance restrictions on cobalt-containing carbide substrates are forcing coating chemistry reformulations across EU-serving production networks. Adapter manufacturers are migrating to nickel-based binder alternatives to maintain tool life performance. German automotive tier-one suppliers are demanding REACH-compliant certification documentation ahead of 2025 supply contract renewals.
After-sales service unbundling is fragmenting traditional distributor value capture in North American metalworking markets. Tier-one suppliers now procure adapters through direct manufacturer portals while sourcing maintenance separately. This pattern is most visible in Michigan and Ohio automotive machining corridors where OEMs negotiate tool life guarantees independent of holder purchase.
Global Tool Holder Adapters Market Segmentation
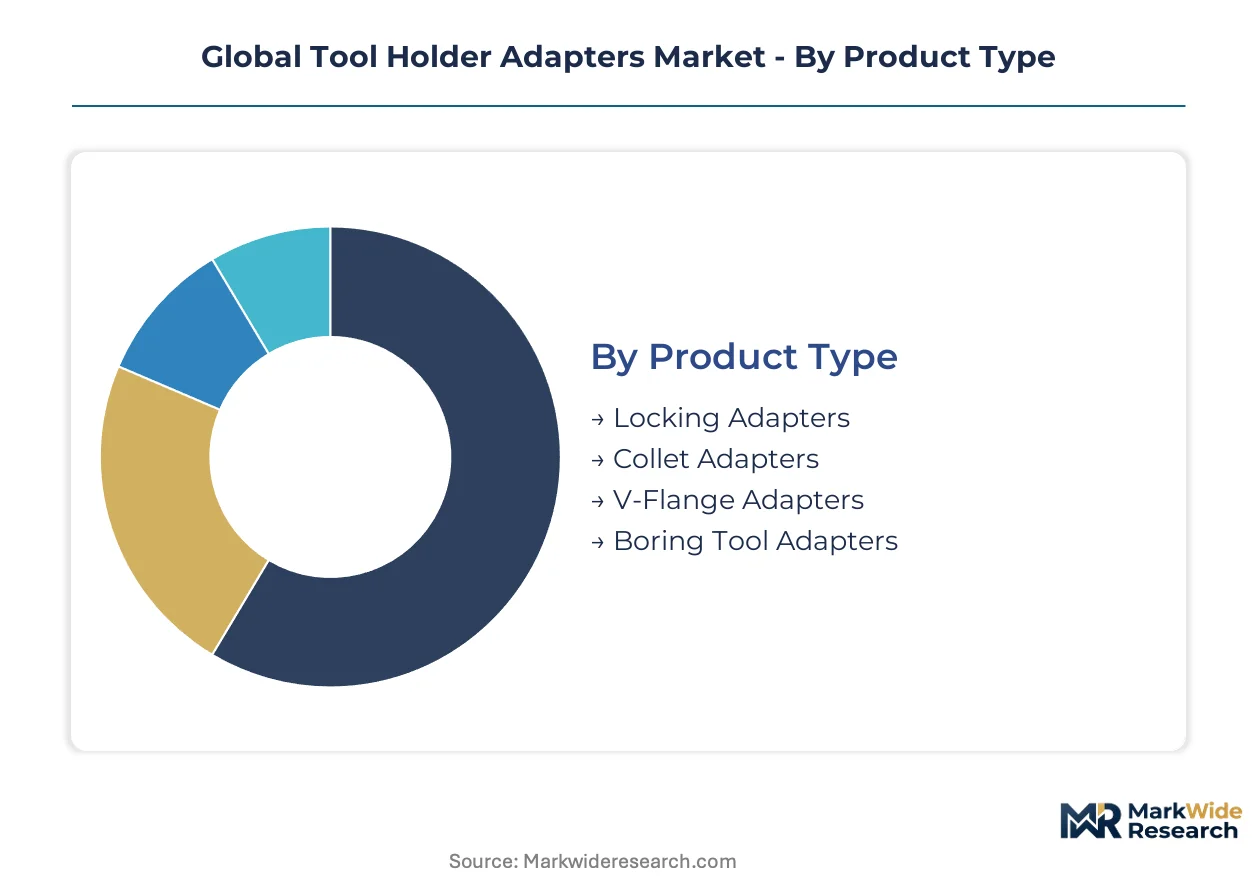
Tool holder adapter segmentation reveals how interface geometries, production methods, and end-use precision requirements fragment procurement patterns across metalworking ecosystems. Each dimension carries distinct certification burdens and margin structures that reshape supplier positioning.
Product Type:
Mature taper interfaces dominate installed bases while emerging clamping mechanisms capture high-speed machining retrofit demand.
- Locking Adapters:Mechanical clamping systems with threaded retention mechanisms secure heavy cutting loads in steel forging operations. German automotive tier-one suppliers specify these for roughing cycles where vibration damping determines insert life.
- Collet Adapters:Spring-loaded collet systems grip cylindrical shanks with radial uniformity, enabling rapid tool changes. Swiss-type lathe applications in Minneapolis medical device corridors drive adoption for bar-feed diameter flexibility.
- V-Flange Adapters:Tapered flange interfaces per CAT and BT standards remain prevalent in legacy vertical machining centers.
- Boring Tool Adapters:Modular boring heads with fine-adjustment mechanisms target precision hole-finishing operations.
Locking adapters handle the majority of throughput in heavy roughing; collet adapters are gaining share fastest in Swiss-type automation.
Technology:
Cost tiers separate subtractive legacy methods from emerging additive and near-net-shape production routes.
- CNC Machining:Precision milling and grinding of hardened tool steel delivers sub-0.003 mm runout tolerances required for aerospace spindle interfaces. Stuttgart and Nagoya machining corridors sustain the largest installed capacity for HSK-certified holder production.
- 3D Printing:Laser powder bed fusion builds conformal-cooling channels within adapter bodies, addressing thermal distortion limits in aerospace blade-root machining that conventional solid designs cannot solve.
- Injection Molding:High-pressure aluminum and zinc die casting suits high-volume standard adapter production for price-sensitive automotive applications.
- Die Casting:Gravity and pressure casting methods produce near-net-shape blanks requiring minimal finish machining.
CNC machining retains volume leadership; 3D printing expands most quickly in aerospace thermal management applications.
Application:
Customer type concentration varies sharply across end-use precision requirements and regulatory exposure.
- Aerospace Manufacturing:Turbine blade and structural component machining mandates HSK polygonal taper interfaces with sub-micron runout. Fleet modernization programs in Germany, Japan, and the United States compress procurement cycles for certified adapter inventory.
- Automotive Assembly:Powertrain and chassis component production favors BT-form factor adapters in high-volume transfer lines. Michigan and Ohio machining corridors specify localized heat-treatment capabilities to shorten tier-one supplier lead times.
- Metalworking:General-purpose job shops balance holder cost against versatility across mixed material processing.
- Woodworking:Lower-speed routing and milling applications tolerate higher runout tolerances and standard V-flange interfaces.
Aerospace manufacturing commands premium positioning; automotive assembly delivers the steepest volume expansion trajectory.
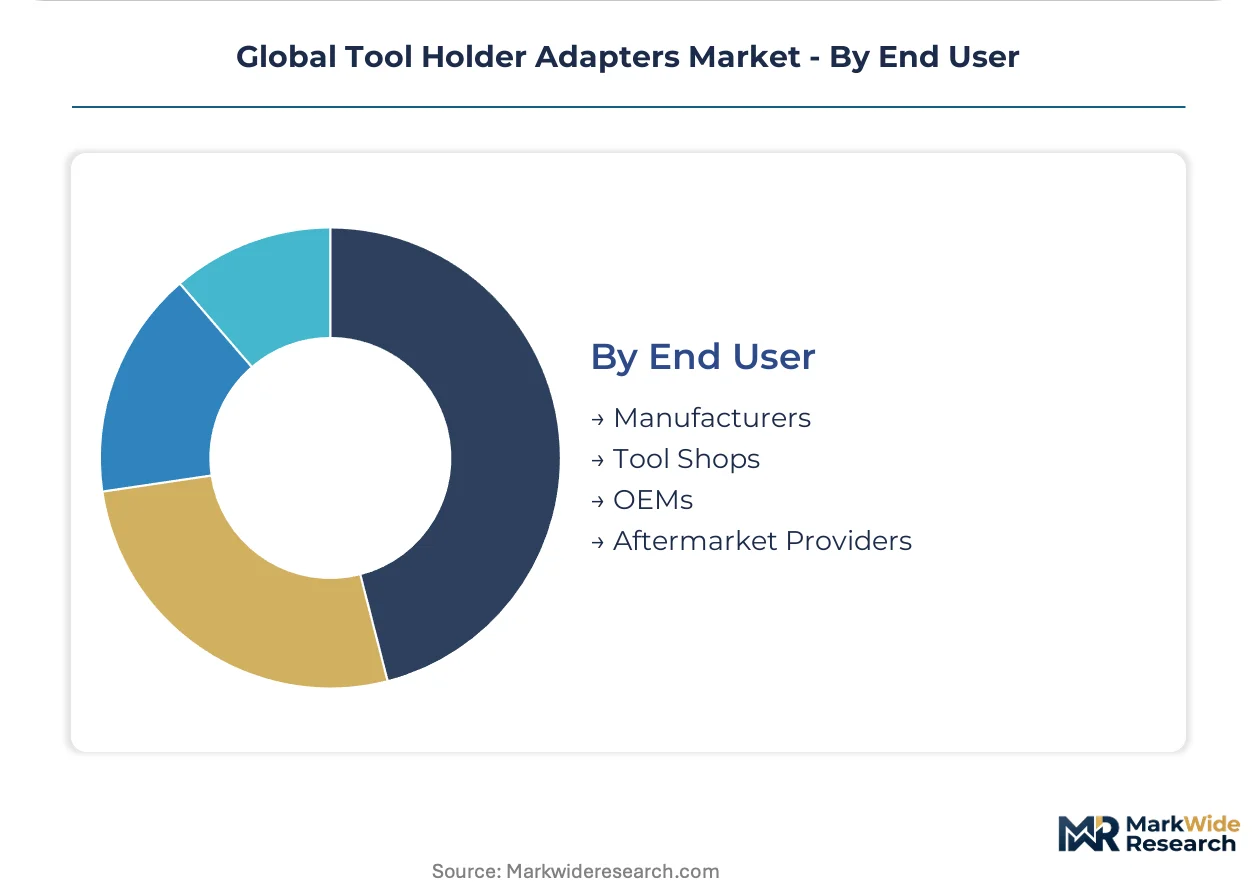
End User:
Margin structures diverge between captive production networks and independent service providers.
- Manufacturers:Captive tool rooms within aerospace and automotive OEMs specify holder adapters for internal spindle populations. Direct-to-factory digital platforms are eroding traditional distributor margins in this segment.
- Tool Shops:Independent precision machining contractors demand adapter versatility across customer specifications. REACH substance restrictions on cobalt-containing carbides are forcing coating chemistry reformulations for EU-serving shops.
- OEMs:Machine tool builders bundle certified adapters with new spindle deliveries to guarantee interoperability.
- Aftermarket Providers:Replacement and retrofit specialists stock legacy taper formats for aging European and North American metalworking parks.
Manufacturers represent the largest addressable base; tool shops are climbing fastest on share as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers command pricing premiums exceeding those in Indian machining corridors by margins tied to DIN 69893 HSK certification scarcity. Aerospace OEMs in Stuttgart and Nagoya corridors absorb these premiums for sub-micron runout tolerances below 0.003 mm. The United States automotive belt shortens lead times through localized heat-treatment networks that bypass transatlantic shipping dependencies.
United States
Michigan and Ohio automotive machining corridors drive BT-form factor adapter procurement for powertrain transfer lines. OSHA machine-guarding rules mandate automatic tool changer reliability thresholds that accelerate replacement cycles in aging metalworking parks. Detroit-area tier-one suppliers negotiate tool life guarantees through direct manufacturer portals that erode traditional distributor margins.
Germany
Stuttgart precision machining clusters sustain captive foundry networks spanning mine-to-finished-holder supply chains for aerospace turbine blade applications. EU Machinery Directive compliance forces certified adapter inventory expansion across Baden-Württemberg production networks. DIN 69893 HSK specifications concentrate metrology technician expertise in corridors where runout measurement below 0.003 mm remains scarce.
Japan
Nagoya aerospace corridors demand JIS B 6339 BT polygonal taper interfaces for fleet modernization programs with sub-micron precision requirements. METI industrial standards align with ISO 26623 baselines that constrain new entrant certification access. Chubu region machine tool builders bundle certified adapters with spindle deliveries to guarantee interoperability for automotive tier-one suppliers.
China
Yangtze River Delta machining clusters face GB standards divergence risk from ISO baselines that force parallel inventory strategies. MIIT industrial policy drives dual-certified production network expansion for multinational tool suppliers. Shanghai-area precision manufacturers navigate REACH substance restriction compliance for cobalt-containing carbide substrates through nickel-based binder alternatives.
India
Maharashtra and Gujarat precision machining corridors benefit from BIS standards convergence with ISO baselines that creates inventory arbitrage potential. CDSCO medical device regulations in Mumbai-Pune belt drive Swiss-type lathe adapter adoption for bar-feed diameter flexibility. Bangalore aerospace subcontractors absorb HSK-certified holder premiums for turbine component export contracts to European OEMs.
Global Tool Holder Adapters Market Competitive Environment
Integrated metallurgy specialists and precision interface fabricators split the market between captive carbide substrate control and outsourced certification-dependent production. The vendor base concentrates around certification laboratory relationships in Stuttgart and Nagoya corridors that limit new entrant access. Three archetypes dominate: diversified tooling conglomerates with backward integration into raw material supply, mid-scale precision specialists focused on shrink-fit and balancing systems, and regional fabricators serving price-sensitive automotive volume contracts. Competitive moves center on captive foundry network expansion and direct-to-factory digital platform deployment that collapses wholesale distribution tiers.
Among diversified tooling conglomerates, Sandvik Coromant and Kennametal Inc. exemplify archetypes built on captive supply chain control over carbide substrate quality from mine to finished holder. Haimer GmbH occupies a position within the precision specialist tier focused on shrink-fit and balancing systems that command premium positioning in German aerospace machining corridors. These three entities represent the span of competitive positioning from integrated metallurgy through precision interface specialization.
| Leading Market Players |
|---|
| Sandvik Coromant |
| Kennametal Inc. |
| Haimer GmbH |
| BIG Kaiser Precision Tooling Inc. |
| Guhring KG |
| Seco Tools AB |
| Emuge-Franken |
| NT Tool Corporation |
| Mapal Group |
| Others |
Value Chain & Pricing Dynamics
Tungsten carbide price volatility determines both pricing tier spreads and supply chain shape across precision tooling networks, compressing margins for standard-grade adapters while amplifying premiums for certified HSK and BT form factors with captive substrate control.
Pricing Analysis
Configured-to-order pricing for sub-0.003 mm runout HSK-certified adapters commands spreads exceeding standard V-flange inventory by certification scarcity and metrology technician concentration. Three-tier pricing structure across aerospace-grade, automotive-transfer-line, and job-shop economy levels stratifies by DIN 69893 and JIS B 6339 compliance tiers. Cost compression in standard collet adapters intensifies because direct-to-factory digital platforms erode distributor markups. Automotive tier-one suppliers in Michigan exhibit highest price sensitivity; Stuttgart aerospace OEMs absorb premium positioning for shrink-fit balancing systems.
Supply Chain Analysis
Captive foundry networks in Germany, Japan, and the United States hold capacity for mine-to-finished-holder carbide substrate production. Raw material flows draw from cemented tungsten carbide mines, nickel-based binder alternatives for REACH compliance, and precision-ground tool steel blanks. Single-source vulnerability concentrates in Stuttgart and Nagoya certification corridors where DIN 69893 and JIS B 6339 laboratory relationships limit new entrant access. Distribution runs through direct manufacturer portals eroding wholesale tiers alongside traditional distributor channels serving independent tool shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conformal-cooling additive manufacturing and REACH substance restrictions on cobalt-containing carbides are accelerating technological and regulatory inflections across adapter procurement networks.
For Market Incumbents: Pre-empt margin erosion in standard taper adapters by deepening captive foundry control over nickel-based binder chemistry for EU-serving production networks. Consolidate metrology technician training pipelines in German aerospace corridors to defend HSK certification scarcity against emerging Indian precision machining clusters. For New Entrants and Emerging Players: Establish a beachhead in Maharashtra and Gujarat precision machining corridors where BIS standards convergence with ISO baselines creates inventory arbitrage potential. Target Swiss-type lathe adapter demand in Minneapolis medical device belts through bar-feed diameter flexibility positioning. Deploy direct-to-factory digital platforms to bypass entrenched wholesale distribution tiers. For Investors and Strategic Acquirers: EU Machinery Directive automatic tool changer reliability thresholds reshape the acquisition landscape toward certified adapter inventory holders with aging European metalworking park replacement exposure. Five-to-ten year viability favors precision specialists with shrink-fit balancing system expertise over commodity automotive volume players. Monitor China's GB standards divergence or convergence with ISO baselines as the critical inflection signal for multinational dual-certified production network strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Network Expansion | Backward integration into carbide substrate mining secures margin control against tungsten price swings. |
| Direct-to-Factory Digital Platform Deployment | Channel restructuring collapses wholesale tiers for tier-one automotive supplier access in Michigan corridors. |
| Conformal-Cooling Additive Manufacturing Scale-Up | Laser powder bed fusion builds thermal management channels for aerospace blade-root machining applications. |
| REACH-Compliant Coating Chemistry Reformulation | Nickel-based binder migration maintains tool life performance for EU-serving production networks. |
| Certification Laboratory Relationship Investment | DIN 69893 and JIS B 6339 access in Stuttgart and Nagoya corridors constrains competitive entry. |
Study Parameters
A spread of perspectives from spindle interface design engineers, automotive tier-one procurement directors, aerospace manufacturing quality managers, and precision tooling distributor principals converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from ISO standard documentation, EU Machinery Directive compliance filings, SEC 10-K disclosures from listed tooling conglomerates, and customs trade data for cemented carbide substrate flows. Bottom-up adapter shipment tallies by form factor and top-down metalworking capital expenditure patterns were triangulated to anchor volume estimates.
Demand-supply-balance framing across the analysis window modeled aerospace fleet modernization program timing against captive foundry capacity expansion in German and Japanese machining corridors. Segmentation dimensions included taper interface geometry, production technology route, end-use precision requirement, and customer type margin structure. CAGRs were derived from regression analysis of historical adapter procurement cycles correlated with machine tool shipment data and regulatory replacement mandates. Industry-specific inputs encompassed HSK and BT form factor adoption curves and REACH substance restriction implementation timelines.
Stress conditions across tungsten carbide price volatility bands, China GB standards divergence scenarios, and metrology technician supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding ISO 26623 polygonal taper standardization pace and automotive electric vehicle transition impacts on powertrain machining demand. Quarterly review of certification laboratory capacity utilization and cobalt substitute coating performance metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Mallets and Sledgehammers Market
Tools
Bandsaw Machines Market
Tools
Belt File Sander Market
Tools
Wood-Burning Tool Market
Tools
Cordless Fillet Weld Grinder Market
Tools
North America Power Tools Market
Tools
Power Press Machines Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Structural Wood Screws Market
Tools
Floor Polishing Machine Market
Tools
Automated Plasma Beveller Market
Tools
Diamond Core Drilling Market
Tools
Paint Spray Guns Market
Tools
Foam Engraving Machines Market
Tools
Portable Boring Machines Market
Tools
Automotive Torque Tools Market