
 Commercial Kettles and Braising Pans Market | 2026-2036
Commercial Kettles and Braising Pans Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Kettles and Braising Pans Market Intelligence
Modular equipment bundling is rebalancing procurement patterns across commercial kitchens as buyers seek integrated cooking stations rather than standalone units. Illinois Tool Works leverages its diversified component portfolio to anchor supply relationships with large-scale foodservice operators. Ali Group competes through broad brand architecture spanning multiple price tiers and regional service networks. Middleby Corporation sustains manufacturing scale advantages across its portfolio of commercial cooking brands.
Commercial kettles and braising pans constitute large-capacity, thermally efficient vessels designed for batch cooking, braising, and simmering operations in professional food preparation environments, typically constructed from stainless steel with steam-jacketed or direct-contact heating surfaces rated for continuous duty cycles. Their primary commercial purpose centers on delivering consistent thermal distribution and volume throughput for institutional and high-volume foodservice operations. Steam-jacketed kettles dominate installed base across mature foodservice markets where energy recovery and precise temperature control anchor replacement demand. Electric resistance systems lead new specification in urban hospitality venues constrained by gas infrastructure limitations. Automated braising pans represent the fastest-growing configuration as labor cost pressures drive capital investment toward programmable cooking cycles.
NSF International standards govern equipment sanitation and materials safety for North American commercial kitchen certification, while CE marking requirements under EU machinery directives shape European market access protocols. The EU F-Gas Regulation progressively constrains refrigerant and thermal system chemistries, indirectly influencing heating technology selection across imported equipment categories. Stakeholders must monitor evolving energy efficiency thresholds as regulatory bodies tighten operational performance benchmarks without grandfathering existing installations.
Market Dynamics
Modular equipment bundling is rebalancing procurement patterns across commercial kitchens as buyers seek integrated cooking stations rather than standalone units. Central kitchen investments by hotel chains across Southeast Asia are accelerating replacement cycles for steam-jacketed kettles and programmable braising systems.
Growth Catalysts
- NSF International certification tightening:North American sanitation standards are forcing equipment upgrades across institutional foodservice operations. Replacement demand concentrates in hospital and university kitchen renovations.
- Electric resistance heating:Urban hospitality venues constrained by gas infrastructure limitations are specifying electric braising pans for new construction projects. This technology shift bypasses utility connection delays in dense metropolitan zones.
- Vietnam manufacturing clusters:Regional foodservice procurement is concentrating in Vietnamese production hubs serving Southeast Asian hotel chains. Central kitchen standardization drives volume commitments from multinational operators.
Market Restraints
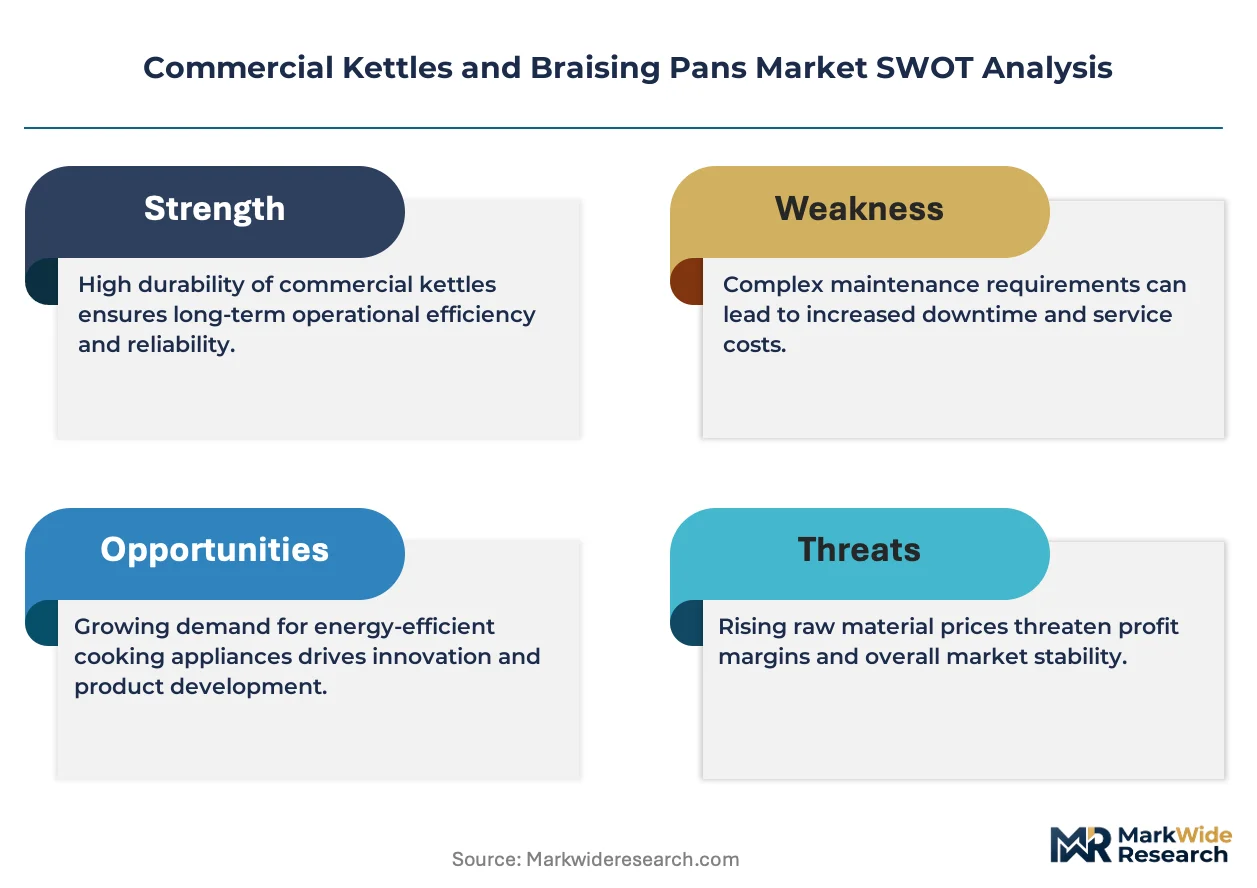
- Stainless steel input volatility:Raw material price swings compress margin stability for equipment fabricators. Grade 304 and 316 sheet stock exposure creates quarterly pricing friction.
- Steam infrastructure dependency:Steam-jacketed kettle penetration remains capped where boiler capacity is absent. Retrofit costs for legacy buildings exceed capital budgets in aged institutional facilities.
- EU F-Gas Regulation constraints:Thermal system chemistries face progressive phase-down schedules. Equipment importers must redesign heating architectures to maintain CE marking compliance.
Strategic Opportunities
- Automated braising pan white space:Programmable cooking cycles with HACCP logging capture labor cost-sensitive segments. Correctional facilities and aged care operators represent underpenetrated specification channels.
- Direct-contact induction retrofit:Energy efficiency mandates in German commercial kitchens are accelerating displacement of conventional gas braising pans. Induction surface technology enables precise temperature profiling for sauce reduction applications.
- Cloud-connected kitchen integration:IoT-enabled kettles with predictive maintenance alerts are penetrating multi-site foodservice operators. Remote diagnostics reduce downtime costs across distributed central kitchen networks.
Industry Challenges
- Certification timeline compression:NSF International and UL listing procedures extend product launch windows. Concurrent multi-jurisdiction approvals strain engineering resource allocation.
- Skilled technician scarcity:Steam-jacketed vessel repair expertise concentrates with aging workforce cohorts. Training pipeline gaps threaten aftermarket service quality in secondary metropolitan markets.
- Legacy control system incompatibility:Programmable braising pan integration with existing kitchen management software requires custom middleware development. Data protocol fragmentation across vendor ecosystems complicates unified fleet management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Kettles and Braising Pans Market |
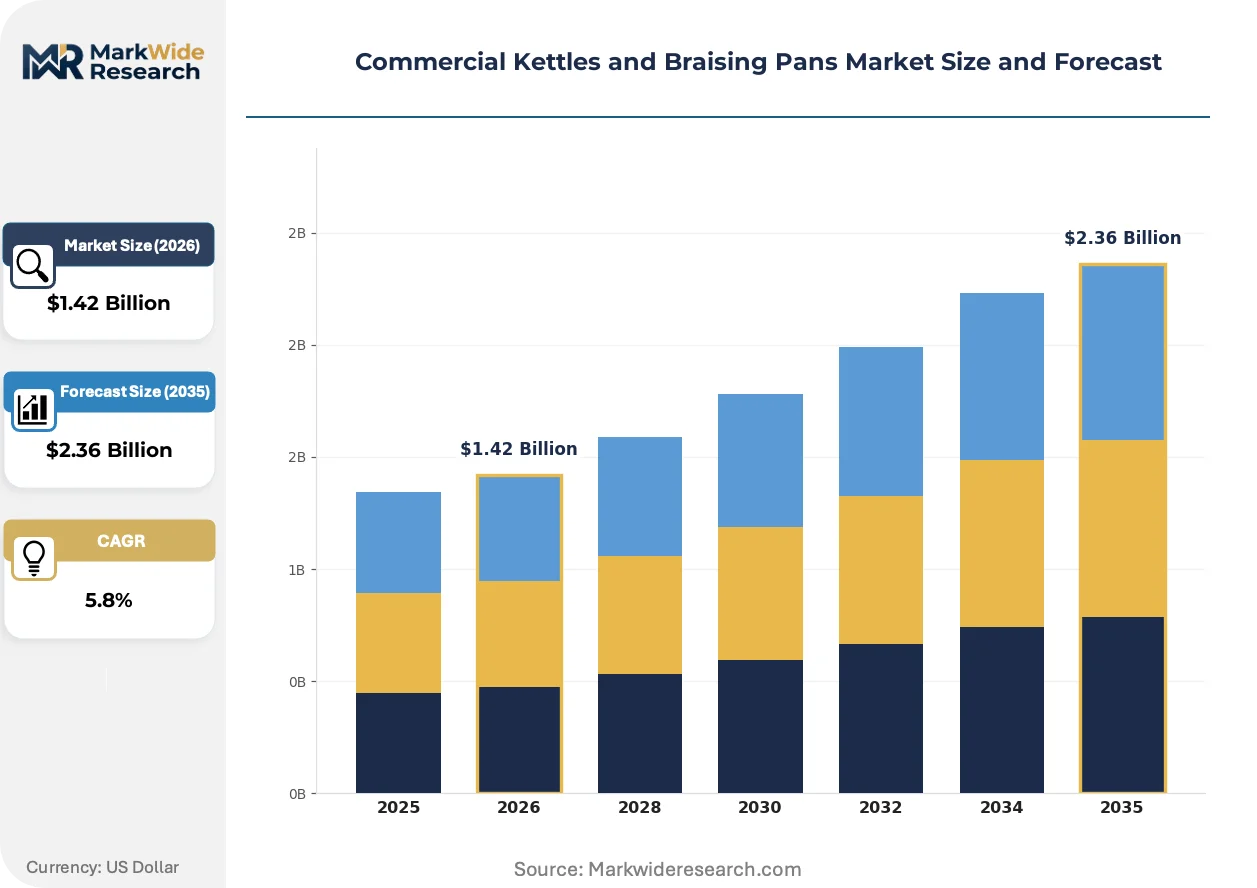
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
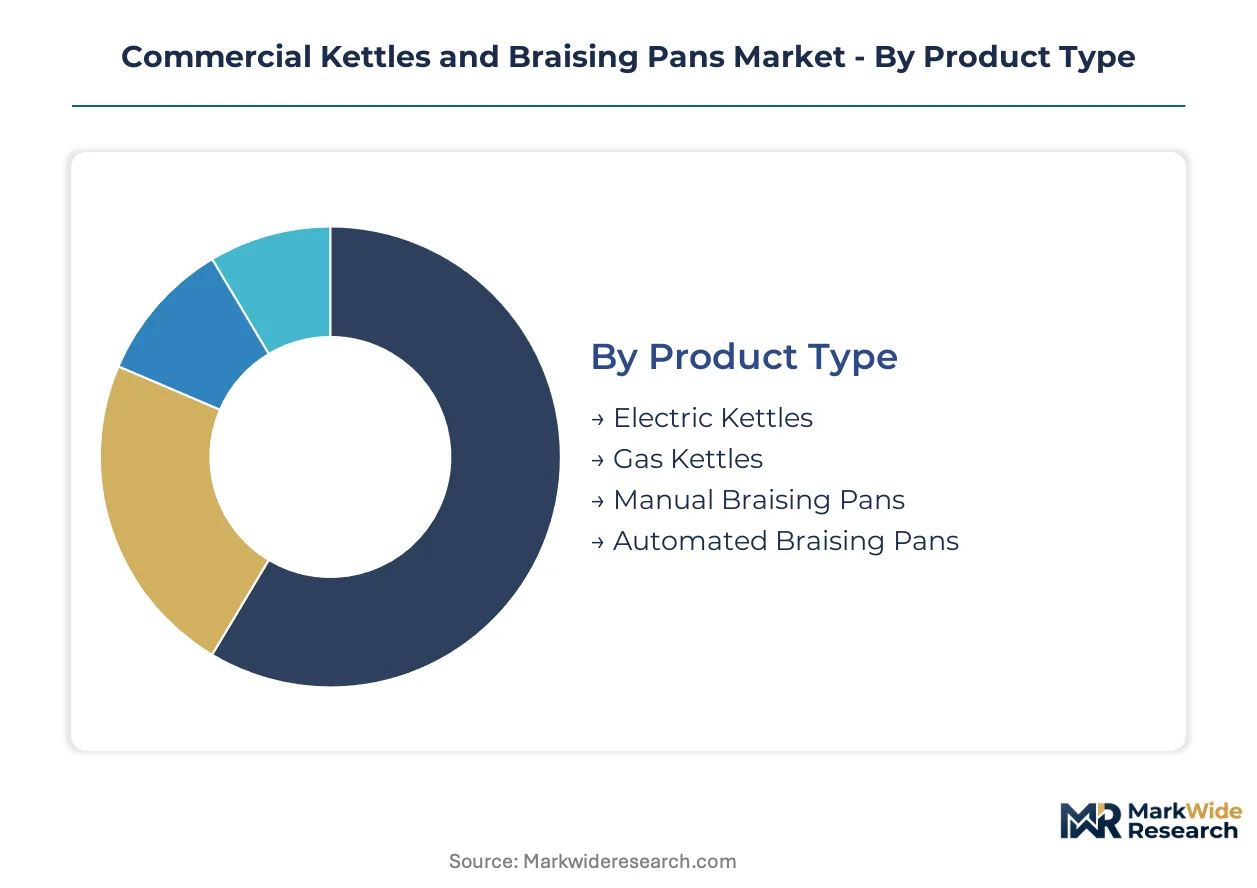
| Segmentation | Product Type: Electric Kettles, Gas Kettles, Manual Braising Pans, Automated Braising Pans Heating Technology: Induction, Direct Flame, Steam Jacketed, Electric Resistance, Radiant, Convection Application: Foodservice Establishments, Institutional Kitchens, Catering Services, Hospitality Venues, Food Processing Units End User Industry: Catering Companies, Restaurants, Hotels, Event Management, Culinary Schools |
| Companies Covered | Illinois Tool Works, AB Electrolux, Ali Group, Öztiryakiler, RATIONAL Group, Middleby Corporation, Dover Corporation, Nilma, Welbilt Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Kettles and Braising Pans Market Strategic Shifts & Innovations
Active reshaping of the commercial kettle and braising pan landscape centers on thermal efficiency optimization, regulatory chemistry constraints, and procurement model rationalization. Equipment specification is migrating toward outcome-verified performance rather than rated capacity alone.
Induction heating technology is absorbing capital allocation from conventional gas and electric resistance systems in European and East Asian urban foodservice construction. High-efficiency induction surfaces deliver sub-minute temperature recovery and eliminate open-flame ventilation requirements. Hotel chains in Singapore and Tokyo are specifying induction braising pans for below-grade kitchen fit-outs where gas infrastructure is prohibitively expensive.
EU F-Gas Regulation phase-down schedules are compressing refrigerant-dependent thermal system designs in imported equipment categories. Manufacturers must reformulate heating chemistries or abandon steam-jacketed architectures entirely. North American exporters face retooling costs to maintain CE marking access as 2024-2025 threshold dates approach for high-global-warming-potential working fluids.
Equipment-as-a-service contracting is displacing outright purchase in multi-site institutional operators. Bundled maintenance, certification renewal, and technology refresh cycles reduce capital budget volatility for hospital and university procurement departments. This model concentrates in US and Canadian healthcare systems where operating lease structures align with public sector accounting requirements.
Commercial Kettles and Braising Pans Market Segmentation
Equipment specification across the commercial kettle and braising pan market fragments along thermal system architecture, operational scale, and regulatory compliance tiers. Procurement decisions increasingly weight total cost of ownership against upfront capital outlay as energy efficiency mandates tighten across major foodservice markets.
Product Type:
Supply concentration tilts toward programmable configurations as labor cost pressures reshape kitchen capital planning.
- Automated Braising Pans:Programmable cooking cycles with integrated HACCP data logging enable precise thermal profiling for sauce reduction and protein braising. Demand concentrates in US correctional facilities and aged care operators where labor substitution justifies premium pricing. Cloud-connected fleet management capabilities differentiate vendor offerings in multi-site healthcare systems.
- Steam-Jacketed Kettles:Double-walled vessels with steam circulation deliver uniform heat distribution for high-volume batch cooking of soups, stocks, and pasta. Hospital and university kitchen renovations across Germany and France drive replacement demand as energy recovery systems improve operational efficiency. NSF International certification requirements anchor North American specification standards.
- Electric Kettles:Direct-contact resistance heating elements serve urban hospitality venues where gas infrastructure constraints limit fuel options.
- Gas Kettles:Open-burner configurations retain cost advantage in regions with subsidized natural gas pricing and established ventilation infrastructure.
- Manual Braising Pans:Operator-dependent tilt-skillet designs persist in small-scale catering operations with limited capital budgets.
Today's leader: Steam-Jacketed Kettles. Tomorrow's challenger: Automated Braising Pans.
Heating Technology:
Margin structures diverge sharply between legacy thermal systems and precision induction architectures.
- Induction:Electromagnetic field generation delivers sub-minute temperature recovery without open-flame ventilation requirements. Singapore and Tokyo hotel chains specify induction braising pans for below-grade kitchen fit-outs where gas infrastructure costs prove prohibitive. German commercial kitchen efficiency mandates accelerate displacement of conventional gas systems.
- Steam Jacketed:External boiler-fed steam circulation enables precise temperature control for delicate sauce preparations and dairy applications. Mature foodservice markets in France and Switzerland maintain substantial installed bases where energy recovery systems justify replacement investment. Boiler dependency limits penetration in aged institutional facilities lacking steam infrastructure.
- Direct Flame:Open gas burner configurations dominate cost-sensitive segments with established ventilation infrastructure.
- Electric Resistance:Calrod-style heating elements serve urban hospitality construction projects facing gas connection delays.
- Radiant:Infrared surface heating addresses specialized applications requiring rapid thermal response.
- Convection:Forced-air thermal circulation appears in hybrid braising pan designs targeting uniform product finish.
Induction systems gain share fastest in premium urban hospitality specification. Steam-jacketed architectures defend position in institutional volume cooking.
Application:
Customer type determines service network requirements and aftermarket revenue potential.
- Institutional Kitchens:Hospital, university, and correctional foodservice operations demand NSF International-certified equipment with documented sanitation compliance. US and Canadian healthcare systems increasingly favor equipment-as-a-service contracting to reduce capital budget volatility. Predictive maintenance capabilities reduce downtime costs across distributed central kitchen networks.
- Hospitality Venues:Hotel and resort kitchen operations prioritize thermal consistency and aesthetic integration with front-of-house visibility requirements. Southeast Asian hotel chains accelerate central kitchen standardization, concentrating procurement volume in Vietnamese manufacturing clusters. Induction systems penetrate below-grade installations where ventilation constraints apply.
- Foodservice Establishments:Independent restaurants and small chains balance equipment versatility against footprint constraints.
- Catering Services:Mobile and off-premise operators value tilt-skillet portability and rapid heat recovery for field deployment.
- Food Processing Units:Industrial-scale batch cooking operations specify heavy-duty configurations with extended duty cycles.
Institutional Kitchens anchor current revenue concentration. Hospitality Venues present the steepest expansion trajectory as Southeast Asian hotel development accelerates.
End User Industry:
Maturity gradients separate established procurement channels from emerging specification opportunities.
- Hotels:Chain operators standardize equipment specifications across central kitchen networks to ensure menu consistency and simplify technician training. Vietnam manufacturing clusters attract regional procurement concentration as multinational operators consolidate supplier relationships. Cloud-connected fleet management enables remote diagnostics across distributed properties.
- Catering Companies:Event and institutional catering operators demand equipment durability under variable load conditions and transport stress.
- Restaurants:Independent and small-chain operators prioritize equipment versatility and rapid payback periods.
- Event Management:Temporary kitchen installations require portable configurations with simplified utility connections.
- Culinary Schools:Training institutions specify transparent thermal systems that demonstrate cooking principles to students.
Hotels dominate capital deployment. Catering Companies represent the most price-elastic demand segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial kettle and braising pan industry traces its modern origins to post-war European foodservice equipment manufacturing, with German and Swiss fabricators pioneering steam-jacketed vessel designs for institutional kitchens. Today's market distributes manufacturing and procurement across distinct national clusters shaped by regulatory regimes and infrastructure legacies.
United States
Hospital and university kitchen renovations drive replacement demand for NSF International-certified steam-jacketed kettles. The FDA's Food Code provisions and OSHA workplace safety standards govern equipment specification in institutional foodservice. Illinois-based manufacturing anchors North American supply relationships with large-scale operators.
Germany
Commercial kitchen efficiency mandates accelerate displacement of conventional gas braising pans toward induction systems. The EU F-Gas Regulation constrains thermal system chemistries in imported equipment categories. Bavarian fabricators lead precision engineering for high-efficiency steam-jacketed architectures serving Central European institutional markets.
France
Energy recovery system improvements justify replacement investment in hospital and university kitchen renovations. CE marking requirements under EU machinery directives shape equipment access protocols. Lyon and Paris metropolitan clusters concentrate demand for programmable braising systems in hospitality and healthcare sectors.
Vietnam
Regional foodservice procurement concentrates in Vietnamese manufacturing hubs serving Southeast Asian hotel chains. Central kitchen standardization by multinational operators drives volume commitments for steam-jacketed and electric kettle specifications. Ho Chi Minh City industrial zones attract component sourcing for regional export markets.
Japan
Hotel chains in Tokyo specify induction braising pans for below-grade kitchen fit-outs where gas infrastructure costs prove prohibitive. METI energy efficiency guidelines influence thermal system selection in new commercial construction. Osaka-Kobe manufacturing maintains specialized capabilities for precision vessel fabrication.
Commercial Kettles and Braising Pans Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive component supply and broad foodservice equipment portfolios. Consolidation pressure concentrates around manufacturers with multi-brand architectures spanning price tiers and regional service networks. Three archetypes dominate: diversified industrial holding companies with cross-sector component leverage, specialized foodservice equipment groups with manufacturing scale advantages, and regional fabricators serving price-sensitive emerging markets. Dominant competitive moves include portfolio diversification through brand acquisition and geographic expansion via regional manufacturing clusters.
Within the diversified industrial tier, Illinois Tool Works and Dover Corporation anchor supply relationships through component portfolio breadth. Ali Group exemplifies multi-brand architecture spanning premium through economy positioning across regional markets. Middleby Corporation occupies a scale-driven position across commercial cooking equipment categories.
| Leading Market Players |
|---|
| Illinois Tool Works |
| AB Electrolux |
| Ali Group |
| Öztiryakiler |
| RATIONAL Group |
| Middleby Corporation |
| Dover Corporation |
| Nilma |
| Welbilt Inc |
| Others |
Cost & Logistics Intelligence
Grade 304 and 316 stainless steel sheet stock volatility cascades through equipment fabricator margins into downstream pricing tiers, compressing standard-configuration quotations while premium programmable systems absorb cost pass-through via HACCP logging and cloud connectivity bundles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NSF International-certified programmable braising pans with IoT diagnostics from basic electric kettles and manual tilt-skillets. Price differentiation hinges on certification grade and after-sales service bundling, with correctional facilities and aged care operators exhibiting highest price sensitivity due to capital budget constraints. Pricing pressure stems from raw material input volatility, particularly stainless steel sheet exposure, while urban hospitality venues constrained by gas infrastructure limitations show lowest price elasticity for induction systems.
Supply Chain Analysis
Dual-sourcing requirements from multinational hotel chains and healthcare systems mandate multi-supplier qualification across Vietnamese manufacturing clusters, German precision fabricators, and US-based NSF-certified production facilities. Raw material dependencies center on Grade 304/316 stainless steel from South Korean and Chinese mills, induction coil assemblies from Japanese suppliers, and programmable control modules from Taiwanese electronics manufacturers. Supply chain risk concentrates in tariff exposure on Chinese steel inputs. Distribution runs through regional foodservice equipment distributors with certified technician networks for aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NSF International certification tightening in North America and EU F-Gas Regulation phase-down schedules in Europe mechanically generate replacement demand regardless of macroeconomic conditions.
For Market Incumbents: Deepen backward integration into stainless steel component forging to defend margin position against raw material volatility. Anchor supply relationships with large-scale foodservice operators through captive aftermarket service networks, while accelerating induction system R&D to preempt regulatory displacement of gas-fired architectures.
For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for induction braising pan specialization targeting below-grade hotel kitchen retrofits. White-space concentrates in automated braising pan specification for US correctional facilities and aged care operators where labor substitution justifies premium positioning. Go-to-market through equipment-as-a-service contracting aligns with public sector accounting requirements in North American healthcare systems.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-brand architectures span premium through economy positioning with regional service network density. Long-term viability favors diversified industrial conglomerates with captive component supply and cloud-connected fleet management capabilities. Acquisition target archetype: precision fabricators with CE marking and NSF International dual certification. Signal to watch: hospital system procurement committee shifts toward outcome-verified performance specifications rather than rated capacity alone.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Forging | Captive supply of Grade 304/316 components insulates margin stability from commodity volatility. |
| Induction Heating Technology Transition | German commercial kitchen efficiency mandates and EU F-Gas Regulation accelerate displacement of gas systems. |
| Cloud-Connected Fleet Management Platform | IoT-enabled predictive maintenance reduces downtime costs across distributed central kitchen networks. |
| Equipment-as-a-Service Contracting Model | Operating lease structures align with public sector accounting requirements in US and Canadian healthcare. |
| Dual Certification Investment (NSF/CE) | Concurrent North American and European market access streamlines product launch windows. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice equipment procurement directors, central kitchen operations managers, NSF International certification engineers, and aftermarket service technicians with secondary validation against SEC filings, customs trade data, and EU machinery directive compliance databases. Bottom-up equipment shipment tracking and top-down foodservice construction spending analysis provided triangulation anchors.
Comparable-period anchoring tied projection assumptions to historical replacement cycle patterns across institutional kitchen renovations and hospitality construction permits. Segmentation modeling spanned thermal system architecture, operational scale tier, application type, and regional regulatory cluster. CAGRs derived from unit economics analysis incorporating energy efficiency mandate compliance costs and labor substitution value propositions. Industry-specific inputs included stainless steel price index movements and hotel chain central kitchen standardization timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt stainless steel tariff escalations or accelerated EU F-Gas Regulation enforcement. Deviation in NSF International certification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Electric Kebab Machine Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Food Automation Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Vee Bee Consistometer Market