
 Europe Aqua Feed Market | 2026-2036
Europe Aqua Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aqua Feed Market Foresight
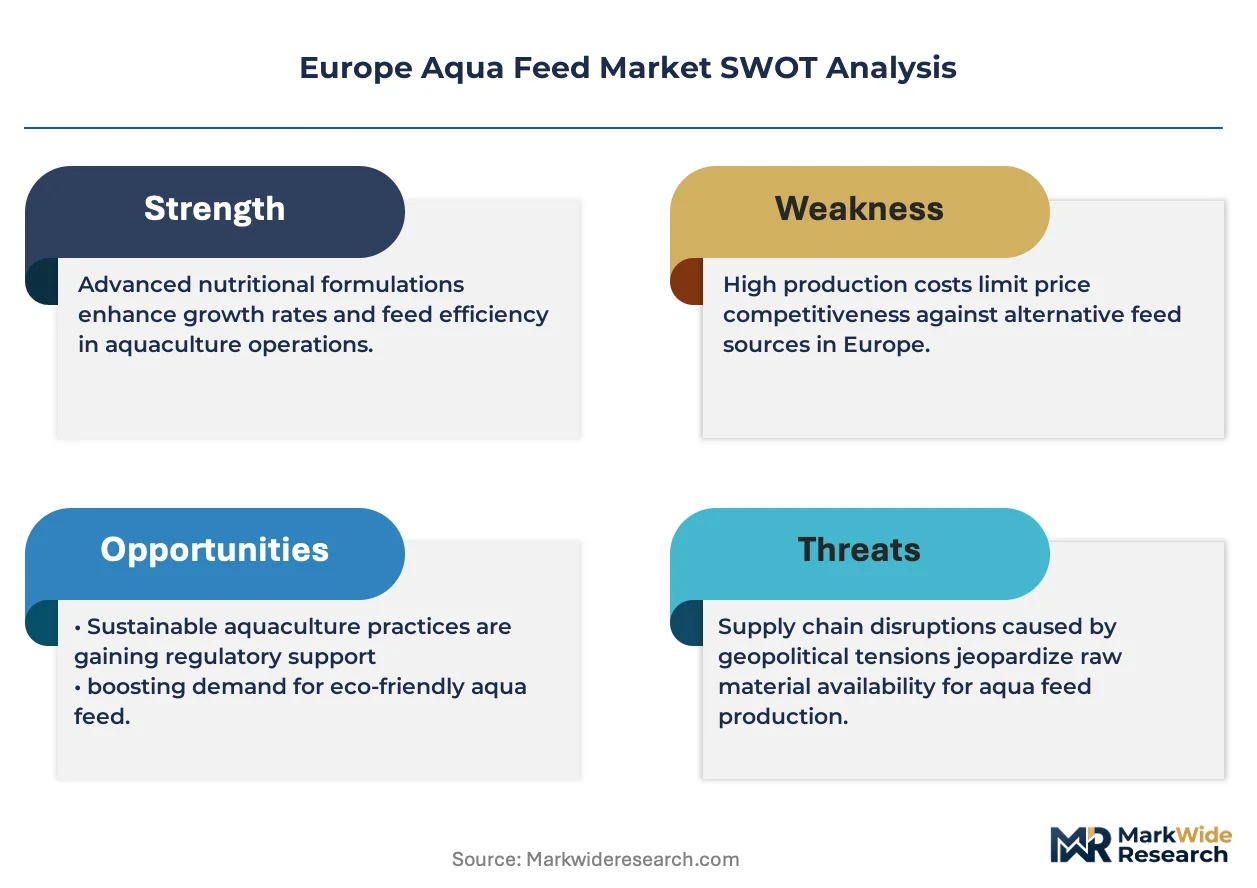
Recirculating aquaculture system deployment is expanding across European salmon and trout operations. Nutreco N.V. leverages its Skretting brand to dominate Atlantic salmon nutrition across Norway and Scotland. BioMar Group anchors its position through specialized feeds for Mediterranean sea bass and sea bream farmers. Cargill competes via its EWOS division, sustaining supply chain control across Nordic coastal zones.
Aqua feed denotes formulated nutritional products combining fishmeal, plant proteins, vitamins, and minerals into extruded pellets or extruded slow-sinking feeds with protein contents typically ranging from 35% to 55% depending on species life stage, designed to optimize growth rates and feed conversion ratios in intensive fish farming. Salmon Feed leads product type revenue as Norwegian and Scottish producers scale offshore cage operations, while Shrimp Feed represents the fastest-expanding category driven by Mediterranean hatchery investments. Ingredient Type margin pools concentrate in Protein Sources, where insect meal and single-cell protein suppliers are displacing traditional fishmeal inclusion rates.
The EU Green Deal and F-Gas Regulation shape feed manufacturing by mandating reduced carbon intensity in supply chains and restricting synthetic additive categories. EMA and EFSA frameworks govern veterinary medicinal feed additives and novel ingredient safety assessments across member states. REACH compliance requirements constrain chemical preservative use, pushing manufacturers toward natural antioxidant formulations. Stakeholders must monitor how the EU AI Act and impending CSRD disclosure rules will reshape feed provenance tracking and environmental reporting obligations.
Market Dynamics
The EU Green Deal's sustainability mandates are restructuring European aqua feed formulations, forcing manufacturers to reduce marine ingredient inclusion rates while maintaining protein density targets for intensive salmon and trout operations.
Growth Catalysts
- Recirculating aquaculture systems:Norwegian and Scottish producers are deploying land-based RAS facilities that require specialized slow-sinking feed formulations with precise nutrient delivery profiles.
- F-Gas Regulation:Restrictions on synthetic refrigerants in processing facilities are accelerating investment in alternative preservation technologies for feed ingredient storage across Nordic coastal zones.
- Single-cell protein inclusion:Fermentation-derived microbial biomass is achieving commercial scale in Danish and Dutch manufacturing plants, displacing conventional fishmeal in high-performance salmon rations.
Market Restraints
- Marine ingredient price volatility:Peruvian anchovy quota fluctuations transmit directly into European fishmeal costs, compressing formulation margins for Atlantic salmon feed producers.
- Protein source concentration:Insect meal supply remains concentrated in Dutch and French production clusters, creating bottleneck risk for manufacturers pursuing EU Green Deal compliance timelines.
- REACH chemical restrictions:ECHA's expanding substance authorization requirements are eliminating synthetic antioxidant options before natural alternatives achieve cost parity at commercial volumes.
Strategic Opportunities
- Mediterranean hatchery expansion:Greek and Turkish sea bass and sea bream producers are modernizing nursery facilities, creating demand for specialized starter feeds with enhanced digestibility profiles.
- CSRD disclosure alignment:The EU's Corporate Sustainability Reporting Directive is creating first-mover advantage for feed manufacturers with verified supply chain carbon accounting systems.
- Precision feeding technology:Underwater camera systems and AI-driven appetite detection are converging with feed delivery mechanisms, enabling Norwegian farmers to optimize conversion ratios.
Industry Challenges
- Novel ingredient approval timelines:EFSA's safety assessment protocols for insect meal and single-cell protein variants extend 18-24 months, delaying product launches against sustainability targets.
- Formulation expertise scarcity:The specialized knowledge required to balance amino acid profiles in reduced-fishmeal diets is concentrated among retiring nutritionists in Norwegian research institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aqua Feed Market |
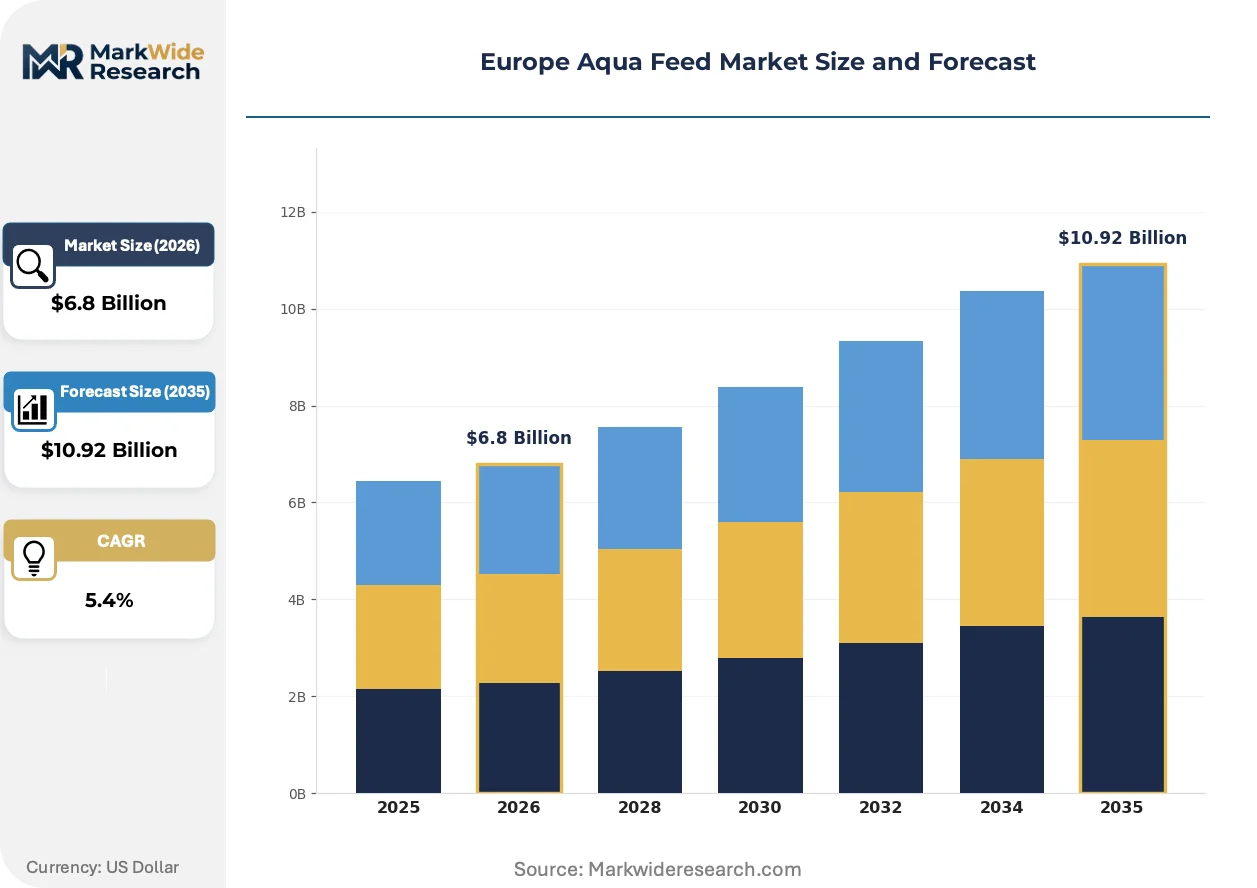
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salmon Feed, Shrimp Feed, Trout Feed, Carp Feed Ingredient Type: Antioxidants, Protein Sources, Vitamins, Minerals Distribution Channel: Direct Sales, Retail, Distributors, E-Commerce End User: Aquaculture Farms, Research Institutions, Feed Manufacturers, Others |
| Companies Covered | Norel Animal Nutrition, Ridley Corporation Limited, Nutreco N.V., Cargill, Nutriad, Aller Aqua, Dibaq Acuicultura, Avanti Feeds, BioMar Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aqua Feed Market Shifts & Advancements
Reformulation pressures are accelerating ingredient diversification across European aqua feed manufacturing, with sustainability verification becoming a competitive differentiator rather than a compliance checkbox.
Single-cell protein derived from methanotrophic bacteria is converging with traditional extrusion processes in commercial salmon feed production. Dutch biotechnology suppliers are scaling fermentation capacity to serve Norwegian and Scottish aquaculture operations. This convergence is compressing the cost premium between novel and conventional protein sources, enabling broader adoption ahead of regulatory deadlines.
CSRD mandates are reshaping environmental disclosure requirements for feed manufacturers operating across EU member states. The directive's scope 3 emissions tracking obligations are forcing upstream supply chain audits for marine ingredient sourcing. Mediterranean sea bass and sea bream producers are responding by demanding verified provenance documentation from their feed suppliers.
Buyer concentration among Norwegian salmon farming conglomerates is consolidating procurement decisions into centralized technical committees. Independent regional feed distributors are losing direct account relationships as volume contracts migrate to manufacturer-direct structures. This shift is most visible in the Trøndelag and Vestland production corridors, where three integrated farming groups control the majority of Atlantic salmon feed offtake.
Europe Aqua Feed Market Segmentation
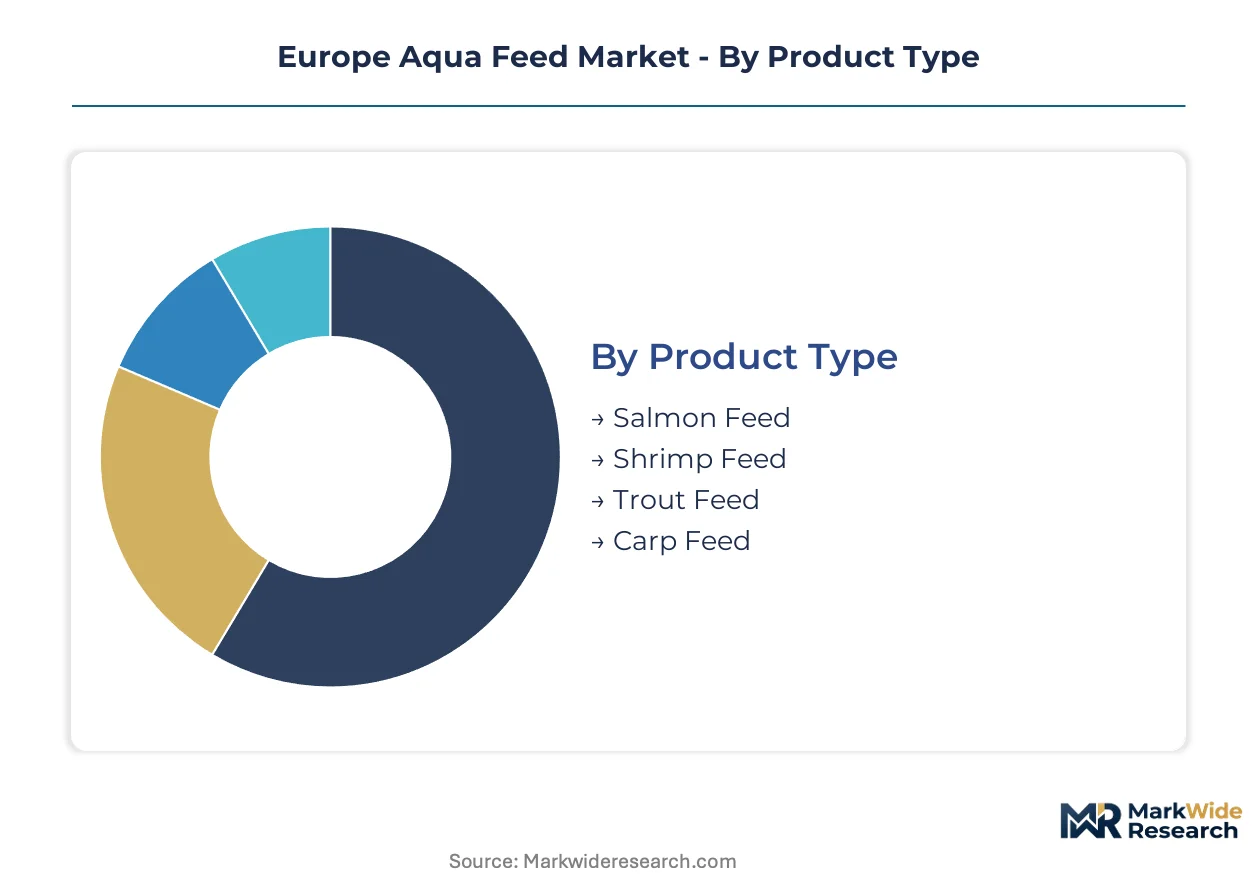
Segmentation in European aqua feed reflects divergent protein density requirements across species life stages and the regulatory pressure driving ingredient substitution. Buyers prioritize formulation precision for intensive salmon operations while sustainability mandates reshape procurement criteria for all categories.
Product Type:
Species-specific nutritional density requirements determine feed selection, with protein content and sinking characteristics varying by farming intensity and water temperature.
- Salmon Feed:Extruded pellets containing 45-55% protein optimize growth rates in Norwegian and Scottish offshore cage operations. Atlantic salmon farmers in Trøndelag and Vestland corridors drive volume concentration as integrated groups consolidate procurement through direct manufacturer contracts.
- Shrimp Feed:Slow-sinking formulations with enhanced digestibility profiles serve Mediterranean hatchery expansion. Greek and Turkish producers modernizing nursery facilities are expanding specialized starter feed offtake most quickly among all product categories.
- Trout Feed:Lower protein rations (35-42%) accommodate freshwater RAS deployment across Danish and German land-based facilities.
- Carp Feed:Cost-optimized plant-heavy formulations dominate Central European pond aquaculture in Poland and Hungary.
Salmon Feed leads on scale; Shrimp Feed leads on momentum.
Ingredient Type:
Margin pools concentrate where novel protein sources displace conventional marine inputs under EU Green Deal compliance timelines.
- Protein Sources:Fishmeal, insect meal, and single-cell protein from Danish fermentation plants comprise the primary cost driver in formulation. EFSA approval bottlenecks for novel variants constrain supply scaling despite sustainability mandates.
- Antioxidants:Natural tocopherol formulations are displacing synthetic BHT and ethoxyquin as REACH authorization requirements eliminate chemical preservatives. Dutch suppliers dominate natural antioxidant production clusters.
- Vitamins:Premix stability in extrusion processes determines inclusion rates across all species formulations.
- Minerals:Bioavailable trace element chelates support immune function in high-density Norwegian salmon operations.
Protein Sources command formulation economics; Antioxidants face the steepest substitution pressure.
Distribution Channel:
Channel selection tracks farm scale and technical service requirements, with volume concentration favoring direct relationships.
- Direct Sales:Manufacturer-to-farm contracts dominate Norwegian salmon feed procurement, eliminating distributor margins for integrated farming groups. Skretting and BioMar field technical teams co-develop rations with major producers.
- Distributors:Independent regional networks retain relevance for Mediterranean sea bass and sea bream farmers requiring smaller batch flexibility.
- Retail:Packaged feeds for hobby aquaculture and ornamental fish serve fragmented demand across German and French consumer markets.
- E-Commerce:Digital procurement platforms are emerging for specialty ingredients and smaller volume orders in research applications.
Direct Sales capture volume concentration; E-Commerce shows the steepest expansion trajectory.
End User:
User type determines service intensity, with commercial farms demanding formulation customization versus standardized rations for research and manufacturing resale.
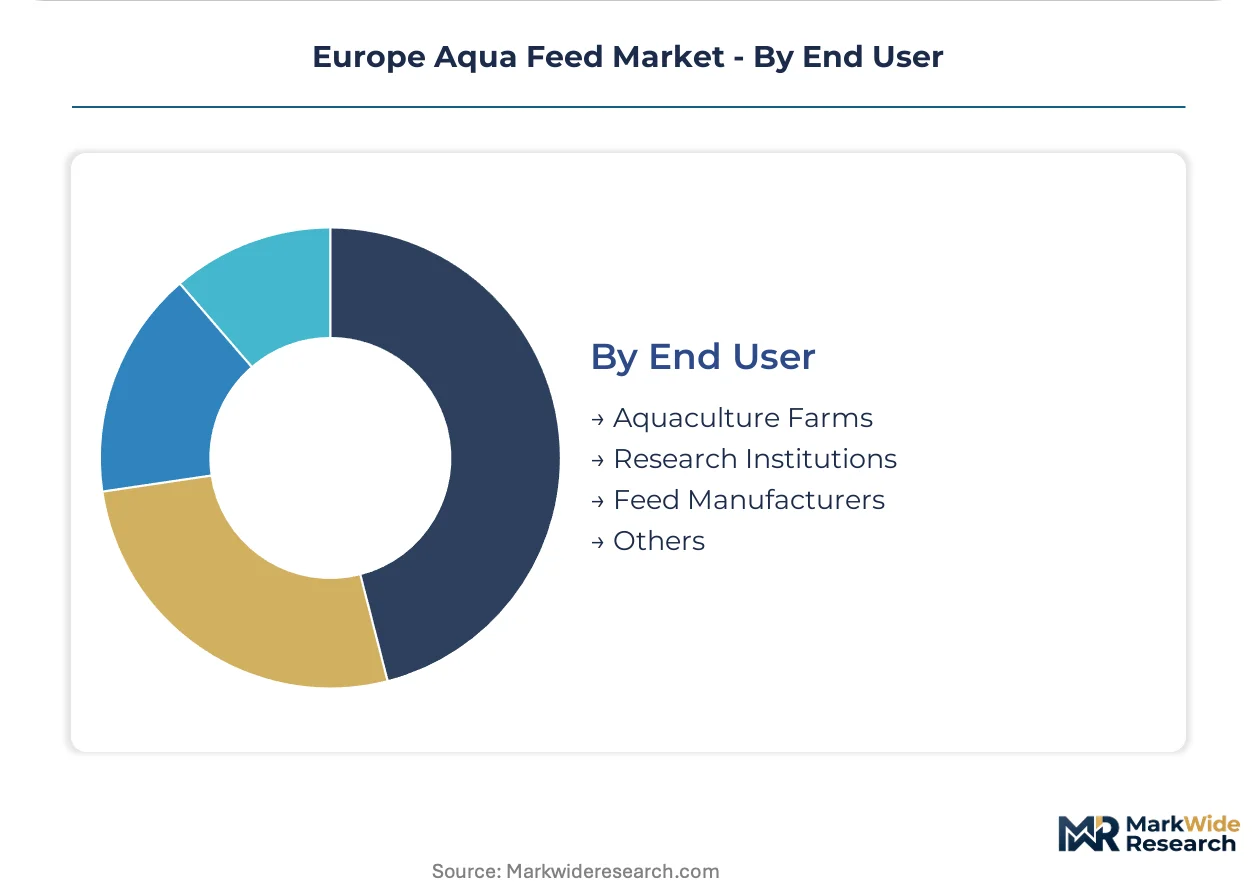
- Aquaculture Farms:Intensive salmon and trout producers in Norway, Scotland, and Denmark specify protein profiles, pellet durability, and sinking rates. CSRD disclosure requirements are forcing supply chain carbon accounting integration into procurement decisions.
- Feed Manufacturers:Compounders purchasing premixes and base materials for regional blending operations concentrate in Poland and Spain.
- Research Institutions:Universities and aquaculture research centers in Wageningen and Tromsø trial novel ingredients under controlled conditions.
- Others:Ornamental fish breeders and public aquariums generate specialized small-batch demand.
Aquaculture Farms dominate absolute consumption; Feed Manufacturers face margin compression from upstream integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping European aqua feed production as manufacturers relocate formulation activities toward jurisdictions with streamlined EFSA novel-ingredient approval pathways and lower carbon-accounting compliance costs. The EU Green Deal's scope 3 emissions tracking creates divergent cost structures across member states.
Norway
Atlantic salmon farming in Trøndelag and Vestland corridors drives specialized high-protein feed consumption. The Norwegian Food Safety Authority enforces strict veterinary medicinal feed additive controls under EMA-aligned frameworks. Bergen and Stavanger host technical service clusters where manufacturers co-develop rations with integrated farming groups.
Scotland
Offshore cage expansion in the Shetland Islands and western Highlands sustains demand for extruded pellet formulations. UK REACH implementation post-Brexit maintains chemical preservative restrictions equivalent to EU standards. Oban and Fort William serve as distribution hubs for salmon feed logistics across coastal zones.
Denmark
Land-based RAS facilities for rainbow trout in Jutland require slow-sinking feed with precise nutrient delivery. Danish environmental permits mandate nitrogen discharge limits that shape feed digestibility specifications. Aarhus and Odense anchor fermentation-derived single-cell protein production clusters serving Nordic aquaculture.
Greece
Mediterranean sea bass and sea bream hatchery modernization in the Peloponnese and Epirus regions expands specialized starter feed offtake. National aquaculture development programs co-fund nursery facility upgrades. Preveza and Igoumenitsa concentrate marine ingredient processing and feed distribution for Hellenic producers.
Netherlands
Insect meal and natural antioxidant production clusters in Noord-Brabant and Gelderland supply reformulated salmon rations. Dutch environmental regulations on circular agriculture incentivize alternative protein R&D. Wageningen hosts research institutions trialing novel ingredients under controlled conditions.
Europe Aqua Feed Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated nutrition companies commanding salmon feed procurement through direct technical relationships while regional compounders retain Mediterranean sea bass and sea bream accounts. The structure concentrates around three strategic archetypes: multinational feed nutrition platforms with species-specific formulation expertise, fermentation biotechnology suppliers scaling novel protein alternatives, and regional distributors serving fragmented hatchery demand. Dominant competitive moves include backward integration into single-cell protein production and strategic partnerships with precision-feeding technology providers.
Among multinational nutrition platforms, Nutreco N.V. and BioMar Group exemplify the species-specialist archetype through their respective Skretting and BioMar branded operations. Cargill occupies a position as the diversified agricultural conglomerate with aqua feed capabilities through its EWOS division. These three entities anchor the competitive set referenced in the analysis.
| Leading Market Players |
|---|
| Norel Animal Nutrition |
| Ridley Corporation Limited |
| Nutreco N.V. |
| Cargill |
| Nutriad |
| Aller Aqua |
| Dibaq Acuicultura |
| Avanti Feeds |
| BioMar Group |
| Others |
Supply & Pricing Matrix
Fishmeal procurement costs cascade through three distinct pricing tiers as Peruvian anchovy quota volatility compresses margins at the formulation stage and concentrates negotiating leverage among Norwegian integrated farming groups.
Pricing Analysis
Distributor margins have collapsed in Norwegian salmon feed procurement as manufacturer-direct contracts displace regional intermediaries. Pricing stratifies across premium, standard, and economy tiers based on protein density certification and volume scale, with integrated farming groups capturing standard-tier discounts through centralized technical committees. Cost compression in the economy tier is intensifying because Dutch insect meal suppliers have not achieved cost parity with conventional fishmeal. Mediterranean sea bass and sea bream farmers exhibit the highest price sensitivity due to fragmented hatchery scale, while Norwegian Atlantic salmon producers prioritize formulation precision over unit cost.
Supply Chain Analysis
REACH certification requirements for novel ingredients gate supply chain participation before EFSA safety assessments conclude. Raw material sourcing draws from Peru for fishmeal, the Netherlands for insect meal, and Denmark for single-cell protein fermentation output. Soy protein concentrate and fish oil constitute secondary input dependencies. Single-source vulnerability concentrates in Peruvian anchovy fisheries where quota fluctuations transmit directly into European formulation costs. Distribution runs through coastal manufacturing plants in Norway, Scotland, and Greece serving adjacent farming zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European aqua feed manufacturing functions as a geographic-arbitrage play where EFSA novel-ingredient approval timelines in the Netherlands outpace Mediterranean jurisdictions, lowering compliance costs for fermentation biotechnology suppliers.
For Market Incumbents: Extend technical service capabilities into precision-feeding technology partnerships before Norwegian farming groups consolidate procurement decisions entirely. Backward integration into single-cell protein production secures supply against Dutch fermentation capacity constraints. EMA veterinary medicinal feed additive restrictions threaten formulation flexibility; captive R&D investment in natural antioxidant alternatives offsets REACH-driven synthetic elimination. For New Entrants and Emerging Players: Specialized distributors serving Greek and Turkish sea bass hatcheries represent the most penetrable channel partner type for regional market entry. Mediterranean starter feed demand outpaces supply as nursery modernization accelerates. A co-development model with Wageningen research institutions accelerates EFSA approval navigation for novel protein variants. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation expertise scarcity intersects with retiring Norwegian nutritionist cohorts. The five-to-ten year viability window favors acquisition of mid-scale compounders with established EFSA submission track records. Watch for CSRD disclosure deadline acceleration as the inflection signal triggering manufacturer valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Single-Cell Protein | Danish fermentation capacity expansion secures novel protein supply against fishmeal price volatility. |
| Precision-Feeding Technology Partnership | Underwater camera integration with Norwegian salmon farms optimizes feed conversion ratios. |
| CSRD-Aligned Carbon Accounting System | Verified supply chain tracking meets EU Green Deal scope 3 emissions disclosure mandates. |
| EFSA Novel Ingredient Submission Acceleration | Streamlined safety assessment pathways compress 18-24 month approval timelines for insect meal variants. |
| Mediterranean Hatchery Technical Service Expansion | Greek and Turkish nursery facility co-development captures fastest-expanding shrimp feed demand segment. |
Research Methodology
Coverage spans Norway, Scotland, Denmark, Greece, and the Netherlands, with primary inputs from each jurisdiction combining executive interviews with feed formulation directors, procurement leads at integrated salmon farming groups, EFSA regulatory affairs specialists, and fermentation biotechnology R&D heads. Secondary validation draws from EU customs trade databases, ECHA substance authorization registers, SEC filings of listed nutrition platforms, and national aquaculture production statistics. Bottom-up volume modeling triangulates against top-down industry association aggregates.
Granularity-level modeling disaggregates revenue and volume across product type, ingredient category, distribution channel, and end-user segments, with additional dimensional depth applied to species life-stage protein density requirements and regulatory compliance tier. CAGRs derive from multivariate regression against historical production data and projected farming intensity expansion throughout the forecast period. Input assumptions incorporate EFSA approval pipeline velocity, Peruvian anchovy quota schedules, and CSRD implementation phase-in timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement intensity and novel protein cost convergence trajectories. Model outputs reflect documented assumptions regarding regulatory timeline adherence and marine ingredient substitution rates. A model refresh is warranted upon material change in EFSA staffing capacity or Peruvian fisheries management policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
North America Shrimp Market
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
South America Aqua Feed Market
Aquaculture Innovations
Norway Aquaculture Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
China Aquafeed Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Smart Aquaculture Systems Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Seaweed Cultivation Market