
 Baby Personal Care Market | 2026-2036
Baby Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Personal Care Market Intelligence
Demand from Millennial and Gen Z parents seeking ingredient transparency is bifurcating the market away from legacy, price-focused consumers. Kenvue Inc. leverages its scientific research heritage to build trust with this discerning demographic. Mustela specializes in plant-based formulations, securing a premium position for newborn care. Procter & Gamble competes through a broad portfolio that addresses diverse consumer needs across multiple channels.
Baby personal care comprises topical formulations specifically developed for the sensitive skin of infants and young children. These products are formulated to be pH-balanced and often exclude known irritants to cleanse, moisturize, and protect delicate skin. The ingredient type segment shows a decisive shift toward natural and organic formulations, which command premium pricing. While wipes represent a high-volume category, higher margins are found in specialized diaper creams and lotions.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Union's Cosmetic Products Regulation establish stringent safety and labeling requirements. China's National Medical Products Administration (NMPA) adds another layer of complexity with its own distinct registration and testing protocols. Navigating these varied international standards while ensuring a transparent supply chain for natural ingredients is the central challenge for manufacturers.
Market Dynamics
The central tension shaping the baby personal care market is the bifurcation of demand between price-sensitive consumers and a growing cohort of ingredient-focused parents, a dynamic amplified by stringent international safety regulations from multiple jurisdictions.
Growth Catalysts
- Premiumization in China:A rapidly expanding middle class in China is increasing expenditure on premium and specialized baby care products, prioritizing perceived safety and quality over price, which attracts investment in the region.
- Demand for Natural Formulations:The parental preference for products with natural and organic ingredients, often verified by third-party certifications, supports premium pricing and creates opportunities for specialized brands focused on clean-label formulations.
- Toddler-Specific Products:Product development is expanding beyond infants to address the needs of toddlers, a segment with distinct requirements that allows for new product categories and higher value propositions.
Market Restraints
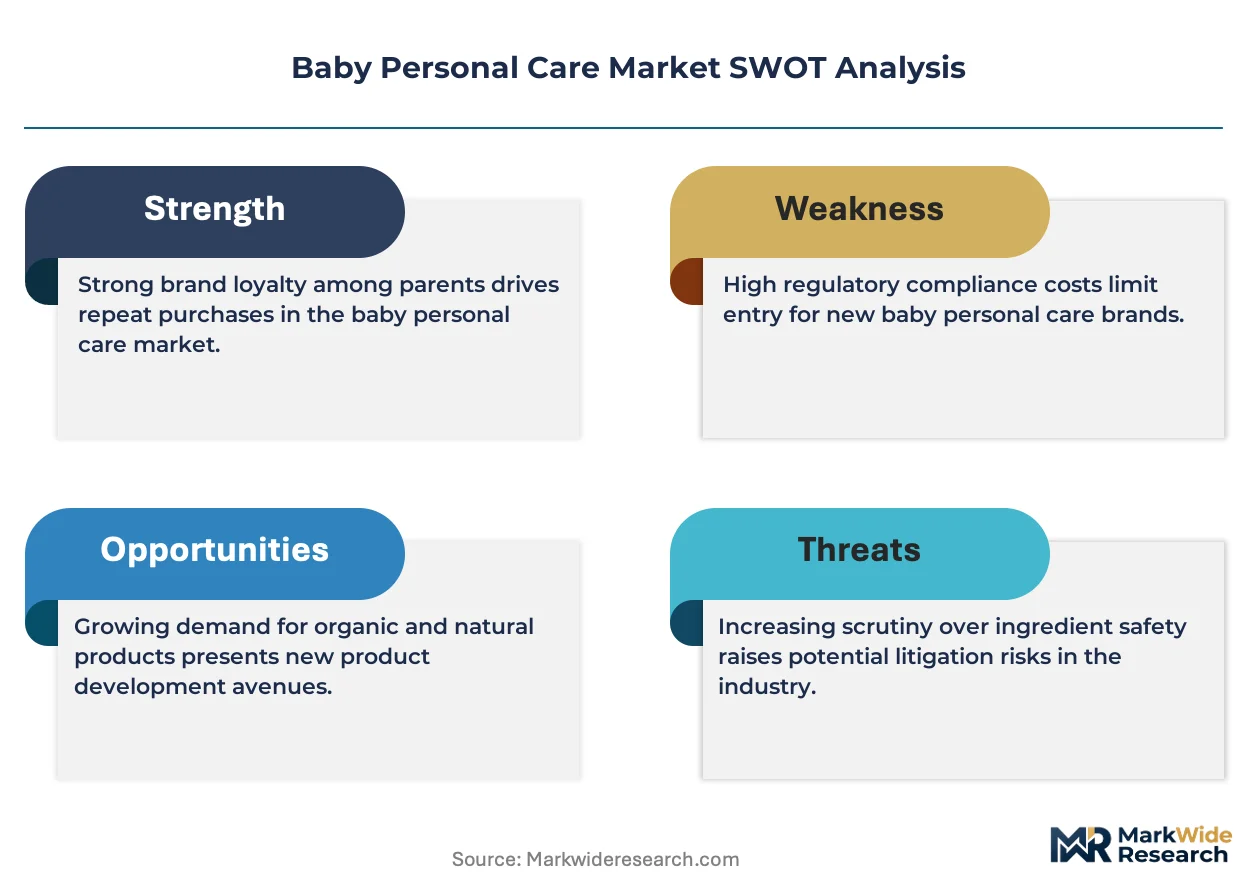
- Regulatory Fragmentation:The need to comply with divergent and complex regulatory frameworks, such as the EU's Cosmetic Products Regulation and China's NMPA protocols, increases R&D costs and time-to-market for new products.
- Input Cost Volatility:The prices for high-demand natural and organic raw materials, including specific botanical extracts and plant-based oils, are subject to supply fluctuations, which can compress manufacturer margins unexpectedly.
- Price Sensitivity in Mass Channels:In hypermarkets and drugstores, intense competition from private-label and economy brands establishes a ceiling on pricing for basic items like wipes, limiting overall margin potential.
Strategic Opportunities
- Geographic Expansion:Markets in Southeast Asia and Latin America present significant white space, characterized by high birth rates and rising disposable incomes, creating new consumer bases for established and emerging brands.
- Therapeutic Formulations:There is an unmet need for clinically-validated products targeting specific infant skin conditions like eczema or extreme sensitivity, opening a pathway for quasi-pharmaceutical product lines with high margins.
- Direct-to-Consumer Channels:Building direct-to-consumer (DTC) e-commerce platforms enables brands to control their narrative, cultivate direct relationships with parents, and capture retail margins previously lost to intermediaries.
Industry Challenges
- Supply Chain Transparency:Establishing and verifying a fully transparent and ethical supply chain for natural ingredients is a significant operational hurdle, requiring substantial investment in traceability systems and supplier audits.
- Complex Compliance Pathways:The lengthy and resource-intensive process of obtaining safety certifications and navigating registration requirements, particularly for market entry into China, acts as a barrier for smaller companies.
- Scientific Communication:Translating complex ingredient science and safety data into clear, trustworthy consumer-facing communication without oversimplifying or making unsubstantiated marketing claims is a persistent challenge for brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Personal Care Market |
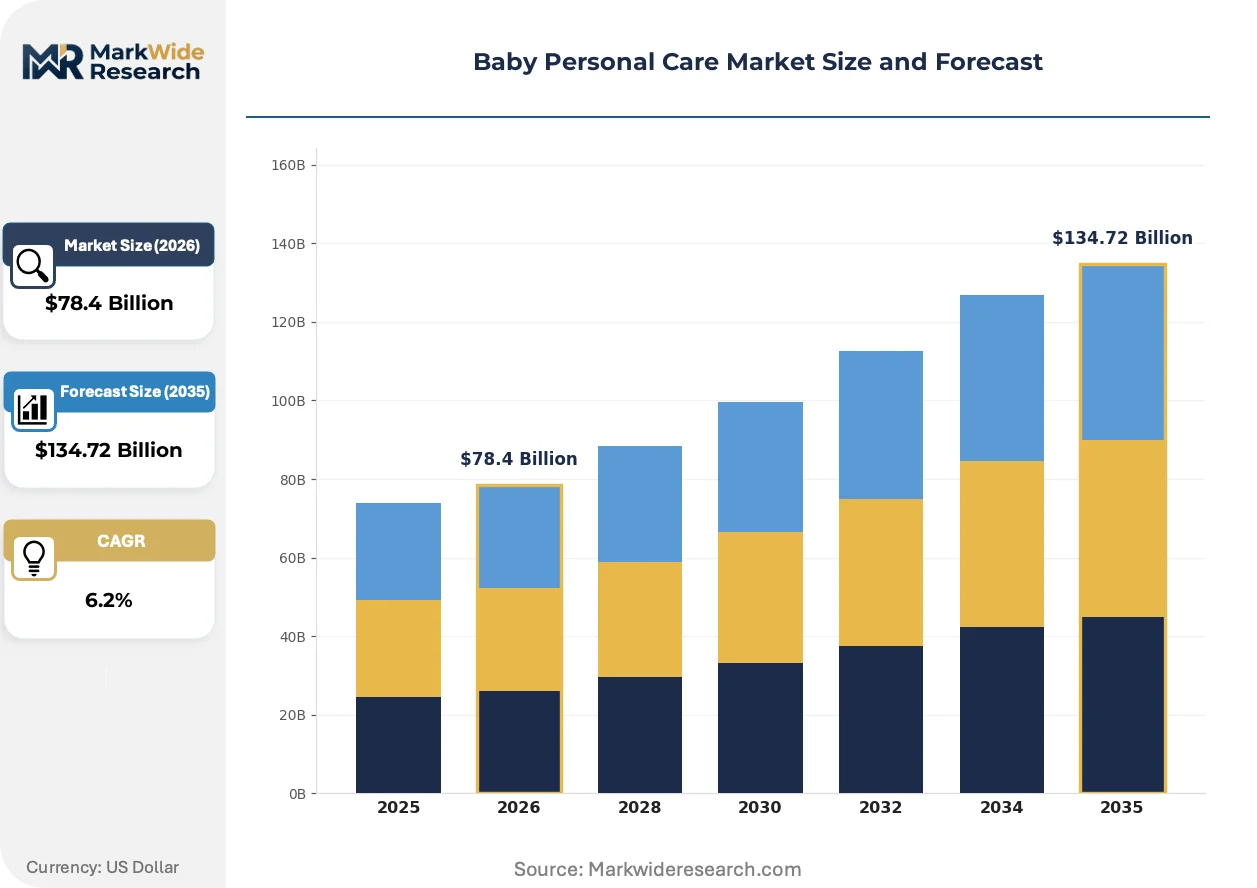
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Lotions, Diaper Creams, Wipes Ingredient Type: Natural, Organic, Hypoallergenic, Chemical-Based Age Group: Newborns, Infants, Toddlers, Preschoolers Packaging Type: Tubes, Bottles, Jars, Pouches |
| Companies Covered | Unilever, Beiersdorf AG, Procter & Gamble, Kenvue Inc., Unicharm Corporation, Kimberly-Clark Corporation, Kao Corporation, Mustela, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Personal Care Market Strategic Shifts & Innovations
Scientific validation of natural ingredients is reshaping product development. The market is pivoting from a simple focus on mildness and avoiding negatives to actively incorporating bioactive, plant-derived compounds that offer demonstrable benefits for infant skin health.
Microbiome-friendly formulations that utilize prebiotics and postbiotics are designed to support the natural balance of an infant's developing skin barrier. Educated parents in North America and Europe are actively seeking out these scientifically advanced products. This focus on skin-biome health is fragmenting the traditional market, creating a new tier of specialized, science-led solutions.
The European Union's Cosmetic Products Regulation establishes some of the world's most stringent safety and labeling requirements. This legislation is forcing manufacturers to conduct exhaustive safety assessments and provide detailed ingredient information for every product sold. The skin protectant category, including diaper creams, is particularly impacted, prompting reformulations to meet strict EU criteria for ingredients like zinc oxide.
Subscription-based purchasing models are achieving significant adoption for consumable products like baby wipes, lotions, and diaper creams. This behavioral shift disrupts traditional brick-and-mortar retail, pulling volume from supermarkets into direct-to-consumer (DTC) and specialized e-commerce channels. This trend is most advanced in the United States and China, where digital-first brands leverage convenience to build customer loyalty.
Baby Personal Care Market Segmentation
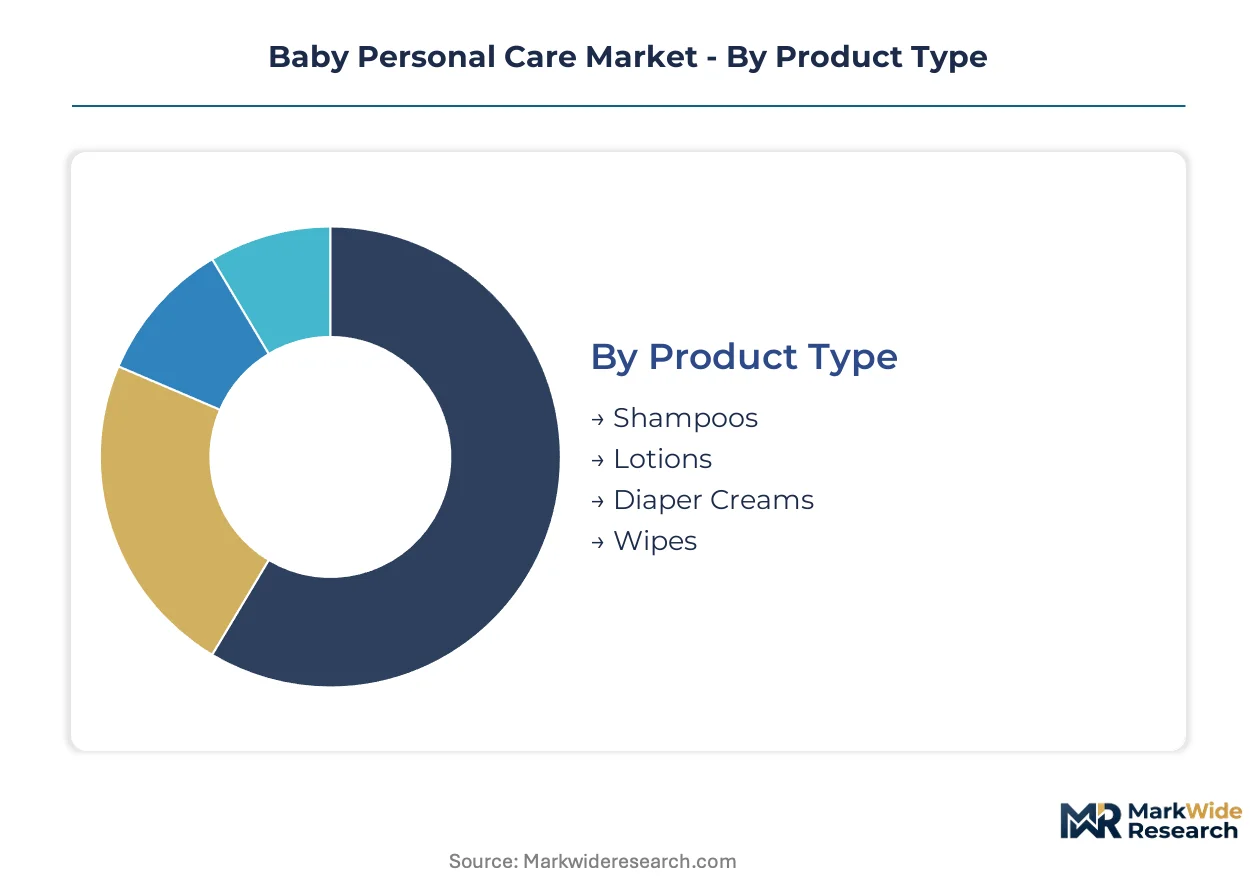
Market segmentation provides a granular view of product development priorities and consumer preferences within the baby personal care sector. Understanding these distinct segments allows manufacturers to tailor formulations, packaging, and marketing strategies effectively. This detailed analysis highlights the specific characteristics and demand drivers for each category.
Product Type:
Regulatory frameworks significantly differentiate product formulations and labeling requirements across the baby personal care market. The EU's Cosmetic Products Regulation mandates rigorous safety assessments for all ingredients in topical applications.
- Diaper Creams:These specialized formulations, often containing zinc oxide or petrolatum, create a protective barrier against moisture and irritation. Higher margins are found in these products due to their therapeutic function and specific ingredient requirements.
- Wipes:Pre-moistened cloths designed for quick cleansing, typically formulated with mild surfactants and moisturizers. Wipes represent a high-volume category driven by convenience, though intense competition limits margin potential.
- Shampoos:Mild, tear-free cleansing agents developed for an infant's delicate scalp and hair. These products prioritize gentle ingredients to avoid irritation.
- Lotions:Moisturizing emulsions formulated to hydrate and protect sensitive baby skin. Lotions often contain emollients and humectants to maintain skin barrier integrity.
Established volume favors Wipes; emerging adoption favors Diaper Creams due to specialized formulations.
Ingredient Type:
Margin potential varies considerably across ingredient types, reflecting both sourcing costs and consumer willingness to pay for perceived benefits. Parental demand for transparency drives innovation in ingredient selection.
- Natural:Formulations derived from plant, mineral, or animal sources, often appealing to parents seeking alternatives to synthetic chemicals. These products command premium pricing and often require third-party certifications.
- Organic:Ingredients cultivated without synthetic pesticides, fertilizers, or genetically modified organisms, verified by specific organic certifications. Organic formulations secure a premium position, particularly in discerning markets like Europe.
- Hypoallergenic:Products specifically formulated to minimize the risk of allergic reactions or skin irritation. These formulations undergo rigorous testing to exclude common allergens.
- Chemical-Based:Products primarily utilizing synthetic compounds for cleansing, moisturizing, or protecting baby skin. These formulations often offer cost-effectiveness and broad availability.
Cost-effectiveness underpins Chemical-Based formulations, while Natural ingredients drive market premiumization.
Age Group:
Specific physiological needs define product development and marketing strategies for distinct pediatric age groups. Skin sensitivity and activity levels evolve as children grow, requiring tailored product attributes.
- Newborns:Products designed for the extremely delicate and developing skin of infants from birth to one month, requiring ultra-mild, often fragrance-free formulations. This segment commands premium pricing due to intense parental scrutiny.
- Toddlers:Formulations addressing the needs of active children aged one to three years, often incorporating more robust cleansing and moisturizing properties. This segment allows for new product categories beyond traditional infant care.
- Infants:Products for babies aged one month to one year, balancing gentle care with increasing exposure to environmental factors. This broad category encompasses a wide range of everyday personal care items.
- Preschoolers:Personal care items for children aged three to five years, often focusing on hygiene habits and mild formulations for slightly more resilient skin. This group increasingly uses products mirroring adult offerings.
Broad consumer access characterizes Infant products, whereas Toddler-specific solutions exhibit the steepest expansion trajectory.
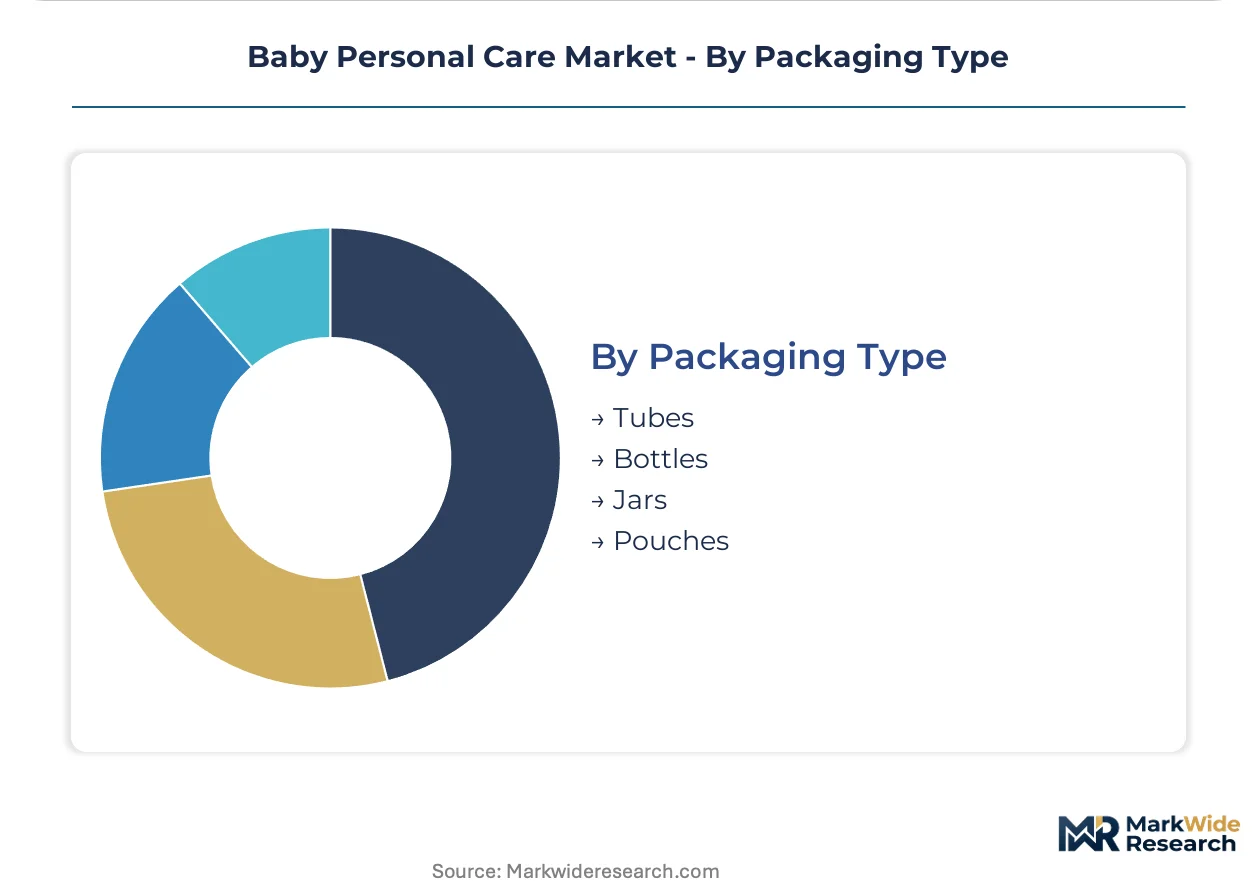
Packaging Type:
Convenience and sustainability considerations increasingly influence packaging choices across the baby personal care sector. Manufacturers balance product protection with user-friendliness and environmental impact.
- Pouches:Flexible, lightweight packaging offering convenience for travel and reduced material usage compared to rigid containers. This format gains traction for single-use or refillable options.
- Bottles:Rigid plastic or glass containers, a traditional format for liquid products like shampoos and lotions. Bottles remain a high-volume packaging choice across mass market channels.
- Tubes:Squeezable cylindrical containers ideal for creams, ointments, and smaller volume products. Tubes offer controlled dispensing and portability.
- Jars:Wide-mouthed containers, typically used for thicker creams, balms, or larger volume products. Jars facilitate easy access to viscous formulations.
Bottles maintain market share for liquid products, while Pouches offer enhanced portability and reduced material footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expanding middle class drives significant demand for premium baby personal care products, influencing global trade flows. European manufacturers often export specialized formulations to these discerning markets. This dynamic shapes investment and product development strategies across continents.
China
Demand for premium and specialized baby care products is surging among China's middle class, prioritizing perceived safety and quality. The National Medical Products Administration (NMPA) enforces distinct registration and testing protocols for imported and domestic goods. Major manufacturing hubs in the Yangtze River Delta actively invest in advanced production facilities for ingredient-focused brands.
United States
Parental preference for natural and organic formulations fuels demand for transparent ingredient lists and certified products in the United States. The US Food and Drug Administration (FDA) establishes stringent safety and labeling requirements for topical baby care items. Innovation clusters in California and New York focus on developing microbiome-friendly and therapeutic formulations for sensitive infant skin.
Germany
Ingredient transparency and plant-based formulations resonate strongly with discerning German parents seeking high-quality baby personal care. The European Union's Cosmetic Products Regulation mandates rigorous safety assessments for all ingredients sold across member states. Chemical and pharmaceutical centers in North Rhine-Westphalia lead research into new, compliant product innovations.
India
Rising disposable incomes and an increasing focus on infant health are driving demand for branded and specialized baby personal care products in India. The Bureau of Indian Standards (BIS) sets quality benchmarks for various consumer goods, including baby products. Manufacturing facilities around Mumbai and Delhi are expanding to meet the needs of a large consumer base.
Brazil
High birth rates and a growing middle class contribute to substantial demand for accessible and effective baby personal care solutions in Brazil. ANVISA, the national health surveillance agency, regulates the safety and efficacy of cosmetic products. Industrial parks in São Paulo are becoming centers for local production and distribution of both domestic and international brands.
Baby Personal Care Market Key Industry Players
Player mix skews toward established consumer goods conglomerates alongside specialized natural and organic brands. The market exhibits a tiered structure, with legacy players competing on broad portfolio and distribution, while niche entrants focus on premium, science-backed formulations. Strategic archetypes include diversified giants, plant-based specialists, and therapeutic solution providers. Portfolio diversification and geographic expansion are dominant competitive moves.
Specialists in science-backed formulations, Kenvue Inc. exemplifies leveraging a deep scientific research heritage to build trust with discerning parents seeking ingredient transparency and proven efficacy. Mustela, a French-based company, anchors the premium plant-based formulations segment, securing a distinct market position with its focus on newborn care. At the scale-driven end, Procter & Gamble, an Ohio-headquartered corporation, occupies a significant position through its broad portfolio, which addresses diverse consumer needs across multiple channels globally. These entities collectively represent the market's bifurcation between ingredient-focused premium offerings and broad-appeal, accessible strategies, each catering to distinct consumer segments.
| Leading Market Players |
|---|
| Unilever |
| Beiersdorf AG |
| Procter & Gamble |
| Kenvue Inc. |
| Unicharm Corporation |
| Kimberly-Clark Corporation |
| Kao Corporation |
| Mustela |
| Johnson & Johnson Services, Inc. |
| Others |
Cost & Logistics Intelligence
Days-of-inventory for specialized natural ingredients often exceed 90 days due to sourcing complexities, directly influencing the supply chain's shape and affecting premium product pricing power. This extended lead time necessitates robust planning.
Pricing Analysis
The pricing gap between advanced microbiome-friendly formulations and basic chemical-based products drives market bifurcation. Premium-mid-economy pricing differentiation exists across product types, with brand reputation and third-party certifications as critical price differentiation drivers. Pricing pressure stems from intense competition in mass channels for high-volume items like wipes, often against economy brands. Price sensitivity is highest among legacy, price-focused consumers, while Millennial and Gen Z parents exhibit lower sensitivity for transparent, science-backed offerings, supporting premium prices.
Supply Chain Analysis
Inventory buffers for specialized ingredients help mitigate volatility in raw material costs, particularly for botanical extracts. Geographic supply concentrates in China and India for mass-market components, while Europe and the US lead sourcing for advanced natural ingredients. Raw material dependencies include specific plant-based oils and zinc oxide. Commodity price volatility for these natural inputs presents a structural supply chain risk. Distribution runs through a hybrid model, combining traditional brick-and-mortar retail with rapidly expanding direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, driven by the increasing penetration of premium, ingredient-transparent products among discerning Millennial and Gen Z parents. Consumers are actively seeking specialized solutions beyond basic care.
For Market Incumbents: Compound scientific research heritage by investing in microbiome-friendly and therapeutic formulations to counter emerging niche brands. Focus R&D on clinically validated natural ingredients to maintain trust with ingredient-focused parents, a segment where legacy players face a threat from specialized entrants. Expand certified production capacity in regions like Europe to meet stringent regulatory demands.
For New Entrants and Emerging Players: Unmet needs for clinically-validated therapeutic formulations targeting specific infant skin conditions offer a significant white space. Target the toddler age group with distinct product categories beyond traditional infant care, leveraging direct-to-consumer channels for rapid market entry. Build brand narratives around transparent supply chains and third-party organic certifications, using e-commerce as a primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a consumer staples growth play because parental spending on perceived safety and health for infants is relatively inelastic. Target specialized brands with strong intellectual property in natural or microbiome-friendly formulations as acquisition archetypes. The signal to watch is the adoption rate of subscription models for premium baby care, indicating sustained consumer loyalty.
| Strategic Initiative | Industry Significance |
|---|---|
| Premium Tier Introduction | Captures higher margins from ingredient-focused parents seeking advanced, science-backed formulations. |
| Direct-to-Consumer Channel Expansion | Cultivates direct customer relationships and captures retail margins previously lost to intermediaries. |
| Microbiome-Friendly Formulation Development | Addresses growing consumer demand for products supporting infant skin barrier health and reduces irritant risk. |
| Certified Organic Sourcing Expansion | Secures supply for premium product lines and strengthens brand trust with transparency-seeking consumers. |
| Geographic Expansion into Southeast Asia | Accesses new consumer bases characterized by high birth rates and rising disposable incomes. |
Research Approach
Initial hypotheses were tested against primary input from brand managers, regulatory affairs leads, and pediatric dermatologists, and refined through iterative feedback. Secondary validation involved analysis of customs records, national health administration reports, and consumer spending data. This approach ensured bottom-up market sizing was triangulated with top-down industry trends.
Variance decomposition guided the analytical framework across the analysis window, modeling market dynamics across product type, ingredient type, age group, and packaging type. An additional dimension was regional regulatory compliance, reflecting market entry barriers. Compound annual growth rates were derived by assessing historical performance against projected demand drivers and market restraints. Forecast inputs included birth rates and disposable income growth in key emerging markets.
Underlying assumptions cover stable regulatory environments and consistent raw material supply, with deviation risk concentrated in unforeseen shifts in consumer preferences or geopolitical trade policies. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Global Organic and Natural Feminine Care Market
Consumer Goods
Probiotic Skin Care Cosmetic Product Market
Consumer Goods
Cutter Staplers Market
Consumer Goods
Computer Keyboard Market
Consumer Goods
Bass Guitar Market
Consumer Goods
Chest Freezers Market
Consumer Goods
Colombia Laundry Appliances Market
Consumer Goods
China Smoking Pipe Market
Consumer Goods
Nebulizing Diffuser Market
Consumer Goods
Running Shoes Market
Consumer Goods
Clothing Iron Market
Consumer Goods
Clothing Retail Market
Consumer Goods
Chunky Sneaker Market
Consumer Goods
United Kingdom Kitchen Appliances Market
Consumer Goods
Heated Tobacco Products Market
Consumer Goods
Home Fragrance Market