
 Bags Market | 2026-2036
Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Bags Market Analysis
Urban professionals and e-commerce fulfillment operators is reorganizing demand away from traditional retail-dependent consumers. Novolex Holdings, Inc. leverages its North American manufacturing footprint to serve grocery and foodservice chains with compliant packaging. Louis Vuitton anchors the luxury leather segment through controlled artisan production and direct retail channels. Mondi Group competes in industrial paper-based solutions with vertically integrated pulp-to-bag operations serving European retailers.
Bags are portable enclosures constructed from woven or non-woven substrates, typically ranging from 20 to 200 liters in volumetric capacity, designed to contain, protect, and transport goods across consumer, commercial, and industrial contexts. Manufacturing processes span cut-and-sew assembly for textile products, thermoforming for synthetic carriers, and glued or stitched fabrication for paper-based shipping sacks. Handbags and backpacks lead value generation through premium material sourcing and brand equity, while sports bags represent the fastest-expanding functional category as athleisure participation broadens. Polyester dominates volume production due to cost efficiency and recyclability, though leather commands the highest margin pools in direct-to-consumer channels.
The European Chemicals Agency enforces REACH substance restrictions that limit certain dyes and finishes in textile bag production, while the EU Packaging and Packaging Waste Directive mandates recyclability thresholds that reshape material selection across member states. China's State Administration for Market Regulation implements GB standards for plastic bag thickness and biodegradability claims, affecting both domestic manufacturers and export-oriented suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based certification schemes to secure compliant feedstock access and maintain market participation across jurisdictions.
Market Dynamics
Material substitution pressure from REACH substance restrictions and state-level plastic bag bans is fragmenting supply chains into regional compliance clusters, forcing manufacturers to maintain parallel feedstock portfolios across jurisdictions.
Growth Catalysts
- REACH substance restrictions:European ECHA enforcement of dye and finish limitations accelerates adoption of bio-based alternatives and recycled polyester across textile bag production.
- Urban professional commuter patterns:Daily transit and travel routines in dense metropolitan areas drive replacement of single-use carriers with durable reusable options.
- China's e-commerce fulfillment infrastructure:Domestic logistics expansion and luxury leather goods consumption concentrate demand growth in manufacturing clusters serving both segments.
Market Restraints
- Petrochemical feedstock volatility:Polyester resin prices fluctuate with crude oil markets, compressing margins on volume production tiers.
- Artisan leather supply concentration:Premium hide sourcing depends on established tannery networks in Italy and France with limited scalable alternatives.
- Biodegradability certification delays:China's SAMR GB standards for plastic bag claims create testing bottlenecks that slow product launches.
Strategic Opportunities
- Extended producer responsibility frameworks:EU Packaging and Packaging Waste Directive recyclability thresholds reward early movers with compliant closed-loop systems.
- Athleisure participation expansion:Sports bags capture functional demand from fitness and outdoor recreation segments with shorter replacement cycles than fashion categories.
- Direct-to-consumer channel migration:Controlled retail networks bypass wholesale margin erosion for premium leather goods producers.
Industry Challenges
- Multi-jurisdiction certification complexity:Manufacturers must simultaneously satisfy ECHA REACH, EU Packaging Directive, and China's GB standards with divergent testing protocols.
- Legacy cut-and-sew workforce transition:Thermoforming and automated assembly adoption requires reskilling programs in traditional textile manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bags Market |
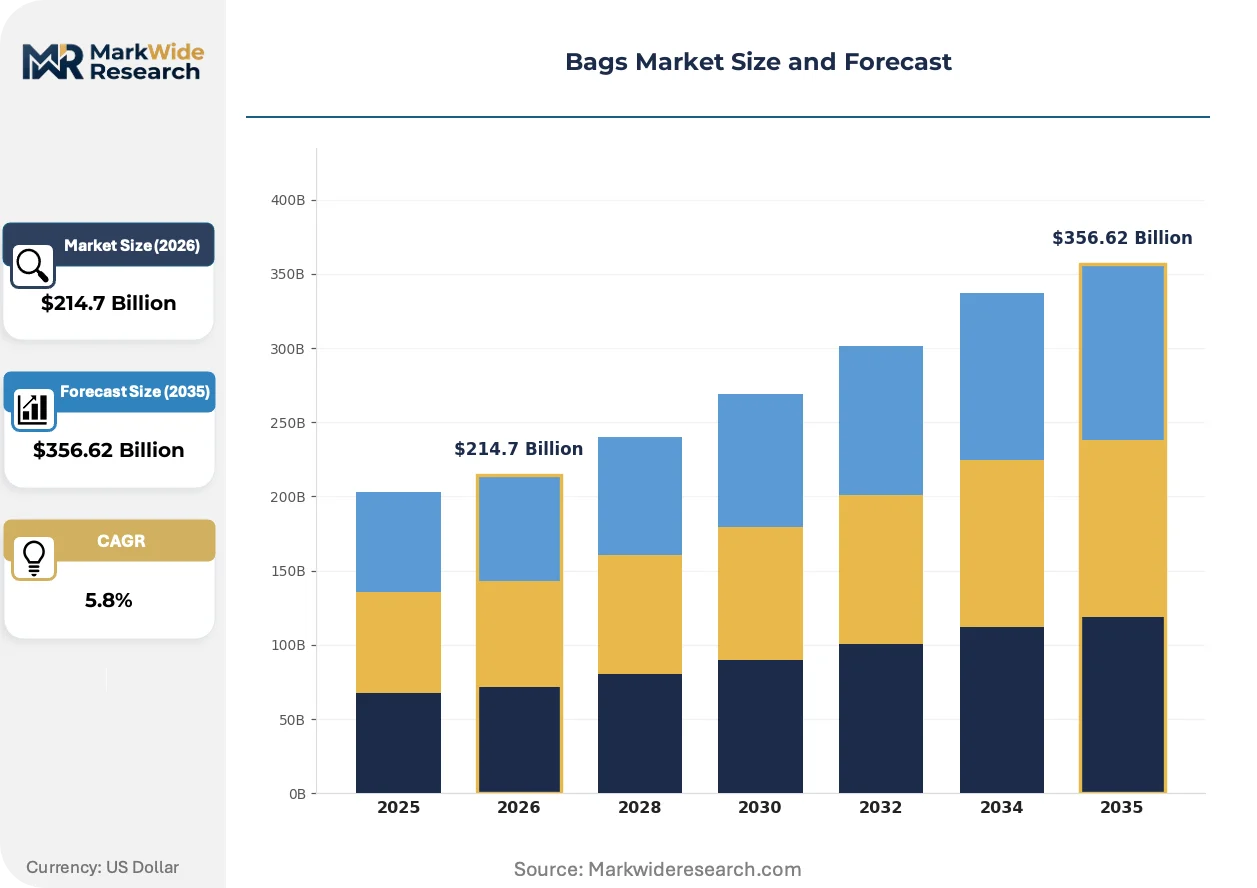
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $356.62 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacks, Handbags, Duffel Bags, Sports Bags Material: Leather, Nylon, Polyester, Canvas End User: Consumers, Retailers, Manufacturers, Wholesalers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores |
| Companies Covered | International Paper Company, Louis Vuitton, Novolex Holdings, Inc., Burberry Group, Hermès International, Mondi Group, Smurfit Kappa Group, LC Packaging International, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bags Market Emerging Trajectories
Active material science development and regulatory threshold tightening are compressing acceptable input portfolios while opening premium positioning for verified sustainable alternatives.
Mechanical and chemical recycling infrastructure for post-consumer polyester is decomposing virgin resin dependence in volume production tiers. Fast-fashion and promotional bag producers adopt certified recycled content at accelerating rates. This technology is decomposing cost parity barriers between virgin and circular feedstocks.
EU Packaging and Packaging Waste Directive recyclability mandates reshape material selection across member states. Industrial paper-based shipping sacks gain share against multi-layer plastic alternatives in European retail fulfillment. German and French grocery chains now specify mono-material constructions to satisfy sorting infrastructure requirements.
Urban professionals now prioritize durability verification and repair service availability over initial purchase price. Premium backpack and handbag segments respond with modular component designs and documented lifecycle programs. This behavioral pivot concentrates in Tokyo, London, and New York metropolitan commuter corridors.
Bags Market Segmentation
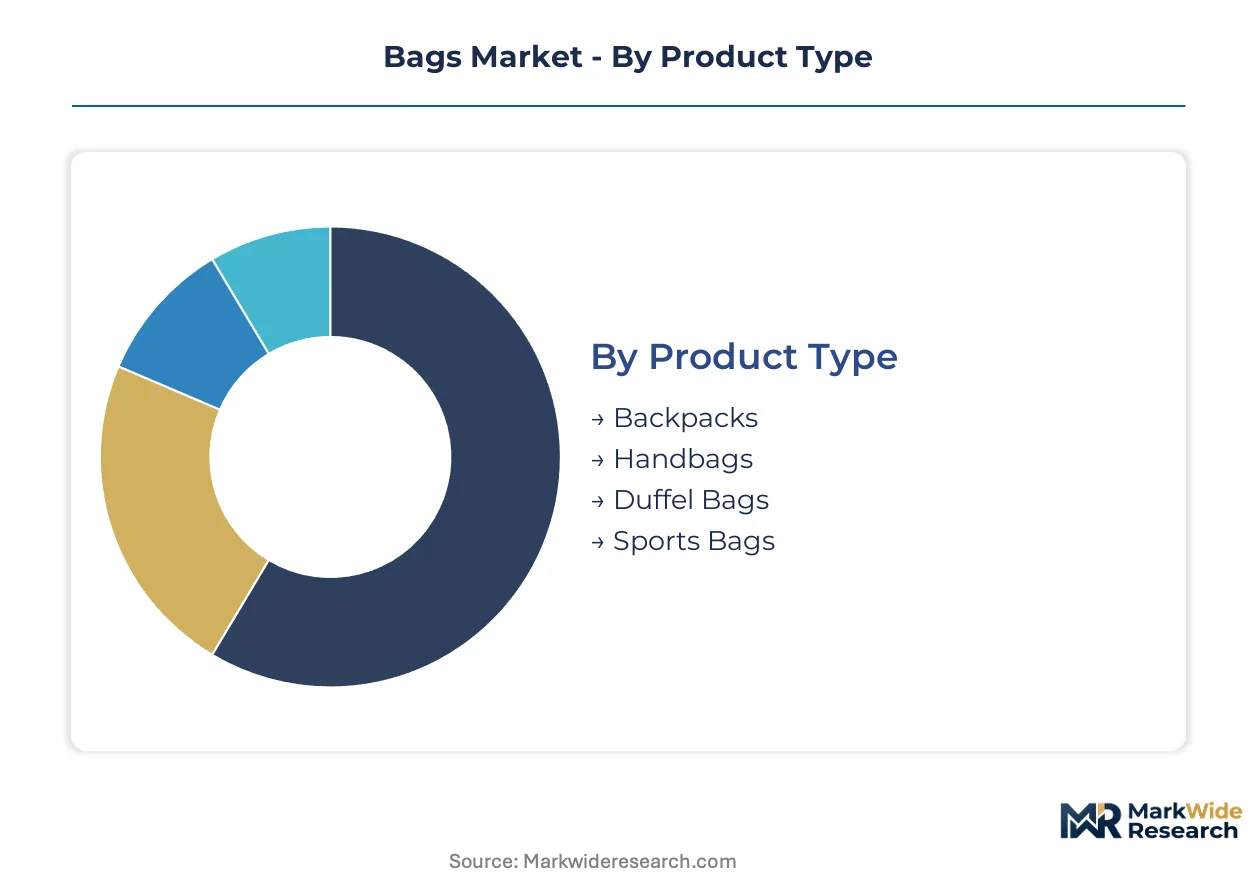
Segmentation in the bags market reveals how regulatory pressure and material substitution reshape competitive boundaries across product tiers. Manufacturers must align portfolio architecture with distinct compliance burdens and end-use durability requirements rather than pursuing undifferentiated scale.
Product Type:
Substitution pressure from reusable carrier mandates and athleisure participation is fragmenting demand across functional categories, with commuter durability requirements displacing single-use orientations.
- Backpacks:Constructed from woven polyester or nylon substrates with reinforced stitching at stress points, typically 20-35 liter capacity for daily commuter use. Demand concentrates in Tokyo, London, and New York metropolitan corridors where urban professionals prioritize modular repairable designs over disposable alternatives.
- Handbags:Premium leather or coated canvas constructions with metal hardware and lined compartments, positioned as fashion accessories and status markers. Italian and French artisan tanneries supply hide inputs to direct-to-consumer luxury channels, constrained by limited scalable alternatives to established European networks.
- Duffel Bags:Cylindrical soft-sided carriers with webbing handles and detachable shoulder straps, serving weekend travel and gym segments. Synthetic constructions face REACH dye restrictions in European fulfillment.
- Sports Bags:Ventilated compartments and water-resistant base panels designed for athletic equipment transport. Athleisure participation broadens replacement cycles in fitness and outdoor recreation segments.
Backpacks retain volume leadership; sports bags hold the steepest expansion curve.
Material:
Cost tier stratification separates premium hide inputs from volume synthetic production, with certification requirements adding margin pressure at each tier.
- Leather:Full-grain and top-grain bovine hides processed through chrome or vegetable tanning, commanding highest margin pools in direct-to-consumer channels. REACH substance restrictions on certain dyes and finishes accelerate bio-based alternative development in European production.
- Polyester:Virgin and recycled polyethylene terephthalate fibers woven into durable substrates, dominating volume production through cost efficiency and mechanical recyclability. Post-consumer recycling infrastructure is decomposing virgin resin dependence in fast-fashion and promotional tiers.
- Nylon:Polyamide polymers with higher tensile strength-to-weight ratios than polyester, serving technical outdoor and military specifications. Petrochemical feedstock volatility compresses margins on volume tiers.
- Canvas:Heavy cotton duck or blended natural fiber weaves, positioned as biodegradable alternatives to synthetic carriers. EU Packaging Directive recyclability thresholds reshape material selection toward mono-material constructions.
Polyester retains volume leadership; leather holds the steepest margin concentration.
End User:
Customer type determines order scale and specification complexity, with procurement patterns diverging between individual replacement cycles and institutional compliance requirements.
- Consumers:Individual purchasers selecting for personal use across fashion, travel, and daily carry applications. Urban professional commuter patterns in dense metropolitan areas drive durable reusable adoption over single-use carriers.
- Retailers:Grocery and fashion chains sourcing private-label and branded inventory for resale. German and French grocery chains now specify mono-material constructions to satisfy EU sorting infrastructure requirements.
- Manufacturers:Industrial purchasers of shipping sacks and protective enclosures for component transport. China's e-commerce fulfillment infrastructure concentrates demand growth in manufacturing clusters serving domestic logistics expansion.
- Wholesalers:Distributors aggregating volume orders for redistribution to smaller retail accounts. Procurement is shifting toward certified recycled content to satisfy downstream compliance documentation.
Consumers retain volume leadership; manufacturers hold the steepest expansion curve.
Distribution Channel:
Channel migration toward controlled retail networks is bypassing wholesale margin erosion for premium tiers while accelerating price transparency in volume segments.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling global reach with reduced physical footprint. China's domestic e-commerce fulfillment infrastructure expands logistics-dependent bag categories.
- Specialty Stores:Curated retail environments emphasizing brand experience and technical consultation, concentrated in premium leather and outdoor equipment segments. Repair service availability now influences purchase decisions in Tokyo and London corridors.
- Supermarkets:Mass-market grocery chains carrying basic reusable carriers and promotional items. State-level plastic bag bans across the United States compel material transitions toward recycled polyester and bio-based alternatives.
- Department Stores:Full-line retailers bridging mid-tier fashion and functional categories with seasonal merchandising. Distribution runs through established wholesale relationships facing margin compression from direct channel migration.
Online retail retains volume leadership; specialty stores hold the steepest margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan leather tanning clusters in Italy and France supply hide inputs to luxury channels, while polyester weaving operations concentrate in China's Yangtze River Delta. Regulatory divergence across ECHA REACH, EU Packaging Directive, and China's GB standards fragments compliance requirements by geography.
United States
State-level plastic bag bans in California and New York drive grocery chains toward recycled polyester carriers. EPA and state environmental agencies enforce varying thickness and reusability standards. Manufacturing for foodservice compliance concentrates in the Midwest industrial corridor serving national distribution networks.
China
E-commerce fulfillment infrastructure and luxury leather goods consumption expand simultaneously in manufacturing clusters. SAMR GB standards for plastic bag thickness and biodegradability claims create testing bottlenecks. Yangtze River Delta weaving operations supply both domestic logistics and export-oriented synthetic bag production.
Germany
Retail fulfillment chains specify mono-material paper constructions to satisfy EU sorting infrastructure requirements. ECHA REACH substance restrictions on textile dyes accelerate bio-based alternative development. Industrial paper-based shipping sack production clusters in the North Rhine-Westphalia packaging belt.
France
Artisan tannery networks in the Auvergne-Rhône-Alpes region supply full-grain hides to direct-to-consumer luxury channels. EU Packaging and Packaging Waste Directive recyclability thresholds reshape material selection toward certified mono-material constructions. Paris-based flagship retail anchors controlled distribution for premium leather goods.
Japan
Tokyo metropolitan commuters prioritize durability verification and repair service availability over initial purchase price. METI oversees standards for textile product safety and quality labeling. Kanto region specialty retailers emphasize modular component designs and documented lifecycle programs.
Bags Market Vendor Landscape
Concentration sits with diversified packaging conglomerates and controlled luxury houses. The vendor base spans vertically integrated paper producers, artisan leather workshops, and synthetic fabricators maintaining parallel feedstock portfolios. Three archetypes dominate: pulp-to-bag integrated paper specialists, direct-to-consumer luxury leather houses, and compliance-focused synthetic carriers. Competitive moves center on regional certification acquisition and repair service network deployment.
Within the luxury leather tier, Louis Vuitton and Hermès International exemplify controlled artisan production with direct retail channel dominance. Among North American packaging specialists, Novolex Holdings, Inc. and International Paper Company occupy positions serving grocery and industrial fulfillment segments. Mondi Group represents the pulp-to-bag integrated archetype with European retail-focused operations. These anchors illustrate how divergent material dependencies—tannery networks versus recycled fiber streams versus petrochemical feedstocks—produce distinct competitive moats across compliance jurisdictions.
| Leading Market Players |
|---|
| International Paper Company |
| Louis Vuitton |
| Novolex Holdings, Inc. |
| Burberry Group |
| Hermès International |
| Mondi Group |
| Smurfit Kappa Group |
| LC Packaging International |
| Berry Global |
| Others |
Supply Flow & Price Mechanics
Recycled polyester substitution for virgin resin is compressing cost differentials while redistributing supply geography toward mechanical recycling clusters in China and Southeast Asia. This feedstock pivot simultaneously erodes traditional petrochemical pricing power and rewards manufacturers with backward integration into post-consumer collection networks.
Pricing Analysis
ECHA REACH substance restrictions dictate the pricing tier structure across European textile bag production. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates verified bio-based alternatives from conventional synthetics. Price compression in volume polyester tiers stems from mechanical recycling infrastructure scaling. Grocery and fast-fashion buyers exhibit highest price sensitivity, while direct-to-consumer luxury channels absorb premium positioning.
Supply Chain Analysis
Inventory cycles stretch 8-12 weeks for European REACH-compliant dye sourcing against 3-4 weeks for standard polyester weaves. Manufacturing concentrates in China, Italy, and Vietnam, with artisan tanning anchored in Italian and French clusters. Raw material flows draw from petrochemical feedstocks, bovine hide networks, and post-consumer PET streams. Single-source vulnerability sits with established European tannery networks. Distribution runs through direct-to-consumer platforms, specialty retail, and grocery wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bags market is experiencing high-growth disruption from regulatory mandates accelerating material substitution timelines. ECHA REACH enforcement and China's GB standards together compress acceptable input portfolios while opening premium positioning for verified sustainable alternatives.
For Market Incumbents: Consolidate tannery network relationships and captive recycling infrastructure to defend margin pools against bio-based substitute entrants. Secure ECHA REACH pre-certification for dye and finish portfolios ahead of 2025 threshold tightening. Deepen backward integration into post-consumer PET collection to secure circular feedstock access.
For New Entrants and Emerging Players: Differentiate on modular repairable design and documented lifecycle programs targeting Tokyo and London metropolitan commuter corridors. White-space opportunity sits in certified biodegradable alternatives to synthetic sports bags. Pursue direct-to-consumer launch with repair service bundling to bypass wholesale margin compression.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed synthetic fabricators lacking REACH-compliant dye portfolios. Five-to-ten-year viability hinges on certification acquisition speed and regional compliance cluster access. Signal to monitor: ECHA substance restriction list expansion velocity and China's SAMR testing bottleneck resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | ECHA REACH pre-certification secures market access ahead of 2025 dye restriction enforcement. |
| Backward Integration | Captive post-consumer PET collection decomposes virgin resin cost volatility for volume tiers. |
| Repair Network Deployment | Documented lifecycle programs capture Tokyo commuter willingness-to-pay durability premiums. |
| Direct Channel Migration | Controlled retail bypasses wholesale margin erosion for premium leather goods producers. |
| Mono-Material Transition | EU Packaging Directive compliance satisfies German and French grocery chain procurement specifications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at luxury leather houses, category buyers at European grocery chains, plant managers at Yangtze River Delta weaving operations, and sustainability officers at packaging conglomerates. Secondary validation drew from ECHA substance restriction databases, EU Packaging Directive implementation reports, China SAMR GB standard filings, and customs trade data on polyester fiber flows. Bottom-up volume modeling triangulated against top-down market sizing across material, product, and end-use dimensions.
Across the analysis window, forecasts reflect segment-specific growth trajectories calibrated to regulatory enforcement timelines and material substitution elasticities. Segmentation dimensions modeled include product type, material substrate, end-user archetype, and distribution channel. CAGR derivation incorporated historical compliance cost pass-through patterns and e-commerce fulfillment infrastructure expansion rates. Industry-specific inputs encompassed REACH certification adoption curves and China's domestic logistics capacity buildout.
The analysis sits within stated boundaries; outcomes outside sustained ECHA enforcement or accelerated SAMR testing throughput would require recalibration. Forecasts reflect assumptions on regulatory threshold stability and mechanical recycling cost parity achievement. Revision becomes warranted when petrochemical feedstock volatility or biodegradability certification delays cross material substitution inflection thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
School Bags Market
Luggage
Kids Backpack Market
Luggage
Travel Bag Market
Luggage
Sewing Bags Market
Luggage
Trolley Bags Market
Luggage
Travel and Business Bags Market
Luggage
Smart Carry-On Luggage Market
Luggage
Laptop Carry Case Market
Luggage
Laptop Messenger Bags Market
Luggage
Global Smart Luggage and Tracking Technologies Market
Luggage
Smart Bags Market
Luggage
Global Outdoor Sports Luggage Market
Luggage
Trunks Market
Luggage
Global Premium Luggage Market
Luggage
Backpack Market
Luggage
Camera Bag Market