
 Classical Guitar Market | 2026-2036
Classical Guitar Market Size, Share, and Industry Trends Forecast 2026-2036
Classical Guitar Market Insights
Specialty retailer networks is narrowing as direct-to-luthier digital platforms capture discerning buyers seeking provenance documentation. Yamaha leverages vertical integration across Asian manufacturing to sustain volume leadership in student-grade instruments. Jose Ramirez Guitars anchors its position through century-old Madrid workshop traditions that dominate heritage-seeking collectors. Cordoba competes by specializing in hybrid designs that bridge nylon-string authenticity with contemporary playability standards.
A classical guitar denotes a nylon-stringed instrument with a flat wooden soundboard, typically spruce or cedar, paired with a rosewood or mahogany back and sides, constructed via Spanish heel or dovetail joint methods to produce warm, sustained tones for solo and ensemble performance. The acoustic segment retains volume leadership due to institutional education procurement and recital culture, though carbon fiber materials represent the fastest-growing structural category as climate-stable alternatives gain traction among touring professionals. Premium and luxury price tiers concentrate margin pools where hand-built European and Japanese ateliers command waiting-list scarcity, while budget and mid-range tiers serve mass enrollment in formal music academies across East Asia and Latin America.
The European Union's REACH framework governs chemical treatments in tonewood finishing, while the U.S. Lacey Act and CITES enforcement restrict endangered rosewood and mahogany trade, compelling makers to certify alternative species or synthetic substitutes. Japan's METI quality labeling standards shape export competitiveness for domestic builders targeting discerning Asian markets. Stakeholders must monitor evolving CITES appendix revisions and regional deforestation enforcement to secure sustainable material pipelines without disrupting heritage craft specifications.
Market Dynamics
The European Union's F-Gas Regulation and CITES enforcement are forcing luthiers to abandon synthetic materials and endangered rosewood, redirecting supply chains toward certified alternative tonewoods while preserving acoustic performance standards.
Growth Catalysts
- South Korean music education procurement:National institutions are expanding instrument acquisition programs, creating institutional volume demand for student-grade nylon-string instruments.
- Carbon fiber structural innovation:Climate-stable composite materials are gaining traction among touring professionals who require humidity-resistant instruments for international performance schedules.
- REACH framework compliance adaptation:European chemical treatment standards are accelerating certified finishing process adoption, legitimating heritage craft methods for export markets.
Market Restraints
- Rosewood and mahogany trade restrictions:U.S. Lacey Act and CITES Appendix II listings have eliminated traditional tonewood sourcing, forcing makers to certify substitute species with unproven acoustic aging profiles.
- Granada-Madrid luthier cluster concentration:Premium handcraft production centers on two Spanish cities, creating geographic supply vulnerability and extended waiting-list scarcity for heritage instruments.
- Synthetic material prohibition:F-Gas Regulation restrictions on fluorinated compounds eliminate established composite alternatives, narrowing material option sets during transition periods.
Strategic Opportunities
- East Asian conservatory enrollment expansion:Formal music academy growth in China and South Korea represents underpenetrated institutional procurement volume for mid-range instrument tiers.
- Direct-to-luthier digital platforms:Provenance documentation capabilities are displacing specialty retailer networks, enabling margin capture and buyer relationship ownership for independent makers.
- Japanese METI quality labeling alignment:Export competitiveness standards create regulatory tailwinds for domestic builders targeting discerning Asian collector markets with certified craftsmanship documentation.
Industry Challenges
- Heritage craft skill transmission:Spanish heel and dovetail joint construction expertise concentrates among aging European and Japanese atelier masters, threatening production continuity without formal apprenticeship pipeline development.
- Alternative tonewood certification timelines:Sustainable species substitution requires multi-year acoustic testing and luthier community acceptance cycles before market legitimacy establishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Classical Guitar Market |
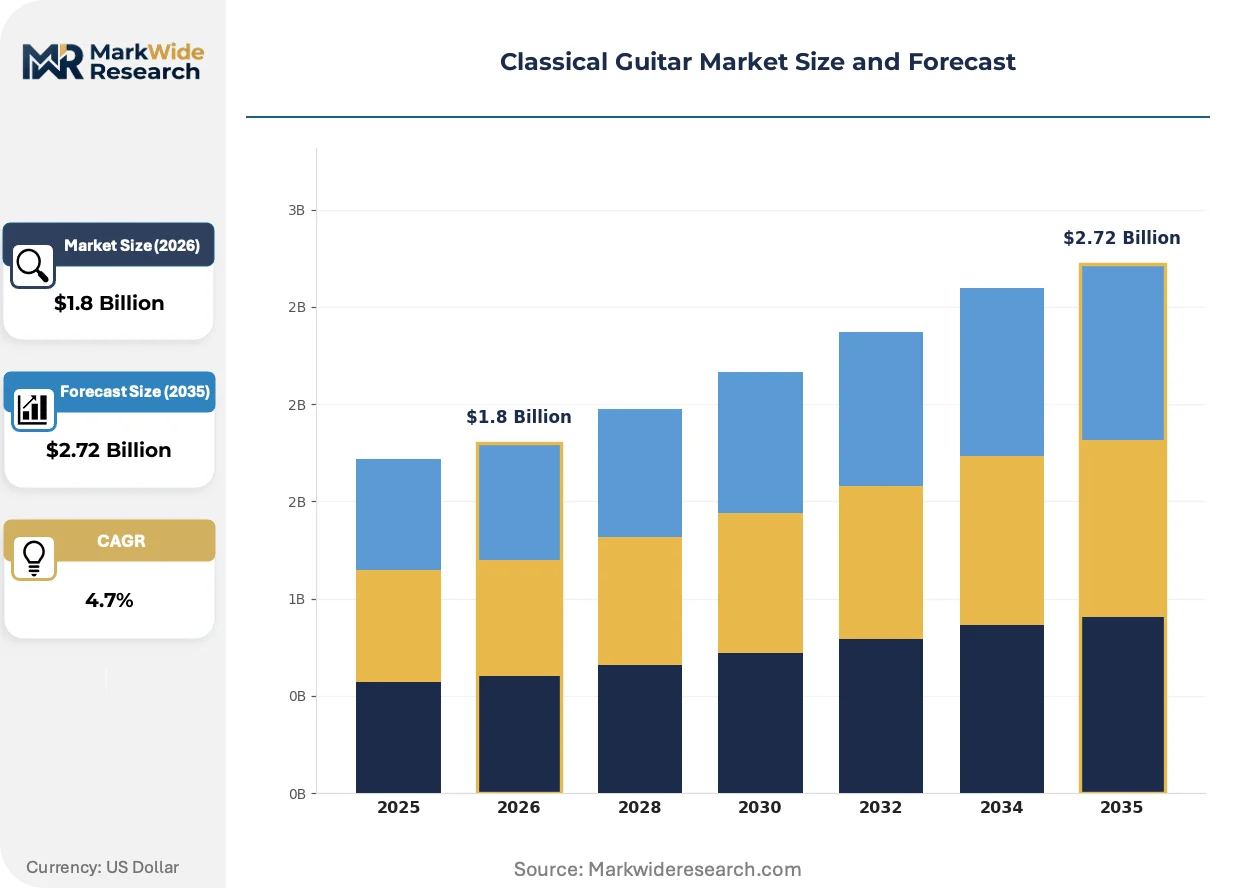
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic, Electric, Hybrid, Travel Material: Wood, Composite, Carbon Fiber, Aluminum Skill Level: Beginner, Intermediate, Advanced, Professional Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Kenny Hill (Hill Guitar Company), Yamaha, Jose Ramirez Guitars, Hanika, Cordoba, Antonio Marin Montero, Gernot Wagner, Altamira, Daniel Friederich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Classical Guitar Market Trends and Innovations
Material science advances and distribution channel restructuring are reshaping competitive positioning between heritage handcraft and manufactured volume segments, with regulatory pressure accelerating convergence toward documented sustainability credentials.
Carbon fiber composite construction is hybridizing traditional Spanish heel methods with climate-stable engineering, enabling touring professionals to maintain intonation consistency across humidity-variable performance environments while retaining nylon-string tonal character. Japanese and North American makers are adopting these hybrid architectures fastest, compressing the historical trade-off between acoustic authenticity and environmental durability.
REACH chemical treatment disclosure mandates and CITES documentation requirements are tightening material provenance standards, compelling European makers to maintain chain-of-custody records from forest harvest through finishing application. Spanish luthier clusters face the steepest compliance burden given their reliance on traditional rosewood reserves, driving accelerated substitution testing for certified mahogany alternatives.
Specialty retailer networks are narrowing as institutional buyers in South Korean and Chinese conservatories establish direct procurement relationships with volume manufacturers, while individual collectors migrate to digital platforms offering workshop documentation and luthier provenance verification. This channel disintermediation concentrates margin capture with production source points and compresses intermediary inventory carrying roles.
Classical Guitar Market Segmentation
Classical guitar procurement patterns diverge sharply across institutional buyers, touring professionals, and heritage collectors. Each segment demands distinct service intensity, from factory warranty support for educational volume to lifetime maintenance relationships for hand-built instruments.
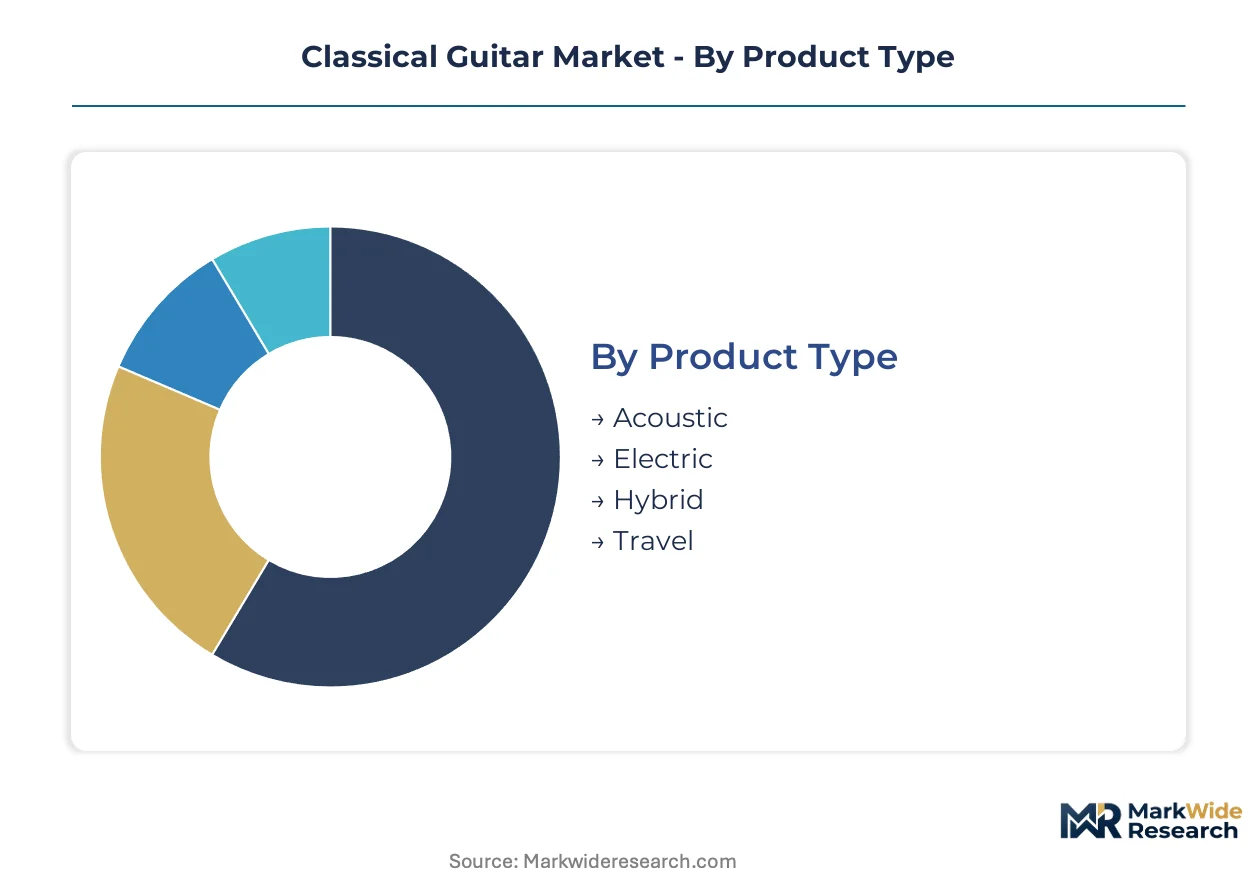
Product Type:
After-sales service intensity varies dramatically by construction method, with solid-wood instruments requiring seasonal humidity management and carbon fiber variants demanding minimal intervention.
- Acoustic:Traditional nylon-string construction with spruce or cedar soundboards and rosewood or mahogany back and sides produces warm, sustained tones. Spanish conservatories and East Asian music academies concentrate procurement volume here, though CITES enforcement on endangered tonewoods constrains supply continuity for institutional buyers.
- Electric:Piezoelectric pickup systems and preamplifier electronics enable stage amplification while preserving nylon-string timbre. Touring professionals in Japan and North America drive replacement demand as onboard electronics require periodic servicing and pickup calibration.
- Hybrid:Combines classical neck width and string spacing with cutaway bodies and ergonomic enhancements. Cordoba and similar manufacturers target advancing students seeking contemporary playability without abandoning nylon-string technique.
- Travel:Reduced-scale bodies and detachable necks address portability requirements. Carbon fiber variants dominate this niche as humidity-stable alternatives for international performers.
Acoustic holds the largest share; momentum sits with Hybrid as conservatory students seek performance-oriented features.
Material:
Supply chain certification burdens concentrate on wood sourcing, while synthetic alternatives face divergent regulatory treatment across manufacturing geographies.
- Wood:Spruce, cedar, rosewood, and mahogany remain the acoustic standard despite CITES Appendix II restrictions. Spanish luthier clusters in Granada and Madrid anchor heritage production, though EU F-Gas Regulation and REACH chemical disclosure mandates complicate finishing processes for export markets.
- Composite:Glass-fiber and resin laminates offer cost-efficient durability for educational institutions. South Korean music programs increasingly specify composite alternatives as procurement volumes strain traditional tonewood availability.
- Carbon Fiber:Climate-stable engineering eliminates humidity-related intonation drift. Touring professionals across humid subtropical performance circuits adopt these instruments fastest, compressing the traditional trade-off between acoustic authenticity and environmental durability.
- Aluminum:Experimental CNC-machined bodies enable precise bracing geometry control. Niche adoption concentrates among avant-garde performers and industrial-design collectors seeking visual distinction.
Wood retains volume leadership; carbon fiber is expanding most quickly as international touring resumes.
Skill Level:
Instructional progression paths determine replacement frequency, with beginner instruments exhibiting highest turnover and professional-grade purchases exhibiting extreme longevity.
- Beginner:Factory-built instruments with laminated construction and standardized setup specifications. Mass enrollment in Chinese and South Korean conservatories drives institutional procurement volume at this tier.
- Intermediate:Solid-top construction with upgraded tuning machines and enhanced fretwork precision. Individual purchasers dominate as students transition from rental programs to personal ownership.
- Advanced:Hand-finished instruments from established European and Japanese workshops. Waiting-list scarcity and provenance documentation become decisive purchase factors.
- Professional:Commissioned builds from named luthiers with specified tonewood reserves and historical pedigree. Madrid atelier instruments command premium positioning through century-old workshop traditions.
Beginner captures the highest unit volume; Advanced generates the steepest margin expansion.
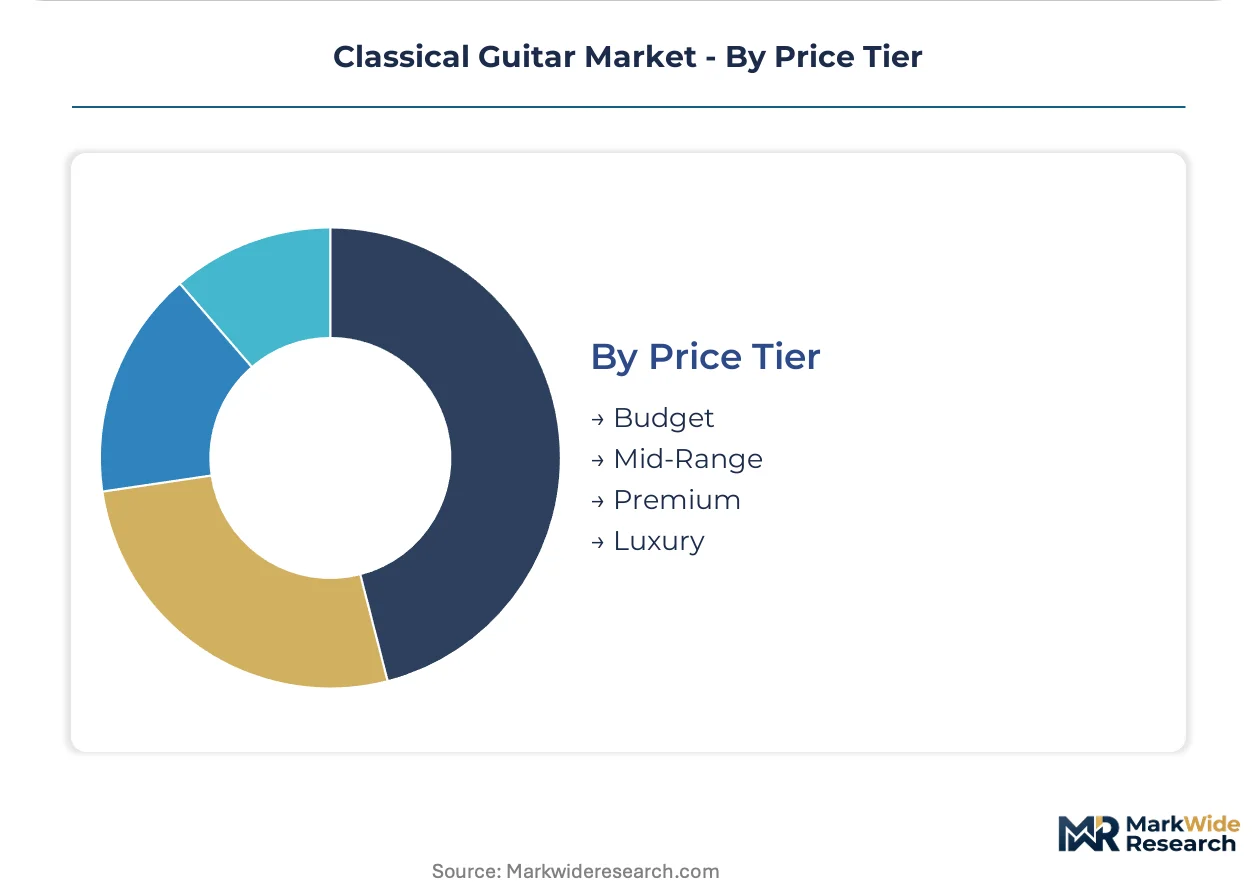
Price Tier:
Margin concentration inversely correlates with volume scale, as hand-built scarcity commands price premiums that factory efficiency cannot replicate.
- Budget:Mass-manufactured instruments targeting rental fleets and introductory educational programs. Yamaha leverages Asian manufacturing scale to sustain leadership here.
- Mid-Range:Solid-wood construction with factory consistency and dealer warranty support. East Asian conservatory expansion represents underpenetrated procurement opportunity.
- Premium:Hand-built instruments from recognized workshops with documented provenance. Jose Ramirez Guitars anchors this tier through Madrid heritage positioning.
- Luxury:Commissioned instruments with specified tonewood reserves, historical pedigree, and direct luthier relationships. Digital platforms displace specialty retailers for provenance documentation at this tier.
Budget and Mid-Range dominate unit shipments; Premium and Luxury concentrate margin pools where scarcity pricing prevails.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Valencia anchors Spain's export logistics for hand-built instruments destined for conservatories across East Asia and North America. This maritime infrastructure underwrites the Granada-Madrid luthier cluster's access to international collector markets.
Spain
Heritage collectors drive demand for Madrid atelier instruments with century-old workshop pedigrees. The EU F-Gas Regulation restricts synthetic materials in finishing processes, compelling makers toward certified tonewood alternatives. Granada luthier workshops concentrate premium handcraft production, though CITES enforcement on rosewood reserves disrupts traditional supply chains.
South Korea
National music education institutions are expanding instrument procurement programs for conservatory enrollment growth. The MFDS quality labeling standards shape import requirements for student-grade nylon-string instruments. Seoul Capital Area distributors are establishing direct relationships with Asian manufacturers, bypassing traditional specialty retailer networks.
Japan
Discerning collectors in Tokyo and Osaka command documented provenance for hand-built European and domestic atelier instruments. METI quality labeling standards create regulatory tailwinds for domestic builders targeting export competitiveness. Kansai region workshops are accelerating carbon fiber hybrid adoption among touring professionals seeking climate-stable alternatives.
United States
University music programs and community college conservatories sustain institutional volume demand for student-grade instruments. The Lacey Act restricts endangered rosewood and mahogany trade, forcing makers to certify alternative species with unproven acoustic aging profiles. California-based direct-to-luthier digital platforms are displacing specialty retailers for provenance documentation.
Germany
Formal music academies in Bavaria and North Rhine-Westphalia drive mid-range instrument procurement for advancing students. ECHA REACH framework compliance mandates chemical treatment disclosure in tonewood finishing, legitimating heritage craft methods for export markets. Baden-Württemberg distributors are consolidating procurement relationships with Spanish ateliers for premium-tier scarcity instruments.
Classical Guitar Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in tonewood sourcing and bracing fabrication. The vendor base stratifies across heritage handcraft ateliers, Asian volume manufacturers, and hybrid-design specialists. Three archetypes dominate: Madrid-centered heritage workshops with century-old traditions, vertically integrated Asian producers leveraging manufacturing scale, and composite-material innovators bridging acoustic authenticity with climate stability. Competitive moves concentrate on direct-to-consumer digital platform development and certified sustainable material pipeline construction.
Within the heritage atelier tier, Jose Ramirez Guitars and Antonio Marin Montero exemplify Madrid workshop traditions that anchor collector-market positioning through documented provenance and waiting-list scarcity. Yamaha occupies the volume-manufacturing archetype, leveraging Asian production scale to sustain leadership in student-grade institutional procurement. Cordoba represents the hybrid-design specialist, bridging nylon-string authenticity with contemporary playability standards for advancing conservatory students.
| Leading Market Players |
|---|
| Kenny Hill (Hill Guitar Company) |
| Yamaha |
| Jose Ramirez Guitars |
| Hanika |
| Cordoba |
| Antonio Marin Montero |
| Gernot Wagner |
| Altamira |
| Daniel Friederich |
| Others |
Pricing and Supply Chain Analysis
Granada-Madrid luthier cluster capacity constraints concentrate pricing power with heritage ateliers commanding waiting-list premiums, while Asian manufacturing scale compresses student-grade margins through volume efficiency.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement patterns. Price differentiation hinges on hand-built certification grade and volume scale, with Madrid atelier instruments commanding scarcity premiums against factory-built alternatives. Pricing pressure stems from CITES enforcement disrupting traditional rosewood reserves, forcing substitution costs onto mid-tier makers. Conservatory procurement officers exhibit highest price sensitivity, while heritage collectors demonstrate inelastic demand for documented provenance.
Supply Chain Analysis
Extended payment terms from Spanish tonewood merchants now stretch 90-120 days as certified alternative species command sourcing premiums. Supply concentrates in Spain, Japan, and China, with Granada workshops drawing from diminishing Andalusian spruce reserves and Asian manufacturers sourcing from plantation cedar. Single-source vulnerability concentrates in Madrid atelier master luthiers whose aging expertise lacks formal apprenticeship pipelines. Distribution runs through direct-to-luthier digital platforms displacing specialty retailer intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spanish heel construction expertise concentrates among aging European and Japanese masters, threatening production continuity as institutional enrollment surges demand replacement instruments.
For Market Incumbents: Harden supply chain resilience by securing certified tonewood forward contracts with FSC-certified plantations before REACH disclosure mandates tighten. Invest in hybrid carbon fiber R&D to capture touring professional demand as climate stability becomes non-negotiable. Defend against direct-to-luthier platform disintermediation by building proprietary provenance documentation systems. For New Entrants and Emerging Players: Pursue East Asian conservatory procurement relationships in South Korea and China where institutional volume strains traditional supply capacity. Carbon fiber composite construction offers the most penetrable entry point given regulatory tailwinds from F-Gas synthetic restrictions. Establish METI quality labeling alignment early to unlock Japanese export competitiveness. For Investors and Strategic Acquirers: Long-term, this sits as a heritage scarcity play because hand-built instrument waiting lists extend years while master luthier demographics compress. Target acquisition archetypes: Japanese ateliers with carbon fiber hybrid capabilities and documented METI certification. Monitor CITES Appendix revision timing as inflection signal for alternative tonewood substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Tonewood Pipeline Securement | FSC-certified spruce and cedar reserves from European plantations satisfy REACH disclosure mandates for Madrid atelier export continuity. |
| Carbon Fiber Hybrid Platform Launch | Climate-stable engineering captures touring professional demand across humid subtropical performance circuits in Asia and Latin America. |
| Direct-to-Luthier Digital Platform Buildout | Provenance documentation capabilities disintermediate specialty retailers and capture margin ownership for independent Spanish makers. |
| East Asian Conservatory Procurement Partnership | Seoul and Beijing institutional volume relationships secure factory-scale demand against traditional European handcraft scarcity. |
| METI Quality Labeling Alignment Investment | Japanese export competitiveness standards create regulatory tailwinds for domestic builders targeting discerning Asian collector markets. |
Research Methodology
Desk research of customs trade databases, CITES permit filings, and music education procurement records preceded structured interviews with luthier atelier owners, conservatory procurement directors, specialty retailer buyers, and tonewood import specialists. Primary fieldwork across Granada, Madrid, and Tokyo workshops combined with secondary validation from EU F-Gas Regulation implementation reports and METI quality standard documentation. Bottom-up instrument shipment tallies triangulated against top-down education enrollment projections.
Assumptions held regulatory enforcement timelines and CITES Appendix listings fixed while varying conservatory enrollment growth rates and carbon fiber adoption curves across the analysis window. Segmentation modeling incorporated construction method, material category, skill level progression, and price tier stratification. CAGR derivation weighted historical shipment volatility against institutional procurement pipeline visibility, with tonewood substitution cost trajectories and digital platform penetration rates as key industry-specific inputs.
Sensitivities concentrate around CITES enforcement intensity and master luthier retirement timelines. Forecasts reflect documented assumption sets without claiming predictive certainty. Macroeconomic contraction in East Asian education funding, accelerated F-Gas synthetic material prohibitions, or breakthrough synthetic tonewood acoustics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Musical Instruments
Electronic Musical Instruments Market
Musical Instruments
Global Piano Market
Musical Instruments
Violin Market
Musical Instruments
Kids Musical Instrument Market
Musical Instruments
Electric Guitar Market
Musical Instruments
Electric Violin Market
Musical Instruments
Smart Musical Instrument Market
Musical Instruments
Digital Ensemble Pianos Market
Musical Instruments
Woodwind Instruments Market
Musical Instruments
Drum Sets Market
Musical Instruments
Bass Guitar Market
Musical Instruments
Digital Piano Market
Musical Instruments
Guitar Market