
 Baby Care Products Market | 2026-2036
Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Care Products Market Analysis
Subscription-based replenishment revenue is reconfiguring how brands capture lifetime value from new parents. Procter & Gamble leverages its direct-to-consumer infrastructure to lock in recurring diaper and wipe deliveries. Kimberly-Clark Corporation anchors its North American position through pharmacy and hospital channel partnerships. Beiersdorf AG differentiates via dermatological testing protocols that sustain premium pricing in European markets.
Baby care products encompass formulated goods engineered for infant hygiene, skin barrier protection, and nutritional supplementation, typically manufactured under ISO 22716 cosmetic GMP standards with pH-balanced surfactant systems below 5.5 to match neonatal skin acidity. These products serve commercial purposes ranging from daily cleansing routines to medical-grade barrier creams preventing diaper dermatitis. Diapers and wipes occupy the largest volume pools due to per-unit consumption frequency, while organic formulations within lotions and shampoos capture expanding margin pools as ingredient transparency becomes a purchase determinant. Online retail channels are accelerating fastest among distribution pathways, though supermarkets still control impulse-driven trial purchases for new product introductions.
FDA cosmetic labeling requirements and the EU REACH framework govern ingredient safety thresholds, with REACH's SVHC candidate list actively restricting preservatives like certain formaldehyde releasers in wipe solutions. China's NMPA and GB standards for infant cosmetics mandate enhanced safety testing that shapes product registration timelines and reformulation cycles for multinational entrants. Stakeholders must monitor evolving state-level chemical disclosure laws in the United States and ingredient blacklist expansions in Europe to anticipate compliance-driven portfolio restructuring.
Market Dynamics
Subscription-based replenishment models are restructuring lifetime value capture in baby care, as direct-to-consumer infrastructure locks parents into recurring diaper and wipe deliveries while eroding traditional retail foot traffic.
Growth Catalysts
- REACH SVHC restrictions:The EU's expanding candidate list of substances of very high concern is accelerating reformulation investment toward bio-based preservatives, creating first-mover advantages for compliant brands in European pharmacy channels.
- Urban millennial purchasing:Parents in tier-one Chinese cities and metropolitan India are consolidating spending through e-commerce platforms that bundle organic lotions with diagnostic skin-monitoring tools.
- pH-balanced surfactant systems:Manufacturing advances in neonatal-matched acidity formulations below 5.5 are opening medical-grade barrier cream categories previously restricted to hospital procurement.
Market Restraints
- Petrochemical feedstock volatility:Superabsorbent polymer inputs for diaper cores face price instability tied to crude oil fluctuations, compressing margin pools for mass-market manufacturers.
- China NMPA registration timelines:Enhanced infant cosmetic safety testing mandates extend product approval cycles to 18-24 months, delaying multinational portfolio launches.
- Plant-based surfactant performance gaps:Natural cleansing alternatives struggle to match synthetic foam stability in hard water regions, limiting geographic rollout for premium organic shampoos.
Strategic Opportunities
- Telehealth-integrated sampling:Pediatric dermatology platforms in the United States are piloting AI-driven skin analysis that triggers personalized product subscriptions, collapsing trial-to-purchase friction.
- India PLI scheme alignment:Domestic manufacturing incentives for personal care inputs are enabling cost-competitive organic formulation production for export to Middle Eastern markets.
- EU Green Deal circularity mandates:Packaging reuse requirements are creating infrastructure partnerships between brands and municipal collection systems in Germany and France.
Industry Challenges
- ISO 22716 auditor scarcity:Certified cosmetic GMP assessors are concentrated in Western Europe, creating bottlenecks for facility qualification in emerging manufacturing hubs.
- Legacy ERP integration:Batch traceability systems required for REACH compliance are forcing mid-tier manufacturers to replace decade-old inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Care Products Market |
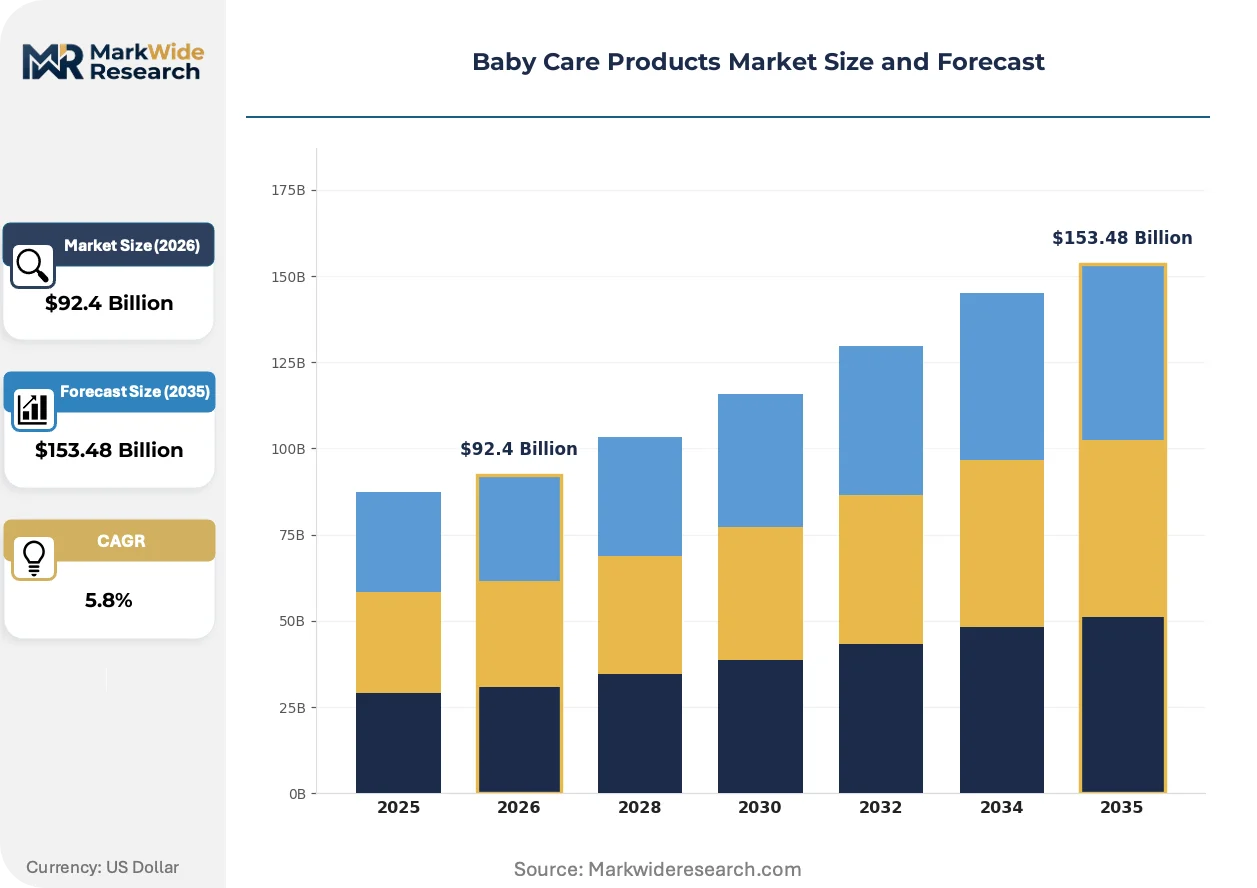
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $153.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Wipes, Lotions, Shampoos Distribution Channel: Supermarkets, Online Retail, Pharmacies, Specialty Stores Age Group: Newborns, Infants, Toddlers, Pre-schoolers Formulation: Organic, Hypoallergenic, Fragrance-Free, Antibacterial |
| Companies Covered | Procter & Gamble, Johnson & Johnson, Kimberly-Clark Corporation, Nestle S.A., Unilever, Abbott Laboratories, Danone S.A., Beiersdorf AG, Pigeon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Care Products Market Emerging Trajectories
Ingredient transparency protocols and biometric monitoring are converging to transform how parents evaluate product safety, shifting purchasing authority from marketing claims to verifiable dermatological data.
Biometric skin-monitoring wearables embedded in diaper elastic bands are collapsing the feedback loop between irritation onset and corrective product application. Premium parents in Seoul and Singapore are adopting these sensors fastest, compressing response times from hours to minutes and enabling predictive rather than reactive barrier cream deployment.
ECHA's SCIP database obligations under REACH are forcing granular supply chain disclosure for articles containing candidate list substances. Wipe manufacturers must now document fragrance compound origins down to the refinery level, with German and Dutch authorities conducting the most aggressive enforcement audits.
Hospital discharge kits are unbundling from institutional procurement into direct-to-parent subscription triggers. New mothers in Texas and California receive branded starter packs at maternity wards, then convert to automated replenishment via pharmacy partnerships rather than supermarket restocking.
Baby Care Products Market Segmentation
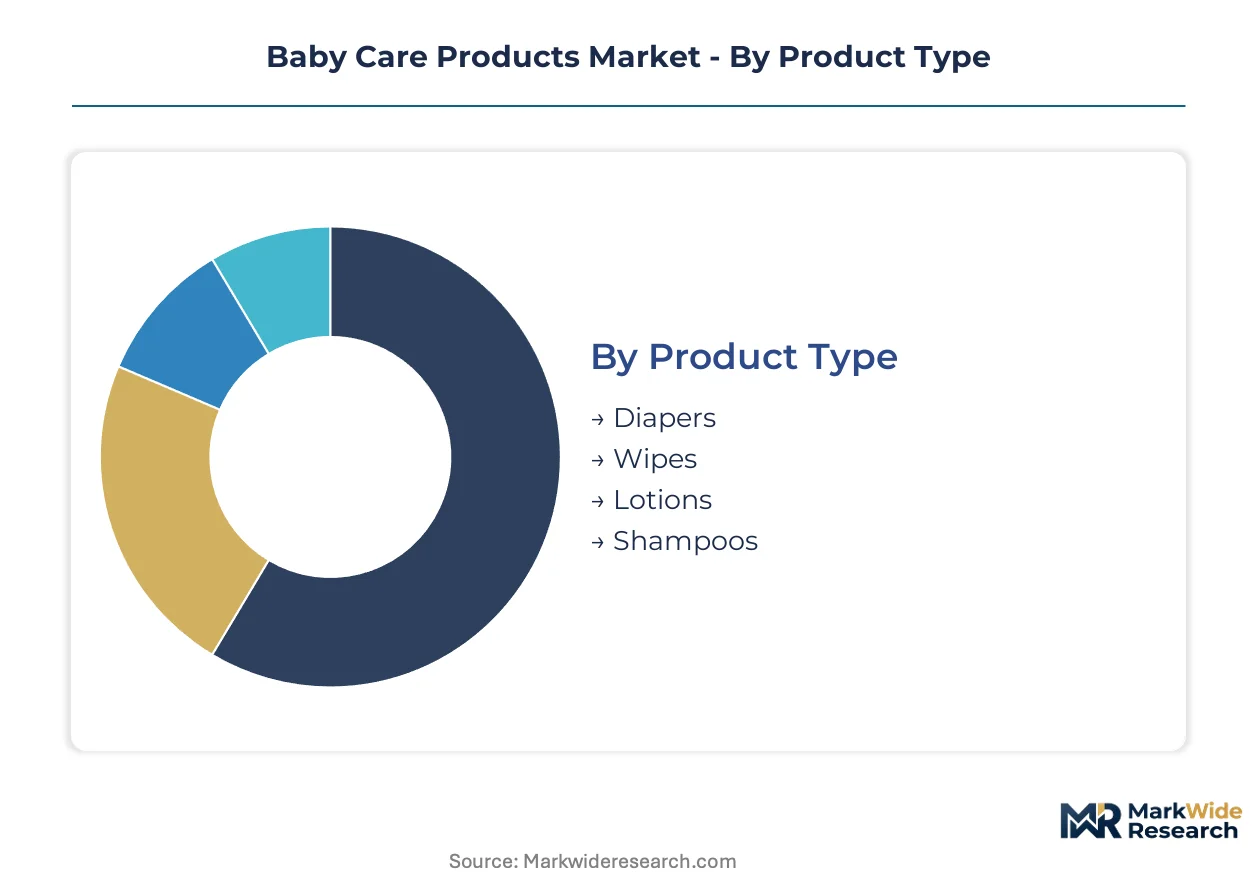
Segmentation in baby care products determines replenishment cadence, channel strategy, and formulation investment intensity. Parents of newborns trigger subscription lock-in, while toddler-stage households shift toward bulk purchasing and private label trial.
Product Type:
After-sales service intensity varies sharply across product types, with diapers demanding automated replenishment infrastructure and lotions requiring dermatological consultation support.
- Diapers:Superabsorbent polymer cores with elastic waistband systems dominate volume consumption. Demand concentrates in China's tier-one cities where subscription models capture recurring revenue from millennial parents seeking convenience.
- Wipes:Non-woven fabric substrates impregnated with pH-balanced cleansing solutions serve multiple daily use occasions. REACH SVHC restrictions on formaldehyde releasers are accelerating reformulation toward bio-based preservatives in European pharmacy channels.
- Lotions:Emulsion-based barrier creams with ceramide fortification address neonatal skin barrier vulnerability.
- Shampoos:Tear-free surfactant systems below 5.5 pH match infant ocular and dermal sensitivity thresholds.
Diapers hold the largest share; momentum sits with wipes as ingredient transparency mandates reshape purchasing criteria.
Distribution Channel:
Channel selection directly determines margin capture, with online retail enabling direct-to-consumer data ownership and supermarkets controlling impulse trial conversion.
- Supermarkets:High-visibility endcap placement drives new parent trial purchases and brand switching. Foot traffic erosion from subscription models is compressing promotional spend effectiveness in North American mass retail.
- Online Retail:Algorithmic bundling of diapers with diagnostic skin-monitoring tools is climbing the fastest in metropolitan India and urban China where smartphone commerce penetration exceeds 80% among new parents.
- Pharmacies:Professional endorsement infrastructure supports premium pricing for dermatologically tested formulations.
- Specialty Stores:Curated organic assortments attract ingredient-conscious parents seeking third-party certification verification.
Supermarkets retain the largest share; steepest expansion trajectory belongs to online retail as telehealth-integrated sampling collapses trial friction.
Age Group:
Developmental stage dictates product specification, usage frequency, and parental price sensitivity across the care continuum.
- Newborns:Medical-grade barrier creams with zinc oxide concentration above 40% address umbilical stump care and initial skin adaptation. Hospital discharge kit partnerships in Texas and California trigger automated replenishment conversion.
- Infants:High-frequency diaper changes and wipe consumption create the densest subscription revenue pools.
- Toddlers:Transition to training pants and finger-food cleanup expands wipe usage occasions beyond diapering.
- Pre-schoolers:Independent toileting reduces diaper dependency while amplifying shampoo and lotion selectivity based on peer influence.
Infants command the largest share; pre-schoolers are gaining share fastest as extended breastfeeding trends lengthen the total addressable window.
Formulation:
Ingredient architecture determines regulatory compliance burden, certification timeline, and premium pricing authorization.
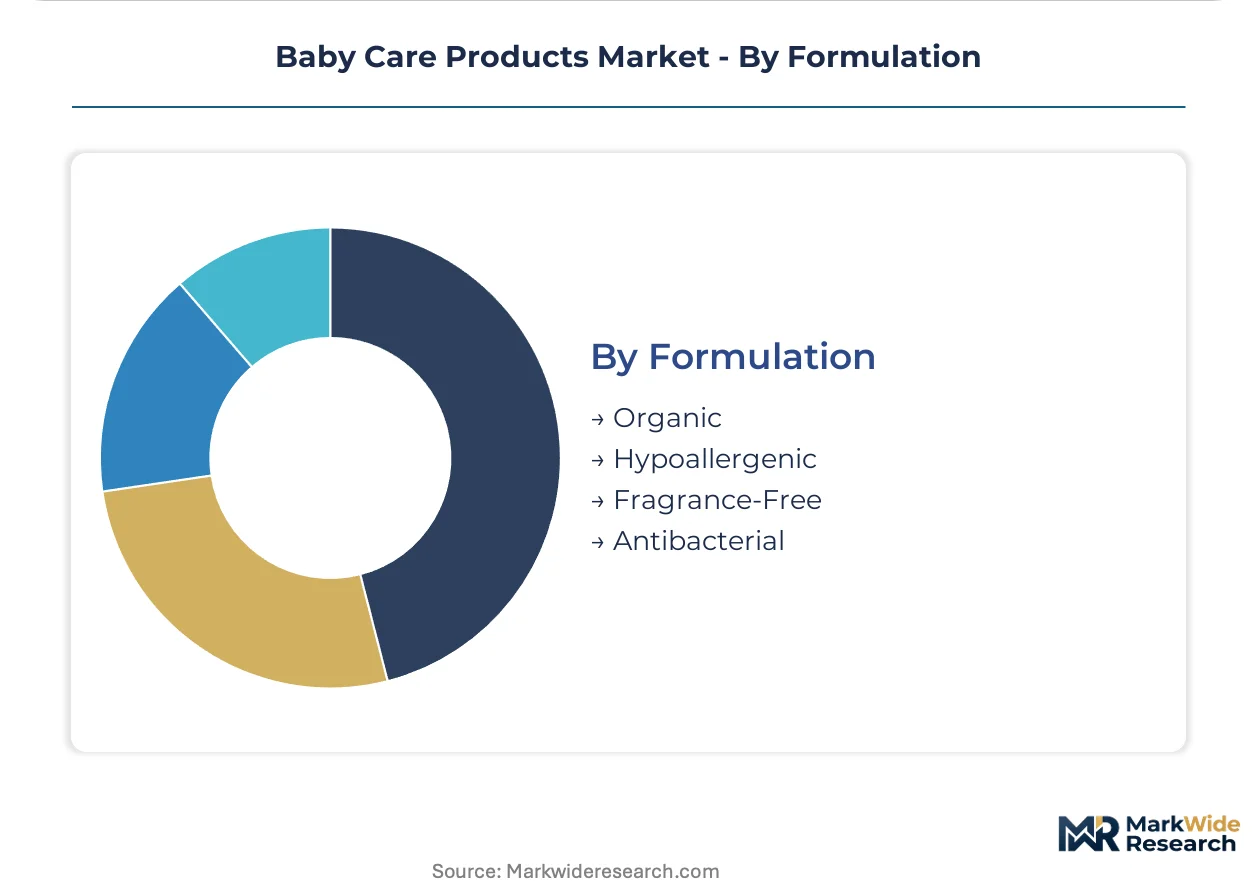
- Organic:Plant-derived surfactants and bio-based preservatives certified to USDA or ECOCERT standards. China's NMPA registration timelines extend 18-24 months for organic claims, delaying multinational portfolio launches.
- Hypoallergenic:Dermatologist-tested protocols with documented patch trial data support pharmacy channel placement and insurance reimbursement in European markets.
- Fragrance-Free:Elimination of synthetic odor compounds addresses parental concern about respiratory sensitization.
- Antibacterial:Controlled-release silver or benzalkonium chloride formulations target immunocompromised infant populations.
Hypoallergenic formulations hold the largest share; organic certification is expanding most quickly as EU Green Deal circularity mandates reshape ingredient sourcing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: parents in China's tier-one cities prioritize subscription convenience and organic certification, while Indian millennial households concentrate purchases through mobile-first e-commerce platforms bundling diagnostic tools with daily essentials.
United States
Hospital discharge kit partnerships in Texas and California trigger automated replenishment conversion for new mothers seeking seamless diaper and wipe continuity. FDA cosmetic labeling requirements govern ingredient safety thresholds for barrier creams and cleansers. Pediatric dermatology platforms in metropolitan clusters pilot AI-driven skin analysis that collapses trial-to-purchase friction for premium formulations.
China
Urban millennial parents in Shanghai and Beijing consolidate spending through e-commerce platforms that bundle organic lotions with skin-monitoring capabilities. NMPA registration timelines extend 18-24 months for infant cosmetic safety testing, delaying multinational organic portfolio launches. The Yangtze River Delta concentration of manufacturing capacity enables rapid reformulation cycles for pH-balanced surfactant systems.
Germany
EU Green Deal circularity mandates and ECHA SCIP database obligations force granular supply chain disclosure for fragrance compound origins in wipe solutions. REACH SVHC restrictions on formaldehyde releasers accelerate reformulation toward bio-based preservatives in pharmacy channels. Municipal collection infrastructure in the Rhine-Ruhr metropolitan region supports packaging reuse partnerships between brands and local authorities.
India
Millennial and Gen Z parents in metropolitan Mumbai and Delhi-NCR expand purchases through smartphone commerce platforms exceeding 80% penetration among new parents. PLI scheme incentives for personal care inputs enable cost-competitive organic formulation production for Middle Eastern export markets. Domestic manufacturing clusters in Maharashtra and Gujarat leverage scheme alignment to capture regional formulation demand.
South Korea
Premium parents in Seoul adopt biometric skin-monitoring wearables embedded in diaper elastic bands fastest, compressing irritation response times from hours to minutes. MFDS cosmetic safety standards shape ingredient approval pathways for neonatal-matched acidity formulations. The Seoul Capital Area concentration of telehealth infrastructure enables predictive barrier cream deployment rather than reactive application.
Baby Care Products Market Vendor Landscape
Capability concentration sits with dermatological testing specialists; scale advantage sits with mass-market manufacturers commanding diaper and wipe volume pools. The market structures around three tiers: multinational conglomerates with direct-to-consumer infrastructure, regional pharmacy-channel specialists with certification depth, and emerging organic formulators with supply chain transparency positioning. M&A activity targets subscription platform capabilities, while portfolio diversification accelerates toward telehealth-integrated sampling and diagnostic tool bundling.
Within the scale-driven tier, Procter & Gamble and Kimberly-Clark Corporation occupy positions anchoring North American recurring revenue capture through automated replenishment infrastructure. Beiersdorf AG exemplifies the dermatological certification specialist archetype, with German-based testing protocols supporting premium pricing authorization in European pharmacy channels. Johnson & Johnson represents the hospital discharge kit originator positioning, leveraging maternity ward partnerships to trigger subscription conversion in Texas and California metropolitan clusters.
| Leading Market Players |
|---|
| Procter & Gamble |
| Johnson & Johnson |
| Kimberly-Clark Corporation |
| Nestle S.A. |
| Unilever |
| Abbott Laboratories |
| Danone S.A. |
| Beiersdorf AG |
| Pigeon Corporation |
| Others |
Supply Flow & Price Mechanics
REACH SVHC regulatory chokepoints on preservative chemistries determine both three-tier pricing spreads across premium, standard, and economy diaper tiers and the geographic reconfiguration of formulation sourcing toward EU-compliant manufacturing hubs.
Pricing Analysis
Long-term offtake contracts between diaper manufacturers and superabsorbent polymer suppliers anchor pricing stability for mass-market tiers, while spot-market volatility in petrochemical feedstocks compresses margins for non-integrated players. Price differentiation separates dermatologically certified pharmacy-channel formulations from supermarket private labels based on ISO 22716 compliance depth and after-sales consultation bundling. Cost compression in economy tiers is intensifying because Indian and Chinese domestic manufacturers leverage PLI scheme incentives to undercut multinational landed costs. Mass-market parents in tier-two Chinese cities exhibit highest price sensitivity; premium subscribers in Seoul and Singapore show least elasticity due to telehealth-integrated diagnostic bundling.
Supply Chain Analysis
Extended payment terms from European pharmacy chains to wipe manufacturers are forcing working-capital restructuring among mid-tier formulators seeking REACH-compliant preservative alternatives. Superabsorbent polymer production draws from Saudi Arabia, South Korea, and the United States; non-woven fabric substrates source predominantly from China, Germany, and India. Single-source vulnerability concentrates in Malaysian palm-oil derivatives for bio-based surfactants. Distribution runs through direct-to-consumer subscription platforms fastest in metropolitan India and urban China, though supermarket warehousing still controls impulse trial conversion in North American mass retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a subscription-moat story where automated replenishment infrastructure creates switching costs that lock parents into recurring revenue streams and erode retail foot traffic.
For Market Incumbents: Build data-network moats by deepening pediatric dermatology platform partnerships that collapse trial-to-purchase friction through AI-driven skin analysis. Anchor supply security through backward integration into bio-based preservative production to preempt REACH SVHC compliance disruptions. Capacity addition in Maharashtra and Gujarat manufacturing clusters captures PLI scheme alignment for Middle Eastern export competitiveness.
For New Entrants and Emerging Players: India's tier-two cities and smaller metropolitan clusters represent the most penetrable white-space where smartphone commerce penetration among new parents lags tier-one adoption curves. Telehealth-integrated sampling partnerships with regional hospital discharge kit programs offer the lowest-friction go-to-market angle against entrenched subscription infrastructure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors dermatological certification specialists with ISO 22716 depth and pharmacy-channel authorization. Acquisition targets should demonstrate REACH-compliant formulation pipelines and established municipal packaging reuse partnerships in Germany or France. Watch for NMPA registration timeline compression as the signal indicating accelerated multinational organic portfolio entry into China.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Integration | Locks recurring diaper revenue through automated replenishment infrastructure that erodes supermarket foot traffic. |
| Dermatological Certification Investment | Secures pharmacy-channel premium pricing authorization under ISO 22716 protocols in European markets. |
| Bio-based Preservative Reformulation | Preempts REACH SVHC restrictions on formaldehyde releasers in wipe solutions across EU member states. |
| Telehealth-Integrated Sampling Partnership | Collapses trial-to-purchase friction through AI-driven skin analysis platforms in Texas and California maternity wards. |
| PLI Scheme Manufacturing Alignment | Enables cost-competitive organic formulation production for Middle Eastern export from Maharashtra clusters. |
Methodological Framework
A standing panel of brand managers at multinational diaper manufacturers, category buyers at pharmacy chains, supply planners at non-woven fabric converters, and regulatory affairs leads at cosmetic formulators provided ongoing calibration against secondary validation from FDA cosmetic labeling filings, ECHA SVHC candidate list updates, NMPA registration databases, and Nielsen retail audit data across Indian metropolitan markets. Bottom-up volume modeling triangulated against top-down category spend estimates anchored the analysis.
Scenario-bracketing around regulatory timeline variance and petrochemical feedstock volatility shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, distribution channel, age group, and formulation certification tier. CAGRs derived from regression analysis of historical subscription adoption curves and organic certification penetration rates, with NMPA approval cycle assumptions and REACH compliance cost trajectories as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by telehealth-integrated new entrants or rapid NMPA timeline compression would shift outcomes. Macroeconomic deviation in crude oil markets, regulatory blacklist expansion in Europe, or breakthroughs in plant-based surfactant performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Portable Cribs Market
Baby Products
Feeding Bra Market
Baby Products
Baby Changing Light Market
Baby Products
Baby Pacifier Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
Baby Products Detergents Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Baby Tableware Market
Baby Products
Baby Bottle Holder Market
Baby Products
Baby Bouncers Market
Baby Products
Breastfeeding Accessories Market
Baby Products
Puppy Teething Toys Market
Baby Products
Baby Bottle Warmers Market
Baby Products
Smart Bottle Warmers Market
Baby Products
Italy Baby Care Products Market
Baby Products
Global Baby Carriers Market