

Outdoor Camping Toilet Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Camping Toilet Market Insights
Polypropylene is shifting from premium to mainstream tiering across portable toilet manufacturing, lowering unit costs for mid-range buyers while maintaining chemical resistance. Thetford leverages captive molding capacity across European and North American plants to sustain margin control on cassette systems. Dometic Group anchors its position through integrated supply chains spanning RV OEM channels and aftermarket retail. Separett specializes in urine-diverting composting designs that compete on waterless operation for backcountry jurisdictions.
Outdoor camping toilets are self-contained sanitation units engineered for temporary deployment in locations without fixed plumbing, typically incorporating waste containment vessels, sealing mechanisms, and either chemical treatment or biological decomposition systems rated for temperatures from minus twenty to fifty degrees Celsius. Their primary commercial purpose is to satisfy human waste disposal requirements in mobile or remote recreational, emergency, and occupational settings while complying with public health and environmental regulations. Portable toilets occupy the largest volume tier due to low price points and broad retail availability, though composting variants represent the fastest-expanding margin pool as Leave No Trace ethics permeate consumer preferences. Chemical toilets retain mature demand from boating and RV applications where pump-out infrastructure exists, while cassette systems concentrate in European caravan markets with standardized disposal point networks.
EPA Office of Water administers Clean Water Act provisions affecting gray- and black-water disposal from camping units on federal lands, while state park agencies in California, Colorado, and Utah enforce site-specific pack-it-out mandates that elevate demand for sealed portable systems. ISO 30500 standards for non-sewered sanitation systems shape product design benchmarks for manufacturers seeking export certification into multiple national markets. Stakeholders must monitor evolving Bureau of Land Management dispersed camping permit systems and state health department composting endorsements to align R&D roadmaps with enforcement trajectories.
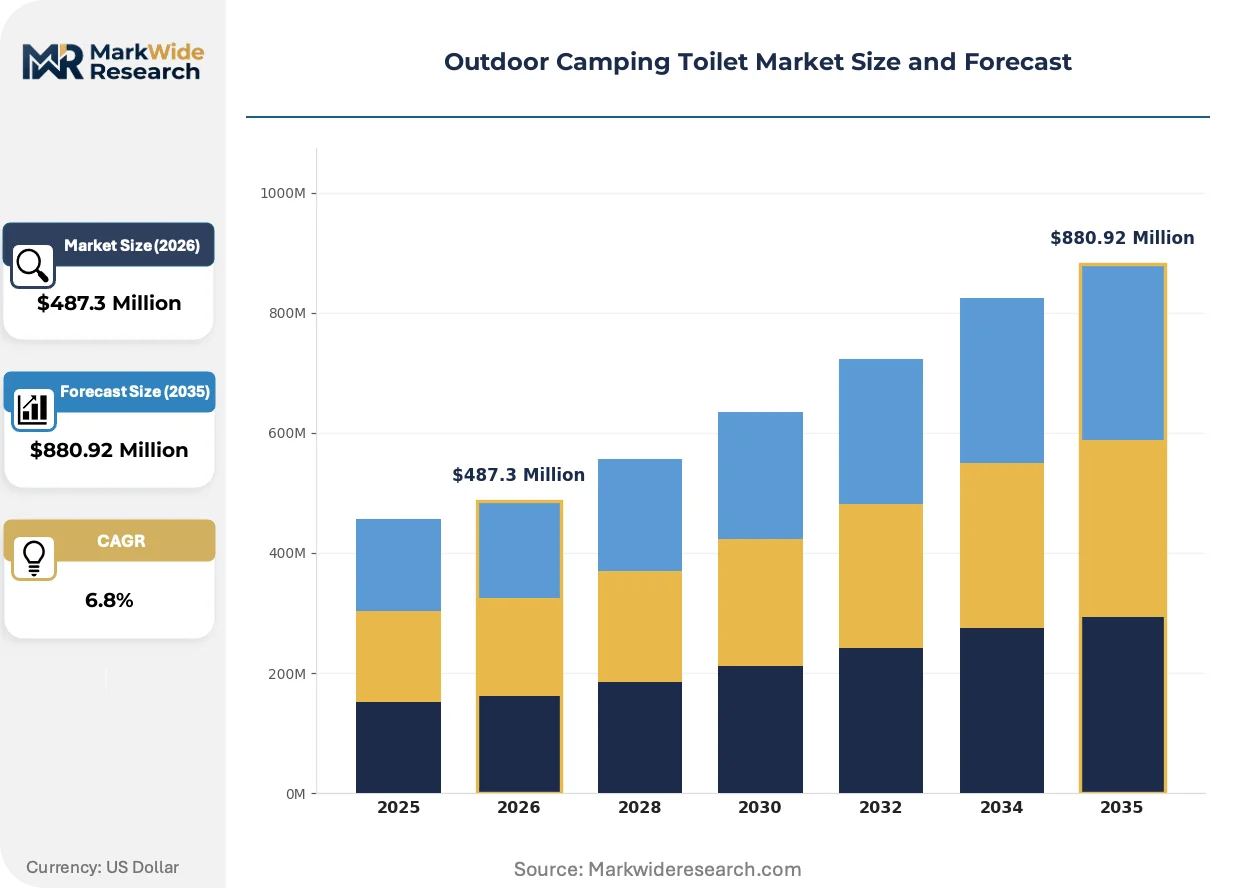
Market Dynamics
Polypropylene resin cost compression is redrawing competitive boundaries in portable toilet manufacturing, forcing mid-tier suppliers to recalibrate margin structures while premium incumbents defend positioning through captive molding networks.
Growth Catalysts
- BLM Dispersed Camping Permits:Bureau of Land Management permit expansion across western US acreage is mandating pack-it-out sanitation for overnight stays, directly elevating sealed-system procurement.
- ISO 30500 Certification:The non-sewered sanitation standard is unlocking export pathways for composting toilet manufacturers seeking multi-market access without redundant testing protocols.
- RV Trip Operator Concentration:Fleet-scale buyers across Arizona, Utah, and Colorado are consolidating procurement into annual contracts, creating volume anchors for cassette system suppliers.
Market Restraints
- Propylene Feedstock Volatility:North American polypropylene contract pricing swings are compressing gross margins for injection-molders without backward integration into resin supply.
- European Disposal Point Fragmentation:Cassette system growth stalls where national caravan club networks lack standardized emptying infrastructure, particularly in eastern EU accession states.
- Waterless Composting Capacity Limits:Urine-diverting designs face throughput ceilings in high-occupancy commercial settings, restricting adoption beyond family-scale recreational use.
Strategic Opportunities
- State Park Concession Bundling:California and Utah are piloting sanitation-as-service contracts for concessionaire operations, creating recurring revenue pools for system providers.
- Emergency Management Stockpiling:FEMA regional logistics centers are expanding mobile sanitation reserves for disaster response, opening institutional procurement channels distinct from recreational retail.
- Compost Endorsement Pathways:Colorado and Vermont health departments are formalizing humanure composting approval frameworks, reducing regulatory friction for biological decomposition systems.
Industry Challenges
- Thermoplastic Welding Specialist Scarcity:Rotational molding and seam-sealing expertise for leak-proof vessel production concentrates in aging workforces across Ohio and Michigan manufacturing corridors.
- EPA State-Delegated Variance Delays:Black-water discharge waivers for novel treatment chemistries face 18-24 month review timelines in states with understaffed environmental health divisions.
- Legacy RV OEM Integration Complexity:Aftermarket composting retrofits require dimensional reconciliation with pre-installed cassette cutouts, raising installation labor costs and return rates.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Camping Toilet Market Trends and Innovations
Electrochemical odor suppression and connected monitoring modules are migrating from marine sanitation into camping applications, compressing the performance gap between portable and fixed-installation systems.
Solid-state electrolytic cells are electrifying waste tank treatment by generating active chlorine species on-demand without liquid chemical carriage. High-end overland vehicle builders in Montana and Idaho are specifying these systems for expedition rigs operating beyond pump-out range. The technology is compressing chemical supply chain dependencies while extending service intervals to fourteen days.
EPA Office of Water is tightening Clean Water Act enforcement on gray-water discharge from dispersed camping units, particularly in California's Sierra Nevada watersheds. The regulatory pressure is elevating sealed-containment designs over traditional dump-valve configurations. Backcountry outfitters in the Mountain West are responding by phasing out open-drain systems from rental fleets.
Direct-to-consumer assembly is displacing retail box sales for composting toilet kits, with buyers accepting flat-pack logistics to access price points below dealer markups. This channel compression is most visible in the Pacific Northwest, where Leave No Trace advocacy groups maintain active purchaser communities. Regional distributors in Oregon and Washington are consolidating inventory risk while ceding final-mile fulfillment to manufacturer logistics.
Outdoor Camping Toilet Market Segmentation
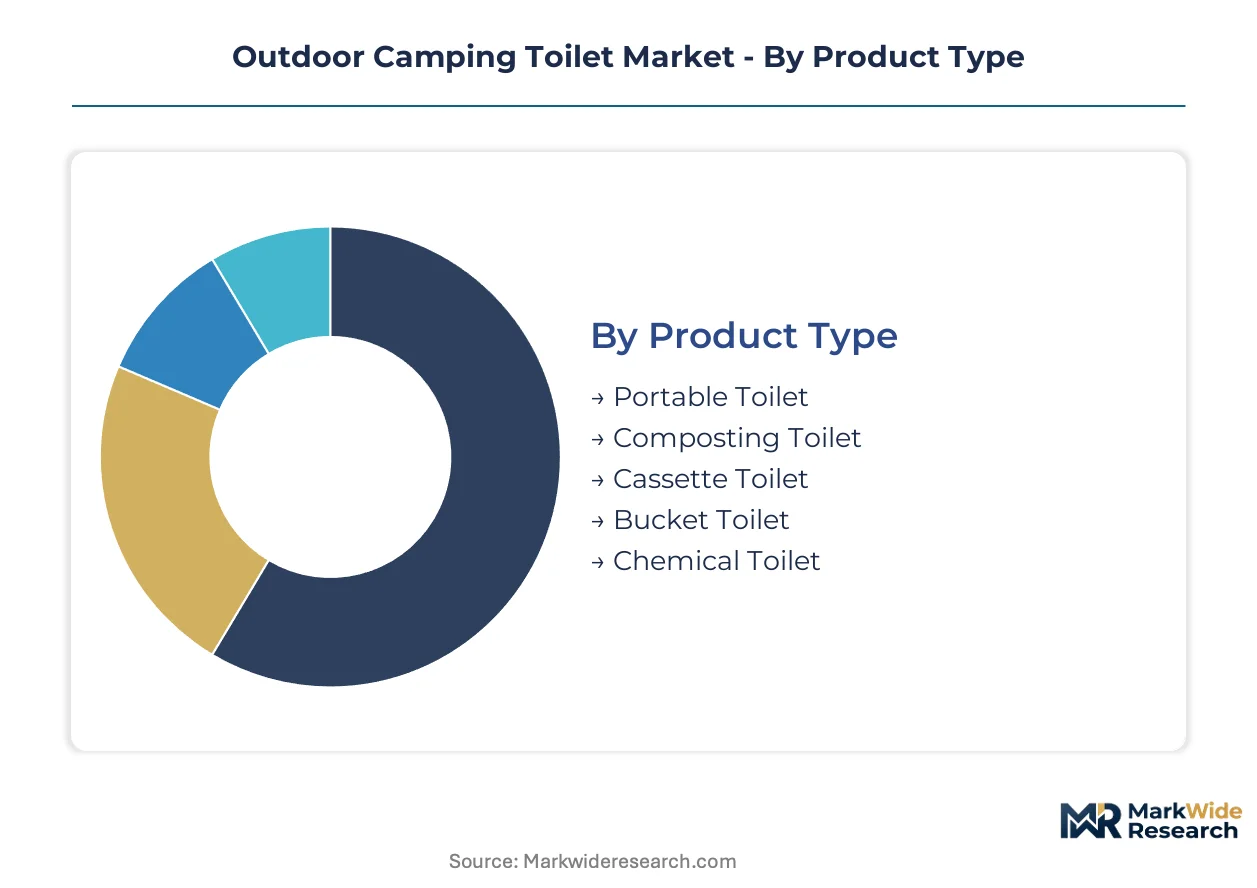
Segmentation in outdoor camping toilets reveals how material sourcing, application requirements, and user sophistication create distinct competitive arenas. Manufacturers must align product architectures with specific waste containment mandates and mobility constraints rather than pursuing universal designs.
Product Type:
Supply concentration in rotational molding capacity across Ohio and Michigan corridors favors high-volume portable and chemical toilet production, while composting systems depend on dispersed sheet-metal and biological component networks.
- Portable Toilet:Injection-molded polyethylene shells with integrated waste tanks dominate mass-market retail. Fleet procurement by Arizona and Utah RV trip operators sustains volume production runs at Thetford's North American plants.
- Composting Toilet:Urine-diverting designs with coconut coir or peat moss media serve backcountry jurisdictions with pack-it-out mandates. Colorado and Vermont health department composting endorsements are accelerating biological decomposition system adoption among Leave No Trace practitioners.
- Cassette Toilet:Removable waste cassettes with standardized docking dimensions anchor European caravan markets where disposal point networks exist.
- Bucket Toilet:Basic sealed pail configurations with biodegradable bag liners satisfy ultralight backpacking demand in Pacific Northwest trail systems.
- Chemical Toilet:Blue-dye formaldehyde or enzyme treatment systems retain installed base in boating applications with pump-out infrastructure access.
Today's leader: Portable Toilet. Tomorrow's challenger: Composting Toilet.
Material:
Cost tier differentiation separates commodity resin grades from performance-engineered polymers, with mid-market buyers increasingly accessing polypropylene properties once reserved for premium tiers.
- Plastic:General-purpose thermoformed ABS and HDPE serve entry-level portable units where unit economics prioritize mold cost over chemical resistance. Big-box retail channels in the western United States move substantial volume through seasonal promotional cycles.
- Polypropylene:Superior chemical resistance to urine and cleaning agents supports extended service intervals in commercial rental fleets. Dometic Group's captive molding capacity across European and North American plants defends margin control as resin cost compression redraws competitive boundaries.
- Stainless Steel:Marine-grade 316L fabrication withstands salt spray in boating applications and supports electrochemical odor suppression integration.
- Aluminum:Extruded and welded construction reduces weight for overland vehicle builders in Montana and Idaho specifying expedition-grade durability.
- Resin:Specialized polymer formulations enable seamless rotomolded tanks with enhanced UV stability for high-altitude desert deployment.
Polypropylene is climbing fastest as captive supply networks unlock mid-tier access to premium properties.
Application:
Volume concentration varies sharply across use cases, with recreational camping and RV trips generating predictable seasonal demand while emergency preparedness creates lumpy institutional procurement patterns.
- Recreational Camping:Dispersed camping on Bureau of Land Management acreage in the western United States drives sealed-system procurement with pack-it-out compliance requirements. California Sierra Nevada watershed enforcement is phasing out open-drain configurations from rental fleets.
- RV Trips:Cassette and portable systems integrate with fixed vehicle plumbing through standardized flange connections. Fleet-scale buyers across Arizona, Utah, and Colorado consolidate procurement into annual contracts creating volume anchors for established suppliers.
- Hiking Expeditions:Sub-kilogram foldable designs with waste bag containment address multi-day backcountry routes where water access is limited.
- Emergency Preparedness:FEMA regional logistics centers stock mobile sanitation reserves for disaster response, opening institutional channels distinct from recreational retail with extended procurement cycles.
- Boating:Coast Guard sanitation device regulations mandate Type III marine toilets with pump-out or treatment discharge capabilities in navigable waters.
Recreational Camping holds current volume leadership. Emergency Preparedness shows steepest expansion trajectory as climate resilience planning accelerates.
End User:
Customer sophistication spans from price-sensitive individual purchasers to technical buyers with fleet-scale maintenance infrastructure and regulatory compliance obligations.
- Outdoor Enthusiasts:Direct-to-consumer assembly kits with flat-pack logistics access price points below dealer markups in Pacific Northwest Leave No Trace communities.
- Tour Operators:Commercial duty cycles and liability exposure drive specification of ISO 30500 certified systems with documented waste containment performance. Utah and Colorado multi-day river trip outfitters maintain sealed-system fleets for compliance with state park concession requirements.
- Hunters:Seasonal remote camp deployment favors chemical toilets with extended treatment intervals where pump-out access is impractical.
- Fishermen:Marine sanitation device compliance and saltwater corrosion resistance prioritize stainless steel and specialized polymer constructions.
- Park Rangers:Federal land management agencies specify standardized portable units for backcountry patrol cabins with pack-it-out waste protocols.
Tour Operators dominate commercial value capture. Outdoor Enthusiasts are gaining procurement sophistication through direct manufacturer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thetford's captive molding networks across Ohio and Michigan anchor North American portable toilet manufacturing, while European cassette system production clusters around Thetford's Dutch and Swedish facilities. Bureau of Land Management dispersed camping permits and EPA wastewater enforcement create divergent procurement patterns across western US states versus European caravan markets.
United States
BLM dispersed camping permit expansion across Arizona, Utah, and Colorado elevates sealed-system procurement for pack-it-out compliance. EPA Office of Water Clean Water Act enforcement in California's Sierra Nevada watersheds phases out open-drain configurations from rental fleets. The Mountain West manufacturing corridor concentrates rotational molding capacity for high-volume portable unit production.
Germany
Caravan club standardized disposal point networks sustain cassette system demand across federal states with dense camping infrastructure. KBA vehicle type approval requirements shape RV-integrated sanitation specifications for cross-border travel. Baden-Württemberg and Bavaria host specialized thermoplastic welding operations serving premium overland vehicle builders.
Sweden
Urine-diverting composting designs gain traction in backcountry jurisdictions with stringent Leave No Trace enforcement. The Swedish Environmental Protection Agency's wastewater discharge guidelines for remote cabins elevate biological decomposition system specifications. Jönköping and Värmland regions concentrate sheet-metal fabrication for waterless toilet component networks.
Australia
Remote station and mining camp procurement drives heavy-duty portable sanitation demand across Western Australia and Queensland. State environmental protection agencies in New South Wales and Victoria enforce containment requirements for river corridor camping. Melbourne and Sydney distributors channel flat-pack composting kits to direct-to-consumer markets.
Japan
Wrappon's electrochemical odor suppression systems address space-constrained vehicle applications in dense urban camping markets. METI energy efficiency guidelines influence power-draw specifications for electrified waste treatment modules. Nagoya and Osaka industrial clusters specialize in compact marine sanitation device adaptation for camping crossover applications.
Outdoor Camping Toilet Market Competitive Landscape
Capacity expansion dominates the current landscape as polypropylene resin cost compression forces mid-tier suppliers to recalibrate margin structures. The vendor base stratifies across three tiers: premium incumbents with captive molding networks, mid-market injection-molders dependent on spot resin contracts, and emerging direct-to-consumer assemblers leveraging flat-pack logistics. Two competitive moves define current positioning: backward integration into resin supply chains and geographic expansion into state park concession bundling opportunities.
Among European specialists, Thetford and Dometic Group exemplify the premium tier through integrated supply chain control across RV OEM and aftermarket channels. Separett occupies a distinct positioning within the biological decomposition archetype, representing urine-diverting composting specialization for backcountry jurisdictions with pack-it-out mandates. These three anchors illustrate how competitive positioning diverges between chemical containment systems and waterless biological alternatives.
| Leading Market Players |
|---|
| Thetford |
| Dometic Group |
| Camco Manufacturing |
| VEVOR |
| Wrappon |
| Cleanwaste |
| Joolca |
| Separett |
| Stansport |
| Others |
Pricing and Supply Chain Analysis
Fleet-scale RV trip operators across Arizona, Utah, and Colorado anchor contract-based pricing structures that reward volume consolidation with preferential unit economics. Their procurement concentration forces suppliers toward transparent cost-plus models while spot-market buyers absorb resin volatility.
Pricing Analysis
Polypropylene resin cost pass-through dominates unit economics, with spot-contract spreads compressing margins for non-integrated molders. Three-tier pricing structure across premium, standard, and economy levels separates captive-molding incumbents from spot-resin dependents and flat-pack assemblers. Price differentiation hinges on ISO 30500 certification tier and after-sales service bundling. Pricing pressure intensifies as mid-tier buyers gain polypropylene access once reserved for premium tiers. Individual outdoor enthusiasts exhibit highest price sensitivity, while tour operators prioritize liability coverage over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with rotational molding capacity concentrated in Ohio and Michigan manufacturing corridors. Supply draws from United States, Germany, and Sweden for finished systems, with polypropylene resin anchored in Gulf Coast petrochemical complexes and European crackers. Component dependencies include electrochemical cell assemblies from Japan, urine-diverting hardware from Nordic sheet-metal networks, and specialized seals from German automotive tier suppliers. Tariff exposure on Asian-sourced electronics modules presents structural risk. Distribution runs through RV OEM direct channels, aftermarket retail networks, and direct-to-consumer flat-pack logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential rests on polypropylene cost compression unlocking premium-tier access for mid-market buyers, while biological decomposition systems command pricing power in regulated backcountry jurisdictions.
For Market Incumbents: Anticipate flat-pack assemblers eroding dealer-channel margins by capturing Pacific Northwest direct-to-consumer demand. Defend positioning through backward integration into resin supply and ISO 30500 certification acceleration for multi-market export eligibility. Prioritize state park concession bundling in California and Utah to secure recurring revenue pools against spot-market volatility. For New Entrants and Emerging Players: Begin with emergency preparedness procurement channels at FEMA regional logistics centers, where institutional buyers prioritize rapid deployment over brand heritage. Target composting system white space in Colorado and Vermont as health departments formalize humanure approval frameworks. Pursue direct-to-consumer flat-pack positioning to bypass distributor markup compression. For Investors and Strategic Acquirers: RV OEM supply chain managers represent the most active acquirer in this space, seeking captive molding capacity to secure margin control. Long-term viability favors specialists with urine-diverting biological decomposition expertise as Leave No Trace enforcement spreads. Monitor Bureau of Land Management dispersed camping permit expansion rates as the inflection signal for sealed-system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polypropylene sourcing insulates Thetford and Dometic from Gulf Coast contract volatility. |
| ISO 30500 Certification Investment | Multi-market export access unlocks without redundant testing protocols for composting manufacturers. |
| State Park Concession Bundling | California and Utah pilot programs create recurring revenue pools distinct from seasonal retail cycles. |
| Electrochemical Odor Suppression Integration | Marine-derived technology extends service intervals for Montana and Idaho overland vehicle builders. |
| Direct-to-Consumer Flat-Pack Launch | Pacific Northwest Leave No Trace communities accept assembly burden for dealer-markup elimination. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Interviews incorporated RV OEM procurement directors, state park concession managers, rotational molding plant engineers, and Leave No Trace advocacy group purchasing coordinators. Secondary sources included EPA Office of Water enforcement disclosures, Bureau of Land Management permit issuance data, ISO 30500 certification registries, and customs records for polypropylene resin trade flows. Bottom-up unit economics modeling converged with top-down market sizing across product type, material grade, and application vertical.
Granularity extended to state-level regulatory clusters within the United States, federal-state variations in Germany, and prefecture-level camping permit systems in Japan. Segmentation dimensions encompassed product architecture, material chemistry tier, end-use application, and buyer sophistication level. CAGRs were derived from installed base growth rates, replacement cycle compression, and penetration assumptions for biological decomposition systems. Forecast inputs incorporated BLM acreage expansion timelines, European caravan club infrastructure development, and FEMA logistics center stockpiling patterns.
Caveats apply where EPA state-delegated variance delays, propylene feedstock volatility, or thermoplastic welding specialist scarcity could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement trajectories and resin cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.